
 Middle East and Africa Edible Insects Market | 2026-2036
Middle East and Africa Edible Insects Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Edible Insects Market Foresight
Automated cricket-rearing climate systems is reconfiguring how producers scale output across arid zones. Aspire Food Group leverages vertical farming infrastructure to sustain breeding cycles in variable temperature environments. Ÿnsect anchors its competitive stance through proprietary mealworm protein extraction platforms optimized for regional feed applications. Protix B.V. competes on bioconversion efficiency metrics that reduce feed-input costs per kilogram of harvested biomass.
Edible insects in the Middle East and Africa encompass arthropod species reared under controlled conditions to produce human-grade protein with amino acid profiles exceeding conventional plant concentrates, typically processed through drying, milling, or fractionation into functional ingredients. The food industry application commands the largest current volume as bakeries and snack manufacturers incorporate cricket powder into formulated goods, while the powder form segment captures expanding margin pools due to its versatility across multiple downstream categories. Mealworm-derived products lead in regulatory approval velocity across Gulf Cooperation Council jurisdictions, and direct sales channels to institutional foodservice buyers represent the fastest-growing distribution pathway as chefs seek traceable supply relationships.
Saudi Arabia's SFDA and South Africa's Department of Health jointly influence product standards through novel food safety assessments that determine which species gain commercial clearance. The EU Green Deal's protein diversification targets indirectly shape investor sentiment and technology transfer flows into regional operations. Stakeholders must monitor how Egypt's national food regulator structures domestic guidelines for insect farming, as this will determine whether Nile Delta agricultural zones become viable production corridors or remain locked under legacy livestock policy frameworks.
Market Dynamics
Automated climate-controlled breeding infrastructure is collapsing the historical yield volatility that constrained arid-zone insect farming, enabling year-round production cycles previously impossible across Middle Eastern and African production zones.
Growth Catalysts
- EU Novel Food Regulation:Gulf regulators in Saudi Arabia and the UAE are adapting EFSA safety assessment templates, accelerating commercial clearance timelines for mealworm and cricket species in regional markets.
- Urban protein-supplement demand:Nigeria's Lagos and Abuja metropolitan corridors are driving institutional procurement of insect-based protein powders for bakery and snack manufacturing applications.
- Vertical farming integration:Controlled-environment agriculture techniques from hydroponics and aquaponics are transferring to cricket-rearing operations, stabilizing output in temperature-variable zones.
Market Restraints
- Feed input cost volatility:Sorghum and soybean meal prices fluctuate with Sahel drought cycles, compressing margins for biomass producers dependent on consistent nutritional substrates.
- Regulatory fragmentation:Egypt's national food regulator has not issued domestic insect farming guidelines, locking Nile Delta agricultural zones under legacy livestock policy frameworks.
- Consumer substitution preference:Conventional poultry and aquaculture proteins retain price advantages and established distribution networks across lower-income demographic segments.
Strategic Opportunities
- Kenya's underpenetrated market:Nairobi's foodservice sector lacks established insect protein suppliers, creating first-mover positioning for direct institutional sales channels.
- EU Green Deal protein diversification:Investor sentiment and technology transfer flows are redirecting toward North African operations capable of serving European import demand.
- E-commerce platform convergence:Direct-to-consumer subscription models for cricket powder supplements are bypassing traditional retail distribution bottlenecks in South African urban centers.
Industry Challenges
- Entomological expertise scarcity:Regional universities produce insufficient graduates in insect rearing and pathology, forcing producers to train biologists from adjacent agricultural disciplines.
- Novel food safety certification timelines:Gulf Cooperation Council jurisdictions require 18-24 month assessment periods for new species approvals, delaying product portfolio expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Edible Insects Market |
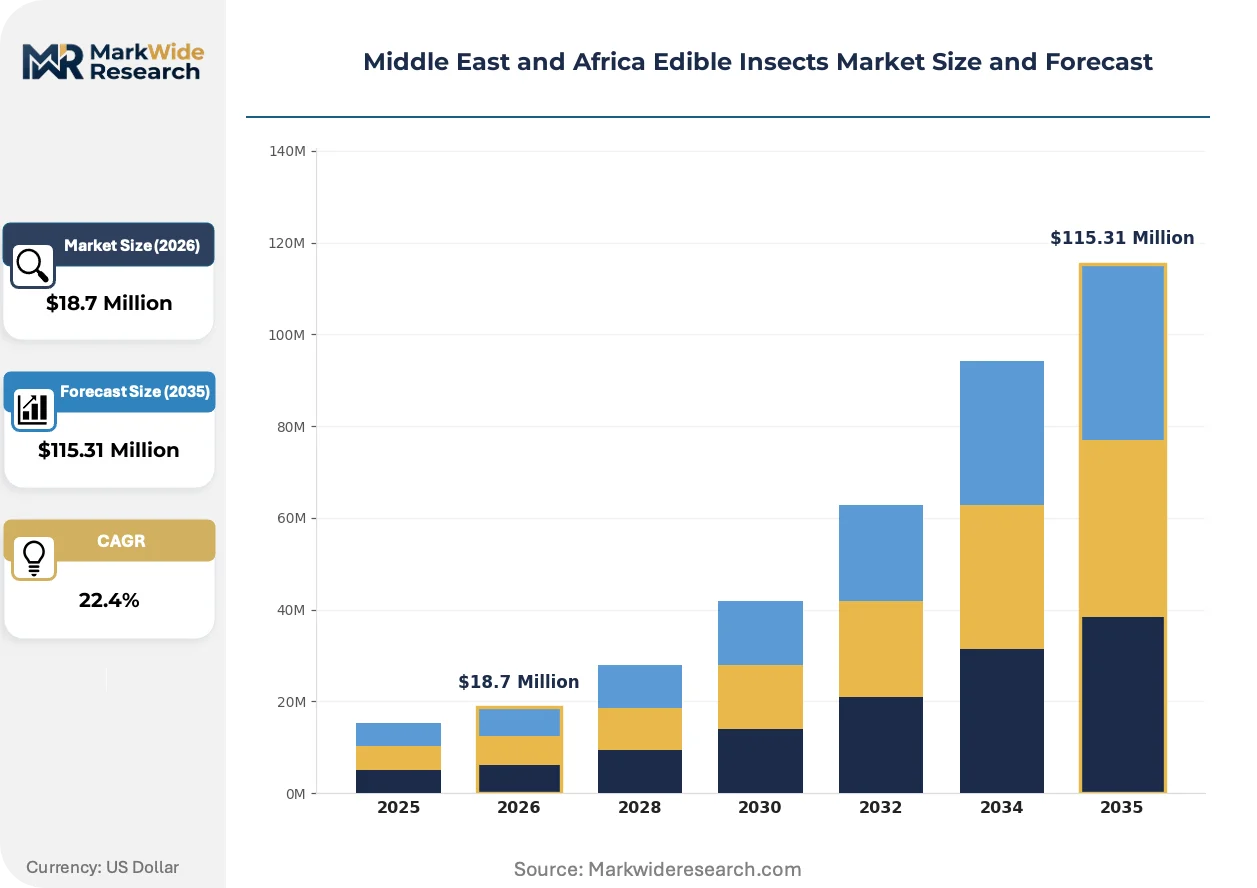
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $115.31 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
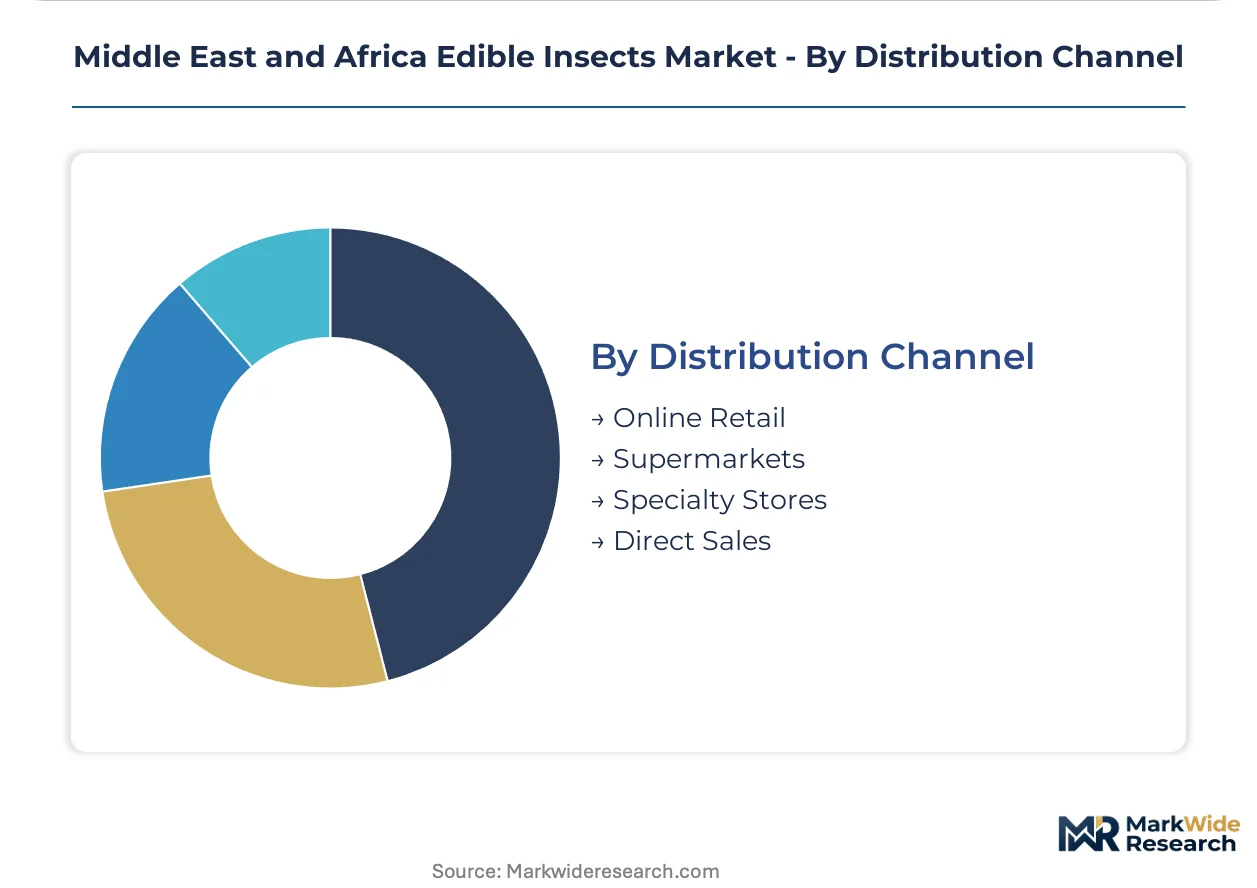
| Segmentation | Product Type: Crickets, Mealworms, Grasshoppers, Ants Form: Whole Insects, Powder, Snacks, Protein Bars Application: Food Industry, Animal Feed, Nutraceuticals, Food Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ÿnsect, Aspire Food Group, Protix B.V., InnovaFeed, Hargol FoodTech, Entomo Farms, EnviroFlight, Cricket Lab Limited, Global Bugs Asia Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Edible Insects Market Shifts & Advancements
Production technology and regulatory harmonization are converging to reshape competitive positioning across the Middle East and Africa edible insects sector, with automation and policy alignment driving structural shifts in supply reliability and market access.
Precision environmental control systems integrating IoT sensors with automated feeding mechanisms are collapsing the mortality rates that previously plagued desert-climate insect farming operations. South African commercial bakeries and snack manufacturers are adopting these systems at accelerating pace to secure consistent cricket powder supply. The compression of yield uncertainty is enabling long-term procurement contracts previously impossible for institutional foodservice buyers.
Saudi Arabia's SFDA and South Africa's Department of Health are jointly developing novel food safety assessment protocols that mirror EFSA evaluation frameworks. This regulatory convergence is reducing duplication costs for producers seeking multi-jurisdiction market access. Mealworm-derived products are capturing disproportionate approval velocity as regulators prioritize species with established European safety dossiers.
Chef-driven traceability requirements are restructuring distribution relationships across Gulf urban foodservice corridors. Direct sales channels to restaurant groups and hotel chains are displacing traditional ingredient wholesalers as buyers demand documented breeding facility audits and batch-level provenance. This pattern concentrates most visibly in Dubai and Riyadh, where premium positioning commands measurable price premiums over commodity protein alternatives.
Middle East and Africa Edible Insects Market Segmentation

Segmentation reveals how protein functionality, processing intensity, and buyer procurement preferences split value capture across the Middle East and Africa edible insects sector. Each dimension exposes distinct margin structures and regulatory exposure profiles.
Product Type:
The use-case spectrum spans from high-volume feed applications to premium human-grade ingredients, with species selection determining amino acid density and regulatory approval velocity.
- Crickets:Acheta domesticus delivers complete protein with all nine essential amino acids at digestibility rates exceeding 85%. South African bakeries and snack manufacturers in Johannesburg and Cape Town concentrate procurement for powder formulations, driven by established SFDA safety dossiers that ease Gulf market entry.
- Mealworms:Tenebrio molitor larvae yield protein concentrates with favorable methionine-to-lysine ratios for poultry feed fortification. Nigerian feed compounders in Lagos and Ibadan drive volume demand as poultry sector expansion strains conventional soy supply chains.
- Grasshoppers:Locusta migratoria and related species carry established consumption traditions across East African markets, though commercial scaling remains constrained by seasonal wild harvesting patterns.
- Ants:Weaver ant larvae and eggs occupy niche gourmet positioning in Vietnamese-influenced foodservice channels, with minimal commercial production infrastructure across the region.
Established volume favors mealworms; emerging adoption favors crickets.
Form:
Processing depth determines shelf stability, formulation flexibility, and price realization across institutional and retail buyer segments.
- Powder:Milled and fractionated insect protein enables seamless integration into bakery, pasta, and beverage formulations without textural disruption. Dubai-based food manufacturers prioritize this form for clean-label product lines targeting health-conscious expatriate consumers.
- Snacks:Roasted whole or minimally processed insect products occupy impulse purchase positioning in urban convenience retail. South African chains in Pretoria and Durban are expanding shelf space allocation as novelty-seeking millennial demographics drive trial rates.
- Whole Insects:Frozen or freeze-dried intact specimens serve ethnic foodservice channels and direct-to-consumer novelty segments with minimal processing overhead.
- Protein Bars:Formulated ready-to-eat products combining insect powder with binding agents and flavor systems target fitness and outdoor recreation segments in Gulf urban centers.
Processing margin concentrates in powder; consumer trial velocity concentrates in snacks.
Application:
End-use differentiation separates commodity feed volume from premium human nutrition value pools with divergent certification requirements.
- Food Industry:Ingredient supply to bakeries, pasta manufacturers, and snack formulators represents the most developed commercial channel. Saudi Arabian and UAE food manufacturers are integrating cricket powder into traditional flatbread and confectionery products to meet protein fortification targets.
- Animal Feed:Aquaculture and poultry operations in Egypt and Morocco are testing insect meal as fishmeal and soy substitution, though cost parity remains elusive at current production scales.
- Food Supplements:Protein powder and capsule formats target fitness enthusiasts and alternative protein adopters in South African and Nigerian urban markets.
- Nutraceuticals:Chitin and derived oligosaccharides for gut health applications remain pre-commercial across regional markets, with extraction technology gaps limiting supply.
Volume scale favors food industry; margin expansion favors food supplements.
Distribution Channel:
Channel selection determines traceability depth, buyer relationship intensity, and working capital requirements for producers.
- Direct Sales:Institutional relationships with hotel chains, restaurant groups, and food manufacturers enable batch-level provenance documentation and chef education. Riyadh and Dubai foodservice corridors show steepest expansion trajectory as traceability requirements harden.
- Online Retail:Subscription and direct-to-consumer platforms bypass traditional retail margin stacking, with South African e-commerce operators pioneering cricket powder subscription models in Johannesburg and Cape Town metropolitan zones.
- Specialty Stores:Health food and organic retail channels provide curated positioning for premium insect products targeting affluent urban consumers.
- Supermarkets:Mass retail penetration remains limited to select South African and UAE chains, with category management hesitation constraining shelf space expansion.
Relationship depth favors direct sales; reach expansion favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional foodservice buyers in Gulf urban centers and Nigerian protein-supplement manufacturers concentrate procurement demand across the Middle East and Africa edible insects sector. Regulatory frameworks in Saudi Arabia and South Africa shape commercial clearance pathways. Production clusters in Egypt's Nile Delta and Morocco's agricultural zones remain constrained by policy uncertainty.
Saudi Arabia
Hotel chains and restaurant groups in Riyadh and Jeddah drive demand for traceable cricket powder supply. The Saudi Food and Drug Authority (SFDA) adapts EFSA safety assessment templates for novel food approvals. NEOM's planned food production zone attracts technology transfer partnerships targeting regional export positioning.
South Africa
Bakeries and snack manufacturers in Johannesburg and Cape Town expand cricket powder procurement for clean-label formulations. The Department of Health coordinates novel food safety protocols with Gulf regulators to reduce multi-jurisdiction compliance costs. Durban's food processing corridor hosts emerging insect ingredient blending operations.
United Arab Emirates
Expatriate health-conscious consumers in Dubai sustain premium insect protein supplement demand. The Ministry of Health and Prevention (MOHAP) processes mealworm product approvals with accelerated timelines for European-dossier species. Dubai Industrial City clusters food manufacturers integrating insect powder into traditional flatbread and confectionery lines.
Nigeria
Feed compounders in Lagos and Ibadan source mealworm protein for poultry sector fortification. The National Agency for Food and Drug Administration and Control (NAFDAC) evaluates novel food guidelines for urban human-grade applications. Abuja's metropolitan foodservice sector tests direct institutional procurement from traceable breeding facilities.
Egypt
Aquaculture operations in the Nile Delta trial insect meal as fishmeal substitution. The national food regulator has not issued domestic insect farming guidelines, locking agricultural zones under legacy livestock frameworks. Cairo-based distributors import South African cricket powder for niche health food retail channels.
Middle East and Africa Edible Insects Market Competitive Landscape
Channel-controlling players compete with product-specialist players across institutional procurement and retail distribution vectors. Market structure shows moderate consolidation around vertically integrated breeding-to-ingredient operations and fragmented specialist rearing facilities. Three archetypes dominate: Gulf-facing regulatory navigators, African market infrastructure builders, and European technology licensors. Competitive moves concentrate on strategic partnerships with food manufacturers and capacity expansion in climate-controlled breeding facilities.
Among Europe-based technology licensors, Ÿnsect and Protix B.V. occupy positions exemplifying bioconversion efficiency specialization. Aspire Food Group represents the vertically integrated archetype with controlled-environment agriculture capabilities. These three entities anchor the competitive map for regional entrants seeking breeding technology partnerships or ingredient supply relationships.
| Leading Market Players |
|---|
| Ÿnsect |
| Aspire Food Group |
| Protix B.V. |
| InnovaFeed |
| Hargol FoodTech |
| Entomo Farms |
| EnviroFlight |
| Cricket Lab Limited |
| Global Bugs Asia Co., Ltd. |
| Others |
Supply & Pricing Matrix
Cricket-rearing substrate suppliers in South Africa's maize belt concentrate upstream bargaining power, compressing margin capture for Nigerian feed compounders while Gulf food manufacturers extract premium realizations through certified ingredient traceability.
Pricing Analysis
Cost-plus contracts indexed to Johannesburg grain exchange prices dominate bulk mealworm supply agreements, with sorghum and soybean meal volatility passing through to Lagos feed compounders. Three-tier pricing structure across premium, standard, and economy levels separates EU-dossier certified cricket powder from SFDA-cleared regional grades and unregistered commodity biomass. Pricing pressure stems from Sahel drought cycles that spike feed input costs. Institutional foodservice buyers in Dubai and Riyadh show least price sensitivity due to traceability requirements, while Nigerian poultry integrators face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentration sits with South African controlled-environment agriculture operators and Moroccan aquafeed blending facilities that toll-process imported larvae. Geographic supply concentrates in South Africa, Nigeria, and Saudi Arabia, with Egyptian Nile Delta zones locked under legacy livestock policy. Raw material dependencies center on sorghum, soybean meal, and wheat bran nutritional substrates. Single-source vulnerability runs through Johannesburg-based climate system providers that service arid-zone breeding infrastructure. Distribution runs through direct institutional sales channels to Gulf hotel chains and South African food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Entomological expertise scarcity constrains breeding facility expansion across the region, with regional universities producing insufficient graduates in insect pathology and rearing optimization to match capacity buildout timelines.
For Market Incumbents: Insulate breeding facility margins through backward integration into substrate production in South Africa's maize corridor, securing sorghum supply against Sahel drought volatility. Pursue dual-jurisdiction SFDA-Department of Health certification to reduce compliance duplication costs for multi-market cricket powder supply.
For New Entrants and Emerging Players: Nairobi's underpenetrated foodservice sector represents the most penetrable entry point for direct institutional sales channels, with chef-driven traceability requirements creating first-mover positioning before established suppliers consolidate. Kenya's lack of domestic breeding infrastructure favors technology licensing partnerships with European bioconversion specialists.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed South African vertical farming operators that have achieved regulatory clearance but require growth capital for Gulf market expansion. Five-to-ten year viability hinges on EU Green Deal protein diversification sustaining technology transfer flows into North African export corridors. Monitor Egypt's national food regulator for domestic insect farming guideline issuance as inflection signal for Nile Delta production zone viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Clearance Pathway | Dual SFDA-Department of Health certification reduces multi-jurisdiction compliance costs for cricket powder suppliers. |
| Backward Integration | In-house substrate production in South Africa's maize belt insulates margins from Sahel drought-driven sorghum volatility. |
| Technology Licensing | European bioconversion partnerships transfer automated climate control systems to Nairobi entrants lacking entomological expertise. |
| Direct Sales Channel Buildout | Chef-facing institutional relationships in Dubai and Riyadh capture traceability premiums over commodity protein alternatives. |
| Capacity Expansion | NEOM food production zone clustering attracts Gulf-facing breeding facilities seeking regional export positioning. |
Research Methodology
A spread of perspectives from insect breeding facility operators, Gulf foodservice procurement directors, Nigerian feed compounder executives, and SFDA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EFSA novel food safety dossiers, and agricultural ministry policy filings. Bottom-up facility capacity assessments triangulated against top-down protein demand projections across bakery, snack, and feed applications.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning species type, processing form, end-use application, and distribution channel. CAGRs were derived from installed breeding capacity trajectories and institutional procurement contract velocity. Forecast inputs incorporated climate system automation adoption curves and regulatory approval timeline distributions for novel food species.
Stress conditions across sorghum price volatility bands, SFDA assessment period extensions, and Egyptian policy guideline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of Gulf regulatory clearance velocity and Nairobi foodservice procurement trial rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Carragean Alternatives Market