
 Spirulina Beverages Market | 2026-2036
Spirulina Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Spirulina Beverages Market Intelligence
The capability gap between vertically integrated spirulina cultivation and sourcing from third-party suppliers is reorganizing the competitive landscape. Cyanotech Corporation leverages its large-scale microalgae production facilities to control quality and supply. In contrast, beverage specialists like Sol-ti, Inc. and RAW JUICERY INC differentiate through innovative flavor combinations and strong brand marketing in the ready-to-drink segment.
Spirulina beverages are functional drinks infused with biomass from the cyanobacterium Arthrospira platensis. These products are formulated to deliver high concentrations of protein, vitamins, and the antioxidant phycocyanin, serving as a liquid nutritional supplement. Within product types, Ready-to-Drink formats are expanding rapidly, appealing to convenience-focused Health Conscious Consumers. While traditional Juice and Smoothie applications remain a core market, protein powder formats capture demand from Athletes and Fitness Enthusiasts.
Market access and product claims are governed by food safety authorities like the United States FDA and the European Food Safety Authority (EFSA). These bodies enforce stringent regulations on novel food ingredients, allowable health benefits, and labeling accuracy, directly impacting formulation and marketing strategies. A key strategic decision for manufacturers involves navigating the cost-benefit analysis of securing organic certifications versus competing in the conventional beverage space.
Market Dynamics
The interplay between upstream cultivation science and downstream beverage formulation defines the market's core dynamic. Securing stable, high-phycocyanin spirulina biomass while masking its potent taste and color in consumer-friendly formats presents the central technical challenge for producers.
Growth Catalysts
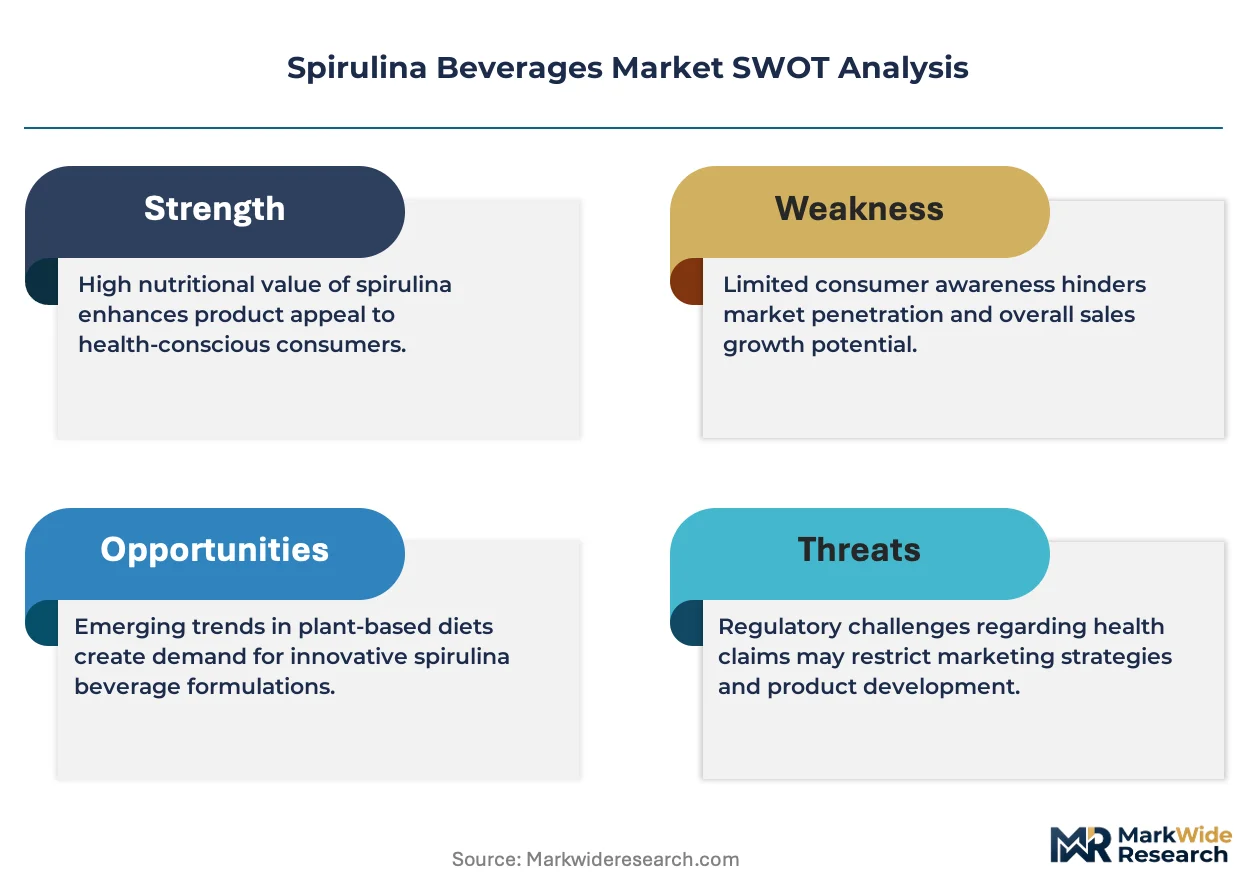
- Plant-Based Nutrition Demand:Heightened consumer interest in nutrient-dense, plant-based diets, especially among millennials in the United States and Germany, creates sustained demand for spirulina as a protein and vitamin source in liquid form.
- Regulatory Clarity:The European Union's Novel Food Regulation (EU) 2015/2283 provides a defined framework for approving spirulina ingredients, reducing uncertainty for manufacturers seeking market access in Europe.
- Formulation Technology:Innovations in microencapsulation and flavor-masking techniques are enabling the development of more palatable spirulina beverages, overcoming a key historical barrier to wider consumer adoption.
Market Restraints
- High Production Costs:The cultivation of high-purity, low-contaminant spirulina involves significant capital and operational expenditure, elevating the final product price beyond that of conventional functional beverages.
- Sensory Profile Challenges:Spirulina’s potent, earthy flavor and intense color require extensive masking agents and complex formulation processes, which can compromise clean-label positioning and increase production costs.
- Supply Chain Concentration:The supply of consistent, high-grade spirulina biomass is concentrated in specific geographies, including the United States and China, exposing beverage producers to potential price volatility and sourcing risks.
Strategic Opportunities
- Functional Water Category Expansion:Formulating spirulina into emerging beverage categories like functional waters and low-sugar sparkling drinks offers a path to attract new consumer demographics beyond traditional juice and smoothie drinkers.
- Geographic Market Entry:There is significant white space in markets like Brazil and the United Arab Emirates, where rising disposable incomes and a growing wellness culture create a receptive environment for novel functional beverages.
- Phycocyanin-Fortified Products:Developing products specifically marketed for their high phycocyanin content allows brands to differentiate on antioxidant properties, targeting consumers focused on anti-inflammatory and immune support benefits.
Industry Challenges
- Certification Complexity:Securing and maintaining organic, non-GMO, and other third-party certifications is a costly and time-consuming process that creates a significant operational burden, particularly for smaller beverage producers.
- Quality Standardization Gaps:A lack of universally accepted standards for spirulina biomass quality, specifically for phycocyanin levels and heavy metal contaminants, complicates procurement and undermines consumer trust in product claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirulina Beverages Market |
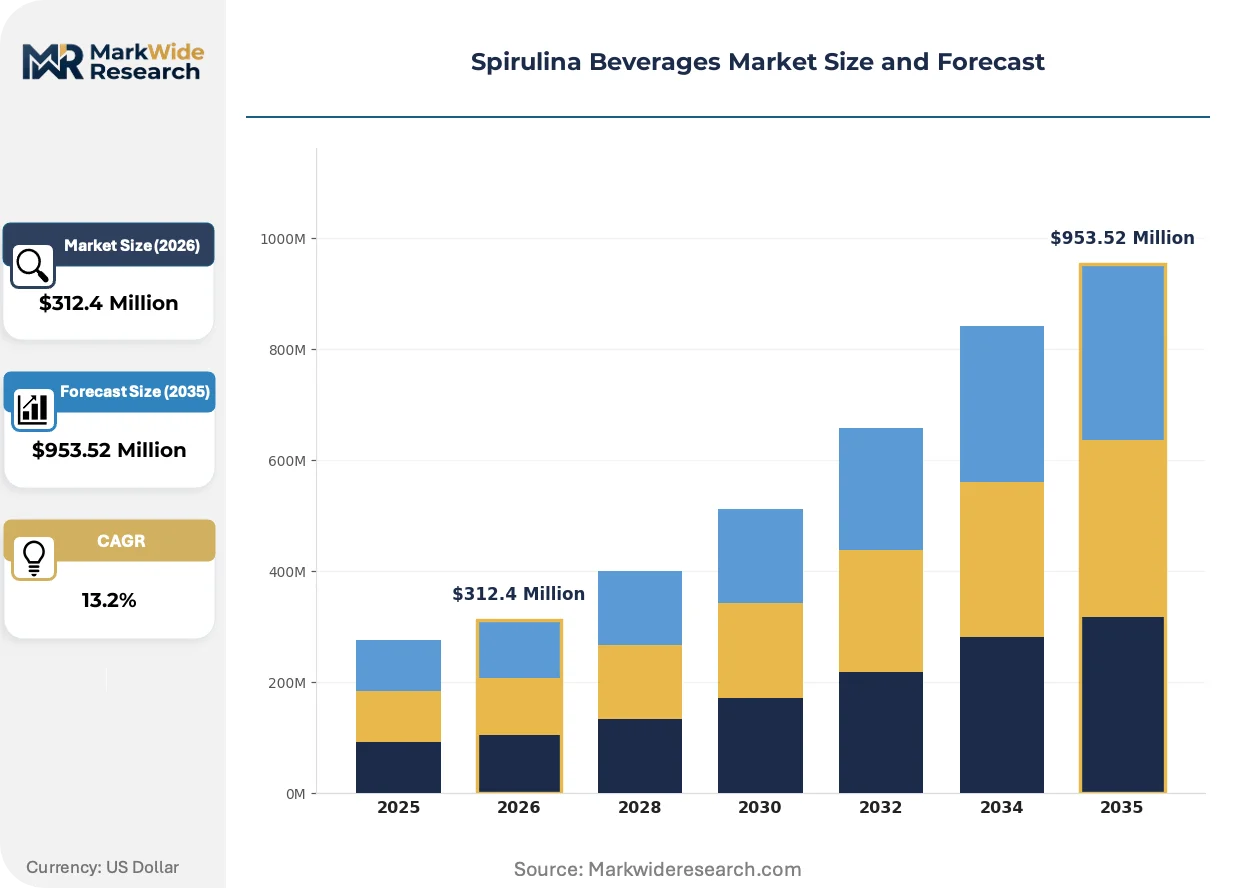
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $953.52 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice, Smoothies, Protein Powder, Ready-to-Drink End User: Health Conscious Consumers, Athletes, Fitness Enthusiasts, Vegans Packaging Type: Bottles, Pouches, Cans, Tetra Packs Flavor: Natural, Strawberry, Chocolate, Citrus |
| Companies Covered | Sol-ti, Inc., PHYCOMANIA, Prolgae Spirulina Supplies Pvt. Ltd., Bitez of Love, Buried Treasure Liquid Nutrients, Cyanotech Corporation, RAW JUICERY INC, The Juice Smith, FUL Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirulina Beverages Market Strategic Shifts & Innovations
Advances in extraction science are unlocking new product formats, while evolving food safety mandates create new guardrails for market participants. These shifts are pushing spirulina-based drinks from niche health food channels toward mainstream beverage aisles.
Phycocyanin extraction isolates the valuable blue pigment-protein from raw spirulina, removing the characteristic green color and taste. Beverage formulators are adopting this extract to create vibrant, naturally blue functional drinks that appeal to mainstream consumers. This development is bifurcating the market between traditional, whole-biomass green drinks and novel blue beverages targeting different consumer aesthetics.
The United States FDA's framework for GRAS notices for spirulina extracts provides a clear pathway for use in food and beverages. This regulatory acceptance encourages investment in product development by reducing compliance risk for manufacturers. Consequently, beverage brands are more confidently formulating with spirulina, particularly in the ready-to-drink segment, and making explicit ingredient-led marketing claims.
A consumer preference for ingredient transparency and customization is altering purchasing behavior. Instead of only buying pre-made drinks, a segment of Health Conscious Consumers now prefers spirulina powders and liquid concentrates to create personalized beverages at home. This shift is most prominent in mature wellness markets like the United States and Australia.
Spirulina Beverages Market Segmentation
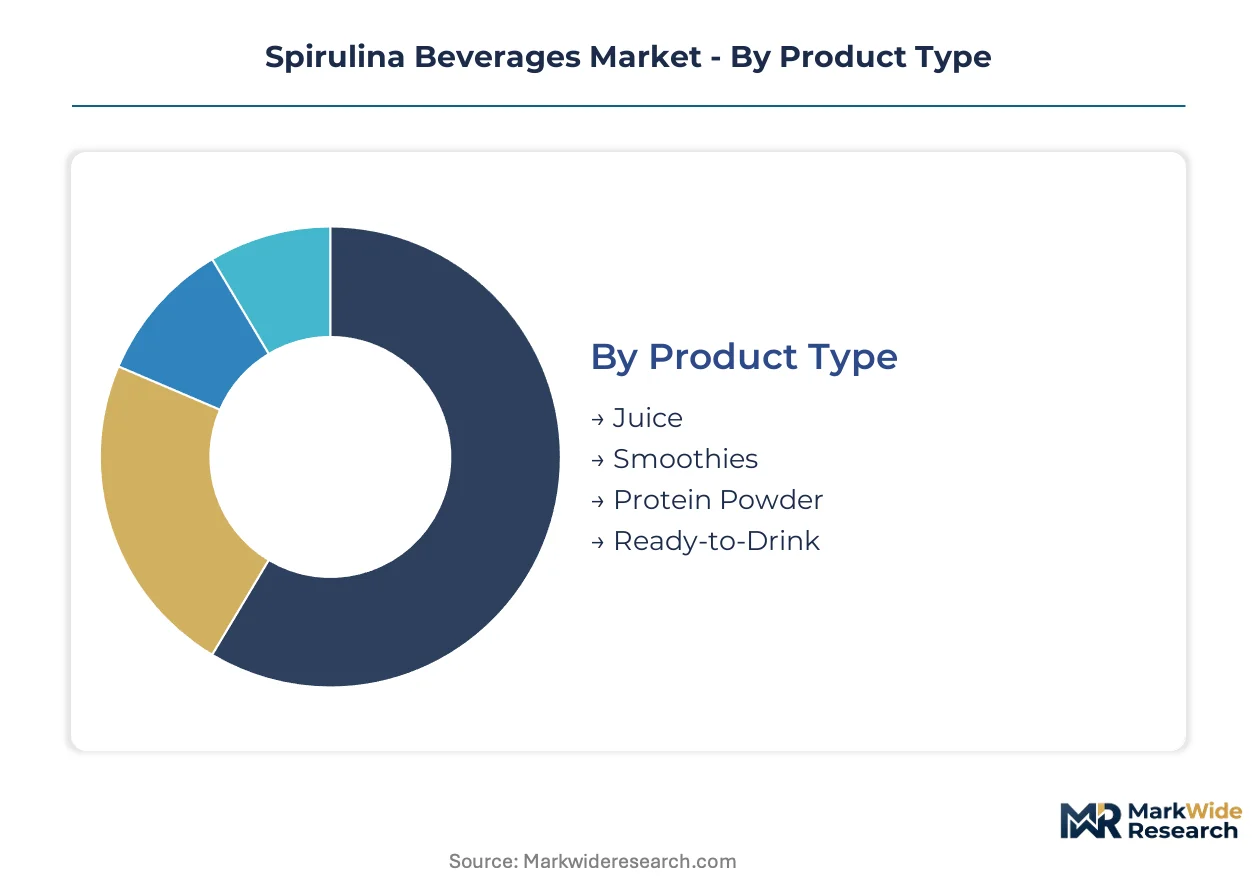
The Spirulina Beverages Market is categorized to reflect the diverse product offerings and consumer preferences driving its expansion. This segmentation highlights distinct avenues for product innovation and market penetration, allowing manufacturers to tailor strategies for specific consumer groups and consumption occasions.
Product Type:
The distribution channels for spirulina beverages are increasingly shaped by the convenience and preparation methods associated with each product type. This influences how products reach Health Conscious Consumers and Athletes, from retail shelves to specialized sports nutrition outlets.
- Ready-to-Drink:These pre-mixed liquid formulations offer maximum convenience, directly targeting on-the-go consumers seeking immediate nutritional benefits. Demand is expanding rapidly among convenience-focused Health Conscious Consumers, particularly in urban centers across the United States.
- Protein Powder:This concentrated format requires mixing by the consumer, catering to those who prefer customization and higher protein dosages. Athletes and Fitness Enthusiasts primarily drive demand for this segment, integrating it into their post-workout recovery routines.
- Juice:Spirulina-infused juices blend the cyanobacterium with fruit or vegetable bases, providing a familiar and palatable entry point for new consumers.
- Smoothies:These thicker, often fruit-based beverages incorporate spirulina for enhanced nutritional density, appealing to individuals seeking a meal replacement or substantial snack.
Juice dominates the installed base. Ready-to-Drink is where expansion concentrates.
End User:
The motivations driving spirulina beverage consumption vary significantly across different end-user segments, each seeking specific health outcomes or lifestyle alignments. Understanding these distinct needs informs product development and targeted marketing efforts for manufacturers.
- Health Conscious Consumers:This broad demographic prioritizes overall wellness, seeking nutrient-dense, plant-based options to support daily health and disease prevention. Their demand for spirulina beverages is particularly strong in mature wellness markets like Germany and Australia.
- Athletes:These individuals consume spirulina beverages for enhanced performance, muscle recovery, and sustained energy during physical activity. The high protein content and antioxidant properties of spirulina directly address their physiological requirements.
- Fitness Enthusiasts:This group integrates spirulina drinks into their active lifestyles for general fitness support, leveraging the nutritional benefits for energy and vitality.
- Vegans:Plant-based consumers adopt spirulina beverages as a vital source of protein and essential nutrients often lacking in strict vegan diets.
The market's long-term growth trajectory is most heavily influenced by the sustained engagement of Health Conscious Consumers.
Packaging Type:
Packaging choices significantly impact the logistics, shelf-life, and consumer interaction experience for spirulina beverage products. These decisions balance cost-efficiency, environmental considerations, and brand presentation across diverse retail environments.
- Bottles:Typically made from PET or glass, bottles remain a standard for spirulina beverages, offering visual appeal and re-sealability. This format dominates the premium segment, particularly in specialized health food stores in the United States.
- Cans:Aluminum cans provide excellent light protection and portability, appealing to the convenience-driven ready-to-drink segment. This packaging type is gaining traction for its recyclability and suitability for active consumer lifestyles.
- Pouches:Flexible pouches offer a lightweight and compact packaging solution, often used for single servings or children's products due to their ease of use.
- Tetra Packs:These aseptic cartons extend shelf life without refrigeration, making them suitable for ambient distribution and larger volume sales in grocery channels.
While Bottles remain foundational, Cans are gaining share fastest due to evolving consumer preferences for sustainability and convenience.
Flavor:
Flavor profiles are critical for enhancing the palatability and broad market acceptance of spirulina beverages, particularly given spirulina's distinct earthy taste. Strategic flavoring helps overcome sensory barriers for new consumers and expands product versatility.
- Natural:These formulations emphasize the inherent taste of spirulina or use minimal, unadulterated fruit and vegetable extracts, appealing to clean-label advocates. Consumers seeking unmasked ingredient transparency often prefer natural flavor options.
- Citrus:Flavors like lemon, lime, or orange are frequently employed to effectively mask spirulina's potent taste and color, making the beverage more refreshing and palatable. This profile is popular in ready-to-drink formats targeting broader consumer appeal.
- Strawberry:This popular fruit flavor offers a sweet and familiar profile, often used to introduce spirulina to consumers less accustomed to its unique taste.
- Chocolate:Chocolate flavors provide a rich and indulgent option, often paired with protein powders to create a more dessert-like or satisfying nutritional drink.
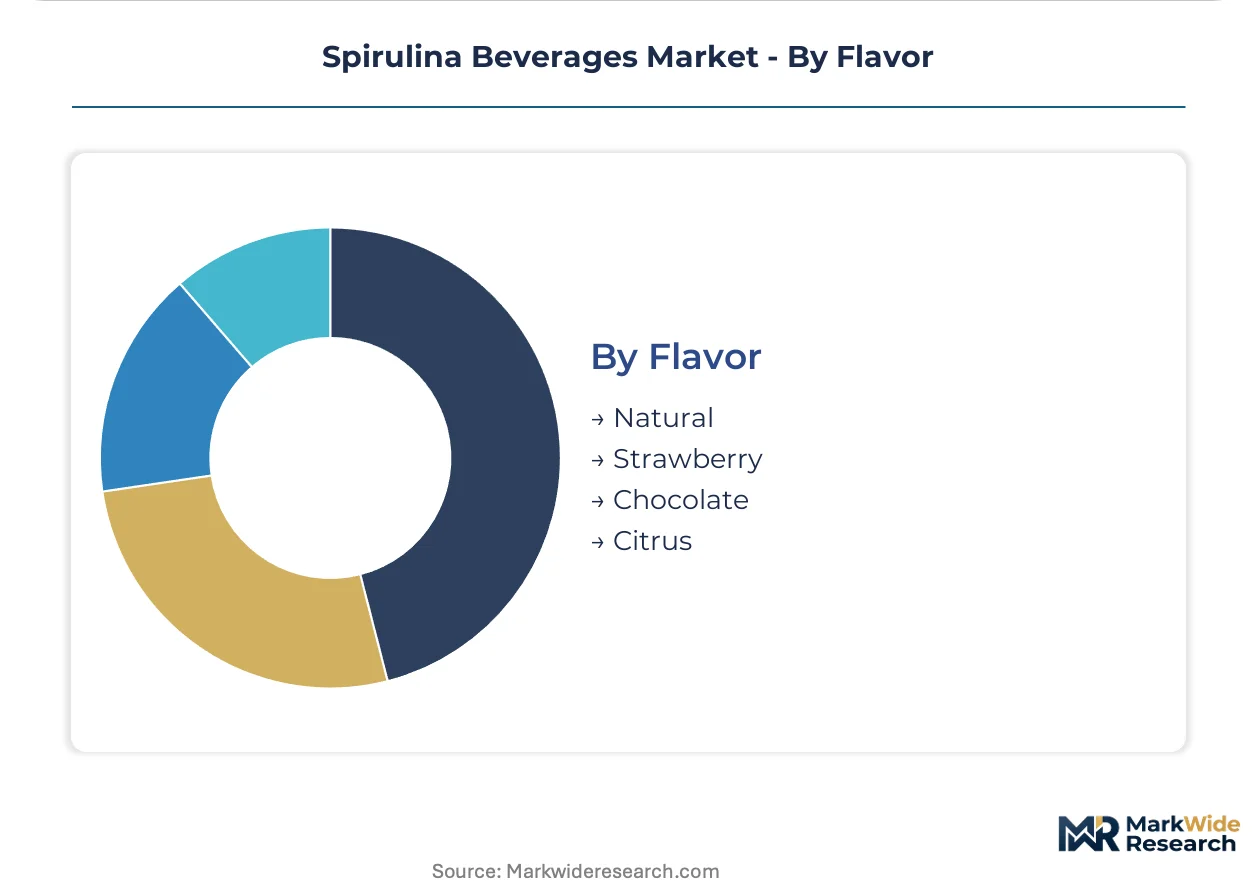
Demand for Natural flavors reflects a desire for clean labels, while Citrus profiles are expanding quickly to mask spirulina's inherent characteristics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for spirulina beverages varies significantly across global markets. Consumers in mature wellness economies demonstrate lower price sensitivity for premium, functional formulations. Emerging markets often exhibit higher price sensitivity, prioritizing affordability alongside nutritional benefits.
United States
The United States represents a significant consumer base, driven by Health Conscious Consumers seeking nutrient-dense, plant-based options. The United States FDA's GRAS notices provide clear regulatory pathways, encouraging product development. California's robust health food sector sees continuous product innovation in ready-to-drink spirulina formats.
Germany
German consumers show heightened interest in nutrient-dense, plant-based diets, propelling demand for spirulina as a protein and vitamin source. The European Union's Novel Food Regulation (EU) 2015/2283 provides a clear framework, reducing market uncertainty. Berlin's vibrant vegan food scene is a focal point for novel functional beverage adoption.
Australia
Australian Health Conscious Consumers show strong preference for ingredient transparency and personalized wellness solutions, driving spirulina demand. The Therapeutic Goods Administration (TGA) regulates health claims for functional foods, influencing marketing. Sydney and Melbourne's wellness markets exhibit high adoption rates for spirulina powders for home preparation.
Brazil
Brazilian markets offer significant white space for novel functional beverages, fueled by rising disposable incomes and an expanding wellness culture. ANVISA ensures food ingredient safety and accurate labeling. São Paulo's large urban centers demonstrate increasing availability of both imported and locally produced health-oriented drinks.
United Arab Emirates
The United Arab Emirates presents a receptive environment for novel functional beverages, supported by high disposable incomes and an evolving wellness culture. MOHAP regulates food supplements and health products, ensuring product safety. Dubai's luxury health and fitness sector drives demand for premium functional drinks infused with spirulina.
Spirulina Beverages Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for spirulina beverages. These integrated firms often control upstream cultivation, ensuring consistent biomass quality and supply. Two key strategic archetypes emerge: large-scale microalgae producers with captive supply and beverage specialists focused on brand and formulation. Dominant competitive moves include vertical integration to secure biomass and extensive product portfolio diversification.
Within the integrated leader archetype, Cyanotech Corporation exemplifies a focus on large-scale microalgae production facilities to control quality and supply. Beverage specialists like Sol-ti, Inc. and RAW JUICERY INC occupy positions in the ready-to-drink segment, differentiating through innovative flavor combinations and strong brand marketing. These companies collectively illustrate the dual competitive vectors of biomass control and consumer-facing product differentiation that characterize the market.
| Leading Market Players |
|---|
| Sol-ti, Inc. |
| PHYCOMANIA |
| Prolgae Spirulina Supplies Pvt. Ltd. |
| Bitez of Love |
| Buried Treasure Liquid Nutrients |
| Cyanotech Corporation |
| RAW JUICERY INC |
| The Juice Smith |
| FUL Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Average cultivation lead times for spirulina biomass, ranging from 7 to 14 days, directly influence inventory management for beverage producers, impacting their pricing power. This rapid production cycle, coupled with concentrated upstream supply, creates a dynamic where raw material availability can quickly translate into price shifts for finished spirulina beverages.
Pricing Analysis
Premium certification tiers, such as organic and non-GMO labels, drive significant lifetime value for spirulina beverage brands. Per-unit transactional pricing dominates the ready-to-drink segment, while protein powder formats often employ value-based pricing reflecting higher protein dosages. Quality grade and brand premium serve as primary price differentiation drivers. Pricing pressure stems from the high production costs of low-contaminant spirulina, particularly affecting conventional beverage segments. Health Conscious Consumers demonstrate lower price sensitivity for certified, nutrient-dense options, whereas new consumers entering the market exhibit higher price sensitivity.
Supply Chain Analysis
The United States and China anchor high-grade spirulina biomass production, forming critical nodes in the global supply chain. Spirulina beverage manufacturers primarily depend on spirulina biomass and specialized flavor-masking agents as key raw material inputs. Supply chain concentration exposes beverage producers to commodity price volatility for high-purity spirulina. Distribution runs through a fragmented network of health food stores, grocery channels, and specialized sports nutrition outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spirulina Beverages Market presents a fragmentation opportunity, driven by consumer preference for ingredient transparency and personalized wellness solutions. This shift creates distinct niches for specialized product offerings.
For Market Incumbents: Compound existing advantages in vertical integration by investing in upstream cultivation technology to secure stable, high-phycocyanin biomass. This move mitigates the threat of raw material price volatility and ensures quality control. Diversify product portfolios to include functional water and low-sugar sparkling drink formats, leveraging established distribution channels to reach new demographics.
For New Entrants and Emerging Players: Anchor in underserved geographic markets like Brazil and the United Arab Emirates, where rising disposable incomes foster a receptive environment for novel functional beverages. Target the functional water category with phycocyanin-fortified products, differentiating on antioxidant properties and a clean-label go-to-market angle. Focus on innovative microencapsulation techniques to overcome sensory profile challenges effectively.
For Investors and Strategic Acquirers: Carve-out targets emerge from beverage specialists with strong brand marketing and innovative formulation capabilities. The market demonstrates long-term viability over the next 5-10 years, supported by sustained plant-based nutrition demand. Seek out firms with proprietary flavor-masking technologies or established organic certification pathways. Regulatory acceptance of phycocyanin extracts by authorities like the United States FDA serves as a key signal to watch for accelerated product development and market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Expanding into functional waters attracts new Health Conscious Consumers beyond traditional juice drinkers. |
| Upstream Control Investment | Securing high-quality spirulina biomass through captive supply ensures consistent product formulation and reduces sourcing risks. |
| Organic Certification Pursuit | Achieving organic status commands premium pricing and appeals to ingredient-transparent consumer segments in Germany. |
| Geographic Market Expansion | Entry into white-space markets like the United Arab Emirates taps into new consumer demographics with high disposable incomes. |
| Flavor Masking Technology Enhancement | Improving palatability through advanced formulation techniques broadens consumer acceptance and market reach. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary market intelligence anchors the qualitative findings within this analysis. The methodology involved extensive conversations with beverage formulators, spirulina cultivators, regulatory affairs leads, and marketing managers across key regions. Secondary data sources included United States FDA GRAS notices, European Food Safety Authority opinions, trade association reports, and company financial filings. Both bottom-up and top-down triangulation were employed to ensure data accuracy and comprehensive market sizing.
Sensitivity analysis informs the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions modeled include product type, end user, packaging type, flavor, and phycocyanin content levels. Compound annual growth rates were derived from historical data trends and forward-looking projections based on identified growth catalysts and market restraints. Key forecast inputs include consumer health spending patterns and the cost of spirulina biomass.
Material uncertainties — unforeseen regulatory shifts or significant technological breakthroughs — sit outside the modeled envelope, representing potential forecast revision triggers. Forecasts reflect assumptions documented through a rigorous data collection and validation process. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market