
 Asia-Pacific Algae Protein Market | 2026-2036
Asia-Pacific Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Algae Protein Market Outlook
China's industrial-scale photobioreactor installations across Shandong and Yunnan provinces is reconfiguring regional supply availability for high-purity algae biomass. DIC Corporation leverages its integrated cultivation-to-extraction infrastructure across Japanese coastal facilities. Euglena Co. Ltd. anchors commercial production of paramylon-enhanced strains through proprietary fermentation protocols. Zhejiang Binmei Biotechnology dominates spirulina powder exports through controlled temperature processing lines.
Asia-Pacific algae protein comprises dried, defatted, or hydrolyzed biomass derived from cyanobacteria and microalgae, typically containing 50-70% crude protein by dry weight with complete essential amino acid profiles, produced via open-pond raceway or closed photobioreactor systems for human nutrition, animal feed fortification, and therapeutic applications. Spirulina occupies the largest volume share due to established extraction economics and GRAS-equivalent regulatory familiarity across multiple jurisdictions. Chlorella competes on higher chlorophyll and nucleic acid content, commanding premium positioning in detoxification and immune-modulation formulations. The nutraceutical end-user segment leads value capture, while food and beverage applications in meat analogs and dairy alternatives are expanding fastest among emerging demand pools.
China's SAMR maintains food-grade algae ingredient licensing under GB standards, while Japan's Ministry of Health, Labour and Welfare governs novel food notifications for microalgae-derived proteins. Australia's Food Standards Code administered by FSANZ dictates heavy metal and allergen thresholds for imported algae products. India's FSSAI recently notified draft quality parameters for chlorella and spirulina supplements, signaling tighter market access ahead. Stakeholders must monitor regulatory divergence on novel food classifications to preempt formulation and labeling compliance costs.
Market Dynamics
China's SAMR is tightening food-grade algae processing standards under updated GB protocols, forcing extraction purity upgrades across regional supply chains while Japanese and Australian buyers accelerate procurement of high-specification isolates.
Growth Catalysts
- Thailand-Vietnam procurement scaling:Plant-based food manufacturers in Bangkok and Ho Chi Minh City are expanding spirulina and chlorella offtake for meat analog formulations.
- Australian nutraceutical corridor demand:Contract manufacturing clusters around Melbourne and Sydney are concentrating demand for therapeutic-grade algae protein.
- Photobioreactor infrastructure expansion:Industrial-scale closed-system installations across Shandong and Yunnan provinces are lifting biomass availability for downstream processors.
Market Restraints
- Input cost volatility:Nutrient media and CO2 feedstock prices fluctuate with energy markets, compressing margins for open-pond operators.
- Supply concentration risk:Spirulina powder processing lines cluster in Zhejiang province, creating single-point vulnerability for export-dependent buyers.
- Regulatory friction:India's FSSAI draft quality parameters for chlorella and spirulina supplements are extending market access timelines.
Strategic Opportunities
- Vietnam underpenetration:Domestic algae protein consumption remains minimal relative to processing capacity, offering first-mover positioning for branded ingredient suppliers.
- Fermentation-convergence:Proprietary paramylon-enhanced strain production via fermentation protocols opens therapeutic applications beyond nutrition.
- SAMR standardization tailwind:China's tightened extraction purity thresholds will advantage pre-compliant exporters into the PRC market.
Industry Challenges
- Photobioreactor engineering talent scarcity:Specialized bioprocess engineers with closed-system design experience command premium compensation across the region.
- Dual certification timelines:Simultaneous GB standard compliance for China and FSANZ alignment for Australia extends product launch cycles.
- Legacy open-pond retrofit complexity:Existing raceway infrastructure requires substantial capex to meet emerging closed-system purity benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Algae Protein Market |
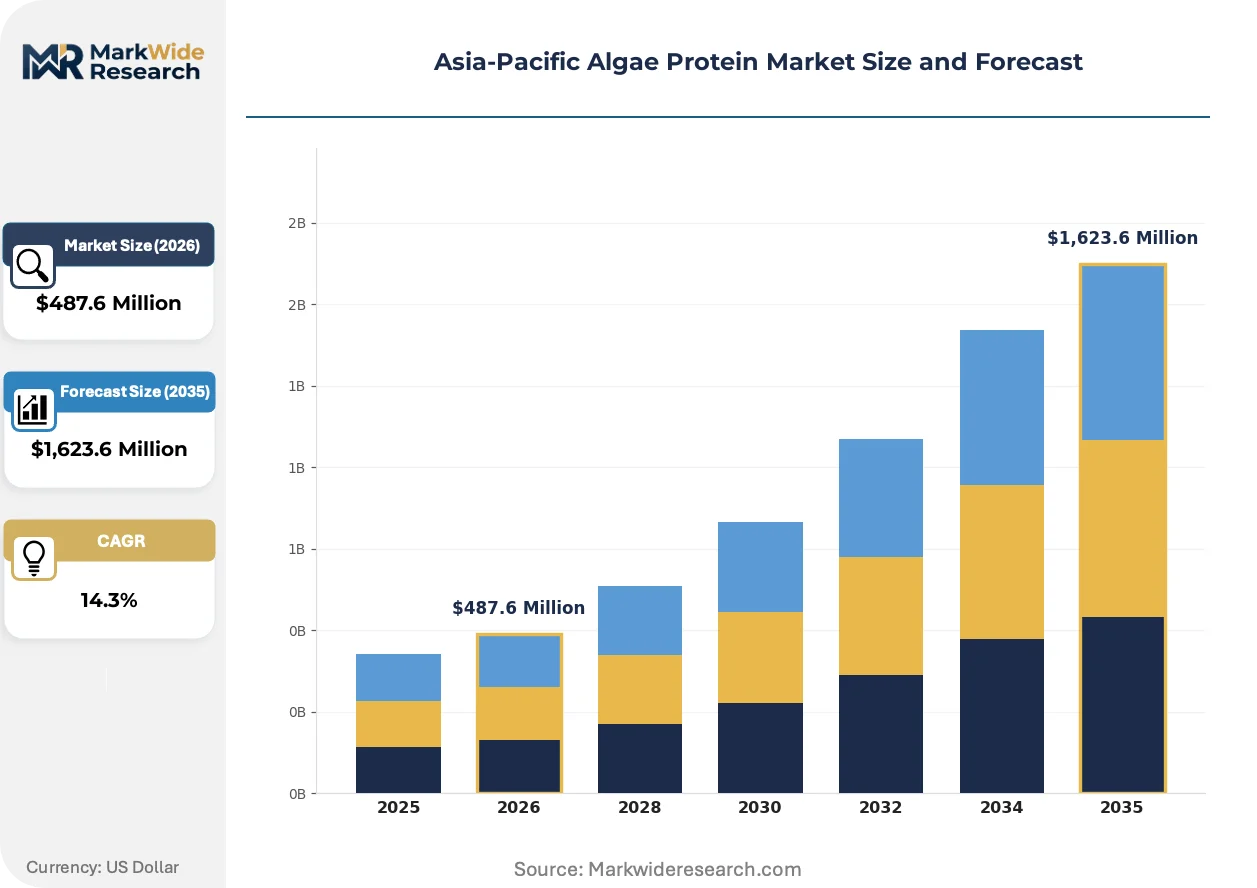
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,623.6 Million |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Dunaliella, Others End User: Food & Beverage, Nutraceuticals, Animal Feed, Pharmaceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Form: Powder, Tablets, Liquid, Capsules |
| Companies Covered | Corbion N.V., DIC Corporation, Cyanotech Corporation, Parry Nutraceuticals, Far East Bio-Tec, Hunan Sunfull Bio-tech, Euglena Co. Ltd., Zhejiang Binmei Biotechnology, AstaReal Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Algae Protein Market Strategic Shifts
Digital cultivation monitoring and precision fermentation are compressing production variability while regulatory divergence between Chinese GB standards and Australian FSANZ codes is fragmenting formulation strategies.
Closed photobioreactor systems with integrated sensor arrays are virtualizing biomass quality control. Nutraceutical contract manufacturers in Australia are adopting these platforms fastest, compressing batch-to-batch protein content variance from historical double-digit spreads to sub-five-percent ranges.
China's SAMR updated food-grade algae processing standards under GB protocols during 2024. Industrial consequence includes mandatory heavy metal and allergen threshold documentation for all imported isolates. Australian FSANZ is responding with reciprocal testing reciprocity negotiations to preserve trade flow efficiency.
Ingredient buyers are consolidating supplier relationships around vertically integrated cultivator-processors. Direct procurement from coastal Japanese facilities is displacing spot-market purchasing through trading houses. This concentration is most visible among Melbourne and Sydney nutraceutical contract manufacturers seeking paramylon-enhanced strain security.
Asia-Pacific Algae Protein Market Segmentation
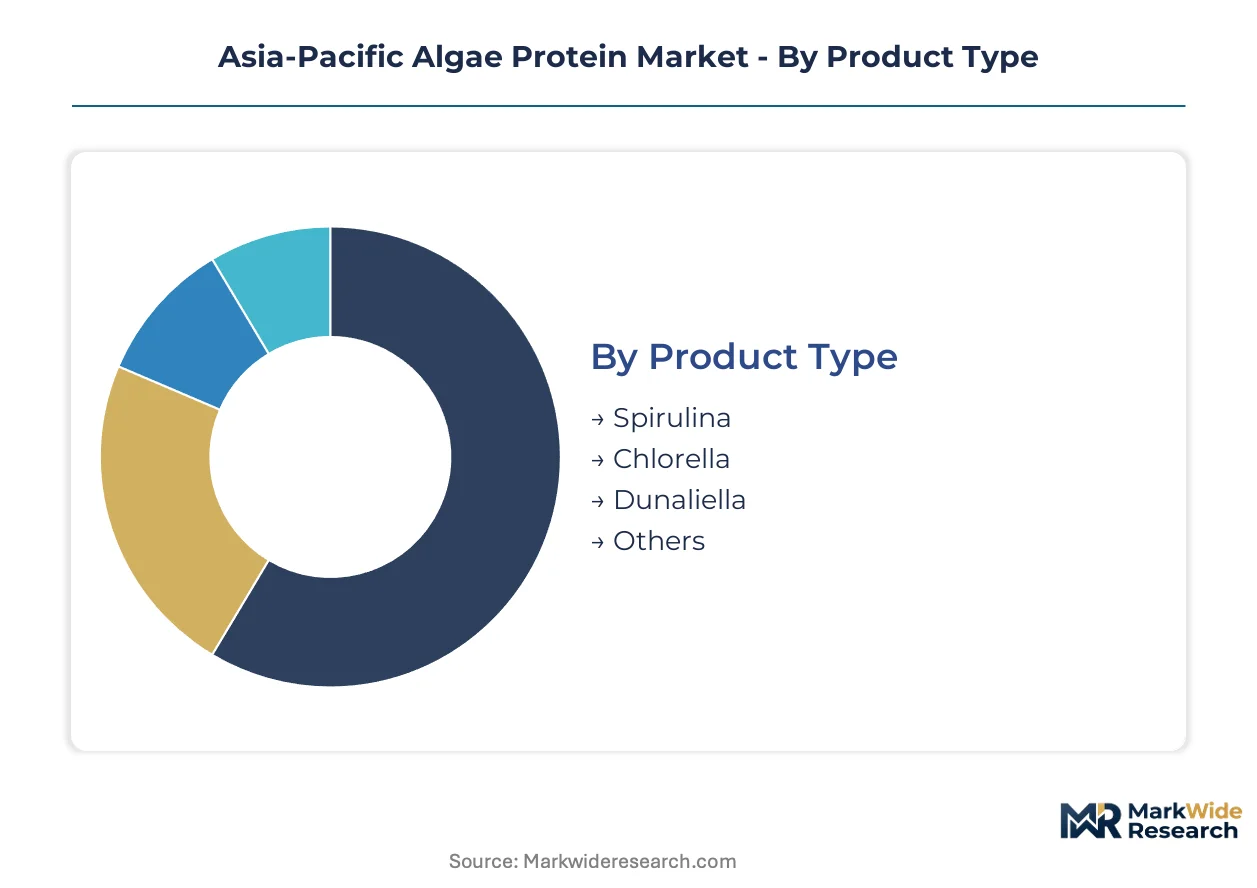
Algae protein procurement patterns diverge sharply across product specifications and channel structures. Understanding these fault lines exposes where margin pools concentrate and which formulation investments align with regulatory trajectories across China, Japan, and Australia.
Product Type:
Cost tier stratification separates commodity biomass from premium isolates with differentiated bioactive profiles.
- Spirulina:Cyanobacterial biomass containing 60-70% protein by dry weight with established GRAS-equivalent status across multiple Asia-Pacific jurisdictions. Procurement concentrates among Thai and Vietnamese plant-based food manufacturers seeking cost-efficient meat analog fortification, though Zhejiang province processing concentration creates supply vulnerability.
- Chlorella:Single-celled green algae with superior chlorophyll density and nucleic acid content commanding 15-25% price premiums over spirulina. Australian nutraceutical contract manufacturers around Melbourne and Sydney absorb therapeutic-grade volumes for detoxification formulations, constrained by India's FSSAI draft quality parameters extending import timelines.
- Dunaliella:Halophilic microalgae cultivated for beta-carotene and glycerol co-products alongside protein fractions.
- Others:Emerging strains including Euglena paramylon-enhanced variants and Nannochloropsis marine isolates for specialized applications.
Spirulina commands the established base. The steepest expansion runs through chlorella as therapeutic positioning deepens.
End User:
Application maturity determines specification thresholds and certification burdens for suppliers.
- Nutraceuticals:Therapeutic-grade isolates with documented heavy metal and allergen compliance under China's SAMR GB standards and Australia's FSANZ codes. Demand clusters in Melbourne and Sydney contract manufacturing corridors seeking batch-to-batch protein variance below 5% through photobioreactor-sourced supply.
- Food & Beverage:Meat analog and dairy alternative formulations driving fastest procurement scaling among Bangkok and Ho Chi Minh City plant-based manufacturers. SAMR extraction purity upgrades are forcing supplier qualification renewals, advantaging pre-compliant Japanese and Australian exporters.
- Animal Feed:Lower-specification biomass for aquaculture and livestock fortification with reduced documentation requirements.
- Pharmaceuticals:Clinical-grade isolates requiring novel food notifications under Japan's Ministry of Health, Labour and Welfare protocols.
Nutraceuticals anchor current value capture. Food and beverage applications are climbing the fastest as formulation pipelines mature.
Distribution Channel:
Customer type and order scale dictate channel economics and relationship intensity.
- Direct Sales:Vertically integrated cultivator-processor relationships displacing spot-market purchasing among Australian nutraceutical contract manufacturers. Japanese coastal facilities with proprietary fermentation protocols secure multi-year offtake agreements for paramylon-enhanced strains.
- Online:E-commerce platforms capturing branded ingredient sales to small-scale formulators and research institutions across Southeast Asia.
- Supermarkets:Mass-market retail for consumer-packaged spirulina and chlorella supplements in urban China and Japan.
- Specialty Stores:Health food and pharmacy channels emphasizing organic certification and origin transparency.
Direct sales dominate therapeutic-grade volumes. Online channels are gaining share fastest among emerging formulators.
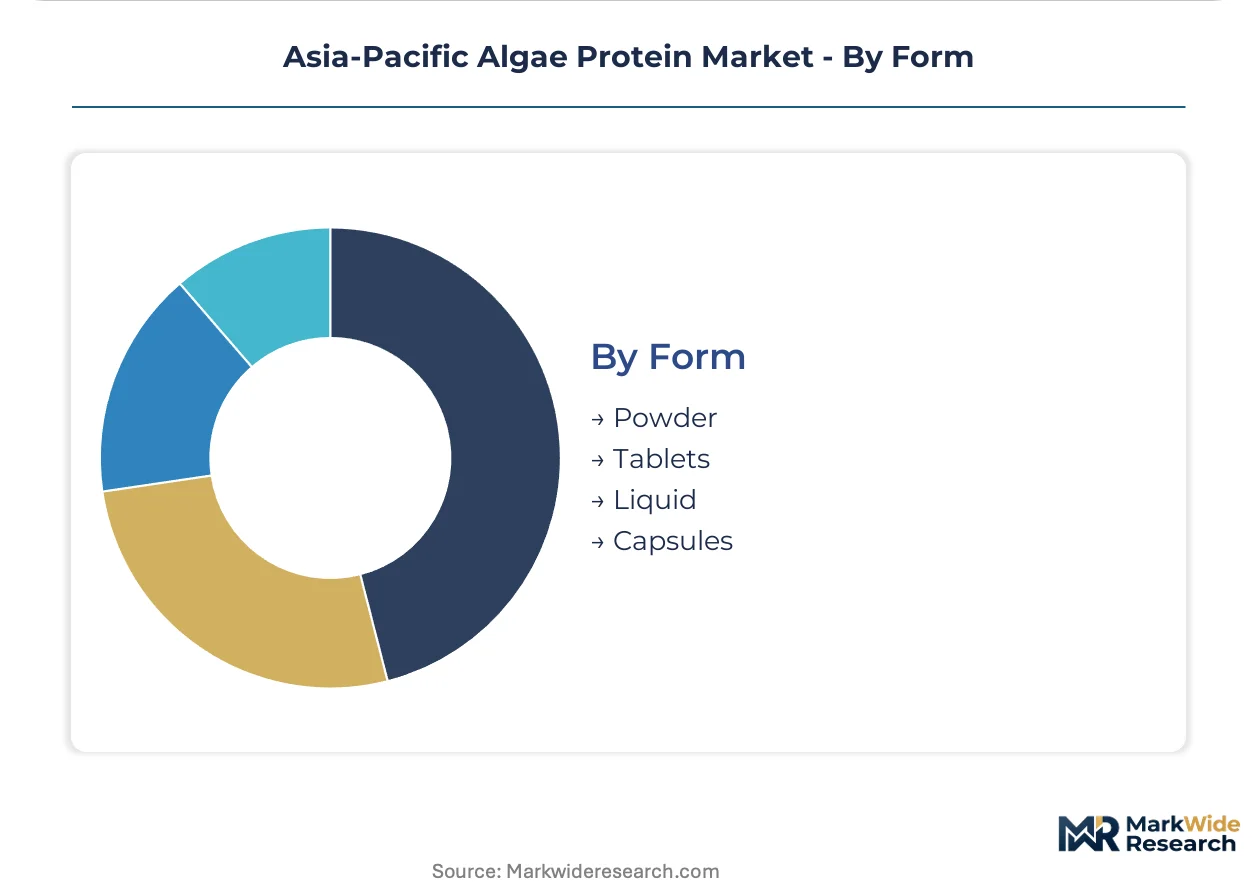
Form:
Processing depth and convenience requirements segment margin structures across the value chain.
- Powder:Bulk dried biomass and isolates processed through Zhejiang Binmei Biotechnology temperature-controlled lines for export markets. China's SAMR updated GB protocols mandate enhanced heavy metal documentation, compressing margins for non-compliant processors.
- Capsules:Encapsulated isolates for precise dosing in nutraceutical applications with premium positioning in Australian therapeutic markets.
- Tablets:Compressed formulations for consumer convenience in mass retail channels.
- Liquid:Suspensions and extracts for beverage fortification and specialized clinical nutrition.
Powder commands the established base. Capsule formats are expanding most quickly as precision dosing requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput infrastructure underwrites China's dominance in algae protein trade flows across the Asia-Pacific basin. Japanese coastal processing facilities and Australian nutraceutical corridors depend on this maritime backbone for biomass feedstock imports and finished isolate exports.
China
Shandong and Yunnan provinces host industrial-scale photobioreactor installations supplying downstream processors with high-purity biomass. SAMR's updated GB standards mandate enhanced heavy metal documentation for all food-grade algae isolates. Zhejiang Binmei Biotechnology anchors spirulina powder exports through temperature-controlled processing lines concentrated in Hangzhou-Ningbo corridor.
Japan
DIC Corporation leverages integrated cultivation-to-extraction infrastructure across coastal facilities for paramylon-enhanced strain production. The Ministry of Health, Labour and Welfare governs novel food notifications for microalgae-derived proteins entering therapeutic applications. Chitose Biome's fermentation protocols in Tsukuba exemplify proprietary biotechnology deployment for therapeutic-grade isolates.
Australia
Melbourne and Sydney contract manufacturing corridors concentrate demand for batch-to-batch protein variance below five percent. FSANZ-administered Food Standards Code dictates heavy metal and allergen thresholds for imported algae products. Direct procurement relationships with Japanese coastal facilities are displacing spot-market purchasing through trading houses.
Thailand
Bangkok-based plant-based food manufacturers scale spirulina offtake for meat analog formulations. Thai FDA alignment with ASEAN harmonized standards facilitates cross-border ingredient trade with Vietnam. Rayong Province's food processing estates attract toll-manufacturing investments from Chinese algae protein exporters.
India
FSSAI draft quality parameters for chlorella and spirulina supplements are extending market access timelines for foreign suppliers. Tamil Nadu's nutraceutical manufacturing belt absorbs therapeutic-grade imports for Ayurveda-integrated formulations. Parry Nutraceuticals' Chennai operations represent domestic cultivation capacity expansion.
Asia-Pacific Algae Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extraction and purification. The vendor base stratifies between vertically integrated cultivator-processors and toll-manufacturing intermediaries. Three archetypes dominate: coastal Japanese firms with proprietary fermentation infrastructure, Chinese processors with temperature-controlled drying lines, and Australian contract manufacturers with therapeutic-grade certification depth. Competitive moves center on multi-year offtake agreements and backward integration into photobioreactor cultivation assets.
Within the integrated-cultivator tier, DIC Corporation and Euglena Co. Ltd. anchor Japanese coastal production with proprietary paramylon-enhanced strain capabilities. Zhejiang Binmei Biotechnology occupies a position among Chinese temperature-controlled processors serving export markets. Among nutraceutical specialists, Parry Nutraceuticals exemplifies Indian domestic capacity expansion. These three represent distinct geographic and technological positioning without implying specific market share or strategic actions.
| Leading Market Players |
|---|
| Corbion N.V. |
| DIC Corporation |
| Cyanotech Corporation |
| Parry Nutraceuticals |
| Far East Bio-Tec |
| Hunan Sunfull Bio-tech |
| Euglena Co. Ltd. |
| Zhejiang Binmei Biotechnology |
| AstaReal Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's Hangzhou-Ningbo processing corridor anchors spirulina powder export capacity, concentrating biomass refinement economics and amplifying pricing leverage for compliant exporters into China's SAMR-regulated market. This geographic concentration interacts with downstream procurement patterns, as Australian nutraceutical contract manufacturers and Thai plant-based food formulators negotiate supply security against purity threshold compliance costs.
Pricing Analysis
China's SAMR GB standards dictate the pricing tier structure across therapeutic-grade isolates, separating premium paramylon-enhanced strains from standard spirulina biomass and economy-grade animal feed fractions. Certification depth under FSANZ and Japan's Ministry of Health, Labour and Welfare commands 15-25% premiums over baseline food-grade offerings. Pricing pressure stems from nutrient media and CO2 feedstock cost volatility squeezing open-pond operator margins. Food and beverage manufacturers in Bangkok and Ho Chi Minh City exhibit highest price sensitivity, while Melbourne and Sydney nutraceutical contract manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are proliferating among Japanese coastal processors to secure multi-year offtake agreements with Australian buyers. Biomass feedstock draws from China's Shandong and Yunnan photobioreactor installations, Japan's coastal cultivation facilities, and India's Tamil Nadu nutraceutical belt. Nutrient media, CO2 feedstock, and proprietary fermentation inputs constitute critical dependencies. Single-source vulnerability concentrates in Zhejiang province's temperature-controlled drying infrastructure. Distribution runs through direct procurement relationships displacing spot-market purchasing, with the Port of Shanghai underwriting regional trade flow efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific algae protein market is recovering from input cost cyclicality as energy markets stabilize and photobioreactor deployment accelerates across Shandong and Yunnan provinces.
For Market Incumbents: Pre-empt margin compression by securing captive biomass supply through backward integration into photobioreactor assets in Yunnan or coastal Japanese facilities. Accelerate dual GB-FSANZ certification investment to capture pre-compliant exporter advantages as China's SAMR tightens extraction purity thresholds. Counter emerging toll-manufacturing competitors in Rayong Province by locking multi-year therapeutic-grade offtake agreements with Melbourne and Sydney contract manufacturers. For New Entrants and Emerging Players: Vietnam's minimal domestic consumption relative to processing capacity represents the most penetrable entry point for branded ingredient suppliers establishing regional presence. Fermentation-convergence applications for paramylon-enhanced strains beyond nutrition offer unc contested therapeutic positioning. Target direct sales channel penetration among small-scale Southeast Asian formulators via e-commerce platforms before incumbent distributors consolidate relationships. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because therapeutic-grade certification depth and proprietary strain IP compound competitive moats over successive regulatory cycles. Acquisition candidates should demonstrate vertical integration from cultivation through extraction with established GB or FSANZ compliance documentation. Monitor India's FSSAI final quality parameter implementation as inflection indicator for market access timeline compression and import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Shandong and Yunnan installations lift high-purity biomass availability for downstream processors. |
| Dual Certification Investment | Simultaneous GB and FSANZ alignment accelerates product launch cycles for pre-compliant exporters. |
| Paramylon Strain Development | Proprietary fermentation protocols open therapeutic applications beyond conventional nutrition markets. |
| Direct Procurement Relationships | Melbourne and Sydney contract manufacturers secure supply by displacing spot-market purchasing. |
| Toll-Manufacturing Partnership | Rayong Province food processing estates attract Chinese exporter investment for ASEAN market access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with photobioreactor engineers, nutraceutical contract manufacturing procurement leads, plant-based food formulators, regulatory affairs specialists at SAMR and FSANZ, and algae cultivation facility managers. Secondary validation drew from customs trade databases, GB standard documentation, FSANZ Food Standards Code amendments, SEC filings of listed algae biotechnology firms, and ASEAN harmonized regulatory frameworks. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, distribution channel, and form dimensions.
Calibration against historical procurement patterns and regulatory implementation timelines anchored projection reliability across the analysis window. Segmentation modeling captured spirulina, chlorella, dunaliella, and emerging strain categories by nutraceutical, food and beverage, animal feed, and pharmaceutical end uses. CAGRs derived from fitted growth curves incorporating photobioreactor installation pipelines, SAMR standardization trajectories, and contract manufacturing capacity expansion in Melbourne and Sydney corridors. Industry-specific inputs included nutrient media cost indices and CO2 feedstock pricing volatility assumptions.
Practitioners should monitor India's FSSAI final notification timeline, China's SAMR enforcement intensity on heavy metal documentation, and photobioreactor engineering talent compensation inflation for early signals of forecast deviation risk. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Single Cell Protein Market