
 Fish Meal Alternative Market | 2026-2036
Fish Meal Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Meal Alternative Market Foresight
Aquaculture feed is rebalancing toward terrestrial and microbial inputs as marine ingredient volatility pressures cost structures. Cargill Inc. leverages its oilseed processing footprint to anchor plant-based protein supply chains across multiple continents. Calysta Inc. specializes in methane-to-protein fermentation technology that sustains consistent output regardless of ocean conditions. Protix competes through industrial-scale black soldier fly facilities that control feedstock traceability from waste stream to finished meal.
Fish meal alternatives comprise formulated protein products designed to replicate or exceed the amino acid density, digestibility coefficients, and palatability profiles of conventional marine meals in animal nutrition systems. Manufacturing routes span solvent-extracted oilseed meals, controlled fermentation of methanotrophic bacteria, and enzymatic processing of insect biomass to achieve crude protein specifications typically ranging from fifty to seventy percent by dry weight. Single-cell proteins occupy the fastest-expanding margin pool where fermentation yield improvements and carbon substrate diversification attract capital deployment. Insect meal leads on traceability premiums as EU feed hygiene regulations harden documentation requirements for aquaculture inclusion. Plant-based proteins retain volume dominance through soybean and pea protein concentrates that benefit from decades of agronomic optimization and established oilseed crushing infrastructure.
The EU Feed Hygiene Regulation and F-Gas Regulation shape ingredient approval pathways and processing energy costs for European manufacturers, while Norway's Seafood Research Fund and Peru's PRODUCE ministry enforce harvest quotas that directly constrain traditional fish meal availability. FDA Center for Veterinary Medicine oversight of novel feed ingredients in the United States creates a dual-track compliance burden for fermentation-derived and insect-based entrants. Stakeholders must monitor how carbon accounting frameworks evolve to either credit or penalize alternative protein production pathways relative to conventional marine harvesting.
Market Dynamics
Wild harvest quotas in Peru and Norway are compressing marine protein availability, forcing feed formulators to reconstitute supply chains around controlled-origin terrestrial and microbial inputs that bypass oceanic volatility entirely.
Growth Catalysts
- EU F-Gas Regulation:Carbon-intensive refrigeration for wild fish meal preservation faces escalating compliance costs, tilting procurement toward fermentation-derived proteins with lower process energy signatures.
- Shrimp farming corridors:Disease outbreaks across Southeast Asian aquaculture zones accelerate demand for traceable, pathogen-controlled alternative proteins that reduce biosecurity risk in intensive pond systems.
- Methane-to-protein fermentation:Industrial biogas offtake agreements create negative-cost carbon substrates, collapsing feedstock economics for single-cell protein producers relative to marine harvesting cycles.
Market Restraints
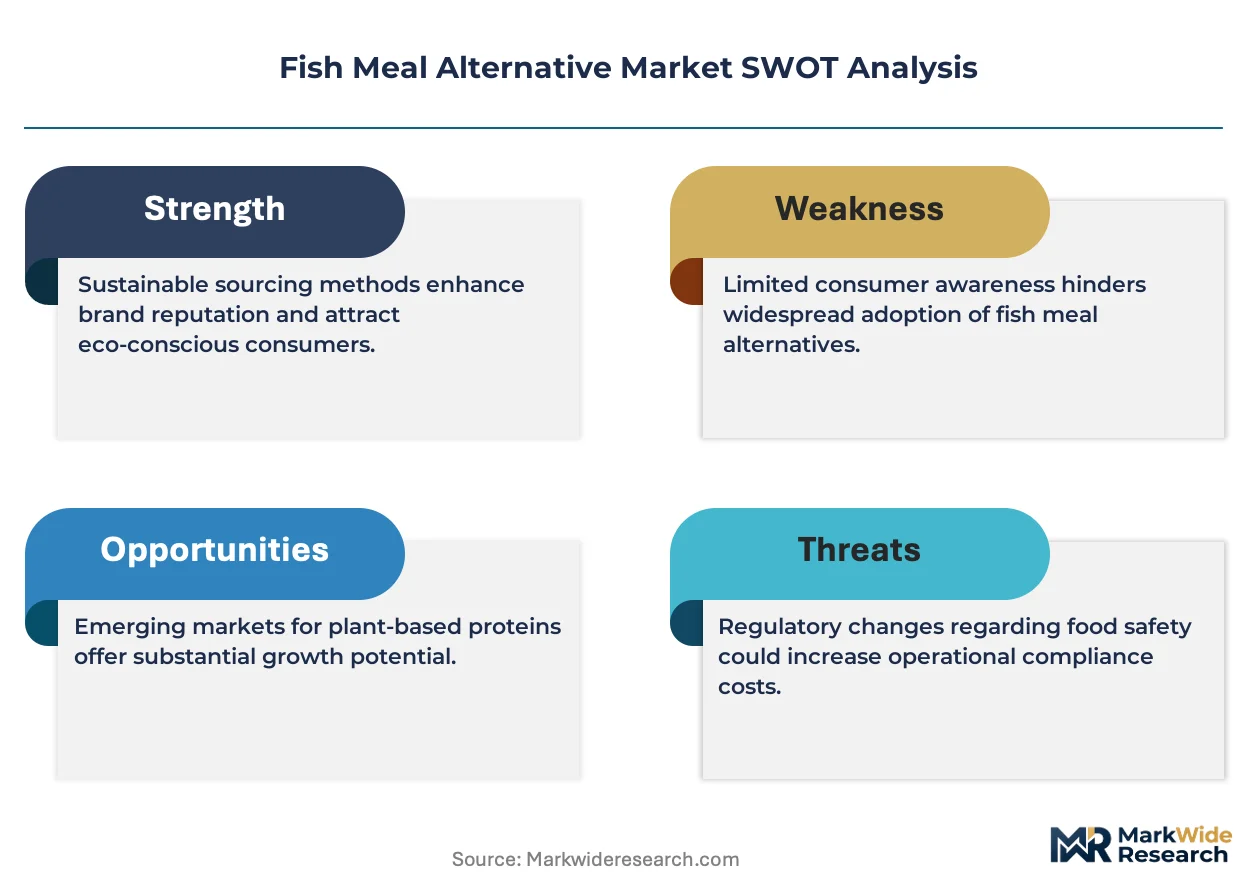
- Input cost volatility:Soybean and pea protein concentrate pricing tracks agricultural commodity futures, exposing formulators to weather-driven margin compression absent in traditional fish meal contracting.
- Supply concentration risk:Black soldier fly larvae production clusters in controlled-climate facilities near urban waste streams, creating geographic chokepoints vulnerable to local permitting delays.
- Regulatory friction:FDA Center for Veterinary Medicine novel ingredient approval timelines extend 18-36 months, freezing market access for fermentation-derived entrants awaiting feed additive designation.
Strategic Opportunities
- Indian aquaculture expansion:FSSAI feed safety standard harmonization with CODEX creates regulatory runway for insect meal inclusion in carp and pangasius diets across Andhra Pradesh and West Bengal.
- Carbon credit monetization:EU Green Deal carbon border adjustment mechanisms may credit methane-capture protein pathways, generating offset revenue streams unavailable to marine harvesters.
- Precision fermentation scale-up:Convergence of CRISPR strain optimization and continuous bioreactor design collapses capital intensity per ton of single-cell protein output below insect farming thresholds.
Industry Challenges
- Protein functionality matching:Formulation chemists struggle to replicate fish meal's precise amino acid digestibility coefficients in plant-based concentrates, requiring enzymatic pre-processing that erodes cost advantages.
- Certification timeline compression:ASC and BAP aquaculture certification schemes demand ingredient traceability documentation that legacy oilseed crushing infrastructure cannot supply without supply chain reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Meal Alternative Market |
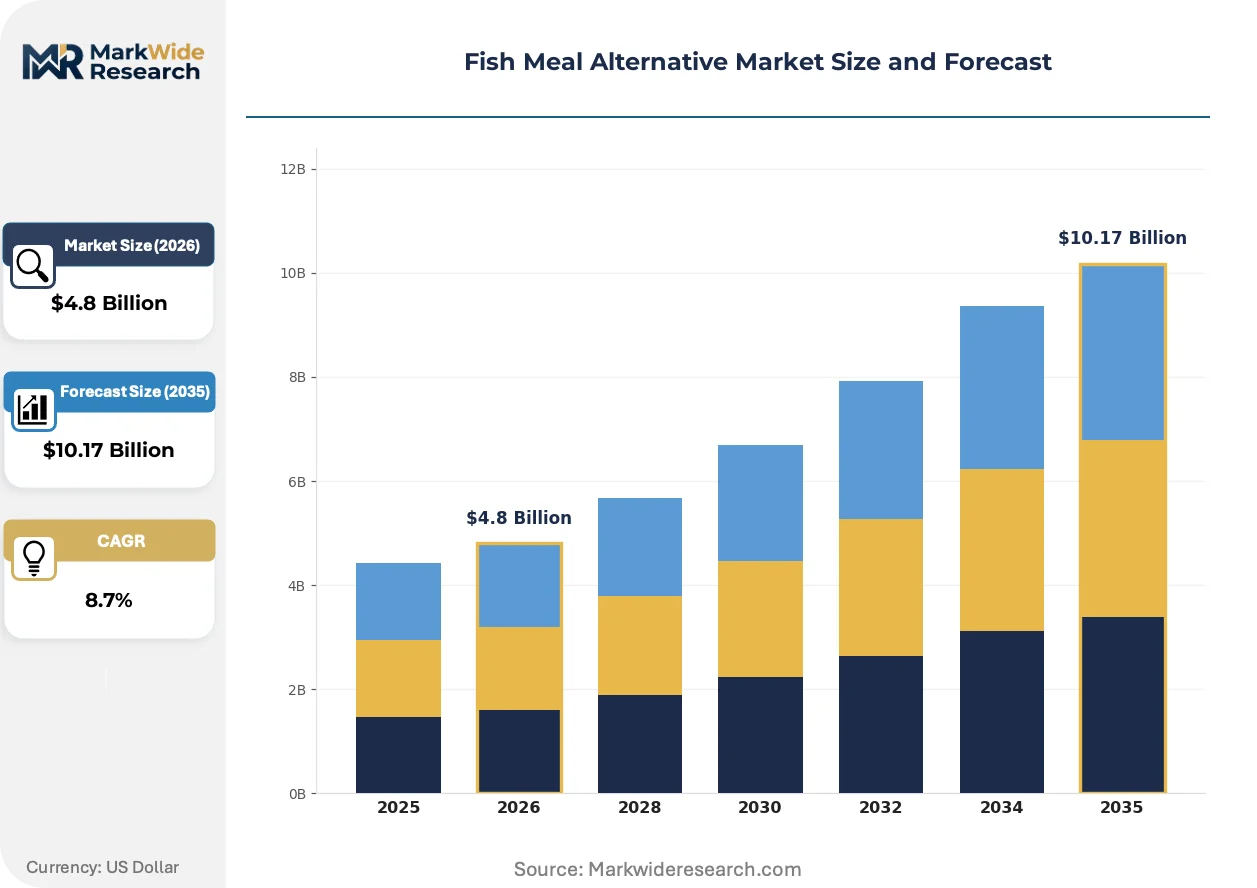
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Proteins, Insect Meal, Algae Meal, Single-Cell Proteins, Animal Byproducts Application: Aquaculture Feed, Livestock Feed, Pet Food, Poultry Feed, Swine Feed End User: Fish Farmers, Poultry Producers, Swine Farmers, Pet Food Manufacturers, Cattle Ranchers Distribution Channel: Direct Sales, Distributors, Online Retailers, Specialized Feed Stores, Cooperatives |
| Companies Covered | Cargill Inc., Archer Daniels Midland, Calysta Inc., Alltech, Angel Yeast Co. Ltd, Nutreco N.V., Protix, Ynsect, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Meal Alternative Market Shifts & Advancements
Fermentation and enzymatic processing architectures are collapsing the traditional distinction between feed-grade and food-grade protein production, enabling nutrient density specifications that match or exceed marine meal performance benchmarks.
Single-cell protein derived from methanotrophic bacteria is unifying carbon capture economics with feed manufacturing, allowing industrial emitters to monetize waste methane through offtake contracts with fermentation operators. Norwegian salmon feed formulators have advanced procurement timelines for these inputs by 18 months following PRODUCE ministry quota announcements. The technology is compressing the cost gap between alternative and marine proteins in high-value aquaculture segments.
REACH authorization requirements for novel feed additives are hardening documentation burdens for insect meal processors seeking EU market access, forcing facility upgrades to satisfy ECHA substance evaluation protocols. German compound feed manufacturers now require batch-level contaminant testing that exceeds prior industry norms. The regulatory friction most acutely affects black soldier fly entrants without existing oilseed infrastructure to absorb compliance overhead.
Long-term offtake contracting is displacing spot market purchasing among Southeast Asian shrimp integrators seeking price stability amid agricultural commodity volatility. Vietnamese and Indonesian processors now lock 24-36 month supply agreements directly with fermentation operators, bypassing traditional trading house intermediaries. This procurement model shift concentrates volume commitments with scale players capable of guaranteeing output consistency across climate cycles.
Fish Meal Alternative Market Segmentation
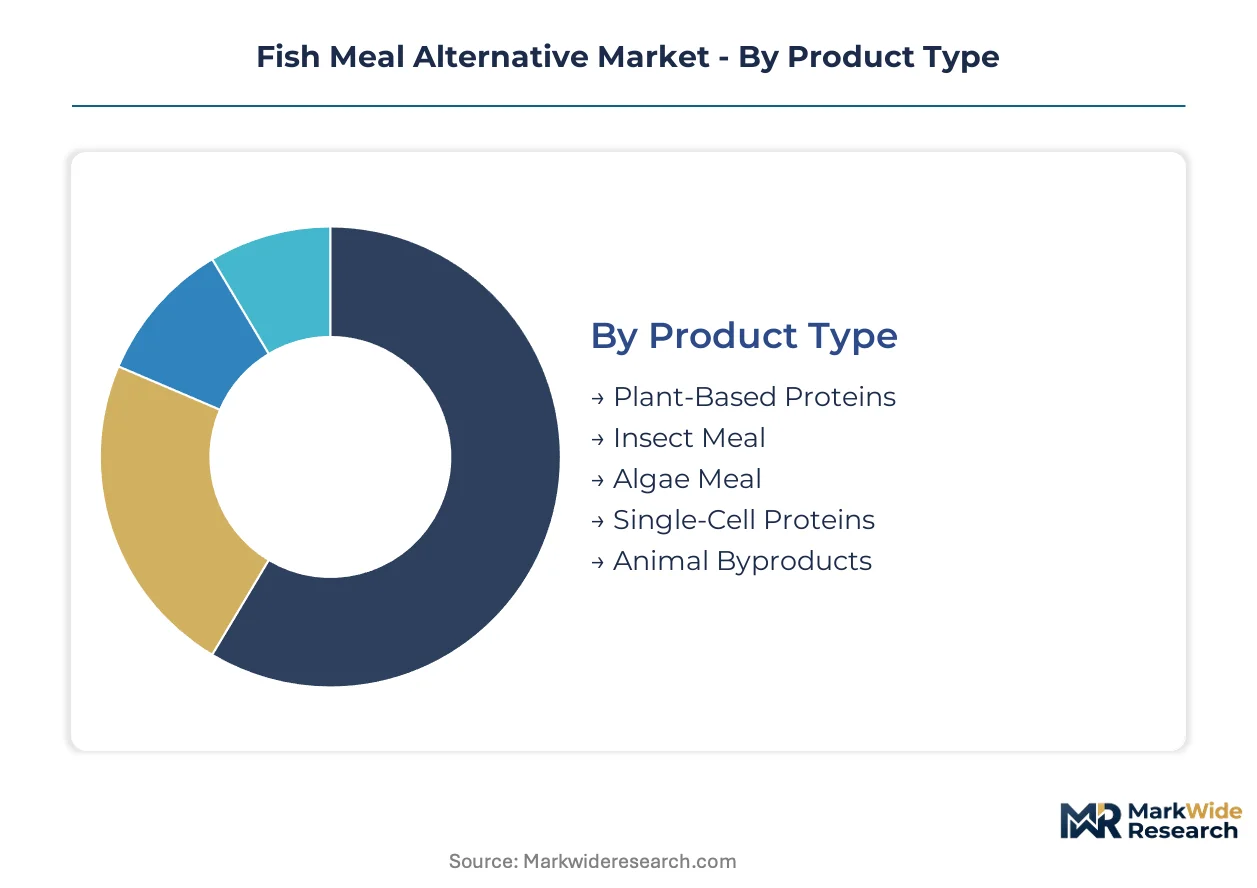
Alternative protein sourcing strategies diverge sharply across product categories, with fermentation infrastructure and insect farming requiring fundamentally different capital deployment timelines than oilseed crushing retrofits. Feed formulators select segments based on amino acid digestibility coefficients, pathogen traceability requirements, and biosecurity protocols specific to target species.
Product Type:
Capital intensity separates these five manufacturing pathways, with methanotrophic fermentation and industrial insect facilities demanding the steepest upfront investment before achieving economies of scale.
- Plant-Based Proteins:Soybean and pea protein concentrates leverage existing oilseed crushing infrastructure, achieving fifty to seventy percent crude protein through solvent extraction and enzymatic refinement. Demand concentrates in Vietnamese and Indonesian shrimp integrators seeking price stability through long-term offtake contracts that bypass agricultural commodity futures volatility.
- Single-Cell Proteins:Methanotrophic bacteria cultivated in continuous bioreactors convert waste methane into sixty-five to seventy percent protein biomass with minimal land footprint. Norwegian salmon feed formulators have accelerated procurement timelines following PRODUCE ministry quota announcements, drawn by fermentation's immunity to oceanic harvest cycles.
- Insect Meal:Black soldier fly larvae processed through enzymatic digestion deliver high digestibility with complete traceability from waste stream to finished product.
- Algae Meal:Phototrophic and heterotrophic cultivation routes yield omega-3 enriched biomass for premium aquaculture segments.
- Animal Byproducts:Rendered poultry meal and blood meal provide cost-competitive amino acid profiles in regions with established slaughterhouse infrastructure.
Most installed capacity flows through Plant-Based Proteins. Expansion is steepest in Single-Cell Proteins.
Application:
Volume distribution across these five feed categories reflects species-specific amino acid requirements and regulatory acceptance thresholds for novel ingredients.
- Aquaculture Feed:Salmon, shrimp, and carp diets demand precise lysine and methionine ratios that alternative proteins must match through formulation blending. Southeast Asian disease outbreaks have intensified procurement of controlled-origin ingredients that reduce biosecurity risk in intensive pond systems across Vietnam and Indonesia.
- Pet Food:Premium companion animal diets command traceability premiums that insect meal processors capture through batch-level contaminant documentation exceeding prior industry norms.
- Poultry Feed:Broiler and layer operations substitute alternative proteins at inclusion rates constrained by methionine bioavailability.
- Swine Feed:Growing-finishing diets tolerate higher plant protein inclusion than nursery phases, segmenting demand by production stage.
- Livestock Feed:Cattle feed applications remain limited by rumen microbial protein synthesis, restricting alternative protein value to dairy pre-calving rations.
Volume leadership sits with Aquaculture Feed. Pet Food captures the highest margin per ton.
End User:
Procurement sophistication varies across these five producer categories, determining whether direct fermentation offtake or distributor intermediation dominates purchasing patterns.
- Fish Farmers:Norwegian salmon producers and Southeast Asian shrimp integrators negotiate directly with Calysta and Protix for twenty-four to thirty-six month supply agreements, bypassing traditional trading houses to lock price stability across climate cycles.
- Pet Food Manufacturers:German and Dutch compounders enforce REACH authorization compliance that black soldier fly entrants without oilseed infrastructure struggle to satisfy.
- Poultry Producers:Integrators in Andhra Pradesh and West Bengal await FSSAI-CODEX harmonization before scaling insect meal inclusion in broiler diets.
- Swine Farmers:Contract growers depend on integrated processor formulations, limiting direct alternative protein procurement.
- Cattle Ranchers:Pasture-based operations show minimal engagement, while feedlot operators in grain-adjacent regions trial protein concentrates.
Direct contracting concentrates among Fish Farmers. Regulatory compliance burdens weigh heaviest on Pet Food Manufacturers.
Distribution Channel:
Channel selection reflects shipment scale, ingredient perishability, and the technical support required for formulation integration.
- Direct Sales:Fermentation operators and industrial insect processors ship bulk tonnage directly to aquaculture integrators, eliminating margin layers and enabling customized amino acid blending specifications.
- Distributors:Regional feed ingredient traders manage inventory risk for smaller poultry and swine operations lacking storage infrastructure for containerized alternative proteins.
- Specialized Feed Stores:Hobby aquaculture and premium pet food channels stock packaged insect meal and algae products with certified origin documentation.
- Cooperatives:Farmer-owned purchasing alliances aggregate demand for plant protein concentrates, achieving volume discounts unavailable to individual operations.
- Online Retailers:E-commerce penetration remains limited to small-package pet supplements and aquaculture hobbyist products.
Direct Sales captures the highest tonnage per transaction. Cooperatives expand fastest in Indian aquaculture corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian salmon feed corridors anchor procurement patterns as aquaculture integrators accelerate alternative protein contracting ahead of marine quota tightening.
Norway
Salmon feed formulators in Bergen and Trondheim regions negotiate directly with fermentation operators for twenty-four-month supply agreements. The Seafood Research Fund enforces harvest quotas that compress traditional fish meal availability. Aker Biomarine's processing complex in Sandefjord repurposes infrastructure for single-cell protein blending.
United States
Midwest oilseed crushing facilities supply solvent-extracted soybean concentrates to domestic aquaculture and pet food channels. FDA Center for Veterinary Medicine oversight creates eighteen-to-thirty-six-month approval timelines for novel fermentation-derived ingredients. Cargill's processing footprint in Minnesota anchors plant-based protein supply chains.
Germany
Compound feed manufacturers in Lower Saxony enforce REACH authorization compliance that exceeds prior industry norms for insect meal inclusion. The EU F-Gas Regulation elevates refrigeration costs for preserved marine meals. Protix's black soldier fly facility near Emsland supplies batch-level contaminant documentation.
Vietnam
Shrimp integrators in Mekong Delta provinces lock long-term offtake contracts to bypass agricultural commodity volatility. Disease outbreaks across intensive pond systems accelerate demand for controlled-origin ingredients. Can Tho processing clusters now source directly from fermentation operators rather than trading house intermediaries.
India
Andhra Pradesh carp and pangasius farmers await FSSAI feed safety standard harmonization with CODEX. The PLI scheme for food processing incentivizes domestic alternative protein manufacturing capacity. Visakhapatnam aquaculture corridors trial insect meal inclusion as biosecurity protocols harden.
Fish Meal Alternative Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation operators and insect processors scale bioreactor and larvae facilities ahead of regulatory approval timelines. The vendor base organizes around three strategic archetypes: oilseed-derived protein specialists leveraging existing crushing infrastructure, methanotrophic fermentation pioneers securing industrial methane offtake, and industrial insect farmers controlling waste-stream traceability. M&A activity concentrates on backward integration into carbon substrate supply, while technology licensing agreements accelerate geographic market entry.
Within the oilseed processing tier, Cargill Inc. and Archer Daniels Midland occupy positions anchored by decades of agronomic optimization and established infrastructure. Calysta Inc. exemplifies the methane-to-protein fermentation archetype through its focus on consistent output independent of oceanic conditions. Protix represents the industrial insect farming vector with facilities designed for feedstock traceability from waste stream to finished meal.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland |
| Calysta Inc. |
| Alltech |
| Angel Yeast Co. Ltd |
| Nutreco N.V. |
| Protix |
| Ynsect |
| Lallemand Inc. |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access, as carbon-intensive refrigeration for wild fish meal preservation faces escalating energy costs that tilt procurement toward fermentation-derived proteins with lower process signatures. Feed formulators now segment procurement across three certification tiers, with REACH-authorized single-cell proteins commanding structural premiums over conventional oilseed concentrates.
Pricing Analysis
Distributor margin compression runs through Southeast Asian trading house intermediaries as Vietnamese and Indonesian shrimp integrators lock twenty-four-to-thirty-six-month direct offtake contracts with fermentation operators. Three-tier pricing structure across premium, standard, and economy levels separates REACH-authorized insect meal from commodity soybean concentrates and unverified animal byproducts. Cost compression in plant-based tiers is intensifying because agricultural commodity futures expose formulators to weather-driven margin volatility absent in traditional fish meal contracting. Price sensitivity concentrates among Indian carp and pangasius farmers awaiting FSSAI-CODEX harmonization, while Norwegian salmon producers show lowest sensitivity due to marine quota-driven supply scarcity.
Supply Chain Analysis
Workforce availability constraints in Dutch and German black soldier fly facilities limit industrial-scale larvae production expansion despite rising EU feed hygiene documentation demands. Supply concentrates in Vietnam, Indonesia, and Norway, with Mekong Delta shrimp corridors and Bergen salmon feed clusters anchoring volume flows. Raw material dependencies center on methane offtake from industrial biogas facilities, solvent-extracted oilseed crushing output, and controlled organic waste streams for insect cultivation. Single-source vulnerability runs through Peruvian anchovy harvest cycles that remain tethered to El Niño oscillations. Distribution runs through direct bulk shipments to aquaculture integrators, bypassing regional trading houses for containerized alternative proteins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with wild harvest quota tightening in Norway and Peru driving steady substitution demand that locks in multi-year procurement contracts across aquaculture feed corridors.
For Market Incumbents: Deepen backward integration into methane substrate supply through industrial biogas offtake agreements that collapse feedstock economics for Calysta-type fermentation entrants. Anchor capacity addition in Andhra Pradesh and West Bengal ahead of FSSAI-CODEX harmonization, securing first-mover positioning as Indian aquaculture scales insect meal inclusion. Certification investment in REACH and EU Feed Hygiene Regulation compliance creates defendable moats against black soldier fly entrants lacking oilseed infrastructure to absorb documentation overhead. For New Entrants and Emerging Players: Launch via direct-to-integrator distribution models that bypass trading house margin layers in Vietnamese and Indonesian shrimp corridors, where disease outbreaks have accelerated demand for controlled-origin ingredients. Target pet food manufacturers in Germany and the Netherlands, where traceability premiums and batch-level contaminant documentation requirements exceed prior industry norms and reward new infrastructure. White-space penetration concentrates on precision fermentation scale-up, where CRISPR strain optimization and continuous bioreactor design collapse capital intensity per ton below insect farming thresholds. For Investors and Strategic Acquirers: Roll-up economics work for industrial insect processors because facility-level traceability documentation creates acquisition synergies that compound across EU regulatory jurisdictions. Five-to-ten-year viability rests on carbon credit monetization pathways as EU Green Deal border adjustment mechanisms may credit methane-capture protein routes. Acquisition target archetype: black soldier fly operators with existing waste-stream contracts and REACH authorization progress. The signal to watch is FDA Center for Veterinary Medicine novel ingredient approval velocity, as eighteen-to-thirty-six-month timelines freeze market access for fermentation-derived entrants awaiting feed additive designation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Norwegian salmon formulators lock twenty-four-month fermentation contracts ahead of PRODUCE ministry quota announcements. |
| Backward Integration | Methane-to-protein operators secure industrial biogas offtake to collapse carbon substrate cost structures. |
| Green Certification Program | REACH authorization compliance separates qualified EU insect meal processors from black soldier fly entrants lacking oilseed infrastructure. |
| Capacity Expansion | Continuous bioreactor deployment in Bergen and Trondheim regions anchors single-cell protein supply to aquaculture integrators. |
| Joint Venture | Indian PLI scheme partnerships incentivize domestic alternative protein manufacturing capacity across Visakhapatnam corridors. |
Research Methodology
Coverage spans Norway, Vietnam, Germany, India, and the United States, with primary inputs from each market's aquaculture feed formulators, fermentation R&D directors, regulatory affairs leads at novel ingredient developers, and procurement officers at Southeast Asian shrimp integrators. Secondary validation draws from FDA Center for Veterinary Medicine filings, ECHA REACH substance evaluations, FSSAI feed safety consultations, and Peruvian PRODUCE ministry harvest quota announcements. Bottom-up volume modeling triangulates against top-down protein substitution elasticity estimates across the analysis window.
Rate-of-change decomposition separates volume growth into aquaculture feed, pet food, poultry feed, swine feed, and livestock feed application segments, with additional modeling across plant-based proteins, single-cell proteins, insect meal, algae meal, and animal byproducts product categories. CAGRs derive from fitted trend extrapolation adjusted for regulatory approval timeline risk and carbon credit policy evolution. Industry-specific forecast inputs include El Niño oscillation patterns affecting Peruvian anchovy yields and EU F-Gas Regulation refrigeration cost escalation curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt wild harvest quota expansion or accelerated FDA approval pathways for novel fermentation ingredients. Forecasts reflect assumptions about methane substrate cost stability, insect meal facility permitting velocity, and agricultural commodity futures volatility. Material deviation in Norwegian Seafood Research Fund quota announcements or Indian FSSAI-CODEX harmonization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Vegan Caviar Market