
 Inorganic Catalyst Market | 2026-2036
Inorganic Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Catalyst Market Intelligence
ISO 9001 quality management certification, alongside specific end-user performance trials, is redrawing the supplier qualification process for inorganic catalysts. BASF SE leverages its extensive R&D infrastructure to develop catalysts for complex chemical synthesis applications. Albemarle Corporation specializes in catalysts for hydroprocessing within the refinery sector. Clariant International Ltd positions itself with specialty catalysts for environmental applications like emissions control.
Inorganic catalysts are substances, typically solid metals or metal compounds, that accelerate chemical reactions without being consumed. Their efficacy depends on surface area, porosity, and specific active sites, such as those on zeolites or platinum. Heterogeneous catalysts dominate due to their ease of separation in large-scale industrial processes like petrochemical processing. Demand for transition metal catalysts is rising, driven by their use in polymerization and specialized chemical synthesis.
Environmental regulations, including the US EPA's Tier 3 standards and Europe's REACH framework, mandate advanced catalysts to reduce pollutants. China's MEE enforces strict emission limits on industrial facilities, directly shaping catalyst requirements for chemical plants. Producers must navigate a complex trade-off between catalyst performance, raw material costs, and compliance with evolving global environmental mandates.
Market Dynamics
Intensifying environmental regulations worldwide are compelling a fundamental redesign of inorganic catalysts. Mandates for lower emissions from industrial facilities and transportation fuels are directly influencing catalyst composition, porosity, and the selection of active metallic components to meet new performance and sustainability benchmarks.
Growth Catalysts
- Petrochemical Demand:Demand from the petrochemical sector for hydroprocessing catalysts is expanding to meet stricter sulfur limits in transportation fuels, particularly in Asia-Pacific and Middle Eastern refining hubs.
- European Regulations:Europe's REACH framework and Green Deal initiatives are pushing for more efficient, less toxic catalysts in chemical manufacturing, creating demand for innovative formulations in polymer production.
- Zeolite Technology:The adoption of advanced zeolite-based catalysts in fluid catalytic cracking (FCC) processes is increasing due to their superior selectivity and ability to produce higher-octane gasoline components.
Market Restraints
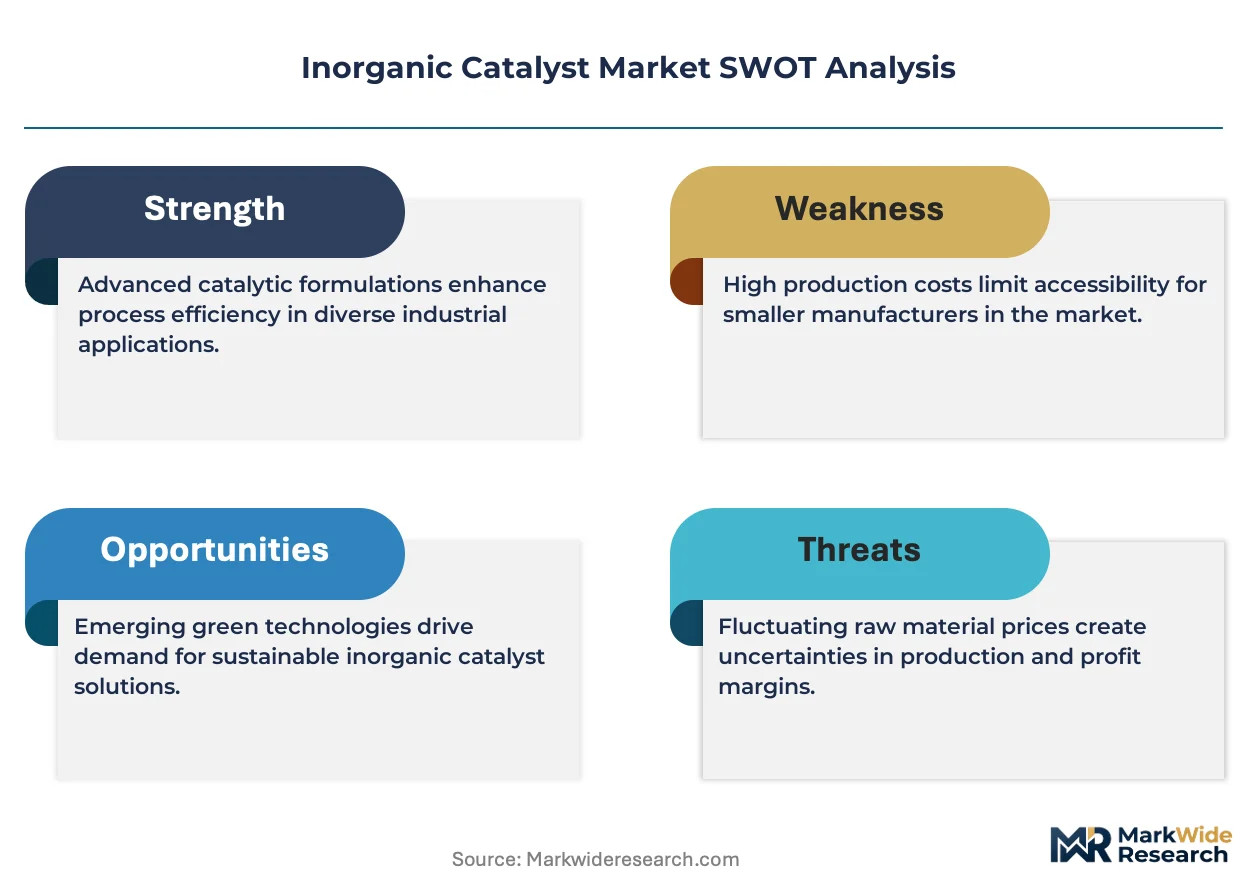
- Raw Material Volatility:Volatility in the prices of precious metals like platinum and palladium, critical components for many high-performance catalysts, creates significant cost uncertainty and margin pressure for manufacturers.
- Supply Chain Concentration:The supply of certain rare earth elements, often used as promoters or supports, is highly concentrated geographically, posing geopolitical and availability risks for the global catalyst supply chain.
- Catalyst Deactivation:The gradual deactivation of catalysts due to coking, poisoning, or sintering remains a persistent technical barrier, requiring costly regeneration cycles or premature replacement in industrial processes.
Strategic Opportunities
- Green Energy Transition:Catalysts for green hydrogen production through electrolysis and for carbon dioxide conversion into valuable chemicals represent a significant new market, driven by global decarbonization commitments.
- China's Environmental Goals:China's "dual carbon" policy and stricter MEE standards for industrial VOCs are creating opportunities for advanced environmental catalysts in sectors like coatings, power generation, and steel production.
- AI-Driven Discovery:The integration of catalyst design with artificial intelligence for high-throughput screening can accelerate the discovery of novel materials with optimized performance for highly specific reactions.
Industry Challenges
- Complex Qualification Processes:Navigating divergent and lengthy supplier qualification requirements, which include ISO 9001 certification and end-user-specific pilot plant trials, significantly delays market entry for new catalyst products.
- Intellectual Property Protection:Protecting IP for novel catalyst formulations and proprietary manufacturing processes is increasingly challenging, especially in multi-partner joint ventures or across different legal jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Catalyst Market |
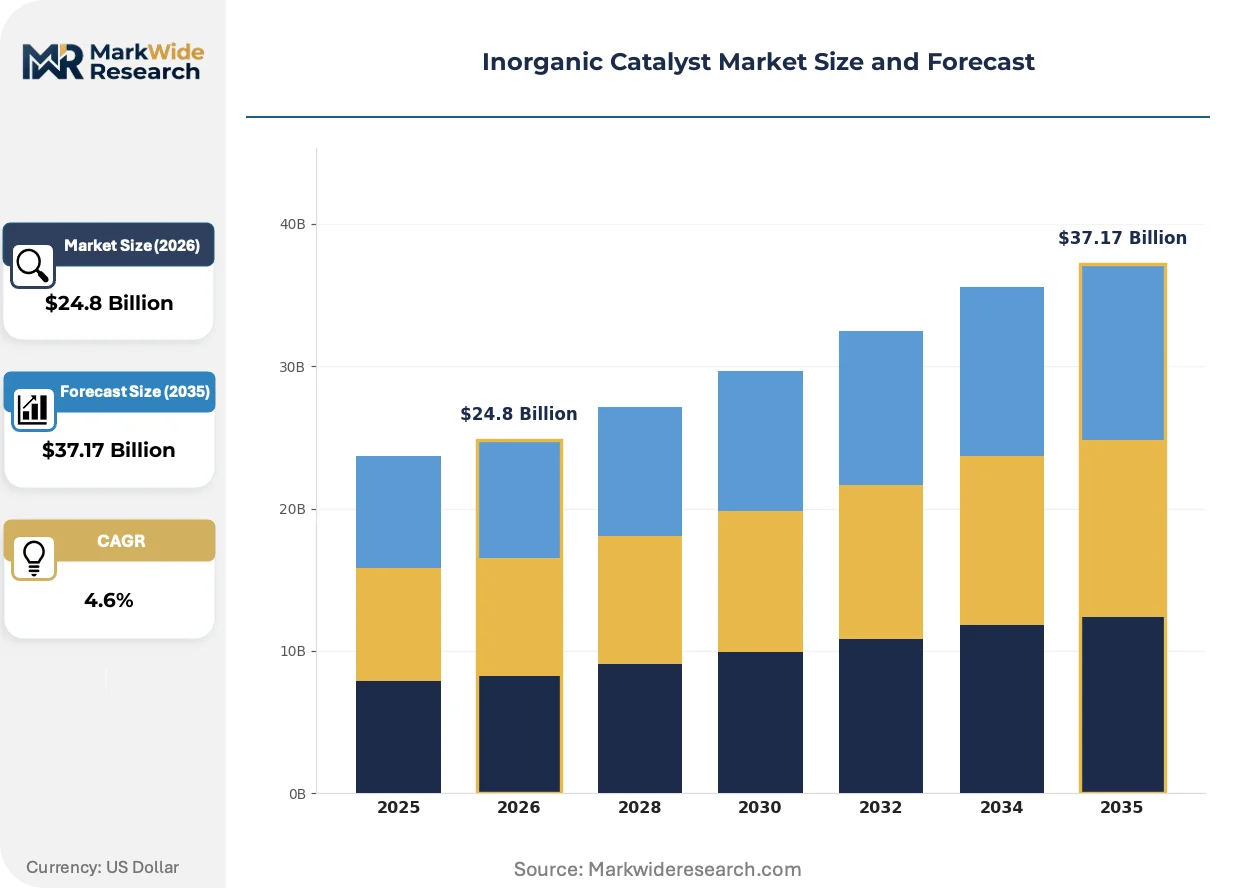
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Catalysts, Transition Metal Catalysts, Homogeneous Catalysts, Heterogeneous Catalysts Application: Chemical Synthesis, Polymerization, Petrochemical Processing, Environmental Applications End User: Chemical Industry, Automotive Sector, Pharmaceuticals, Agriculture Technology: Hydrocracking, Catalytic Reforming, Ammonia Synthesis, Fischer-Tropsch Synthesis |
| Companies Covered | LyondellBasell Industries Holdings B.V., DOW, BASF SE, W. R. Grace & Co.-Conn., Haldor Topsoe A/S, Albemarle Corporation, Arkema, Clariant International Ltd, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Catalyst Market Strategic Shifts & Innovations
Material science innovation is reshaping the inorganic catalyst development cycle, moving beyond incremental gains. This evolution is driven by the dual pressures of achieving sustainability targets and enabling more complex, resource-efficient chemical synthesis pathways.
Advanced Catalyst Architectures
Single-atom catalysts (SACs) feature isolated metal atoms anchored on a support, maximizing atomic efficiency for specific transformations. Academic and corporate R&D in specialty chemicals are leading adoption, though industrial scale-up remains in early stages. This technology is supplanting traditional nanoparticle catalysts in high-value applications where selectivity and minimal metal usage are paramount.
Regulatory-Driven Upgrades
The US Environmental Protection Agency's (EPA) Tier 3 standards impose stricter limits on sulfur in gasoline and vehicle emissions. This regulation necessitates advanced hydrodesulfurization (HDS) and hydrodenitrogenation (HDN) catalysts within petroleum refineries. Refinery operators are most affected, forcing investment in catalyst upgrades to produce cleaner fuels for the domestic market.
Performance-Based Selection
A shift toward performance-based qualification is altering catalyst supplier selection by large chemical and refining companies. Simple specification sheets are replaced by rigorous pilot plant trials validating catalyst lifetime and activity. This trend is most visible in China's new large-scale chemical industrial parks, which demand performance guarantees before procurement.
Inorganic Catalyst Market Segmentation
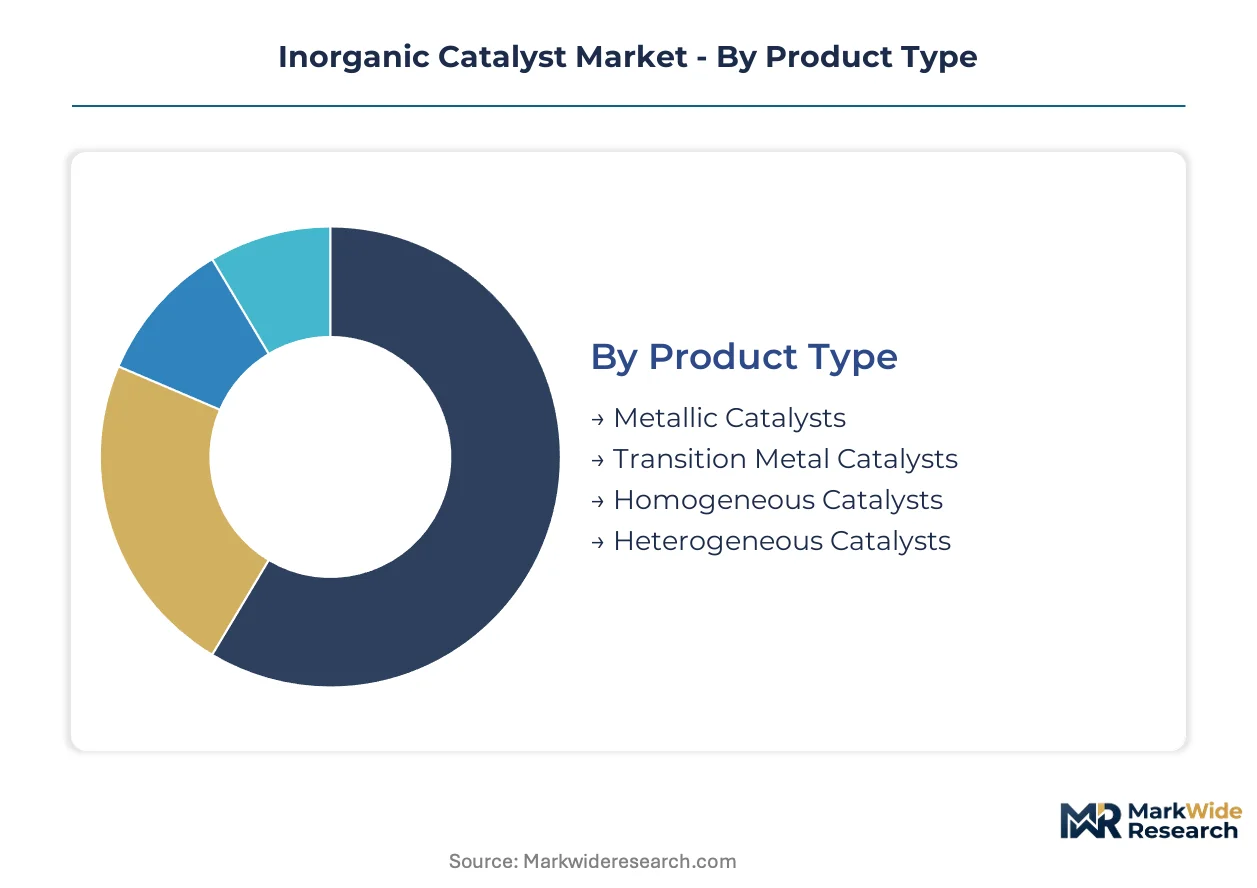
The inorganic catalyst market is structured by distinct product types, applications, end-users, and core technologies. This segmentation reflects the diverse chemical processes and industrial demands driving catalyst innovation and deployment. Understanding these divisions reveals specific growth pockets and technological shifts across the global chemical landscape.
Product Type:
The geographic spread of manufacturing capabilities influences the prevalence of specific inorganic catalyst types. Certain catalyst formulations are more readily produced and exported from established chemical hubs.
- Heterogeneous Catalysts:These solid catalysts operate in a different phase from reactants, facilitating easy separation and regeneration in large-scale industrial processes. Demand concentrates in petrochemical processing facilities across the Middle East and Asia-Pacific for fuel production.
- Transition Metal Catalysts:Catalysts based on transition metals like platinum, palladium, and nickel are crucial for polymerization reactions and specialized chemical synthesis due to their variable oxidation states. China's expanding polymer and synthesis projects drive significant demand for these catalysts.
- Metallic Catalysts:Composed primarily of metals or metal alloys, these catalysts are widely used in hydrogenation, oxidation, and other core chemical reactions. Their application spans various industrial sectors requiring high activity.
- Homogeneous Catalysts:These catalysts exist in the same phase as the reactants, often liquids, offering high selectivity but posing challenges for separation and recovery. Pharmaceutical and fine chemical synthesis frequently employs homogeneous catalyst systems.
Heterogeneous Catalysts hold the largest share; momentum sits with Transition Metal Catalysts.
Application:
The breadth of application for inorganic catalysts directly correlates with the scale and complexity of industrial chemical processes. Each application area demands specific performance characteristics from the catalyst system.
- Petrochemical Processing:Catalysts are essential for refining crude oil into fuels and chemical feedstocks, including hydroprocessing for sulfur removal and catalytic cracking for gasoline production. Stricter sulfur limits in transportation fuels, particularly in India and Saudi Arabia, compel catalyst upgrades.
- Environmental Applications:These catalysts mitigate industrial emissions and pollutants from stationary and mobile sources, including vehicle exhaust and industrial flue gases. Europe's Green Deal initiatives push for innovative formulations to meet stringent emission reduction targets.
- Chemical Synthesis:Inorganic catalysts enable the efficient production of a vast array of chemicals, including bulk chemicals, specialty chemicals, and intermediates. Advanced materials and process optimization in Germany and Japan drive catalyst innovation for complex synthesis.
- Polymerization:Catalysts facilitate the formation of long-chain polymers from monomers, critical for plastics, rubbers, and fibers. Large-scale polymer projects in China and the United States require high-performance catalysts for efficient production.
Petrochemical Processing applications generate the highest volume; Environmental Applications show the steepest expansion trajectory.
End User:
The type of end-user industry dictates the specific requirements for catalyst performance, durability, and regulatory compliance. Each sector faces unique operational and environmental challenges.
- Chemical Industry:This sector utilizes inorganic catalysts for the production of fertilizers, plastics, synthetic fibers, and a wide range of organic and inorganic chemicals. Large-scale chemical industrial parks in China demand performance guarantees before procurement.
- Automotive Sector:Catalysts in this sector primarily address emissions control in internal combustion engines, converting harmful pollutants into less toxic substances. The US EPA's Tier 3 standards necessitate advanced catalyst technology for vehicle emissions.
- Pharmaceuticals:Catalysts are crucial in the synthesis of active pharmaceutical ingredients (APIs) and intermediates, where high selectivity and purity are paramount. Specialized chemical companies in Switzerland and Ireland develop catalysts for complex drug synthesis.
- Agriculture:Catalysts are employed in the production of ammonia for fertilizers and other agrochemicals, supporting global food production. India's agricultural sector relies on efficient ammonia synthesis for crop yield enhancement.
The Chemical Industry represents the largest consumer base; the Automotive Sector is gaining share fastest due to regulatory pressures.
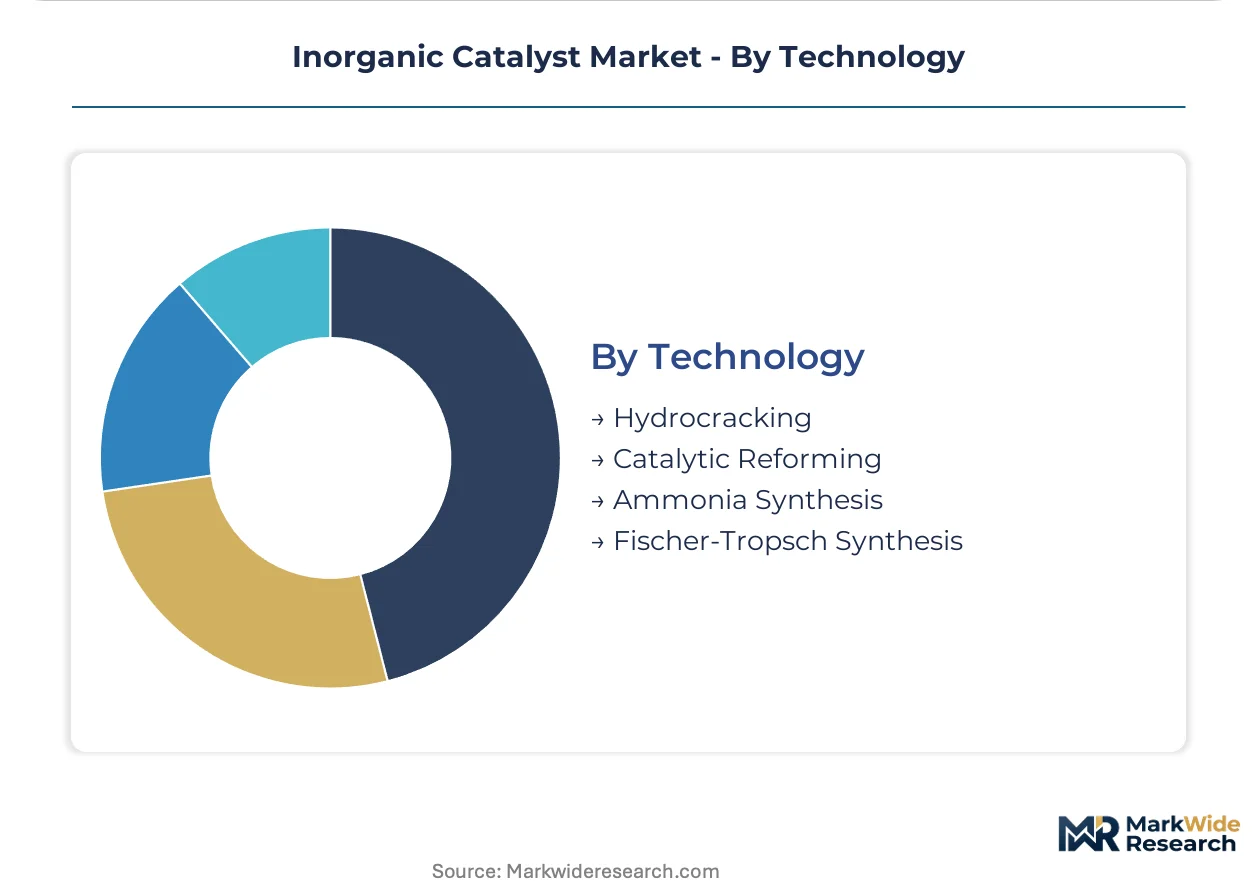
Technology:
The operational focus and specific chemical reactions define the various catalyst technologies employed across industries. Each technology optimizes a particular process for efficiency, yield, or environmental compliance.
- Hydrocracking:This technology uses catalysts to convert heavy petroleum fractions into lighter, higher-value products like gasoline and diesel, while also removing sulfur and nitrogen. Refinery operators in the United States invest in hydrocracking technology for cleaner fuel production.
- Ammonia Synthesis:This process, primarily the Haber-Bosch process, uses iron-based catalysts to synthesize ammonia from nitrogen and hydrogen, a cornerstone for fertilizer production. Large chemical plants in Russia and the Netherlands operate extensive ammonia synthesis facilities.
- Catalytic Reforming:This process converts low-octane naphtha into high-octane gasoline components and aromatic hydrocarbons using platinum-rhenium catalysts. Refineries in South Korea and Singapore utilize catalytic reforming to meet fuel quality standards.
- Fischer-Tropsch Synthesis:This technology converts syngas (carbon monoxide and hydrogen) into liquid hydrocarbons, primarily used for synthetic fuels or chemical feedstocks. South Africa and Qatar operate Fischer-Tropsch plants for gas-to-liquids conversion.
Hydrocracking technology holds a significant share; Ammonia Synthesis demonstrates robust and consistent demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental regulations and decarbonization commitments are driving shifts in inorganic catalyst demand across major industrial economies. Governments implement policies to promote cleaner production and reduce emissions. This regulatory impetus shapes investment priorities and technological advancements in key chemical manufacturing hubs.
China
China's "dual carbon" policy and stringent MEE standards create demand for advanced environmental catalysts. Large-scale polymer and synthesis projects in chemical industrial parks require high-performance transition metal catalysts. The Yangtze River Delta region, a dense chemical manufacturing base, experiences significant investment in catalyst upgrades.
Germany
The European Green Deal pushes for more efficient, less toxic catalysts in chemical manufacturing, fostering innovation. Advanced materials and process optimization in German chemical synthesis drive demand for specialized catalysts. Companies in the Rhine-Main region actively develop new catalyst formulations for sustainable production.
United States
US EPA's Tier 3 standards mandate advanced hydrodesulfurization (HDS) and hydrodenitrogenation (HDN) catalysts for cleaner fuels. Refinery operators in the Gulf Coast region invest in catalyst upgrades to comply with these stricter limits. The chemical industry in Texas, a major petrochemical hub, requires diverse catalysts for bulk chemical production.
India
India's agricultural sector relies on efficient ammonia synthesis for crop yield enhancement, driving catalyst demand. Stricter sulfur limits in transportation fuels compel catalyst upgrades in petrochemical processing facilities. Industrial clusters in Gujarat, a prominent chemical manufacturing state, prioritize catalyst efficiency for fuel and fertilizer production.
Saudi Arabia
Saudi Arabia's expansion in refining capacity and petrochemical production increases demand for hydroprocessing catalysts. Vision 2030 targets emphasize industrial growth, including large-scale chemical projects. Industrial cities like Jubail, central to Saudi Arabia's petrochemical strategy, are key consumers of advanced catalysts for fuel and chemical production.
Inorganic Catalyst Market Key Industry Players
Listed leaders compete with private specialists across inorganic catalyst development and supply. The market structure exhibits consolidation among top-tier global chemical companies, alongside a fragmented landscape of niche players providing specialized solutions. Strategic archetypes include diversified chemical giants, specialized catalyst manufacturers, and technology innovators focused on sustainability. Dominant competitive moves involve strategic partnerships for R&D and targeted capacity expansion to meet evolving regional demand.
Specialists in advanced catalyst solutions include BASF SE, a German-based AG that represents a diversified chemical giant leveraging extensive R&D infrastructure for complex chemical synthesis. Albemarle Corporation, a US-based Corporation, exemplifies a specialized catalyst manufacturer focusing on hydroprocessing within the refinery sector. Clariant International Ltd, a Swiss-based Ltd, occupies a position as a provider of specialty catalysts for environmental applications like emissions control. These entities collectively anchor innovation and market presence across various critical end-use segments, adapting to regulatory pressures.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| DOW |
| BASF SE |
| W. R. Grace & Co.-Conn. |
| Haldor Topsoe A/S |
| Albemarle Corporation |
| Arkema |
| Clariant International Ltd |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Typical catalyst replacement cycles, often spanning 1-5 years depending on application intensity, directly influence long-term contract pricing and shape strategic inventory holdings for major industrial consumers.
Pricing Analysis
ISO 9001 quality management certification creates the primary spread in inorganic catalyst pricing, distinguishing premium formulations from standard offerings. The dominant pricing structure involves contract-based long-term offtake agreements for large-volume petrochemical and chemical industry buyers. Price differentiation stems from catalyst performance guarantees and precious metal components like platinum. Pricing pressure arises from raw material cost volatility, especially for transition metals, impacting manufacturers' margins. Petrochemical processing exhibits lower price sensitivity due to performance criticality; commodity chemical production is more cost-driven.
Supply Chain Analysis
Geopolitical tensions impacting rare earth element supply from China underwrite a significant structural risk for catalyst manufacturers. The supply chain for critical raw materials, including platinum and palladium, draws heavily from South Africa and Russia. Logistics chokepoints, such as major shipping lanes, introduce additional vulnerability and cost fluctuations. Distribution runs through direct sales channels to large industrial facilities and specialized chemical distributors globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This inorganic catalyst market requires a robust substitution defense, as emerging biocatalysts and enzyme technologies threaten to displace traditional chemical synthesis routes in certain applications.
For Market Incumbents: Secure long-term raw material supply agreements, particularly for precious metals like platinum and palladium, to mitigate price volatility and ensure production continuity. Invest in advanced R&D for next-generation catalyst architectures, such as single-atom catalysts, to defend against performance threats from novel materials. Strategic capacity expansion in key growth regions like China can reinforce market presence against intensifying local competition.
For New Entrants and Emerging Players: Anchor in niche applications requiring high selectivity and lower operating temperatures, such as specialized pharmaceutical synthesis or fine chemical production. Target environmental applications in emerging economies, where evolving MEE standards in China create demand for advanced emissions control solutions. A go-to-market angle focusing on AI-driven catalyst discovery platforms can offer a distinct performance advantage.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced catalyst manufacturing, driven by complex synthesis requirements for high-performance materials. Long-term viability over a 5-10 year window favors firms with deep intellectual property and R&D capabilities. Acquisition targets should be specialized catalyst manufacturers focusing on green energy transition or environmental applications. The signal to watch is successful industrial scale-up of single-atom catalysts for broader adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands production capabilities to meet rising demand from China's large-scale polymer projects. |
| Joint Venture | Accelerates AI-driven catalyst discovery, optimizing formulations for specific complex chemical reactions. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns production processes with Europe's REACH framework. |
| R&D Investment | Develops next-generation single-atom catalysts for high-value applications requiring extreme selectivity. |
| Long-term Supply Agreement | Secures consistent access to precious metals, mitigating raw material price volatility for manufacturers. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. Primary insights gathered from plant managers, R&D directors, and chemical company procurement leads informed market nuances. Secondary validation drew from customs data, industry reports, and regulatory filings from the US EPA and ECHA. Rigorous bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
Sensitivity analysis informed the forecast framework, ensuring robustness across the modeling period. The market was segmented by product type, application, end-user, technology, and regional production hubs. Compound annual growth rates derived from historical trends, projected industrial output, and anticipated regulatory impacts. Key inputs included global crude oil prices and evolving environmental emission standards.
Decision-makers should treat outputs as directional under current geopolitical and technological assumptions; material deviation warrants model refresh. Practitioners should keep alternative scenarios live as raw material supply dynamics and technological breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Refining Catalysts Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Catalyst Handling Services Market
Catalysts
Precious Metal Catalysts Market