
 Platinum and Palladium Carbon Catalyst Market | 2026-2036
Platinum and Palladium Carbon Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum and Palladium Carbon Catalyst Market Outlook
Market Context
REACH is expanding the cost-of-entry calculus for catalyst suppliers serving European chemical manufacturers. Johnson Matthey leverages its precious metals refining heritage to sustain long-term supply agreements with hydrogen infrastructure developers. BASF anchors its position through backward integration into platinum group metal sourcing. Umicore competes via closed-loop recycling capabilities that reduce virgin metal dependence.
Technical Definition and Segment Structure
Platinum and palladium carbon catalysts consist of nanoscale noble metal particles dispersed on activated carbon supports, typically containing 0.5-10 wt% metal loading, functioning primarily to accelerate hydrogenation, dehydrogenation, and electrochemical reactions in industrial processes. Palladium catalyst dominates current volume owing to established pharmaceutical and fine chemical synthesis demand, while bimetallic formulations represent the fastest-growing product category as engineers optimize activity-selectivity tradeoffs for proton exchange membrane fuel cells. Hydrogen generation applications command premium positioning within the application matrix, whereas emission control remains the most mature segment with consolidated buyer power among automotive OEMs.
Regulatory Frame and Outlook
The EPA enforces Tier 3 emission standards that sustain palladium loading requirements in North American catalytic converters, while EMA guidelines shape pharmaceutical manufacturing validation protocols for catalyst reuse cycles. China's MEE implements dual carbon goals that redirect refinery hydrogen production toward lower-carbon pathways. Stakeholders must monitor evolving critical minerals designations that could reshape platinum group metal trade flows and inventory strategies.
Market Dynamics
The energy transition is compressing catalyst development cycles as hydrogen infrastructure developers demand higher metal efficiency and longer service intervals than conventional petrochemical applications require.
Growth Catalysts
- EU Green Deal emission benchmarks:Industrial catalyst users face tightening carbon intensity requirements that favor high-activity platinum and palladium formulations capable of operating at lower temperatures with reduced metal loading.
- Proton exchange membrane fuel cells:Bimetallic catalyst architectures are displacing single-metal designs in electrolyzer stacks, creating pull-through demand for precision-engineered carbon supports with controlled pore distributions.
- German green hydrogen pilot projects:Chemical manufacturers in the Ruhr industrial cluster are scaling electrolyzer deployments that specify catalysts with verified durability under intermittent renewable power input.
Market Restraints
- Platinum group metal price volatility:South African mining concentration and refining bottlenecks expose catalyst producers to input cost swings that compress margin predictability in long-term supply contracts.
- REACH registration burden:ECHA's expanding substance evaluation protocols extend time-to-market for novel catalyst formulations, particularly for nanoscale particle variants with uncertain toxicological profiles.
- Homogeneous catalysis substitution:Organometallic catalyst systems in fine chemical synthesis are capturing select hydrogenation applications where product separation economics favor soluble rather than heterogeneous approaches.
Strategic Opportunities
- Closed-loop metal recovery:Spent catalyst recycling infrastructure in Belgium and Germany offers feedstock security independent of primary mining supply chains, with Umicore's Hoboken facility processing kiloton-scale precious metal streams.
- Ammonia cracking for hydrogen transport:Japanese shipping consortia are evaluating palladium-rich membrane catalysts for maritime fuel cell applications, opening a volume segment beyond stationary power.
- US Inflation Reduction Act hydrogen production credits:Treasury guidance on clean hydrogen tax incentives is redirecting refinery and chemical plant investment toward electrolyzer-based supply chains that specify high-performance catalyst loadings.
Industry Challenges
- Electrochemist talent scarcity:The specialized skill set spanning surface science, carbon materials, and membrane electrode assembly integration commands premium compensation and extends R&D team buildout timelines.
- MEA integration complexity:Catalyst suppliers must coordinate particle size distribution and ionomer compatibility with membrane manufacturers, creating technical interface risk that delays qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum and Palladium Carbon Catalyst Market |
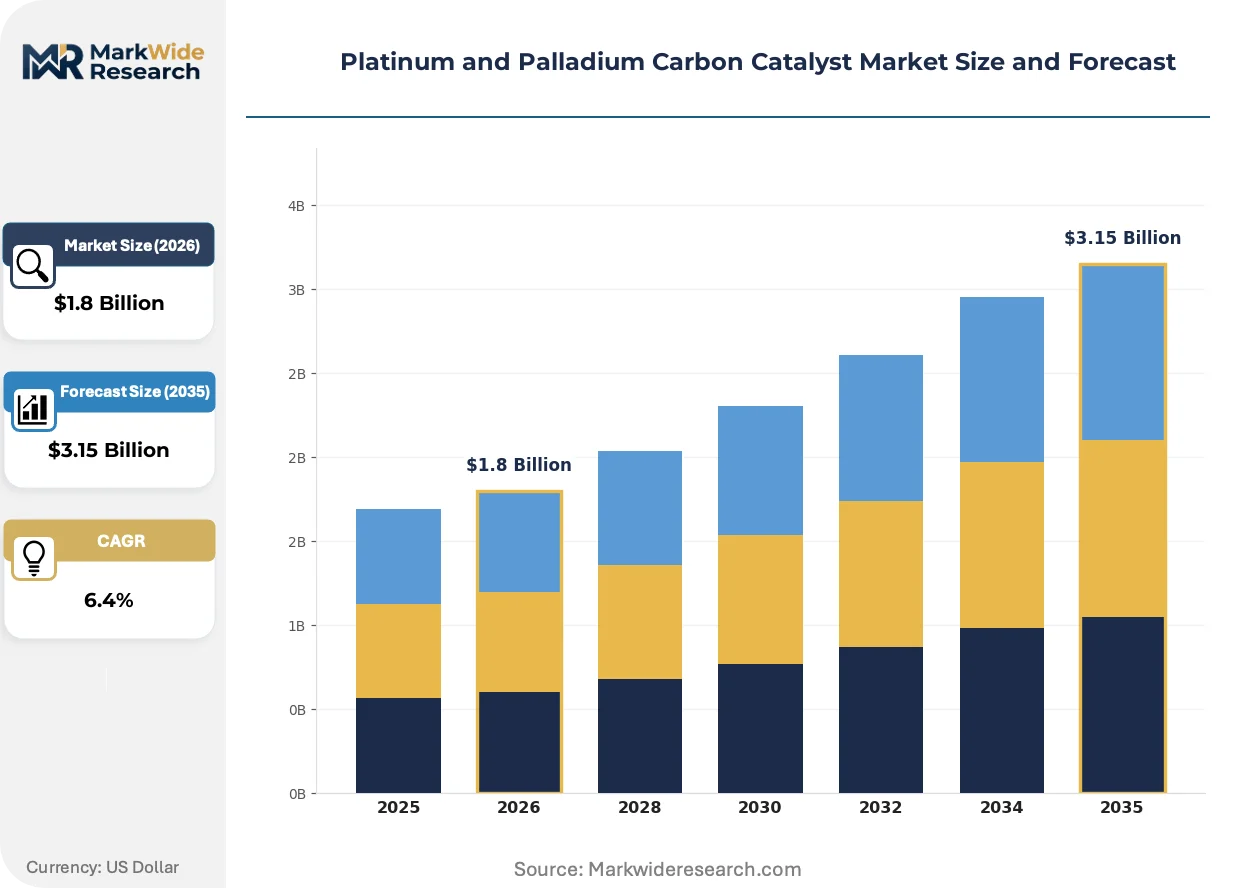
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum Catalyst, Palladium Catalyst, Bimetallic Catalyst, Supported Catalyst Application: Chemical Synthesis, Fuel Cells, Emission Control, Hydrogen Generation End User: Automotive, Electronics, Chemical Industry, Renewable Energy Delivery Mode: Bulk Supply, Customized Orders, Pre-packaged Solutions, Perishable Units |
| Companies Covered | Clariant, Shanghai Petrochemical Catalyst, Johnson Matthey, Heraeus Holding, Umicore, Evonik, Vineeth Chemicals, SABIC, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum and Palladium Carbon Catalyst Market Strategic Shifts
Electrolyzer stack designs are forcing catalyst architecture evolution as engineers optimize for intermittent operation, metal loading reduction, and membrane compatibility simultaneously.
Atomic layer deposition surface modification is modularizing catalyst manufacturing by enabling precise control of metal particle nucleation sites on functionalized carbon substrates. Electrolyzer OEMs in Denmark and Norway are qualifying these architectures for PEM stacks operating under variable renewable input. The approach is compressing traditional wet impregnation methods in premium efficiency tiers where metal cost amortization dominates lifetime economics.
REACH authorization requirements for nickel compounds are redirecting R&D investment toward platinum-rich alternatives in hydrogenation applications where nickel catalysts previously dominated. Specialty chemical manufacturers in the Netherlands and Belgium are reformulating processes ahead of sunset date enforcement. The shift is elevating palladium demand in pharmaceutical intermediate production where regulatory compliance timelines outpace process revalidation cycles.
Long-term catalyst leasing contracts are displacing spot procurement in European hydrogen project finance structures, transferring metal price and performance risk from plant operators to catalyst suppliers. Infrastructure funds in Germany and the Netherlands are mandating these arrangements to secure bankability for electrolyzer investments. The model concentrates credit exposure with Johnson Matthey and BASF while fragmenting buyer decision-making across engineering-procurement-construction consortia.
Platinum and Palladium Carbon Catalyst Market Segmentation
Catalyst procurement patterns diverge sharply across end-use applications, with hydrogen infrastructure developers demanding precision-engineered formulations while automotive buyers prioritize volume-scale palladium loading contracts. Metal efficiency specifications and regulatory compliance timelines create distinct segment economics that reshape supplier positioning strategies.
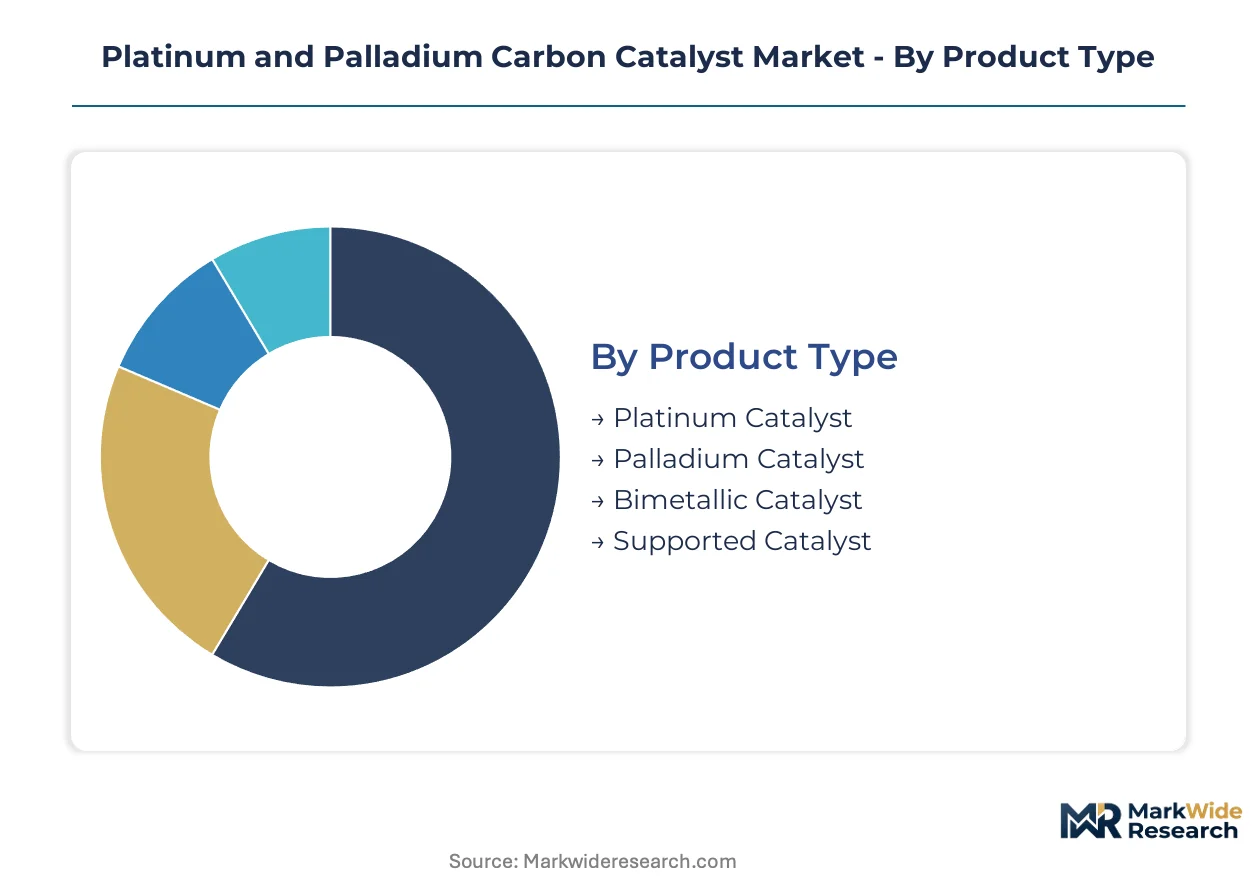
Product Type:
Supply concentration in South African platinum mining and Russian palladium refining forces catalyst manufacturers to hedge metal exposure through product portfolio diversification and closed-loop recovery partnerships.
- Palladium Catalyst:Dominant commercial volume with established pharmaceutical hydrogenation and automotive catalytic converter demand. Fine chemical manufacturers in Germany and Belgium specify palladium-on-carbon for API intermediate production under EMA validation protocols. Metal price volatility from Norilsk refining disruptions compresses margin predictability in long-term supply agreements.
- Platinum Catalyst:Electrochemical applications in proton exchange membrane stacks command premium positioning. Danish and Norwegian electrolyzer OEMs qualify platinum-rich formulations for intermittent renewable power operation. PEM fuel cell deployment timelines in Japanese maritime shipping redirect R&D investment toward membrane compatibility optimization.
- Bimetallic Catalyst:Expanding most quickly as engineers optimize activity-selectivity tradeoffs through alloy particle engineering.
- Supported Catalyst:Activated carbon substrate functionalization enables controlled pore distribution for specialized hydrogenation sequences.
Today's leader: Palladium Catalyst. Tomorrow's challenger: Bimetallic Catalyst.
Application:
Cost tier differentiation separates premium electrochemical grades from commodity hydrogenation catalysts, with electrolyzer stack specifications commanding 3-4x metal loading premiums over petrochemical process applications.
- Hydrogen Generation:Electrolyzer OEMs in Germany's Ruhr cluster specify catalysts with verified durability under variable renewable input. US Treasury guidance on IRA clean hydrogen production credits redirects refinery investment toward electrolyzer-based supply chains. Metal efficiency requirements compress development cycles for atomic layer deposition surface modification techniques.
- Chemical Synthesis:REACH authorization deadlines for nickel compounds elevate platinum-rich alternatives in pharmaceutical intermediate production. Dutch and Belgian specialty chemical manufacturers reformulate processes ahead of sunset date enforcement. Regulatory compliance timelines outpace process revalidation cycles, locking in palladium demand.
- Fuel Cells:Japanese shipping consortia evaluate palladium-rich membrane catalysts for maritime applications beyond stationary power.
- Emission Control:EPA Tier 3 standards sustain palladium loading requirements in North American catalytic converters with consolidated automotive OEM buyer power.
Volume concentrates in Chemical Synthesis. Margin accretion shifts toward Hydrogen Generation.
End User:
Customer type fragmentation separates project-finance-backed hydrogen developers from integrated chemical manufacturers with captive catalyst recycling infrastructure.
- Chemical Industry:Integrated manufacturers in Germany and the Netherlands leverage closed-loop metal recovery to reduce virgin platinum group metal dependence. Johnson Matthey and BASF structure long-term leasing contracts that transfer price risk from plant operators to suppliers. Process validation requirements under EMA guidelines extend catalyst reuse cycle documentation burdens.
- Automotive:Catalytic converter procurement consolidates among OEMs with dual-sourcing strategies hedging South African supply concentration. EPA emission enforcement sustains palladium loading specifications despite powertrain electrification timelines.
- Renewable Energy:Electrolyzer project finance structures mandate performance-guaranteed catalyst supply with bankability requirements.
- Electronics:Precision hydrogenation for semiconductor materials specifies ultra-low contamination catalyst grades.
Contract tenure longest in Chemical Industry. Credit exposure concentrates with Renewable Energy project finance.
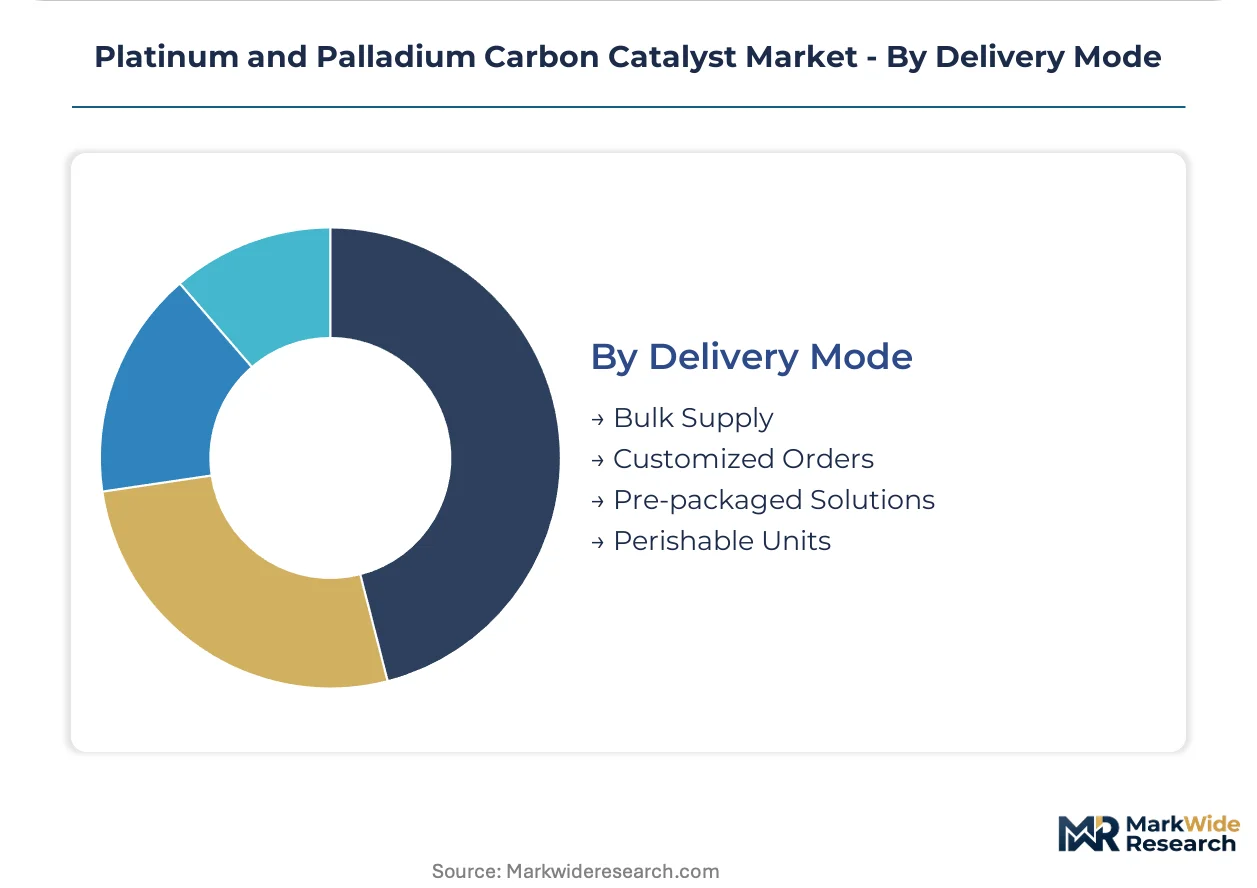
Delivery Mode:
Procurement patterns are shifting from spot market transactions toward structured supply agreements as hydrogen infrastructure scale-up demands inventory security.
- Customized Orders:Electrolyzer stack manufacturers specify particle size distribution and ionomer compatibility coordinated with membrane suppliers. MEA integration complexity creates technical interface risk that delays qualification cycles. Atomic layer deposition surface modification requires batch-specific quality documentation.
- Bulk Supply:Petrochemical hydrogenation processes in German refineries specify standardized palladium loadings with quarterly procurement schedules.
- Pre-packaged Solutions:Pharmaceutical manufacturers under EMA validation protocols demand sealed catalyst cartridges with chain-of-custody documentation.
- Perishable Units:Air-sensitive formulations for specialized fine chemical synthesis require controlled atmosphere packaging with limited shelf life.
Transaction frequency highest in Bulk Supply. Technical service intensity peaks in Customized Orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemist talent pools concentrate in German industrial clusters and Japanese materials science hubs, anchoring catalyst innovation capacity in these geographies.
Germany
Ruhr industrial cluster electrolyzer deployments specify catalysts with verified durability under intermittent renewable power. EU Green Deal emission benchmarks tighten carbon intensity requirements for chemical manufacturers. BASF and Johnson Matthey structure long-term leasing contracts with hydrogen infrastructure developers in North Rhine-Westphalia.
United States
Refinery and chemical plant investment redirects toward electrolyzer-based supply chains under IRA clean hydrogen production credits. EPA Tier 3 standards sustain palladium loading requirements in catalytic converters. Texas Gulf Coast hydrogen hub developers specify performance-guaranteed catalyst supply with bankability requirements.
Japan
Shipping consortia evaluate palladium-rich membrane catalysts for maritime fuel cell applications beyond stationary power. METI hydrogen roadmap targets commercialize ammonia cracking for hydrogen transport. Osaka-Kobe industrial corridor electrolyzer OEMs qualify bimetallic formulations for PEM stacks.
China
Dual carbon goals redirect refinery hydrogen production toward lower-carbon pathways. MEE enforcement tightens emission benchmarks for industrial catalyst users. Yangtze River Delta chemical manufacturers scale green hydrogen pilot projects with domestic catalyst qualification requirements.
Belgium
Closed-loop metal recovery infrastructure offers feedstock security independent of primary mining supply chains. REACH authorization requirements for nickel compounds elevate platinum-rich alternatives in pharmaceutical synthesis. Umicore's Hoboken facility processes kiloton-scale precious metal streams from spent catalyst recycling.
Platinum and Palladium Carbon Catalyst Market Competitive Environment
The competitive structure tilts toward integrated precious metals specialists with captive refining capacity and backward integration into platinum group metal sourcing. Market concentration reflects high barriers to entry from metal price volatility, REACH registration burdens, and electrochemist talent scarcity. Two archetypes dominate: diversified chemical conglomerates with catalyst divisions and focused precious metals technology specialists. Competitive moves center on closed-loop recycling partnerships and long-term leasing contract structures that transfer metal price risk to suppliers.
Among European-integrated specialists, Johnson Matthey and Umicore occupy positions anchored in precious metals refining heritage, while BASF represents the diversified chemical conglomerate archetype with in-house platinum group metal sourcing. These three exemplify the strategic divide between metal recovery-focused positioning and backward-integrated supply security.
| Leading Market Players |
|---|
| Clariant |
| Shanghai Petrochemical Catalyst |
| Johnson Matthey |
| Heraeus Holding |
| Umicore |
| Evonik |
| Vineeth Chemicals |
| SABIC |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Johnson Matthey's platinum group metal price index cascades through catalyst manufacturing into three distinct pricing tiers: electrochemical grades for PEM electrolyzers, pharmaceutical validation-tier formulations, and bulk refinery hydrogenation specifications. Metal loading precision and carbon support functionalization separate premium contracts from commodity spot purchases, with EU Green Deal compliance timelines compressing negotiation windows for long-term supply agreements.
Pricing Analysis
Bundled metal leasing contracts are displacing unbundled spot procurement as hydrogen infrastructure developers transfer price risk to suppliers. Three-tier pricing structure across premium electrochemical, standard pharmaceutical, and economy petrochemical levels reflects certification grade differentiation and volume scale. Cost compression in standard tiers is intensifying because REACH registration burdens extend time-to-market for novel formulations. Petrochemical refiners exhibit highest price sensitivity due to consolidated buyer power, while electrolyzer OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from German chemical manufacturers and Japanese shipping consortia mandate multi-supplier qualification for platinum and palladium feedstock. Geographic supply concentration centers on South African platinum mining, Russian palladium refining, and Belgian closed-loop recovery infrastructure. Raw material dependencies rest on Norilsk refining output, Hoboken recycling capacity, and Ruhr industrial cluster demand aggregation. Single-source vulnerability from South African mining concentration exposes catalyst producers to geopolitical disruption. Distribution runs through long-term leasing structures with engineering-procurement-construction consortia rather than spot market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hydrogen generation applications displace commodity chemical synthesis demand, with bimetallic catalyst architectures commanding premium positioning through verified durability under intermittent renewable power input.
For Market Incumbents: Lock in backward integration into platinum group metal sourcing through closed-loop recycling partnerships with Belgian and German facilities. Secure electrochemist talent pools in Ruhr and Osaka-Kobe industrial corridors before compensation premiums escalate further. Defend against homogeneous catalysis substitution in fine chemical synthesis by accelerating REACH-compliant nickel-alternative formulations ahead of sunset date enforcement. For New Entrants and Emerging Players: IRA clean hydrogen production credits in the United States open a window for electrolyzer catalyst qualification with Texas Gulf Coast hydrogen hub developers. Target ammonia cracking applications for maritime fuel cells where Japanese shipping consortia lack established supplier relationships. Pursue atomic layer deposition surface modification capabilities as a technical differentiation wedge against incumbent wet impregnation methods. For Investors and Strategic Acquirers: Asymmetric upside sits with closed-loop metal recovery specialists possessing kiloton-scale processing infrastructure independent of primary mining supply chains. Five-to-ten year viability hinges on electrolyzer deployment timelines outpacing powertrain electrification erosion of automotive palladium demand. Watch for Treasury guidance refinement on IRA clean hydrogen tax incentives as the inflection signal redirecting refinery capital expenditure toward electrolyzer-based supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Catalyst Leasing Contracts | Transfers metal price risk from plant operators to suppliers under EU Green Deal project finance structures. |
| Closed-loop Metal Recovery Partnerships | Secures feedstock independence from South African mining concentration via Belgian recycling infrastructure. |
| Atomic Layer Deposition Qualification | Enables precision particle nucleation for Danish and Norwegian electrolyzer OEM durability specifications. |
| Bimetallic Formulation R&D Investment | Optimizes activity-selectivity tradeoffs for proton exchange membrane fuel cell membrane compatibility. |
| Electrochemist Talent Acquisition | Addresses surface science and membrane electrode assembly integration skill scarcity in German clusters. |
Study Parameters
Multiple input streams — primary interviews with catalyst procurement managers, electrolyzer OEM technical directors, and precious metals refining executives; secondary validation through ECHA REACH registration databases, SEC filings from integrated chemical conglomerates, and EU hydrogen project development registries — were reconciled through bottom-up and top-down triangulation. Plant managers at Ruhr industrial cluster facilities, pharmaceutical process validation leads under EMA guidelines, and closed-loop recycling operators at Belgian precious metals facilities provided demand-side perspective. Customs trade data, national hydrogen roadmap publications, and electrolyzer deployment announcements furnished supply-side benchmarks.
Historical capacity expansion patterns were cross-referenced against panel input from membrane electrode assembly integrators and carbon support manufacturers across the projection horizon. Segmentation dimensions modeled include metal loading tier, application end-use, carbon support functionalization grade, and regional regulatory cluster. CAGRs were derived through iterative reconciliation of metal efficiency improvement trajectories, electrolyzer deployment schedules, and REACH compliance timeline impacts. Forecast inputs incorporated intermittent renewable power duty cycles for durability verification and palladium-for-platinum substitution elasticity in pharmaceutical hydrogenation.
Revisions become necessary when South African mining supply disruptions, Treasury IRA guidance deviations, or ECHA nickel compound authorization enforcement timelines materialize differently than assumed. Deviation in electrolyzer bankability requirements or membrane manufacturer qualification protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Steam Methane Reforming Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Refinery Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
North America Zeolite Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Precious Metal Catalysts Market