
 Precious Metal Catalysts Market | 2026-2036
Precious Metal Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Precious Metal Catalysts Market Intelligence
The shift toward single-atom catalysis is narrowing the performance gap between homogeneous and heterogeneous catalysts, allowing for maximum atom utilization and reducing required metal loading. Johnson Matthey leverages its extensive R&D in automotive applications to pioneer formulations for emission control. BASF dominates the chemical synthesis segment with its broad portfolio of heterogeneous catalysts. Heraeus Precious Metals specializes in high-purity catalysts for pharmaceutical and fine chemical production.
Precious metal catalysts are substances containing platinum, palladium, rhodium, or other noble metals dispersed on a high-surface-area support like alumina or carbon. They function by accelerating chemical reactions without being consumed, enabling processes from automotive emission control to pharmaceutical synthesis. Platinum and rhodium products command the highest value, particularly for their use in three-way catalytic converters. While automotive emission control remains the largest application, demand for catalysts in fuel cells represents the fastest-growing opportunity.
Regulatory mandates are a primary market influence, with standards from the US EPA, Europe's ECHA under REACH, and China's MEE setting strict limits on industrial and vehicular emissions. These regulations directly compel the use of advanced catalysts to achieve compliance, particularly for nitrogen oxides and particulate matter. Consequently, catalyst manufacturers must navigate a complex web of regional testing and certification protocols to secure market access. The key decision for suppliers now revolves around balancing investment in mature combustion engine applications against development for emerging hydrogen technologies.
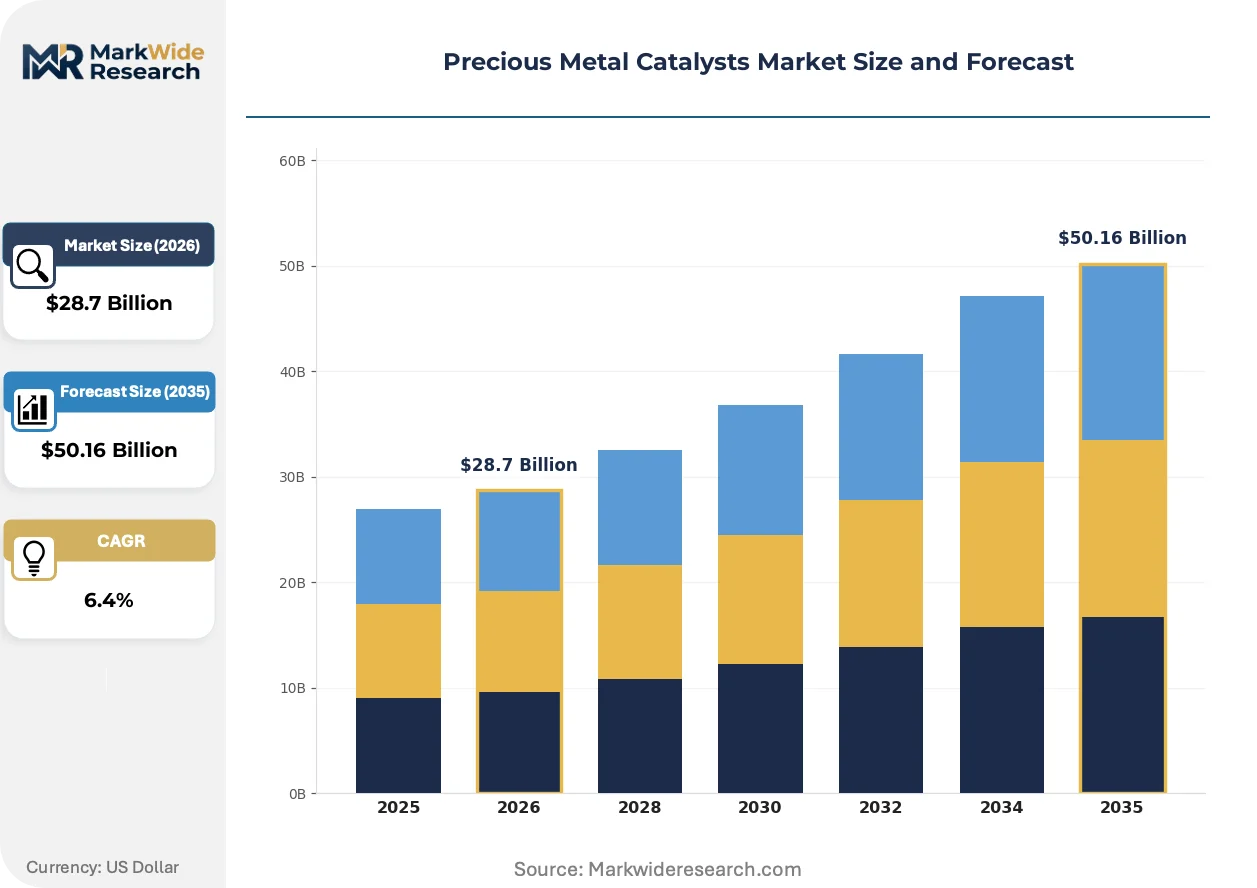
Market Dynamics
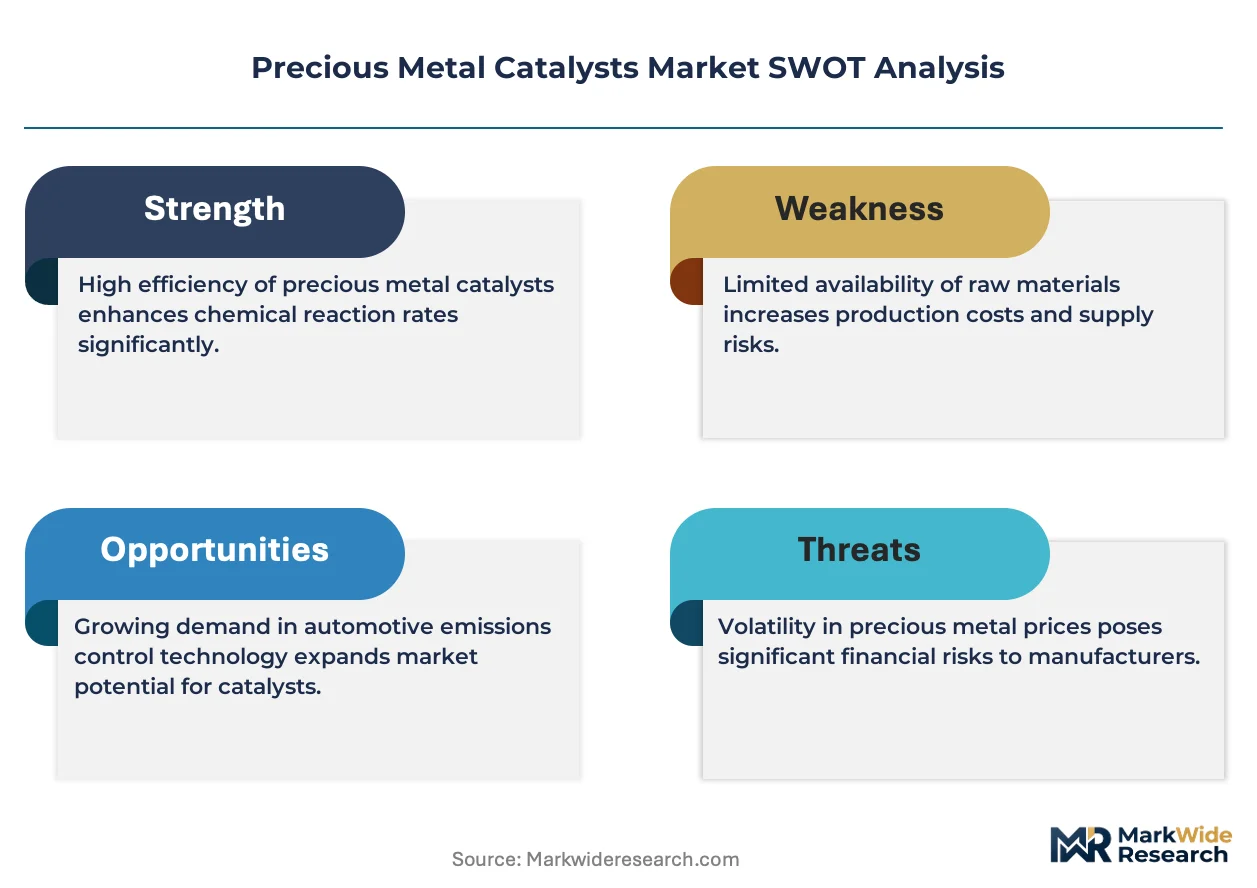
The central tension in the precious metal catalysts market is the strategic imperative to balance investment. Manufacturers must support mature, high-volume automotive emission control applications while simultaneously funding R&D for nascent, high-growth hydrogen and fuel cell technologies.
Growth Catalysts
- Stringent Emission Standards:China's MEE regulations and dual carbon goals mandate higher-performance catalysts for vehicles and industrial processes, concentrating demand in its manufacturing sector.
- Single-Atom Catalysis:This technology reduces precious metal loading by maximizing atom utilization, expanding applications in fine chemical synthesis.
- Fuel Cell Development:The global push for hydrogen-powered heavy-duty transport creates a new demand vector for platinum-based catalysts.
Market Restraints
- Input Cost Volatility:Extreme price fluctuations and the concentrated supply of rhodium and palladium from a few countries create significant cost uncertainty for manufacturers.
- Substitution Threat:In some chemical processes, lower-cost catalysts based on transition metals like nickel can replace precious metal formulations.
- Catalyst Deactivation:Performance degradation from poisoning by fuel impurities necessitates costly regeneration or premature replacement, impacting operational economics.
Strategic Opportunities
- Green Hydrogen Production:Developing catalysts for water electrolysis aligns with global decarbonization initiatives, opening a major new market for platinum group metals.
- Pharmaceuticals in India:Supplying high-purity catalysts for active pharmaceutical ingredient (API) manufacturing to India's expanding pharmaceutical sector presents a key opportunity.
- Circular Economy Models:Establishing robust metal recovery services creates a circular supply chain, mitigating price volatility and sourcing risks for key metals.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers must navigate disparate regional testing and certification protocols, such as those from the US EPA and Europe's ECHA, lengthening time-to-market.
- High Capital Intensity:Scaling up production facilities for novel catalyst formulations, particularly for emerging fuel cell and hydrogen applications, requires significant capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precious Metal Catalysts Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum, Palladium, Rhodium, Silver, Gold Technology: Chemisorption, Photocatalysis, Electrocatalysis, Heterogeneous, Homogeneous Application: Automotive Emission Control, Chemical Synthesis, Fuel Cells, Petroleum Refining, Environmental Remediation End User: Catalyst Manufacturers, Chemical Producers, Energy Providers, Automotive OEMs, Environmental Agencies |
| Companies Covered | Heraeus Precious Metals, Evonik Industries, Johnson Matthey, Alfa Aesar, Honeywell International, BASF, Clariant, American Elements, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precious Metal Catalysts Market Strategic Shifts & Innovations
The market's evolution is defined by the pursuit of atomic-level efficiency and greater material circularity. This drive responds directly to raw material scarcity and increasingly stringent environmental performance mandates from regulators across the globe.
Computational modeling and machine learning platforms allow for the rapid screening of potential catalyst structures. Chemical manufacturers are adopting these tools to accelerate research and development cycles. This approach is digitizing the traditionally trial-and-error process of catalyst discovery, reducing development costs and overall project timelines.
Europe's Green Deal and its associated policies, including stricter automotive emission standards, compel manufacturers to use more sophisticated catalytic converters. This directly increases the loading or complexity of platinum, palladium, and rhodium in exhaust systems. The automotive catalyst segment is most affected, investing heavily in next-generation formulations.
A shift toward closed-loop supply agreements is gaining traction among large-scale catalyst users in the chemical industry. Instead of simple purchasing, producers are entering long-term contracts that include catalyst supply, performance monitoring, and end-of-life metal recovery. This trend is most prominent in Germany's chemical sector.
Precious Metal Catalysts Market Segmentation
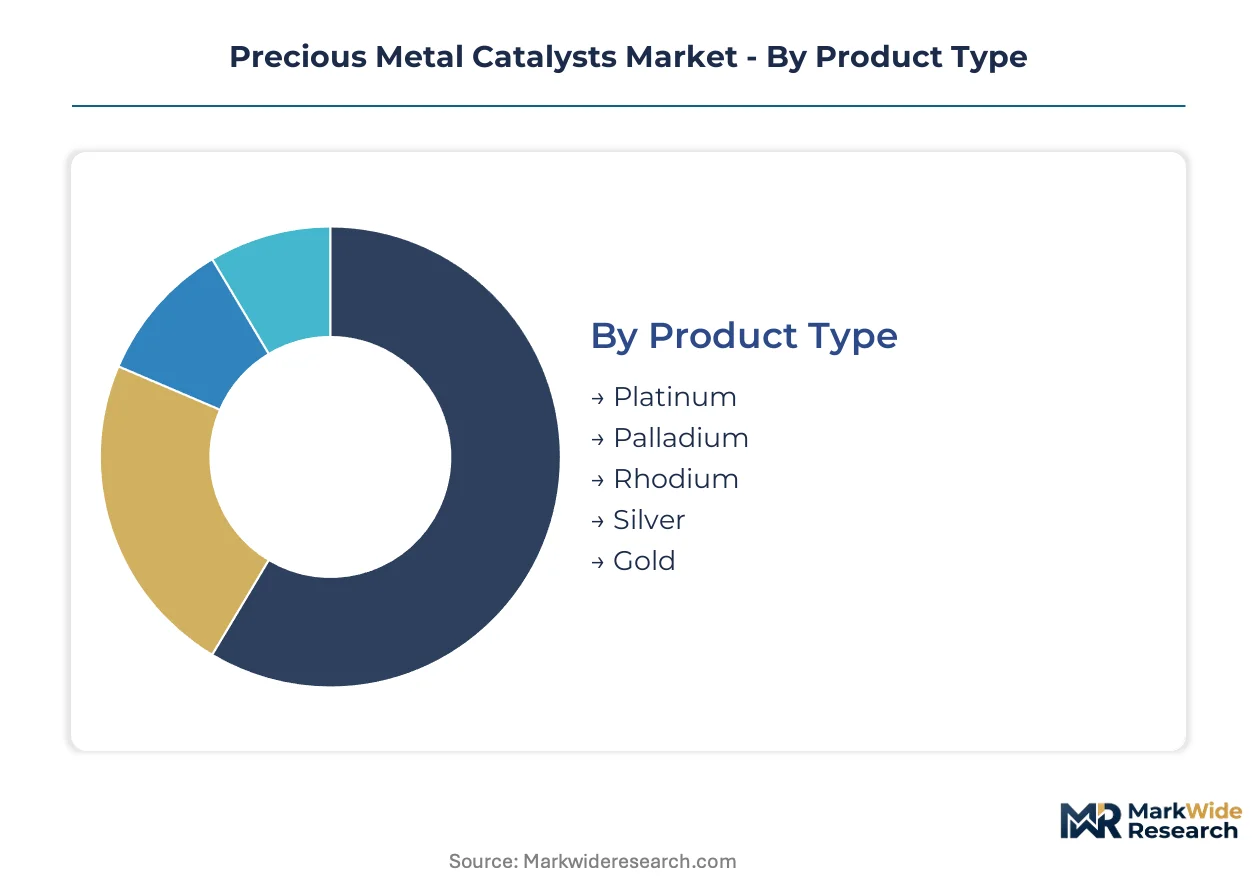
The precious metal catalysts market exhibits diverse segmentation driven by the specific noble metals used, the underlying catalytic technologies, varied application demands, and the distinct requirements of end-user industries. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth opportunities.
Product Type:
The market for precious metal catalysts differentiates significantly based on the specific noble metal employed.
- Platinum:This high-value metal is essential for automotive emission control, particularly in three-way catalytic converters for gasoline engines. Demand for platinum in fuel cells represents the fastest-growing opportunity, driven by hydrogen mobility initiatives.
- Rhodium:Commanding the highest value among precious metals, rhodium is critical for nitrogen oxide reduction in three-way catalytic converters. Its concentrated supply from a few countries creates significant cost uncertainty for manufacturers.
- Palladium:A key component in automotive catalysts, palladium also finds use in various chemical synthesis processes and hydrogen purification applications.
- Silver:Utilized in oxidation reactions for ethylene oxide production and serves as a catalyst in specific fine chemical manufacturing processes.
- Gold:Emerging as a catalyst for low-temperature oxidation reactions and increasingly adopted in pharmaceutical synthesis due to its unique catalytic properties.
Platinum holds significant installed capacity in automotive applications. Gold is rotating up the share rankings with its emerging applications.
Technology:
Different catalytic mechanisms define the technology landscape within the precious metal catalysts market.
- Heterogeneous:These catalysts are in a different phase from the reactants, typically solid materials with high surface areas. Heterogeneous catalysts dominate chemical synthesis and automotive emission control due to their ease of separation and regeneration.
- Homogeneous:Catalysts existing in the same phase as the reactants, often as dissolved metal complexes. Homogeneous catalysts offer high selectivity for complex organic reactions, particularly important in pharmaceutical synthesis.
- Chemisorption:This fundamental process involves chemical bonding between reactants and the catalyst surface, forming the basis for many industrial catalytic processes.
- Photocatalysis:This technology utilizes light energy to drive chemical reactions, finding applications in environmental remediation and sustainable hydrogen production methods.
- Electrocatalysis:Crucial for accelerating electrochemical reactions at electrode surfaces, electrocatalysis is vital for fuel cells and green hydrogen production via water electrolysis.
Heterogeneous catalysis maintains its broad industrial footprint. Electrocatalysis is expanding most quickly in energy applications.
Application:
The end-use industries dictate specific catalyst performance requirements across the market.
- Automotive Emission Control:This remains the largest application, driven by stringent emission standards from regulatory bodies like the US EPA and China's MEE. It requires platinum, palladium, and rhodium for three-way catalytic converters.
- Fuel Cells:This segment presents a significant growth opportunity, propelled by the global push for hydrogen-powered heavy-duty transport. Fuel cells primarily utilize platinum-based catalysts for efficient energy conversion.
- Chemical Synthesis:A broad segment encompassing the production of fine chemicals, polymers, and bulk chemicals, with companies like BASF providing extensive portfolios of heterogeneous catalysts.
- Petroleum Refining:Precious metal catalysts are essential for processes such as naphtha reforming, which produces high-octane gasoline and valuable aromatic compounds.
- Environmental Remediation:This application includes catalysts for treating industrial wastewater and air pollutants, complementing automotive exhaust treatment.
Automotive emission control represents the largest volume. Fuel cells are gaining share fastest in the energy transition.
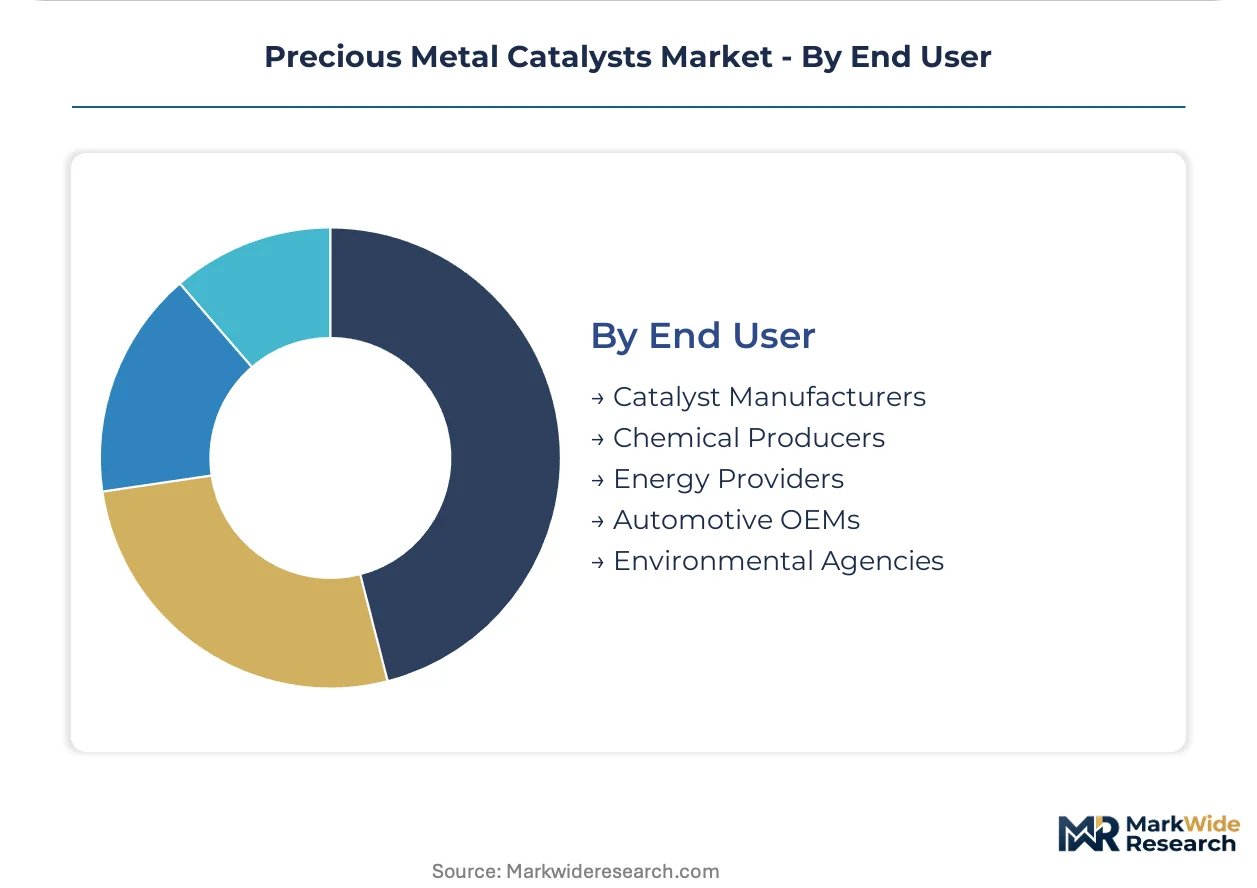
End User:
The primary customer types for precious metal catalysts vary across industrial sectors.
- Chemical Producers:These entities are major consumers of catalysts for synthesizing a wide array of products, from pharmaceuticals to bulk chemicals. They often engage in closed-loop supply agreements for metal recovery.
- Automotive OEMs:Original Equipment Manufacturers integrate catalytic converters into vehicle exhaust systems to meet strict emission standards. Their demand is concentrated in manufacturing hubs like China and Germany.
- Catalyst Manufacturers:These companies specialize in producing the catalysts themselves, often sourcing precious metals and then supplying finished products to other end-users.
- Energy Providers:Utilize catalysts for fuel processing, hydrogen production, and the development of advanced fuel cell technologies.
- Environmental Agencies:While not direct purchasers, these agencies, such as Europe's ECHA, set regulatory mandates that compel the use of advanced catalysts across various industries to achieve compliance.
Chemical producers drive consistent demand for synthesis catalysts. Energy providers are increasingly influencing new catalyst development for decarbonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade flows for precious metal catalysts are significantly shaped by major manufacturing hubs in China and Germany. These regions supply critical catalytic materials to diverse international markets, influencing global demand patterns. Regional regulatory frameworks and industrial concentrations are key determinants of market dynamics.
China
China's automotive and chemical sectors generate substantial demand for precious metal catalysts, especially for emission control. The MEE regulations and dual carbon goals compel higher-performance catalytic solutions. Manufacturing clusters in the Yangtze River Delta region are pivotal for catalyst consumption.
Germany
Germany's automotive and chemical sectors consume significant precious metal catalysts for emission reduction and fine chemical synthesis. The EU Green Deal mandates complex catalytic systems for vehicles and industrial applications. Chemical manufacturers in the Rhine-Ruhr region pioneer circular economy models for catalyst management.
United States
United States demand for precious metal catalysts stems from its automotive market, petroleum refining, and chemical synthesis operations. The US EPA regulations compel advanced catalysts to meet air quality standards. Refining and petrochemical clusters along the Gulf Coast are major consumers.
India
India's expanding pharmaceutical sector drives a need for high-purity precious metal catalysts for API manufacturing. The national pharmaceutical regulator influences quality and performance requirements. Pharmaceutical clusters in Maharashtra and Gujarat are key centers for this catalyst demand.
Japan
Japan's automotive industry and chemical sector create steady demand for catalysts, including for emission control. METI supports R&D initiatives for sustainable catalytic technologies. Automotive manufacturing centers in the Kanto region focus on advanced catalytic converter designs.
Precious Metal Catalysts Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, combining large diversified chemical producers with specialized precious metal refiners and focused automotive catalyst innovators. These players often differentiate through extensive research and development in novel catalyst formulations. Key competitive moves involve strategic partnerships for closed-loop supply agreements and significant investments in emerging fuel cell technologies.
Specialists in catalyst manufacturing include BASF, which anchors the chemical synthesis segment with its broad portfolio of heterogeneous catalysts, leveraging its global footprint and extensive R&D capabilities. Johnson Matthey, a UK-based company, represents significant investment in automotive applications, pioneering advanced emission control formulations and extending its research into next-generation solutions. Heraeus Precious Metals, a German entity, exemplifies expertise in high-purity catalysts for pharmaceutical and fine chemical production, serving critical niche markets worldwide with specialized offerings and a focus on material purity. These entities collectively shape the competitive dynamics through their distinct areas of focus.
| Leading Market Players |
|---|
| Heraeus Precious Metals |
| Evonik Industries |
| Johnson Matthey |
| Alfa Aesar |
| Honeywell International |
| BASF |
| Clariant |
| American Elements |
| Umicore |
Cost & Logistics Intelligence
Existing capacity utilization for automotive emission control catalysts influences supplier behavior and pricing strategies. Significant investment in hydrogen technologies creates new capacity requirements, shifting market dynamics.
Pricing Analysis
Next-generation catalyst formulations, particularly for fuel cells, command a premium over traditional combustion engine catalysts. The market primarily operates on contract-based long-term offtake agreements, often incorporating value-based performance metrics. Price differentiation stems from formulation complexity and certification level for specific applications. Pricing softness reflects input cost volatility, particularly for rhodium and palladium, as manufacturers pass on some fluctuations. Automotive OEMs exhibit moderate price sensitivity due to high volumes, while pharmaceutical manufacturers prioritize high purity, showing lower price sensitivity.
Supply Chain Analysis
Upstream feedstock supply for precious metal catalysts relies heavily on platinum, palladium, and rhodium. Catalyst manufacturing concentrates in China and Germany, influencing global trade flows. The market faces a structural risk from commodity price volatility due to the concentrated supply of key noble metals. Downstream distribution primarily involves direct sales to automotive OEMs and contract-based closed-loop agreements with chemical producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a buyer-power shift driven by the consolidation of procurement through closed-loop supply agreements among large chemical producers. These long-term contracts influence supplier investment and strategic focus.
For Market Incumbents: Entrench core positions by leveraging extensive R&D in both mature automotive emission control and emerging hydrogen applications. Establish robust metal recovery services to mitigate input cost volatility and secure supply, offering a crucial lever against substitution threats. Deepen partnerships with key automotive OEMs and chemical producers through long-term closed-loop supply agreements. Invest in advanced computational modeling to accelerate new catalyst discovery.
For New Entrants and Emerging Players: Pursue niche opportunities in green hydrogen production, specifically developing electrocatalysts for water electrolysis, which represents a significant white space. Target India's expanding pharmaceutical sector with high-purity catalysts for API manufacturing, a penetrable segment due to specific quality requirements. A go-to-market angle could involve offering advanced computational catalyst design services to accelerate client product development. Focus on sustainable, low-PGM formulations to address raw material scarcity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catalyst manufacturers offering integrated closed-loop services and high-purity products for pharmaceutical synthesis. Long-term viability hinges on the global decarbonization agenda and the transition to hydrogen technologies, ensuring sustained demand for advanced catalysts. Target acquisition archetypes include specialized firms in electrocatalysis for green hydrogen or single-atom catalysis for fine chemicals. The signal to watch is the acceleration of global regulatory mandates for hydrogen-powered transport and industrial processes.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Closed-Loop Metal Recovery Services | Mitigates input cost volatility for rhodium and palladium, enhancing circular economy models for chemical producers. |
| Invest in Electrocatalysis R&D | Accelerates development of platinum-based catalysts crucial for fuel cells and green hydrogen production initiatives. |
| Develop Single-Atom Catalyst Formulations | Maximizes atom utilization, reducing precious metal loading for fine chemical synthesis and automotive applications. |
| Strengthen Regulatory Compliance Teams | Ensures market access by navigating complex testing protocols from the US EPA, ECHA, and China's MEE. |
| Form Strategic Partnerships for Hydrogen Infrastructure | Secures early market position for platinum-based catalysts in the rapidly growing heavy-duty transport sector. |
Research Approach
Cross-validation between primary interviews and extensive secondary market reports anchors the qualitative findings. This involved discussions with automotive OEMs procurement managers, chemical R&D directors, and catalyst manufacturers' technical leads. Secondary validation utilized regulatory body publications from the US EPA and ECHA, alongside industry association reports on PGM markets. A combination of bottom-up segment data and top-down overall market triangulation informed the analysis.
Quantitative models were calibrated against historical market performance and validated through expert insights across the analysis window. Segmentation dimensions modeled included specific noble metals, catalytic technologies, application areas, end-user industries, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs included precious group metal price forecasts and anticipated emission limits.
Sensitivities concentrate around precious group metal price volatility and evolving regulatory landscapes. Forecasts reflect assumptions regarding technological advancements in non-PGM catalysts and the pace of hydrogen economy development. Cross-checking against PGM market reports and global automotive production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Inorganic Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Environmental Catalysts Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Europe PGM Catalyst Market