
 Inorganic Chemicals Market | 2026-2036
Inorganic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Chemicals Market Analysis
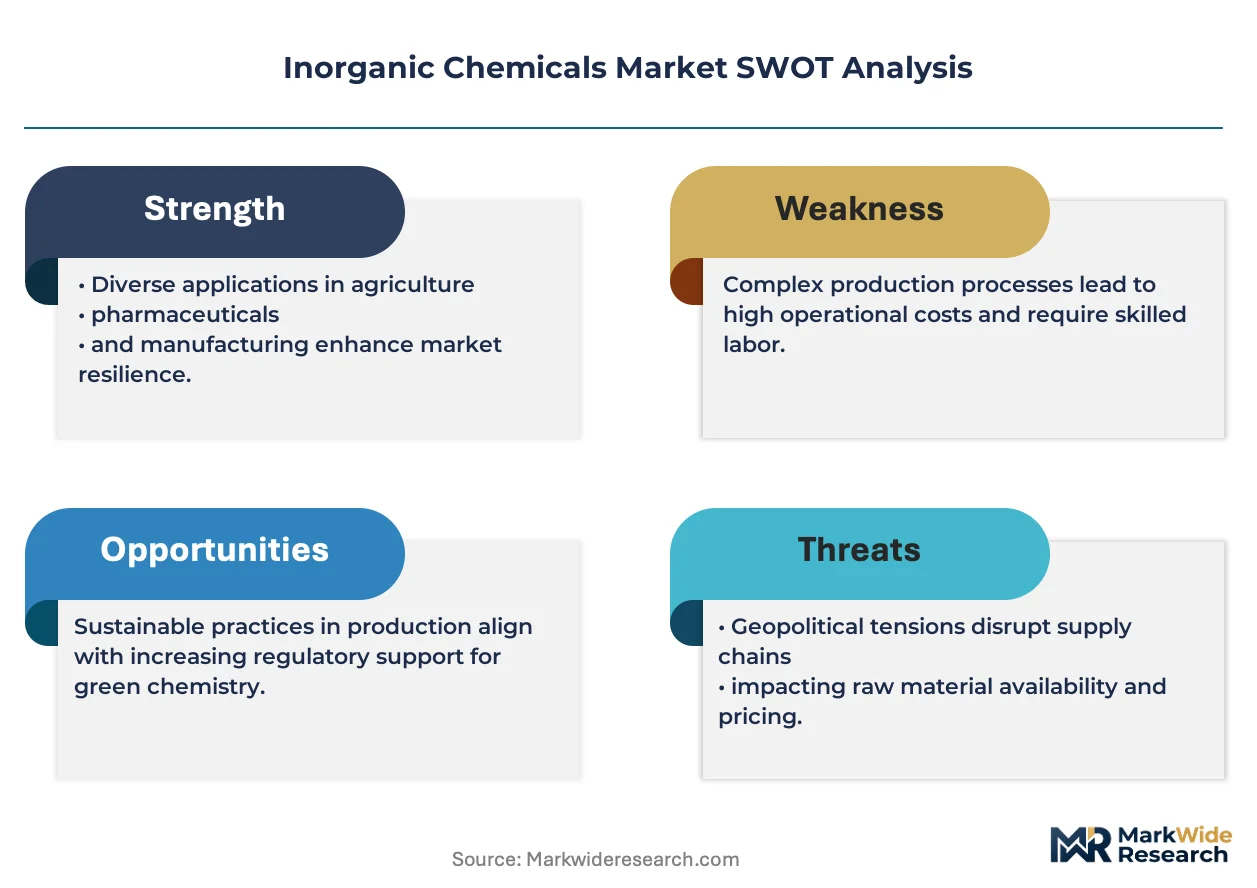
Specialty electronics manufacturers are rotating toward high-purity inorganic precursors as semiconductor fabrication scales. BASF SE leverages integrated oxide production networks across Germany and Belgium to serve this shift. SABIC anchors regional supply through its Saudi-based sulfur derivative complexes. Evonik Industries AG differentiates via reagent-grade phosphates for pharmaceutical synthesis.
Inorganic chemicals encompass non-carbon-based compounds including oxides, sulfates, carbonates, and phosphates, typically manufactured through thermal decomposition, acid-base neutralization, or electrochemical processes yielding purities from technical grade to semiconductor specification. These materials serve as feedstock for catalysis, pH adjustment, mineral supplementation, and electronic substrate preparation. Oxides dominate volume flows into construction and ceramics, while phosphates capture expanding margin pools in lithium-ion battery electrolyte additives. Electronics-grade sulfates represent the fastest-growing application tier as wafer fabrication demands sub-ppb contamination thresholds.
EPA effluent guidelines and REACH substance restrictions constrain mercury-cell chlor-alkali output and cadmium-bearing pigment formulations, redirecting capital toward membrane electrolysis and rare-earth substitution. China's MEE enforces stricter SO₂ and NOₓ caps on sulfuric acid facilities, compressing marginal smelter-acid capacity. India's BIS certification for technical-grade sulfates in water treatment creates non-tariff barriers for unqualified importers. Stakeholders must monitor regulatory divergence between EU F-Gas phase-downs and US IRA clean chemistry incentives to align regional manufacturing footprints with compliance-bound demand.
Market Dynamics
Membrane electrolysis technology is displacing mercury-cell chlor-alkali capacity across integrated chemical complexes, forcing simultaneous retooling of sulfuric acid and sulfate derivative lines to meet semiconductor-grade purity thresholds.
Growth Catalysts
- EPA effluent standard tightening:US water treatment utilities are accelerating sulfate and phosphate procurement to meet revised discharge limits, expanding specialty chemical offtake.
- Electronics-grade purity demand:Wafer fabrication facilities now require sub-ppb contamination thresholds for sulfuric acid derivatives, pulling capacity upgrades across chlor-alkali networks.
- China's integrated complex expansion:Concentrated sulfuric acid and chlor-alkali capacity in Jiangsu and Shandong provinces is capturing regional electronics and construction demand.
Market Restraints
- Sulfur feedstock volatility:Smelter-acid supply fluctuations from copper and zinc refining operations create input cost instability for sulfate manufacturers.
- REACH substance restrictions:Cadmium-bearing pigment formulations face phase-out timelines, compressing established product lines without immediate rare-earth substitute scale.
- Mercury-cell legacy liabilities:Remediation obligations from decommissioned chlor-alkali plants constrain balance-sheet capacity for technology transition investments.
Strategic Opportunities
- India BIS certification gaps:Unqualified importers of technical-grade sulfates face non-tariff barriers, creating captive supply opportunities for domestic certifiers.
- Lithium-ion electrolyte additives:Phosphate-derived flame retardants and conductive salts are capturing margin expansion in battery chemical supply chains.
- EU F-Gas phase-down alignment:Fluorinated gas reduction mandates are redirecting process cooling investments toward ammonia and sulfur hexafluoride alternatives.
Industry Challenges
- Semiconductor-grade certification timelines:Multi-year qualification protocols for wafer-fabrication chemical supply are extending customer conversion cycles.
- Electrochemical process reconfiguration:Membrane cell retrofits require simultaneous utility and materials-handling system overhauls, complicating brownfield execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Chemicals Market |
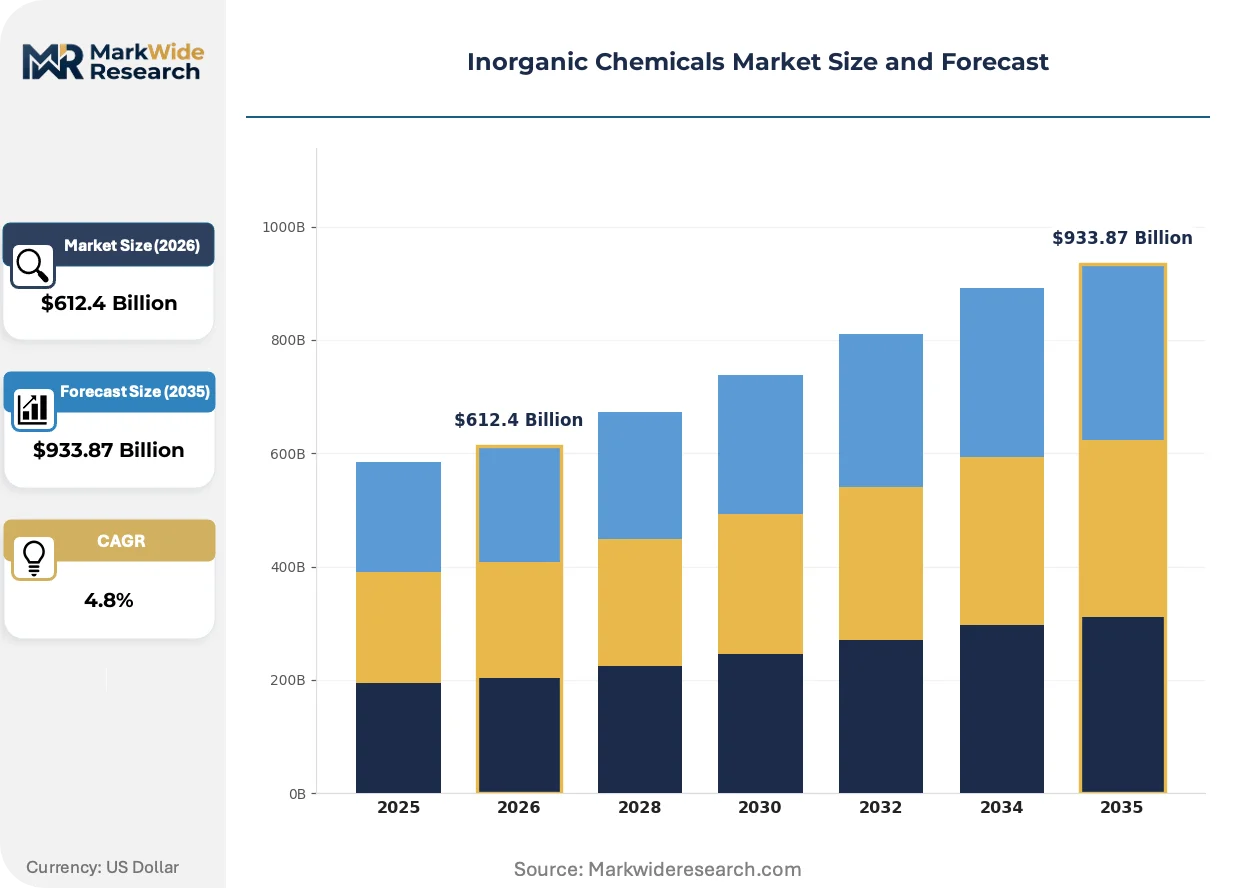
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $933.87 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxides, Sulfates, Carbonates, Phosphates Application: Agriculture, Construction, Pharmaceuticals, Electronics End Use Industry: Mining, Water Treatment, Food Processing, Textile Grade: Industrial, Reagent, Food Grade, Technical |
| Companies Covered | BASF SE, SABIC, Solvay SA, LANXESS AG, Akzo Nobel N.V., Evonik Industries AG, INEOS Group Limited, Tata Chemicals Limited, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Chemicals Market Emerging Trajectories
Process intensification and digital quality control systems are compressing batch-to-batch variation in high-purity production, while regulatory phase-downs accelerate chemistry substitutions across legacy applications.
Membrane electrolysis technology is fragmenting the chlor-alkali installed base as mercury-cell decommissioning accelerates. Semiconductor fabs and specialty pharmaceutical manufacturers are adopting membrane-derived caustic soda and chlorine at expanded rates. This technology is fragmenting regional supply pools into membrane-capable and legacy-dependent clusters, with purity-tier pricing widening between technical and electronics grades.
REACH substance restrictions and EPA effluent guidelines are synchronizing mercury and cadmium phase-outs across Atlantic supply chains. Industrial pigment and battery chemical manufacturers face reformulation mandates with compressed substitution timelines. Electronics-grade sulfate producers in Germany and Belgium are capturing qualification advantages from early membrane conversion investments.
Direct mill-to-fab chemical supply contracts are displacing distributor-mediated procurement in semiconductor clusters. Specialty gas and chemical handlers are consolidating logistics functions previously fragmented across multiple intermediaries. This channel compression is most visible in Taiwan and South Korea, where integrated chemical suppliers are capturing specification-setting roles with foundry customers.
Inorganic Chemicals Market Segmentation
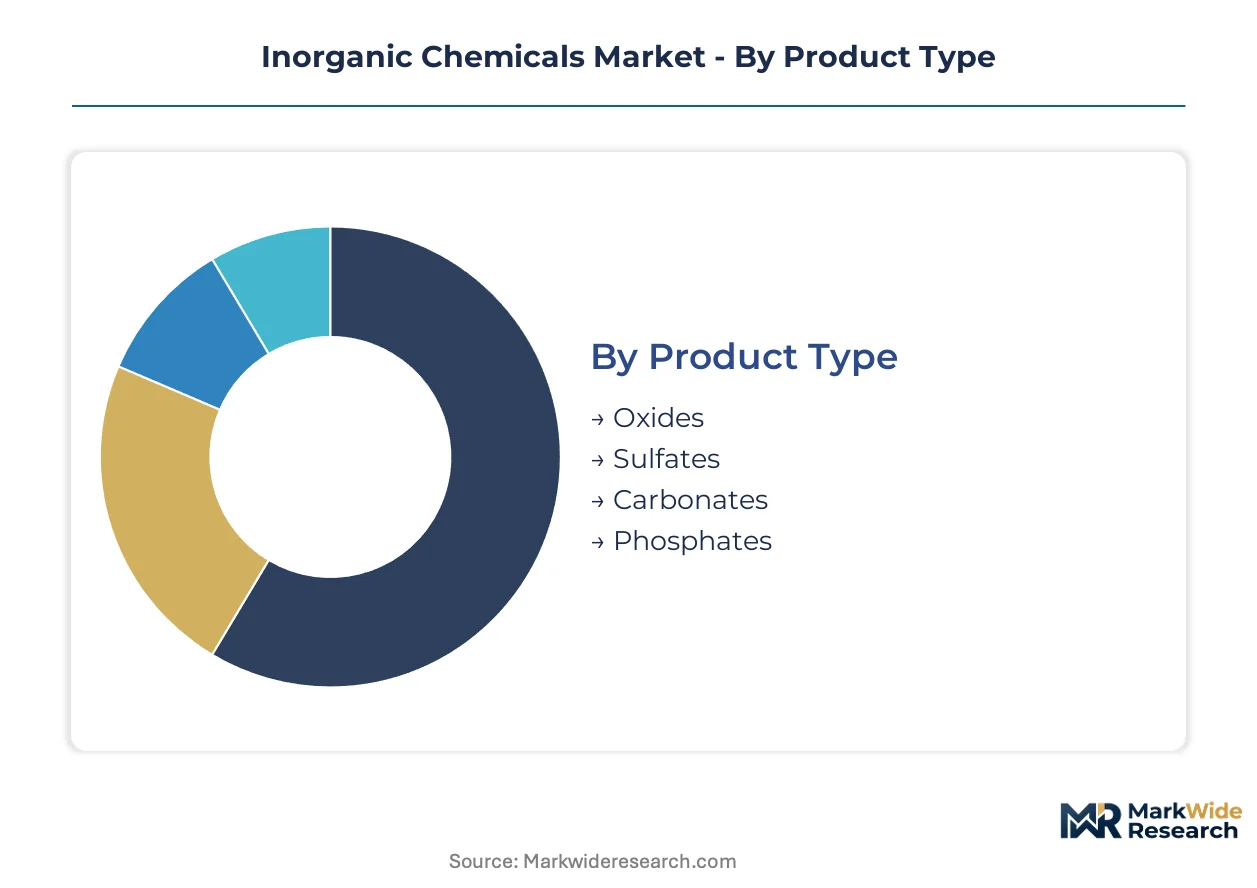
Channel configuration varies sharply across inorganic chemical segments. Electronics-grade materials flow through direct mill-to-fab contracts, while industrial grades move via distributor networks serving fragmented end users.
Product Type:
Oxides and sulfates dominate bulk chemical channels, with phosphates increasingly bypassing traditional distributors for battery electrolyte supply chains.
- Oxides:Metal oxide compounds including titanium dioxide, zinc oxide, and aluminum oxide serve ceramics, coatings, and construction binders. Jiangsu and Shandong province complexes in China capture regional construction and electronics substrate demand through integrated chlor-alkali networks.
- Sulfates:Copper sulfate, zinc sulfate, and aluminum sulfate span technical-grade water treatment applications to semiconductor-grade etching agents. Wafer fabrication facilities in Taiwan and South Korea now require sub-ppb contamination thresholds, pulling membrane-electrolysis capacity upgrades.
- Carbonates:Sodium carbonate and calcium carbonate feed glass manufacturing, pulp processing, and pH adjustment systems across industrial water treatment utilities.
- Phosphates:Mono-, di-, and tri-calcium phosphates serve lithium-ion battery electrolyte additives and pharmaceutical synthesis, with reagent-grade specifications commanding premium positioning.
By volume, oxides lead. By growth pace, phosphates are climbing the fastest.
Application:
Margin structure diverges sharply: agriculture and construction run on commoditized pricing, while electronics and pharmaceuticals extract certification premiums.
- Agriculture:Fertilizer-grade sulfates and phosphates supply soil amendment and micronutrient delivery, with procurement concentrated through cooperative purchasing networks.
- Construction:Cement additives, concrete accelerators, and ceramic glazes absorb technical-grade oxides and carbonates from regional chemical complexes.
- Pharmaceuticals:Reagent-grade phosphates and sulfates meet USP and EP monograph standards for active pharmaceutical ingredient synthesis and buffer preparation.
- Electronics:High-purity precursors for semiconductor fabrication, printed circuit board etching, and display substrate preparation require membrane-derived chlorine and caustic soda feedstocks.
Agriculture commands the largest volume share. Electronics generates the steepest margin expansion.
End Use Industry:
Customer scale determines contract structure: mining and water treatment utilities negotiate multi-year offtake agreements, while food processing and textile buyers purchase on spot markets.
- Mining:Flotation reagents, leaching agents, and pH modifiers consume sulfuric acid derivatives and cyanide complexes through integrated mine-site chemical plants.
- Water Treatment:Municipal and industrial utilities procure aluminum sulfate, ferric chloride, and phosphate-based coagulants under EPA effluent compliance mandates tightening discharge limits.
- Food Processing:Food-grade carbonates and phosphates serve leavening, buffering, and mineral fortification applications under FDA and EFSA additive regulations.
- Textile:Dye fixation, bleaching, and finishing processes consume technical-grade sulfates and chlor-alkali derivatives through regional textile chemical distributors.
Water treatment leads by procurement value. Mining shows the most volatile demand cyclicality.
Grade:
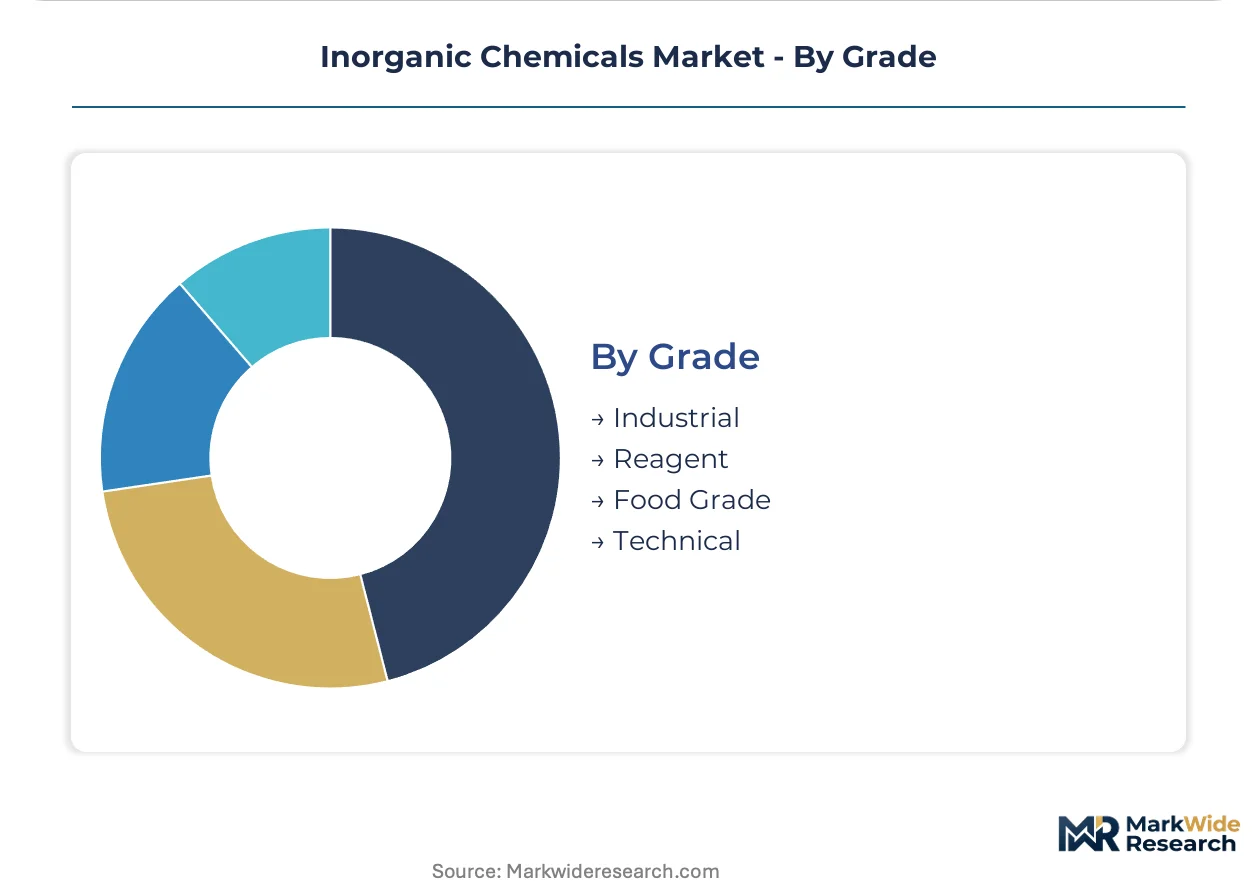
Certification tier determines channel access: industrial and technical grades flow through commodity distributors, while reagent and food grades require audited supply chains.
- Industrial:Bulk chemicals for manufacturing processes with moderate purity requirements, sourced through regional chemical distributors and integrated producer direct sales.
- Reagent:ACS and ISO-specified materials for analytical chemistry and pharmaceutical synthesis, with qualification protocols extending customer conversion timelines.
- Food Grade:FCC and E-number compliant additives for human consumption, subject to HACCP and FSSC 22000 supply chain audits.
- Technical:Specification-grade materials for water treatment, mining, and construction with purity thresholds between industrial and reagent tiers.
Industrial grade dominates tonnage. Reagent grade captures the widest price-to-cost spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor's integrated chemical logistics network underwrites Europe's position, while China's Yangtze River Delta pipeline grid and the US Gulf Coast's barge-terminal system anchor transcontinental supply flows.
United States
Water treatment utilities along the Ohio River basin are expanding aluminum sulfate procurement to meet EPA effluent guideline revisions. The EPA's tightening discharge limits for heavy metals are forcing municipal procurement shifts toward membrane-compatible coagulants. Houston's chlor-alkali complex is retooling mercury-cell capacity to serve semiconductor fabs in Austin and Dallas with sub-ppb grade caustic soda.
China
Jiangsu and Shandong province electronics manufacturers are pulling concentrated sulfuric acid from integrated chlor-alkali complexes for wafer fabrication feedstock. MEE enforcement of SO₂ and NOₓ caps is compressing marginal smelter-acid capacity and redirecting investment toward membrane electrolysis. The Yangtze River Delta pipeline network is consolidating specialty chemical distribution for display substrate and battery electrolyte additive producers.
Germany
Leverkusen and Ludwigshafen chemical parks are capturing electronics-grade oxide qualification advantages from early membrane conversion investments. REACH substance restrictions on cadmium-bearing pigments are compressing established product lines and accelerating rare-earth substitution R&D. BASF SE's integrated oxide production networks across the Rhine corridor are serving semiconductor fabrication scaling in Dresden and Munich.
Saudi Arabia
Jubail Industrial City's sulfur derivative complexes are anchoring regional sulfate supply for water treatment and construction chemicals across Gulf Cooperation Council markets. SAMR enforcement of product conformity standards is creating certification barriers for unqualified importers. SABIC's sulfuric acid and chlor-alkali integration is capturing construction demand from NEOM and Red Sea coastal development zones.
India
Gujarat's specialty chemical belt is expanding technical-grade sulfate capacity to capture domestic water treatment procurement under BIS certification mandates. CDSCO alignment with ICH guidelines is tightening pharmaceutical-grade phosphate import specifications. Mumbai-Pune industrial corridor manufacturers are qualifying reagent-grade materials for lithium-ion battery electrolyte additive supply chains.
Inorganic Chemicals Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded German and Belgian chemical conglomerates holding integrated oxide networks while private Middle Eastern and Asian producers concentrate on sulfur derivative scale. The market structure fragments into three archetypes: integrated chlor-alkali-oxide producers, specialty phosphate and sulfate specialists, and regional smelter-acid converters. Dominant competitive moves include membrane electrolysis technology licensing for mercury-cell replacement and direct mill-to-fab contract capture in semiconductor clusters.
Within the integrated producer tier, BASF SE and Evonik Industries AG represent European qualification advantages in electronics-grade materials, while SABIC anchors Middle Eastern sulfur derivative supply. These three exemplify divergent geographic and vertical strategies: Rhine-based oxide integration, Ruhr-focused reagent-grade phosphates, and Gulf Coast sulfur complex scale. Their positioning reflects the market's split between membrane-capable purity tiers and legacy-dependent technical grades.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Solvay SA |
| LANXESS AG |
| Akzo Nobel N.V. |
| Evonik Industries AG |
| INEOS Group Limited |
| Tata Chemicals Limited |
| Olin Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between chlor-alkali producers and semiconductor fabs lock in multi-year supply access while anchoring price visibility against sulfur feedstock volatility. These agreements concentrate procurement power among membrane-capable suppliers in Germany, China, and the United States as EPA and REACH compliance costs reshape contract structures.
Pricing Analysis
Volume-discount tiering separates electronics-grade reagent specifications from technical-grade water treatment materials, with sub-ppb purity thresholds commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade and geographic delivery cost, with membrane-derived caustic soda carrying brand premium over mercury-cell legacy output. Cost compression in technical-grade sulfates is intensifying because sulfur feedstock volatility from copper smelter operations feeds spot-market instability. Mining and water treatment utilities show highest price sensitivity through cooperative purchasing networks, while semiconductor fabs absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
China and Germany anchor integrated chlor-alkali-oxide production, with Jiangsu province complexes feeding electronics substrate demand and Rhine corridor facilities serving pharmaceutical synthesis. Raw material dependencies center on sulfur from copper/zinc smelting, salt brine for electrolysis, and phosphate rock for lithium-ion additives. Single-source vulnerability concentrates in smelter-acid supply chains where copper refining output fluctuations transmit directly to sulfate manufacturers. Distribution runs through direct mill-to-fab contracts for electronics grades and regional distributor networks for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrolysis technology is disrupting legacy chlor-alkali economics, with mercury-cell decommissioning timelines compressing competitive repositioning windows across integrated chemical complexes.
For Market Incumbents: Compound membrane conversion investments to capture semiconductor-grade qualification advantages before REACH substance restrictions eliminate mercury-cell capacity entirely. Backward integration into sulfur derivative production hedges smelter-acid volatility, while early certification in India's BIS technical-grade sulfate framework defends against emerging domestic competitors. Capacity addition in Saudi Arabia's Jubail Industrial City leverages regional construction demand from NEOM development zones. For New Entrants and Emerging Players: Anchor in India's Gujarat specialty chemical belt where BIS certification gaps create captive supply opportunities for technical-grade sulfates in water treatment procurement. White-space targets concentrate on reagent-grade phosphates for lithium-ion battery electrolyte additives, with Mumbai-Pune corridor manufacturers seeking qualified domestic sources. Go-to-market positioning should emphasize direct mill-to-fab contract capture in Taiwan and South Korea semiconductor clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane-capable integrated producers with locked semiconductor fab offtake agreements spanning the analysis window. Long-term viability favors acquisition targets with early REACH compliance investments and rare-earth substitution R&D pipelines rather than legacy pigment or mercury-cell dependent assets. The signal to watch is qualification protocol completion timelines for wafer-fabrication chemical supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrolysis Conversion | REACH and EPA mercury phase-outs force technology transition investments across Rhine and US Gulf Coast facilities. |
| Backward Integration into Sulfur Derivatives | Captive sulfuric acid production insulates sulfate manufacturers from copper smelter output volatility. |
| Direct Mill-to-Fab Contract Capture | Taiwan and South Korea semiconductor clusters consolidate procurement through specification-setting chemical suppliers. |
| BIS Certification Investment | India's technical-grade sulfate mandates create non-tariff barriers favoring domestic qualified producers. |
| Rare-Earth Substitution R&D | REACH cadmium pigment restrictions accelerate reformulation timelines without immediate substitute scale. |
Methodological Framework
A standing panel of chlor-alkali plant managers, downstream OEM procurement leads, specialty chemical distribution partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA effluent guideline documentation. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation across grade tiers and regional production hubs.
Consistency checks validated volume and value outputs against external benchmarks including trade flow databases and regional chemical association statistics. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub segmentation across the projection horizon. CAGRs were derived from production capacity expansion schedules, end-use demand elasticity coefficients, and regulatory compliance cost trajectories. Forecast inputs incorporated membrane electrolysis conversion timelines and semiconductor fab buildout pipelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA effluent tightening and REACH substance restriction enforcement; material deviation in sulfur feedstock pricing or mercury-cell decommissioning acceleration would warrant model refresh. Recalibration cycles align with material shifts in regulatory compliance timelines and semiconductor capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Potassium Alum Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
United States Construction Chemicals Market
Chemicals
Egypt Acidulants Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Global Construction Chemical Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Ferric Chloride Market
Chemicals
South Korea Methanol Market
Chemicals
Iscotrizinol Market
Chemicals
Naturally Derived Fatty Alcohol Market