
 Europe Refining Catalysts Market | 2026-2036
Europe Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refining Catalysts Market Foresight
European catalyst manufacturing capacity is hardening around a core of specialized producers with deep technical heritage. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply advantages for hydrotreating formulations. Haldor Topsoe A/S anchors its position through proprietary metal-support architectures that dominate hydrocracking catalyst supply to Nordic and Baltic refiners. Albemarle Corporation competes on scale, operating large-scale production nodes that extend its reach into Central European refinery maintenance cycles.
Refining catalysts are heterogeneous substances—typically alumina, silica-alumina, or zeolite supports impregnated with active metals such as cobalt, molybdenum, nickel, or platinum group elements—that accelerate petroleum conversion reactions under elevated temperature and pressure conditions. Their primary function is to upgrade crude oil fractions into transportation fuels and petrochemical feedstocks while managing sulfur, nitrogen, and heavy metal contaminants. Hydrotreating catalysts occupy the largest volume position due to mandatory sulfur reduction across European diesel and gasoline pools. Hydrocatalysts command premium pricing tied to rare earth metal loading and reactor severity requirements. Advanced technology deployments are gaining share as refiners retrofit for hydrogen integration and biofeed co-processing.
The European Chemicals Agency (ECHA) governs substance registration and hazard classification under REACH, directly affecting catalyst precursor imports and waste catalyst disposal protocols. The EU Green Deal's carbon border adjustments and the F-Gas Regulation's phase-down schedules are forcing reformulations with lower emission profiles and altered activation chemistries. Stakeholders must track how the EU AI Act and digital product passport requirements reshape catalyst performance verification and supply chain documentation obligations.
Market Dynamics
European refiners face a structural squeeze between heavier crude slates requiring more intensive hydrotreating and the EU Green Deal's tightening carbon intensity benchmarks for transport fuels.
Growth Catalysts
- EU Green Deal carbon intensity mandates:Refiners must reduce lifecycle emissions from diesel and gasoline pools, forcing catalyst reloads with higher activity metal loadings and advanced support architectures.
- Heavier North Sea and Russian-origin crude processing:Deteriorating feedstock quality across Northwest European refineries expands hydrotreating catalyst consumption per barrel of throughput.
- Biofeed co-processing retrofits:Vegetable oil and waste lipid integration into fluid catalytic cracking and hydrocracker units demands specialized catalyst formulations tolerant to oxygenates and phosphorus contaminants.
Market Restraints
- Cobalt and molybdenum price volatility:Active metal costs constitute 35-45% of hydrotreating catalyst manufacturing economics, with concentrate supply concentrated in the Democratic Republic of Congo and Chile.
- REACH registration burdens:ECHA substance authorization timelines for novel catalyst precursors extend 18-36 months, freezing formulation innovation cycles for European producers.
- Platinum group metal substitution risk:Base-metal alternatives in naphtha reforming catalysts threaten premium-priced noble metal formulations in smaller European refineries.
Strategic Opportunities
- Hydrogen integration projects in the Netherlands:Rotterdam and Amsterdam refining clusters are retrofitting for green hydrogen feedstock, creating demand for sulfur-tolerant shift catalysts and purification absorbents.
- Digital product passport compliance:The EU AI Act and CSRD traceability requirements favor catalyst suppliers with integrated sensor platforms and blockchain-verified performance data.
- Spent catalyst metal recovery:Circular economy mandates under the EU Critical Raw Materials Act position regenerators and reclaimers for closed-loop cobalt, nickel, and rare earth recovery contracts.
Industry Challenges
- Specialized hydroprocessing engineering talent scarcity:Retiring catalyst technologists and reactor designers in Germany and Belgium outpace university pipeline replenishment.
- Legacy refinery control system integration:Advanced catalyst monitoring platforms require retrofitting DCS architectures from the 1990s, complicating real-time optimization deployments.
- Multi-jurisdiction waste catalyst disposal:Cross-border shipment of spent hydrotreating materials faces divergent hazardous waste classifications between German Länder and Benelux authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refining Catalysts Market |
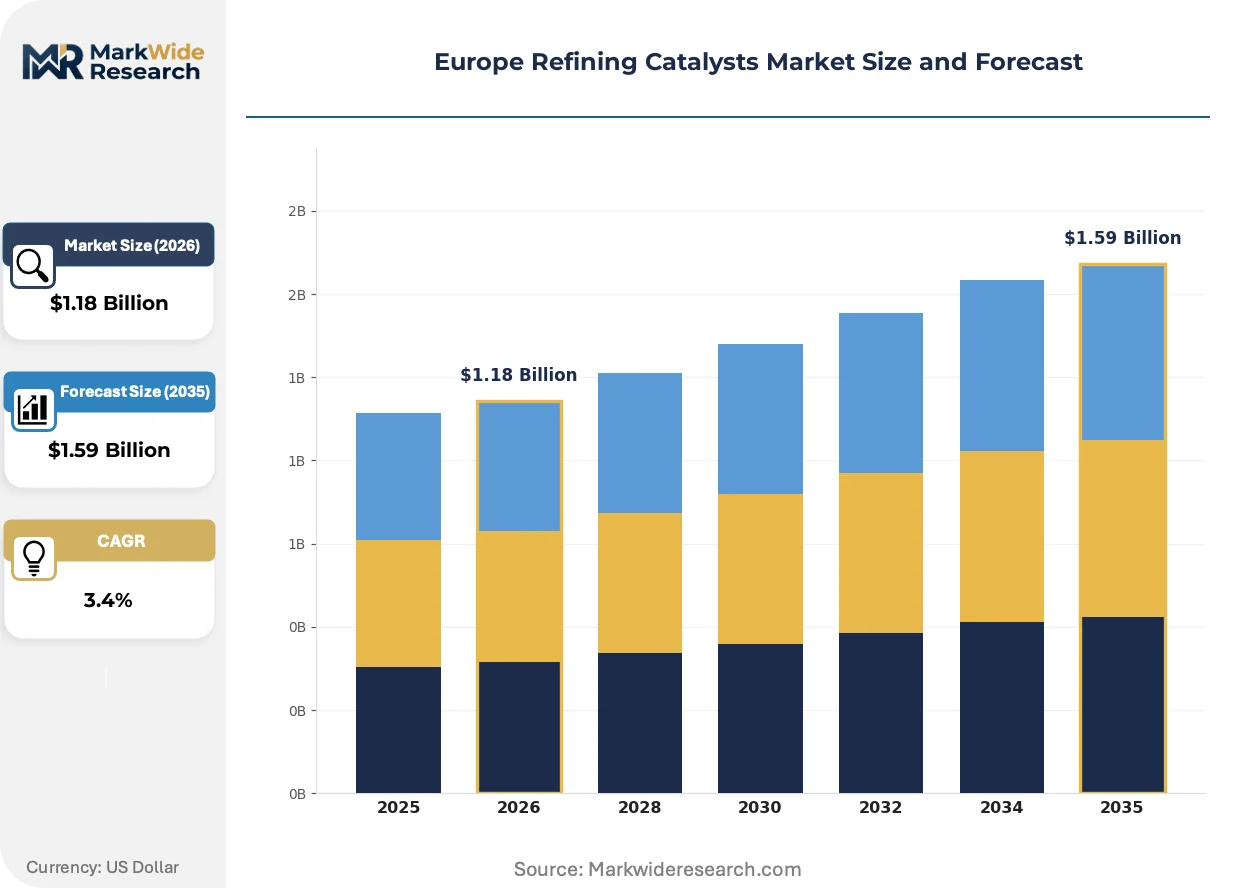
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.59 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
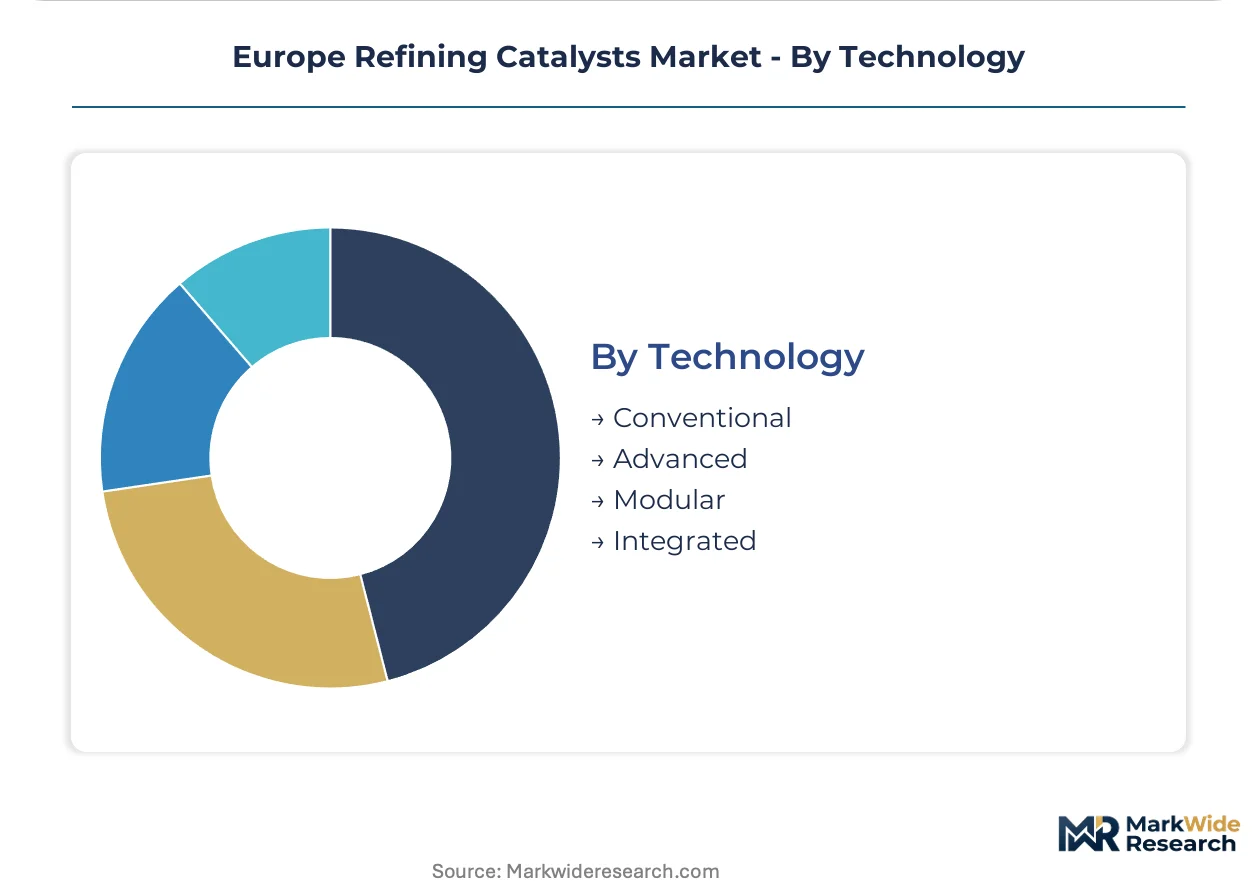
| Segmentation | Catalyst Type: Hydrocracking, Catalytic Reforming, Alkylation, Hydrotreating End User: Oil Refineries, Petrochemical Plants, Biofuel Producers, Specialty Chemicals Form: Granules, Powder, Liquid, Tablets Technology: Conventional, Advanced, Modular, Integrated |
| Companies Covered | BASF SE, Albemarle Corporation, Haldor Topsoe A/S, W. R. Grace & Co.-Conn., Axens, Clariant, Johnson Matthey, Honeywell International Inc., Arkema, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refining Catalysts Market Shifts & Advancements
Catalyst architecture is fragmenting into application-specific formulations as European refiners abandon universal designs in favor of precision-tuned systems for biofeed tolerance and hydrogen efficiency.
Layered zeolite-metal composite supports are modularizing hydrotreating reactor design. These structures separate sulfur saturation from aromatic saturation functions across discrete zones. Nordic refiners in Denmark and Sweden are piloting these configurations for renewable diesel production. The technology is modularizing vessel sizing standards, allowing smaller European refineries to match larger complex yields without full reactor replacement.
The F-Gas Regulation phase-down is forcing fluorinated catalyst precursor reformulation. Perfluorinated compounds in catalyst synthesis face mounting restriction under 2024-2030 reduction schedules. German and Belgian catalyst producers are accelerating fluorine-free activation chemistries for hydrocracking formulations. This regulatory pressure is compressing patent landscapes around alternative surface modification techniques.
Refinery procurement departments are consolidating catalyst supply contracts into multi-year performance agreements. Traditional spot purchasing for turnaround cycles is yielding to indexed contracts tying payment to actual sulfur removal efficiency and catalyst cycle length. This shift is most advanced among integrated operators in the ARA hub, where procurement teams now mandate digital performance verification through embedded reactor sensors.
Europe Refining Catalysts Market Segmentation
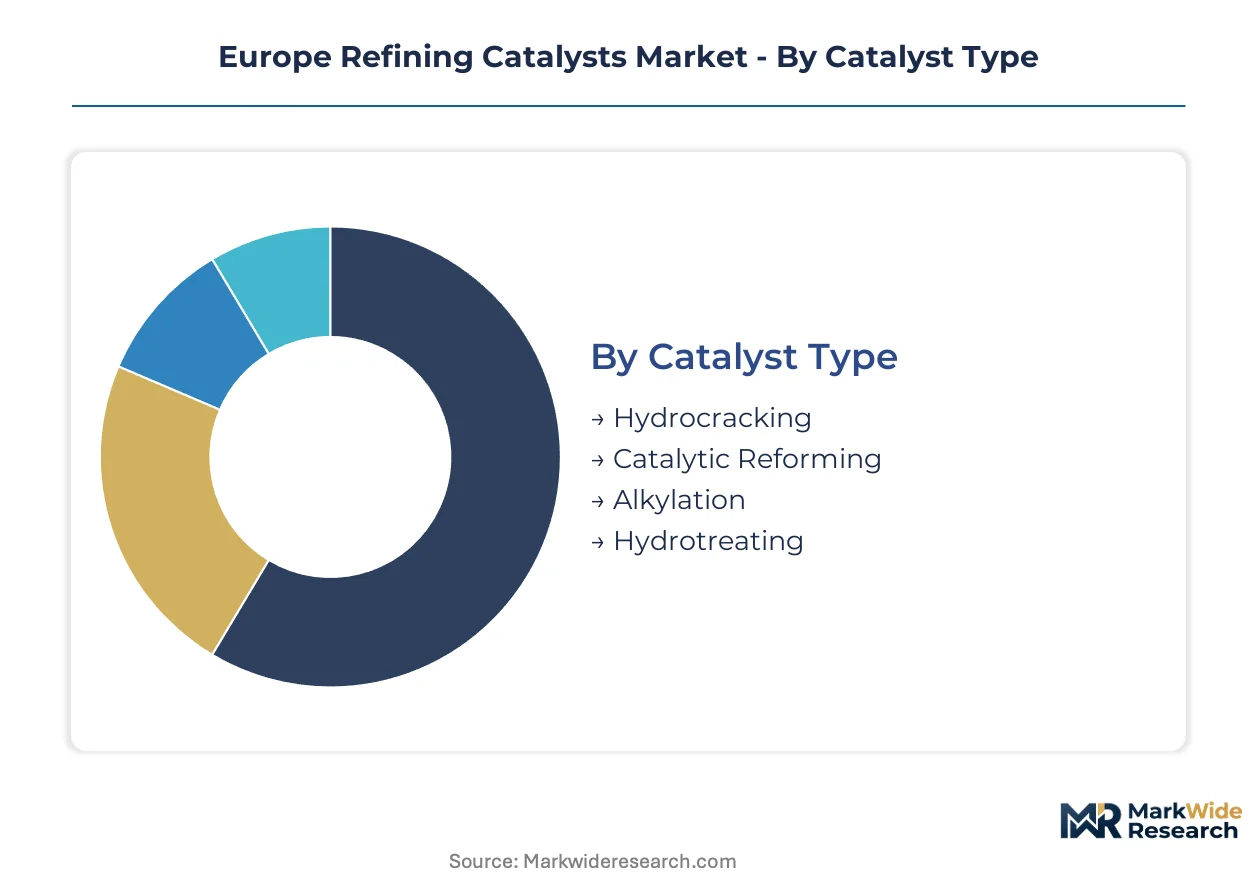
Refining catalyst procurement in Europe fragments across technical specifications, reactor configurations, and regulatory compliance tiers. Each segmentation axis reveals distinct margin structures and supplier relationships that determine competitive positioning for catalyst manufacturers and refinery operators alike.
Catalyst Type:
Standardization dominates commodity hydrotreating formulations, while hydrocracking and reforming catalysts demand extensive customization to match feedstock quality and reactor severity profiles.
- Hydrotreating:These cobalt-molybdenum or nickel-molybdenum formulations on alumina supports saturate sulfur and nitrogen heteroatoms in distillate streams. Demand concentrates in German and Dutch refineries processing heavier North Sea crudes, where the EU Green Deal's sulfur reduction mandates force frequent catalyst reloads with higher metal loadings.
- Hydrocracking:Bifunctional catalysts combining acidic zeolite supports with noble metal hydrogenation components crack heavy vacuum gas oil into middle distillates. Nordic refiners in Sweden and Finland deploy these for maximum diesel yield from deteriorating feedstock quality, with cycle lengths directly tied to rare earth metal stability.
- Catalytic Reforming:Platinum-rhenium or platinum-tin on chlorided alumina convert naphtha into high-octane reformate and aromatics.
- Alkylation:Solid acid or liquid acid catalysts combine olefins with isobutane for gasoline blending components.
Leading the category by volume: Hydrotreating. Expanding most quickly: Hydrocracking.
End User:
Customer scale and technical sophistication determine service intensity, with integrated oil companies demanding performance guarantees that smaller biofuel entrants cannot negotiate.
- Oil Refineries:These operators consume catalyst volumes tied to crude throughput and complexity configuration. The ARA hub refineries in Rotterdam and Antwerp maintain the densest procurement schedules, with turnaround cycles every 3-4 years driving predictable replacement demand for hydrotreating and hydrocracking formulations.
- Petrochemical Plants:Naphtha crackers and aromatics complexes require specialized reforming and dehydrogenation catalysts. Belgian operators along the Port of Antwerp-Bruges corridor represent the most sophisticated demand segment, specifying custom metal loadings and particle size distributions for fluidized bed applications.
- Biofuel Producers:Renewable diesel and SAF facilities process vegetable oils and waste lipids through hydrotreating pathways.
- Specialty Chemicals:Fine chemical and pharmaceutical intermediate manufacturers utilize precision hydrogenation catalysts.
Highest procurement sophistication: Petrochemical Plants. Fastest demand emergence: Biofuel Producers.
Form:
Physical presentation shapes reactor hydrodynamics and pressure drop economics, with granular forms dominating fixed-bed applications and liquids penetrating slurry-phase systems.
- Granules:Extruded cylindrical or spherical particles between 1.2-3.2 mm diameter optimize void fraction and surface area in fixed-bed hydrotreaters. German refiners specify narrow particle size distributions to minimize pressure drop across multi-reactor trains, with attrition resistance testing mandatory under ECHA substance characterization protocols.
- Powder:Finely divided catalysts serve ebullated-bed and slurry-phase hydrocracking configurations. These forms dominate pilot-scale biofuel co-processing trials in Denmark and Sweden, where renewable feedstock compatibility testing precedes commercial-scale granule procurement.
- Liquid:Homogeneous catalyst precursors or dispersed nanoparticle suspensions enable specific activation chemistries.
- Tablets:Compressed cylindrical forms with controlled crushing strength suit radial-flow reactors.
Dominant volume position: Granules. Steepest expansion trajectory: Powder.
Technology:
Technology tier correlates with digital integration intensity and predictive maintenance capability, separating legacy installations from retrofit-ready platforms.
- Advanced:These formulations incorporate embedded sensors, layered support architectures, and AI-optimized activation protocols. Dutch refiners in Rotterdam mandate these systems under procurement contracts tying payment to verified sulfur removal efficiency, with performance data feeding directly into EU AI Act compliance documentation.
- Integrated:Catalyst-reactor systems designed as unified packages with proprietary hardware and software interfaces. Belgian operators deploy these for maximum hydrogen efficiency in hydrocracking service, with vendor lock-in creating long-term supply security.
- Conventional:Standard formulations without embedded monitoring or predictive capabilities.
- Modular:Pre-configured catalyst packages for rapid deployment in smaller refineries.
Widest installed base: Conventional. Sharpest growth slope: Advanced.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea crude slate deterioration and Rhine corridor refining density position Germany, the Netherlands, Belgium, France, and the United Kingdom as the primary demand centers for hydrotreating and hydrocracking catalyst formulations.
Germany
Ludwigshafen and the broader Rhine-Neckar chemical triangle sustain captive catalyst production alongside third-party procurement for hydrotreating reloads. The German Federal Immission Control Act implements EU Green Deal carbon intensity benchmarks through binding emission limits on refinery operations. Bavarian refineries near Ingolstadt and Karlsruhe processing heavier Russian-origin crudes drive elevated catalyst consumption per barrel.
Netherlands
Rotterdam and Amsterdam harbor clusters anchor Northwest European catalyst demand through dense hydrocracker and hydrotreater configurations processing high-sulfur feedstocks. The Dutch National Climate Agreement mandates transport fuel carbon intensity reductions that force catalyst formulations with higher metal loadings. Port of Rotterdam operators retrofitting for green hydrogen integration generate demand for sulfur-tolerant shift catalysts and purification absorbents.
Belgium
Antwerp-Bruges port corridor refineries specify custom hydrocracking catalysts for maximum middle distillate yield from deteriorating feedstock quality. Flanders and Wallonia maintain divergent hazardous waste classifications for spent catalyst shipment, complicating cross-border logistics. Belgian operators deploy integrated catalyst-reactor systems with proprietary hardware interfaces for hydrogen efficiency optimization.
France
Normandy and Provence-Alpes-Côte d'Azur refining clusters process North African and Middle Eastern crudes requiring intensive hydrotreating for EU diesel sulfur specifications. France's national low-carbon strategy implements EU Green Deal benchmarks through binding refinery emission reduction trajectories. Gonfreville and La Mède facilities pilot biofeed co-processing catalysts for renewable diesel production.
United Kingdom
Grangemouth and Pembroke refineries sustain hydrotreating catalyst demand through North Sea crude processing with rising sulfur content. The UK Emissions Trading Scheme parallels EU carbon border adjustment mechanisms, forcing catalyst reloads for emission intensity compliance. Scottish and Welsh facilities face spent catalyst disposal constraints under devolved environmental permitting regimes.
Europe Refining Catalysts Market Competitive Landscape
Global majors compete with regional champions across formulation specialization and captive supply integration. The European refining catalysts market exhibits tiered concentration with integrated chemical conglomerates holding scale advantages alongside specialized technology licensors commanding premium positions in hydrocracking architectures. Three archetypes dominate: integrated chemical majors with backward catalyst production, dedicated catalyst technology licensors, and diversified materials suppliers extending into petroleum processing applications. Competitive dynamics center on multi-year performance contracting and digital product passport compliance capabilities.
Among Germany-based integrated producers, BASF SE anchors the captive supply archetype through Ludwigshafen manufacturing integration. Danish technology licensor Haldor Topsoe A/S exemplifies the specialized architecture tier with proprietary metal-support formulations. Albemarle Corporation represents scale-driven diversification from specialty chemicals into refinery catalyst supply. These three occupy distinct competitive positions without direct segment overlap, reducing price-based rivalry in favor of performance-guarantee contracting.
| Leading Market Players |
|---|
| BASF SE |
| Albemarle Corporation |
| Haldor Topsoe A/S |
| W. R. Grace & Co.-Conn. |
| Axens |
| Clariant |
| Johnson Matthey |
| Honeywell International Inc. |
| Arkema |
| Others |
Supply & Pricing Matrix
Cobalt and molybdenum concentrate costs cascade through hydrotreating catalyst manufacturing economics, with active metal loadings constituting the dominant input tier that separates premium formulations from standard reload contracts across ARA hub procurement desks.
Pricing Analysis
Warranty bundling now separates contract tiers, with integrated operators in Rotterdam and Antwerp demanding multi-year performance guarantees that tie payment to verified sulfur removal efficiency and catalyst cycle length. Three-tier pricing structure across premium, standard, and economy levels reflects metal loading density, support architecture complexity, and digital verification capability. Cost compression in economy-grade hydrotreating formulations is intensifying because REACH registration timelines freeze formulation innovation cycles. Integrated oil companies exhibit lowest price sensitivity due to performance-contracting mandates, while smaller biofuel entrants face acute margin pressure on spot procurement.
Supply Chain Analysis
Freight costs for spent catalyst cross-border shipment have risen sharply under divergent hazardous waste classifications between German Länder and Benelux authorities, complicating circular economy logistics. Manufacturing concentration centers on Germany, Belgium, and the Netherlands, with Ludwigshafen and Antwerp-Bruges anchoring formulation capacity. Active metal sourcing draws from Chilean molybdenum concentrates and Democratic Republic of Congo cobalt, creating single-source vulnerability for hydrotreating economics. Distribution runs through refinery procurement departments consolidating multi-year agreements with embedded sensor verification mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active metal supply concentration and REACH authorization bottlenecks constrain European catalyst manufacturing capacity, propping pricing power for incumbents with captive precursor supply or established registration portfolios.
For Market Incumbents: To counter base-metal substitution threats in naphtha reforming catalysts, deepen proprietary metal-support architectures through R&D investment in layered zeolite composites, while securing backward integration into rare earth stabilizer supply through long-term offtake agreements with Nordic reclaimers. For New Entrants and Emerging Players: Fluorine-free activation chemistries offer a technology-first wedge into hydrocracking formulation supply, with German and Belgian producers accelerating patent landscapes around alternative surface modification techniques. Target biofuel co-processing catalyst trials in Denmark and Sweden, where renewable feedstock compatibility testing precedes commercial-scale procurement and incumbent relationships remain unformed. For Investors and Strategic Acquirers: EU AI Act digital product passport mandates are the leading indicator that catalyst suppliers with integrated sensor platforms and blockchain-verified performance data will command acquisition premiums. Over a multi-year horizon, prioritize targets with closed-loop spent catalyst metal recovery capabilities under Critical Raw Materials Act circular economy positioning, watching for Rotterdam hydrogen integration project announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Metal Supply | Secures cobalt and molybdenum concentrate access against Democratic Republic of Congo supply volatility. |
| Fluorine-Free Formulation Development | Accelerates patent positioning ahead of F-Gas Regulation phase-down deadlines. |
| Digital Product Passport Compliance | Meets EU AI Act traceability mandates through embedded reactor sensor platforms. |
| Spent Catalyst Metal Recovery Partnerships | Positions for closed-loop contracts under EU Critical Raw Materials Act circular economy requirements. |
| Biofeed Co-Processing Catalyst Trials | Captures renewable diesel and SAF facility demand ahead of commercial-scale procurement cycles. |
Research Methodology
Multi-period observation of refinery turnaround cycles, catalyst reload frequencies, and ECHA registration timelines anchored the trend analysis, supplemented by interviews with catalyst procurement managers at ARA hub refineries, technical R&D directors at formulation producers, and spent catalyst reclaimers in Germany and Belgium. Secondary validation drew from ECHA substance registration databases, EU customs trade data for catalyst precursor imports, and SEC filings of diversified materials suppliers. Bottom-up volume modeling triangulated against top-down market sizing across catalyst type, end user, and technology tier segments.
Segment-weighting applied catalyst metal loading economics and reactor severity coefficients to distribute value across hydrotreating, hydrocracking, and reforming categories. CAGRs derived from regression analysis of historical reload patterns and projected crude slate deterioration trajectories across the analysis window. Forecast inputs incorporated EU Green Deal carbon intensity mandate implementation schedules and F-Gas Regulation reformulation timelines specific to European refining chemistry.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Democratic Republic of Congo cobalt supply disruptions or accelerated EU carbon border adjustment mechanism implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Hydrotreating Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
BDO Synthesis Catalyst Market