
 Europe PGM Catalyst Market | 2026-2036
Europe PGM Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Europe PGM Catalyst Market Insights
Aftermarket catalyst recycling is reconfiguring margin pools away from virgin PGM sales toward closed-loop recovery services. BASF SE leverages its Ludwigshafen integrated site to control refining-to-catalyst production pathways. Johnson Matthey sustains technology leadership in gasoline particulate filter formulations. Umicore anchors European supply security through its Hoboken precious metals recycling complex.
Platinum group metal catalysts are heterogeneous or homogeneous systems employing platinum, palladium, or rhodium dispersed on ceramic or metallic substrates, typically operating at temperatures between 200°C and 600°C with surface areas exceeding 50 m²/g to maximize active site exposure. Their primary commercial purpose is to lower activation energy for oxidation, reduction, and hydrogenation reactions in emissions control and chemical processing. Palladium catalysts dominate automotive three-way converter applications due to superior light-off performance under cold-start conditions. Heterogeneous catalysis occupies the largest technology share, though electrocatalysis for proton exchange membrane fuel cells represents the fastest-expanding application segment. Mixed metal catalysts command premium pricing as automakers seek to reduce palladium loadings amid sustained metal price volatility.
The European Chemicals Agency enforces REACH authorization requirements for nickel and cobalt catalyst alternatives, directly elevating PGM substitution demand in hydrogenation processes. The EU F-Gas Regulation and forthcoming Euro 7 standards from the European Commission mandate stricter cold-start emission limits, compelling catalyst manufacturers to engineer higher PGM loadings or advanced washcoat architectures. Stakeholders must monitor ECHA substance evaluation timelines and Euro 7 implementation protocols to anticipate procurement cost shifts and qualify next-generation catalyst formulations.
Market Dynamics
The Euro 7 emission standards are compressing catalyst design cycles and forcing automakers to absorb higher PGM loadings per vehicle, fundamentally restructuring procurement economics across the European supply base.
Growth Catalysts
- Tightening nitrogen oxide thresholds:The European Commission's Euro 7 protocols mandate near-zero cold-start emissions, compelling OEMs to deploy advanced washcoat architectures with elevated palladium and rhodium densities.
- REACH authorization pressure:ECHA restrictions on nickel and cobalt catalyst alternatives are accelerating PGM substitution in hydrogenation processes across European chemical manufacturing.
- Rhineland industrial clustering:Co-location of PGM refining and catalyst fabrication in Germany's chemical corridor reduces logistics friction and enables just-in-time substrate delivery to automotive Tier 1 suppliers.
Market Restraints
- PGM price volatility:Palladium and rhodium spot market swings create margin compression for catalyst fabricators locked into long-term automotive supply contracts.
- Primary supply concentration:South African platinum and Russian palladium dominance exposes European processors to geopolitical supply disruptions and export restriction risks.
- Substitute catalyst development:Base-metal zeolite systems for lean-burn gasoline engines threaten palladium loadings in specific vehicle segments.
Strategic Opportunities
- Closed-loop recovery services:Aftermarket catalyst recycling in Belgium and Germany captures margin pools previously flowing to virgin metal traders, with Umicore's Hoboken complex anchoring European capacity.
- Proton exchange membrane fuel cells:Electrocatalysis applications for hydrogen mobility represent the fastest-expanding technology segment as EU Green Deal funding accelerates electrolyzer deployment.
- Poland and Czech Republic expansion:Eastern European automotive assembly growth creates demand for regional catalyst supply nodes outside the saturated German market.
Industry Challenges
- Wet chemistry expertise scarcity:PGM refining and washcoat formulation requires specialized metallurgical and ceramic engineering skills that European technical universities are not producing at replacement rates.
- Euro 7 certification timelines:Accelerated validation protocols compress the window for catalyst qualification, forcing simultaneous engineering changes across substrate, washcoat, and canning operations.
- Legacy diesel catalyst inventory:Stranded palladium loadings in declining diesel applications create working capital drag and complicate metal hedging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe PGM Catalyst Market |
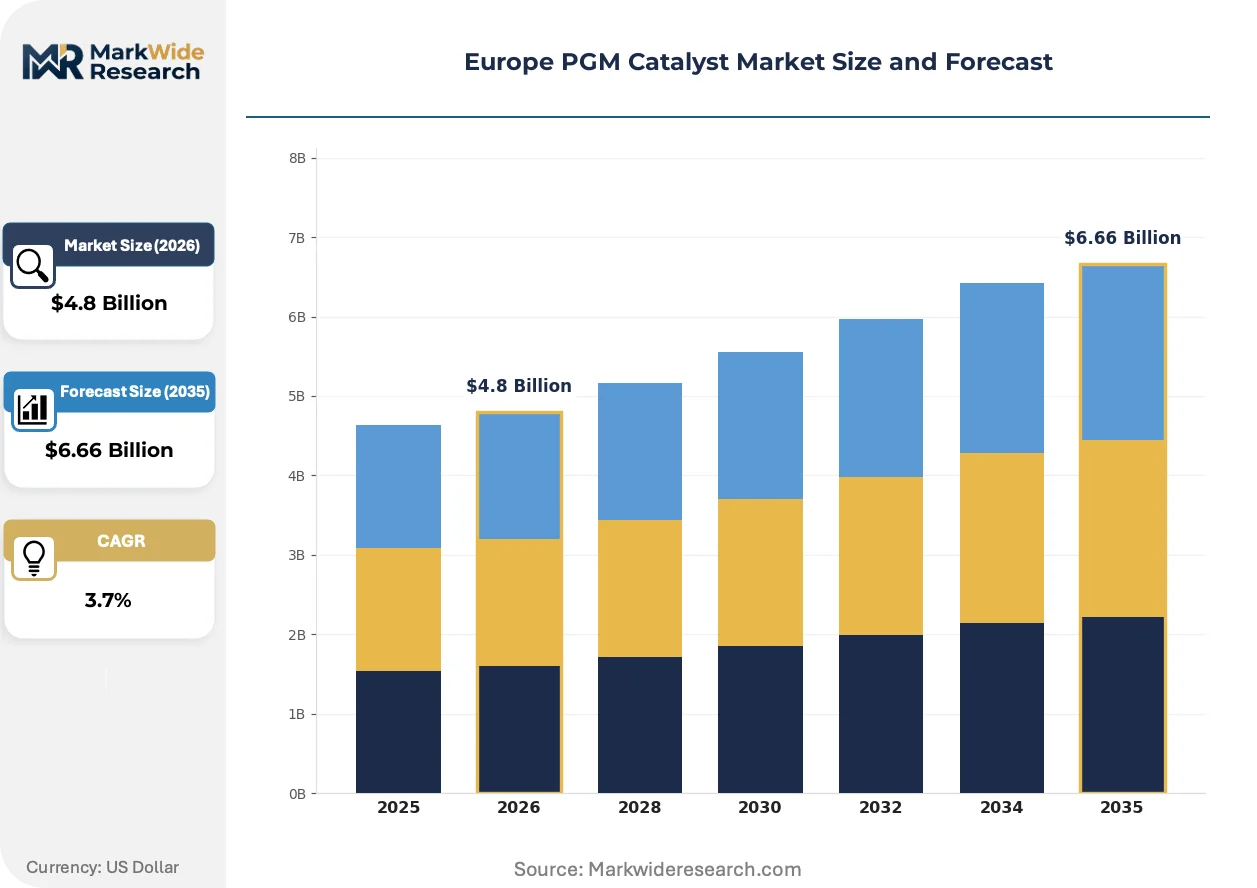
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum Catalysts, Palladium Catalysts, Rhodium Catalysts, Mixed Metal Catalysts End User: Automotive Industry, Chemical Manufacturing, Oil Refining, Environmental Applications Application: Emissions Control, Fuel Cells, Bioreactors, Hydrogen Production Technology: Catalytic Converters, Homogeneous Catalysis, Heterogeneous Catalysis, Electrocatalysis |
| Companies Covered | BASF SE, Johnson Matthey, Umicore, Heraeus Holding, Clariant, Evonik Industries AG, Topsoe A/S, Chimet, Axens, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe PGM Catalyst Market Trends and Innovations
European catalyst engineering is pivoting from incremental washcoat optimization toward architecture-level redesigns that integrate thermal management, PGM distribution, and substrate geometry into unified emission control systems.
Advanced mixed-metal catalyst formulations are hybridizing platinum-palladium-rhodium ratios to maintain light-off performance while reducing absolute metal content per converter. German and French OEM procurement teams are qualifying these systems for 2027 model year gasoline platforms. The technology is hybridizing what were previously distinct palladium-dominant and platinum-dominant supply chains into unified procurement categories.
The EU F-Gas Regulation and impending Euro 7 implementation protocols are mandating stricter cold-start emission limits that legacy catalyst architectures cannot satisfy. This regulatory pressure is forcing simultaneous redesign of substrate geometry, washcoat porosity, and PGM distribution patterns. Catalytic converter suppliers in Germany, France, and Italy are responding by vertically integrating PGM refining capabilities to control metal sourcing costs.
Automotive OEMs are consolidating catalyst procurement under single-source agreements that bundle substrate supply, PGM metal management, and end-of-life recycling obligations. This behavior compresses the supplier base and shifts commercial risk from automakers to catalyst fabricators. The pattern is most visible in German premium vehicle manufacturing, where procurement teams are eliminating dual-source strategies in favor of closed-loop partnerships with integrated refining-to-catalyst producers.
Europe PGM Catalyst Market Segmentation
PGM catalyst procurement patterns diverge sharply across end-use applications, with automotive contracts commanding multi-year supply commitments while chemical process catalysts turn over on 18-24 month replacement cycles. Understanding these velocity differentials enables fabricators to optimize working capital deployment and metal hedging strategies.
Product Type:
Replacement cycles vary from continuous electrochemical cell replenishment to decade-long automotive substrate life, creating distinct inventory risk profiles across metal categories.
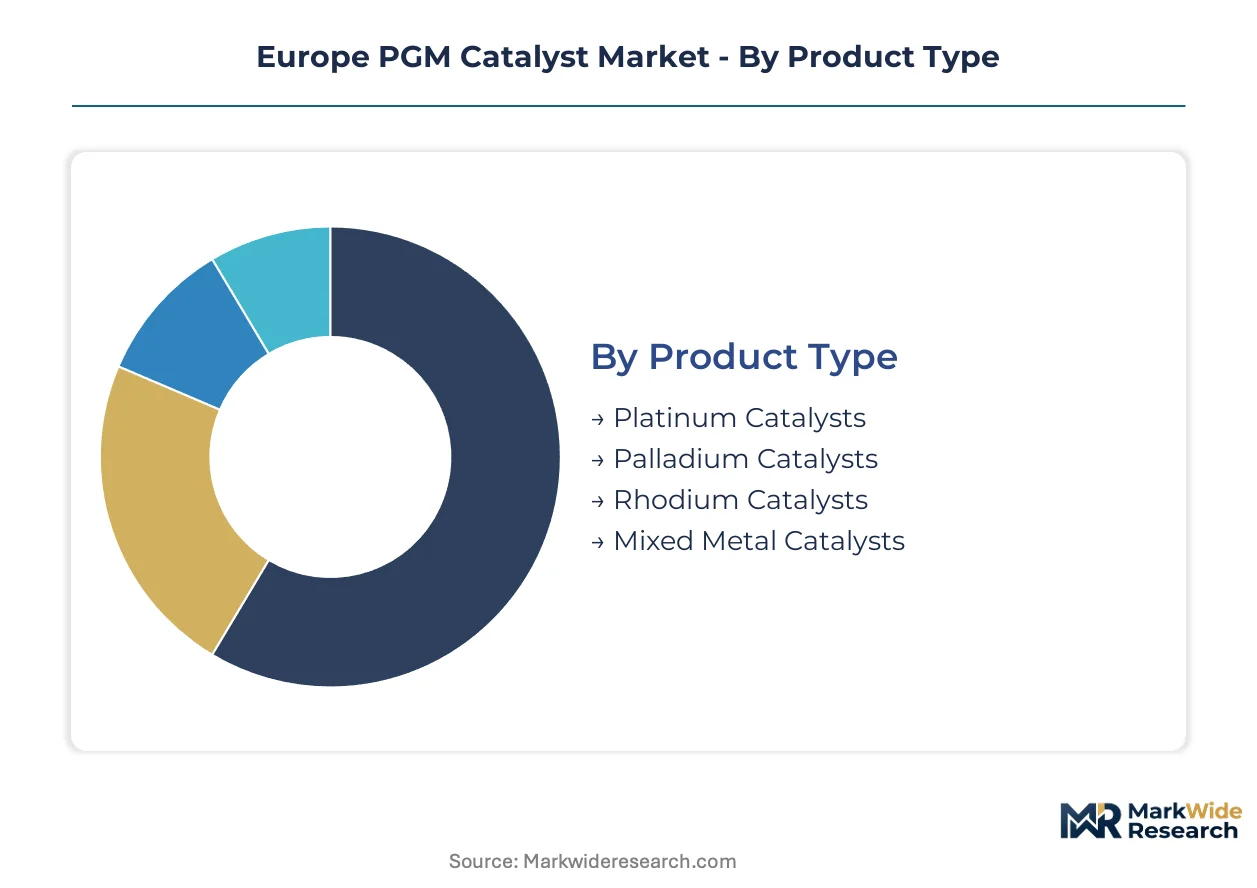
- Palladium Catalysts:These formulations dominate three-way converter applications through superior low-temperature light-off performance, with washcoat loadings concentrated in German and Czech automotive assembly corridors. Euro 7 cold-start mandates are compressing qualification timelines and forcing higher metal densities per unit.
- Mixed Metal Catalysts:Hybrid platinum-palladium-rhodium architectures enable load reduction while maintaining emission performance, attracting premium positioning from French and German OEM procurement teams. Metal price volatility accelerates adoption as automakers seek hedging flexibility through composition flexibility.
- Platinum Catalysts:Established diesel oxidation catalyst base with declining automotive demand offset by stationary fuel cell expansion in the Netherlands and Denmark.
- Rhodium Catalysts:Nitrogen oxide reduction specialist with concentrated demand in gasoline particulate filter formulations for Italian and Spanish vehicle production.
Palladium formulations anchor the volume base while mixed metal systems gain share at the steepest rate.
End User:
Customer concentration patterns split between consolidated automotive OEM procurement desks and fragmented chemical processor maintenance schedules.
- Automotive Industry:Catalytic converter procurement concentrates under single-source agreements bundling substrate supply, PGM metal management, and end-of-life recycling, with German premium manufacturers eliminating dual-source strategies. REACH compliance and Euro 7 certification compress supplier qualification windows.
- Chemical Manufacturing:Hydrogenation process catalyst demand concentrates in Belgium's Antwerp refining cluster and Germany's Rhineland corridor, with ECHA nickel and cobalt restrictions accelerating PGM substitution.
- Oil Refining:Reforming and hydrocracking catalyst replacement cycles align with refinery turnaround schedules, primarily serving Rotterdam and Mediterranean basin facilities.
- Environmental Applications:Stationary emission control and water treatment catalysts serve industrial boiler upgrades and municipal wastewater facilities across Poland and Romania.
Automotive procurement anchors the volume base while chemical manufacturing gains share at the steepest rate.
Application:
Performance specifications escalate from passive emission control toward active electrochemical energy conversion, reshaping technical competency requirements.
- Emissions Control:Three-way and diesel oxidation catalysts remain the dominant revenue pool, with washcoat architectures evolving to integrate thermal management and PGM distribution for Euro 7 compliance. Italian and French suppliers are vertically integrating refining capabilities to control metal sourcing costs.
- Fuel Cells:Proton exchange membrane electrocatalysts for hydrogen mobility represent the fastest-expanding segment as EU Green Deal funding accelerates electrolyzer deployment in Germany and the Netherlands.
- Hydrogen Production:Water electrolysis catalyst demand concentrates in Nordic and German green hydrogen project pipelines, with alkaline and PEM technologies competing for metal loading specifications.
- Bioreactors:Pharmaceutical and fine chemical synthesis applications serve specialized batch production in Swiss and Irish manufacturing facilities.
Emissions control anchors the volume base while fuel cell applications climb the fastest.
Technology:
Process intensification is blurring boundaries between heterogeneous fixed-bed systems and homogeneous dissolved-phase catalysis.
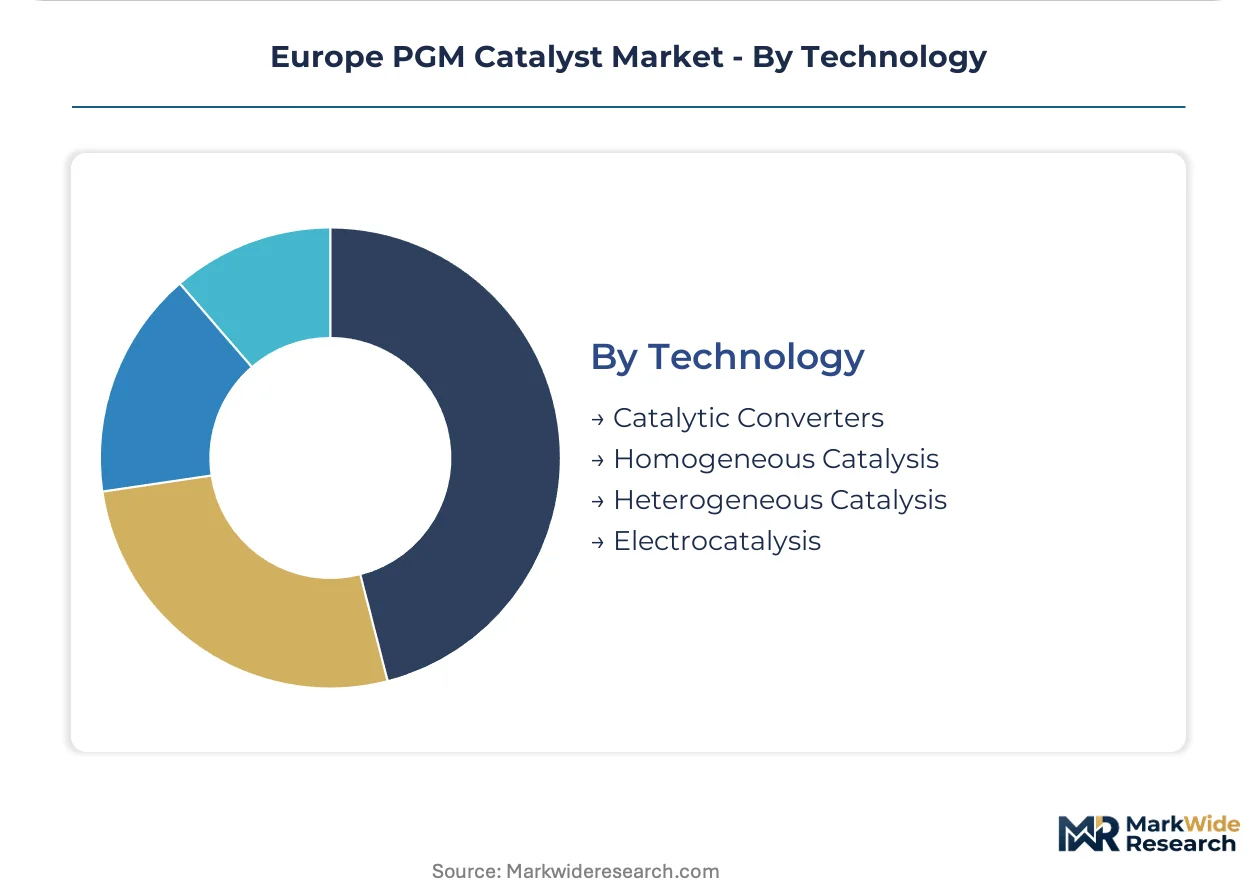
- Heterogeneous Catalysis:Solid-phase PGM dispersions on ceramic or metallic substrates dominate automotive and petrochemical applications, with surface area optimization exceeding 50 m²/g for active site exposure. German substrate manufacturers are consolidating washcoat and canning operations to compress design cycles.
- Electrocatalysis:Electrode-bound PGM nanoparticles for fuel cells and electrolyzers are expanding most quickly as EU hydrogen infrastructure funding flows toward Dutch and German project developers.
- Catalytic Converters:Integrated substrate-washcoat-canning systems serve gasoline and diesel vehicle platforms with declining differentiation between powertrain architectures.
- Homogeneous Catalysis:Dissolved PGM complexes for fine chemical synthesis serve pharmaceutical and agrochemical batch production in Swiss and Belgian facilities.
Heterogeneous systems anchor the volume base while electrocatalysis climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German refining and catalyst fabrication capacity anchors European supply security, with Rhineland chemical corridors hosting integrated PGM-to-substrate production chains that serve automotive OEMs across the continent.
Germany
Automotive OEM procurement desks in Stuttgart and Munich are consolidating catalyst supply under single-source agreements that bundle metal management with end-of-life recycling obligations. The KBA enforces Euro 7 pre-certification timelines that compress supplier qualification windows. Ludwigshafen and the broader Rhineland corridor host captive PGM refining operations that feed directly into washcoat formulation plants.
Belgium
Antwerp's petrochemical refining cluster generates steady hydrogenation catalyst replacement demand as ECHA REACH restrictions on nickel alternatives accelerate PGM substitution. The port's logistics infrastructure enables just-in-time delivery of refined metals to catalyst fabricators serving Rotterdam and Mediterranean basin facilities. Umicore's Hoboken complex anchors European closed-loop recovery capacity for spent automotive catalysts.
France
French OEM procurement teams in Paris and the Auvergne-Rhône-Alpes region are qualifying mixed-metal formulations for gasoline platforms ahead of 2027 model year launches. ANSM oversight of industrial chemical applications intersects with EU F-Gas Regulation compliance for stationary emission control systems. The Lyon-Grenoble corridor hosts specialized electrocatalysis R&D facilities targeting hydrogen mobility applications.
Italy
Italian vehicle production concentrated in Piedmont and Emilia-Romagna drives gasoline particulate filter formulations with elevated rhodium loadings for nitrogen oxide reduction. The Ministry of Economic Development channels EU Green Deal funding toward electrolyzer catalyst deployment in southern industrial zones. Milan-based chemical processors are vertically integrating PGM refining capabilities to hedge metal price volatility.
Netherlands
Rotterdam's refinery turnaround schedules align with reforming and hydrocracking catalyst replacement cycles serving Northwest European petrochemical demand. The Dutch national hydrogen strategy accelerates proton exchange membrane electrocatalyst procurement for electrolyzer projects in Groningen and Zeeland. Eindhoven's high-tech manufacturing ecosystem supports precision ceramic substrate fabrication for fuel cell applications.
Europe PGM Catalyst Market Competitive Landscape
Integrated refining-to-catalyst producers and specialized substrate fabricators split the market into distinct capability tiers, with metal sourcing control separating strategic positioning. Consolidation around Rhineland and Belgian industrial corridors has compressed the viable supplier base to operators with captive PGM processing or closed-loop recovery infrastructure. Three archetypes dominate: diversified chemical conglomerates with catalyst divisions, dedicated precious metals refiners with downstream formulation capabilities, and technology licensors with specialized washcoat IP. Competitive dynamics center on backward integration into refining assets and geographic expansion into Eastern European automotive assembly zones.
Among Germany-based chemical conglomerates, BASF SE anchors the integrated refining-to-catalyst archetype through its Ludwigshafen site operations. Johnson Matthey represents the technology-licensor model with specialized gasoline particulate filter expertise. Umicore occupies the closed-loop recovery position via its Belgian Hoboken complex. These three exemplify how metal sourcing control, formulation IP, and recycling infrastructure define competitive separation in European PGM catalyst supply.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Umicore |
| Heraeus Holding |
| Clariant |
| Evonik Industries AG |
| Topsoe A/S |
| Chimet |
| Axens |
| Others |
Pricing and Supply Chain Analysis
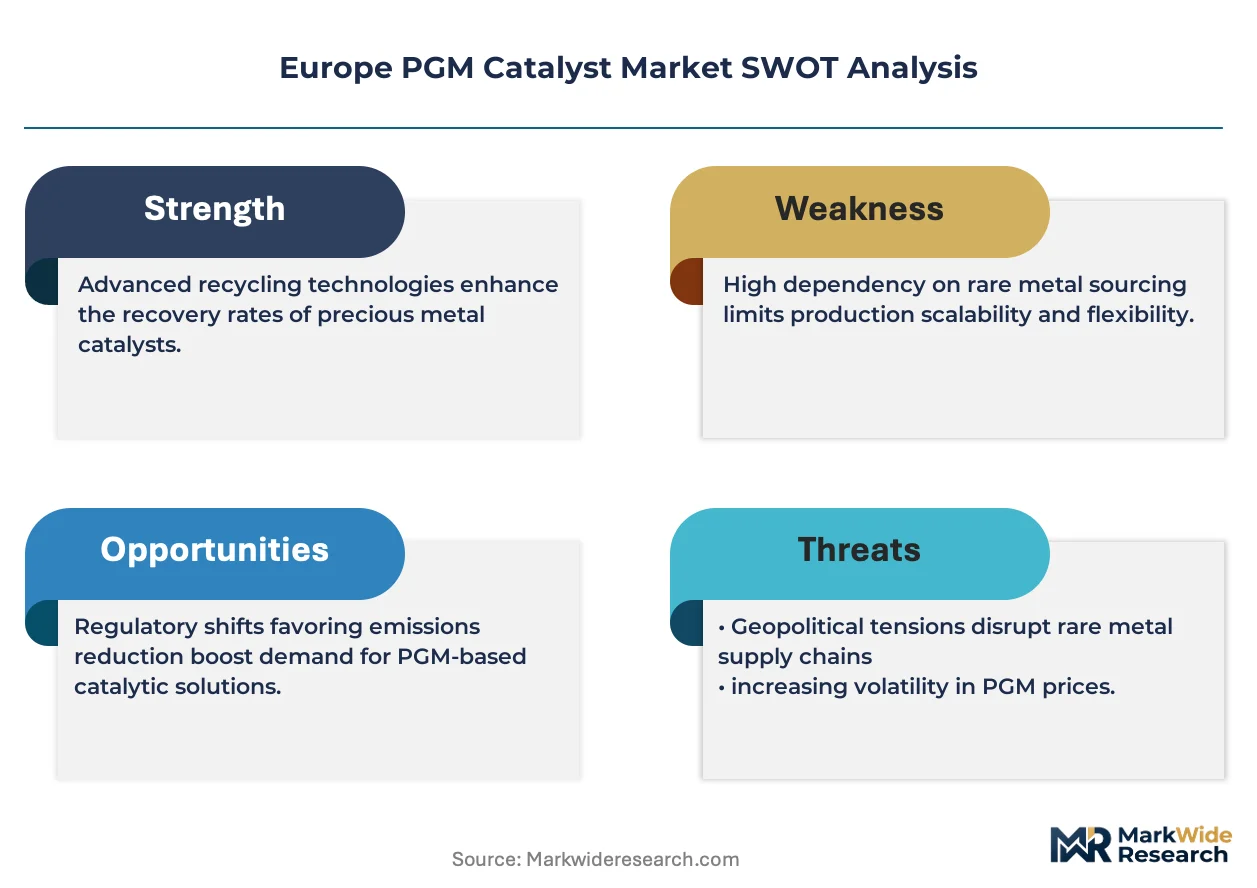
South African platinum and Russian palladium dominance concentrates upstream metal supply, pushing European catalyst fabricators to capture margin downstream through captive refining and closed-loop recovery services rather than spot market trading.
Pricing Analysis
Euro 7 mandates dictate the pricing tier structure across European PGM catalyst procurement, with cold-start emission thresholds forcing premium positioning for advanced washcoat architectures that carry higher palladium and rhodium densities. Price differentiation separates certified formulations meeting KBA pre-certification timelines from standard grades serving aftermarket replacement. Cost compression in standard-grade catalysts is intensifying because base-metal zeolite substitutes threaten palladium loadings in lean-burn gasoline segments. Chemical manufacturing procurement desks exhibit highest price sensitivity due to ECHA-driven substitution timelines, while German premium automotive OEMs absorb metal volatility through closed-loop metal management contracts.
Supply Chain Analysis
PGM concentrate feedstock draws from South Africa, Russia, and Zimbabwe, with European refining capacity concentrated in Belgium's Hoboken complex and Germany's Rhineland corridor. Ceramic substrate supply rests on cordierite and silicon carbide imports, while washcoat alumina sources from Ukrainian and Turkish bauxite processing. Single-source vulnerability runs through South African platinum output exposed to power grid instability and labor disruptions. Distribution runs through just-in-time substrate delivery networks serving automotive Tier 1 suppliers clustered along the Czech-German assembly corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe PGM Catalyst Market dynamics trace automotive production cycles, with Euro 7 implementation compressing design cycles and forcing simultaneous qualification of substrate, washcoat, and canning operations across the supply base.
For Market Incumbents: Insulate margin pools by deepening backward integration into PGM refining assets in the Rhineland corridor, capturing metal price volatility internally rather than passing exposure downstream. Secure captive supply of rhodium concentrates against gasoline particulate filter demand acceleration. Defend against base-metal zeolite substitution threats by accelerating mixed-metal formulation patents ahead of 2027 model year procurement deadlines.
For New Entrants and Emerging Players: Build out regional catalyst supply nodes in Poland and Czech Republic automotive assembly zones, where incumbent saturation in Germany creates white-space opportunity. Target electrocatalysis applications for proton exchange membrane fuel cells as the most penetrable technology segment, leveraging EU Green Deal funding visibility to anchor initial customer relationships with Dutch and German electrolyzer developers.
For Investors and Strategic Acquirers: Capital is best deployed toward closed-loop recovery specialists with Hoboken-scale refining infrastructure and automotive OEM recycling contracts, positioning for structural metal supply tightness across a multi-decade horizon. Watch ECHA substance evaluation timelines for nickel and cobalt catalyst restrictions as the inflection signal that accelerates PGM substitution demand in European hydrogenation processes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Refining | BASF's Ludwigshafen captive supply model eliminates metal price exposure and compresses catalyst design cycles. |
| Closed-Loop Recovery Infrastructure | Umicore's Hoboken complex captures stranded palladium from declining diesel applications for automotive reuse. |
| Mixed-Metal Formulation Patenting | Johnson Matthey's gasoline particulate filter IP creates defensible positioning against palladium loading reduction mandates. |
| Eastern European Supply Node Expansion | Polish and Czech automotive growth creates regional catalyst fabrication demand outside saturated German corridors. |
| Electrocatalysis R&D Partnership | French and Dutch electrolyzer developers require proton exchange membrane catalyst qualification ahead of green hydrogen deployment. |
Research Methodology
A standing panel of automotive Tier 1 procurement directors, PGM refining operations managers, ECHA regulatory affairs specialists, and chemical plant hydrogenation engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from KBA type-approval databases, EU F-Gas Regulation implementation protocols, customs trade data for PGM concentrate flows, and SEC filings from listed chemical conglomerates. Bottom-up catalyst unit demand estimates triangulated against top-down automotive production forecasts from vehicle registration databases.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation modeling spanning product type, end-user industry, application technology, and regional production cluster dimensions. CAGRs derived from metal loading intensity trajectories under Euro 7 versus Euro 6d baselines, cross-referenced against ECHA substitution timelines for nickel and cobalt catalyst alternatives. Fuel cell electrocatalyst demand incorporated EU Green Deal funding disbursement schedules and national hydrogen strategy targets.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese PGM refiners or accelerated base-metal zeolite commercialization would shift outcomes substantially. Cross-checking against ECHA substance evaluation timelines and KBA certification protocol updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Refinery Catalyst Market
Catalysts
Hydrodesulfurization Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Catalyst Regeneration Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Refining Catalysts Market
Catalysts
Global Zeolites Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Natural Zeolites Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Emission Control Catalyst for Marine Market