
 Lime Sulfur Market | 2026-2036
Lime Sulfur Market Size, Share, and Industry Trends Forecast 2026-2036
Lime Sulfur Market Analysis
REACH compliance is consolidating the European supplier base for lime sulfur formulations, raising barriers for smaller importers. Tessenderlo Kerley Inc. leverages its integrated sulfur processing network to control raw material costs across North American distribution. BASF SE anchors its position through dedicated polysulfide R&D facilities in Ludwigshafen. Syngenta AG competes by extending its biological crop protection portfolio into sulfur-based fungicide adjacencies.
Lime sulfur is an aqueous solution of calcium polysulfides, typically containing 22 to 24 percent sulfur by weight, manufactured by reacting calcium hydroxide with elemental sulfur under controlled thermal conditions. The compound functions primarily as a broad-spectrum fungicide, insecticide, and miticide in agricultural and horticultural settings. Agricultural formulations dominate volume throughput due to entrenched vineyard and orchard spraying protocols, while pharmaceutical-grade polysulfide extracts command premium positioning in dermatological applications. Liquid concentrates sustain the largest share of form factor demand, though powder variants are gaining traction in emerging market supply chains where cold-chain logistics remain underdeveloped.
The EPA regulates lime sulfur under FIFRA pesticide registration standards, requiring chronic toxicity and environmental fate studies for label retention. ECHA enforces REACH Article 33 obligations on sulfur compound importers, compelling full supply chain substance disclosure. Australia's APVMA maintains parallel registration requirements that govern access to the country's horticultural export corridors. Stakeholders must monitor pending regulatory harmonization between EPA and ECHA testing protocols, as divergent data requirements threaten to fragment formulation approval timelines and lock regional suppliers into non-transferable compliance investments.
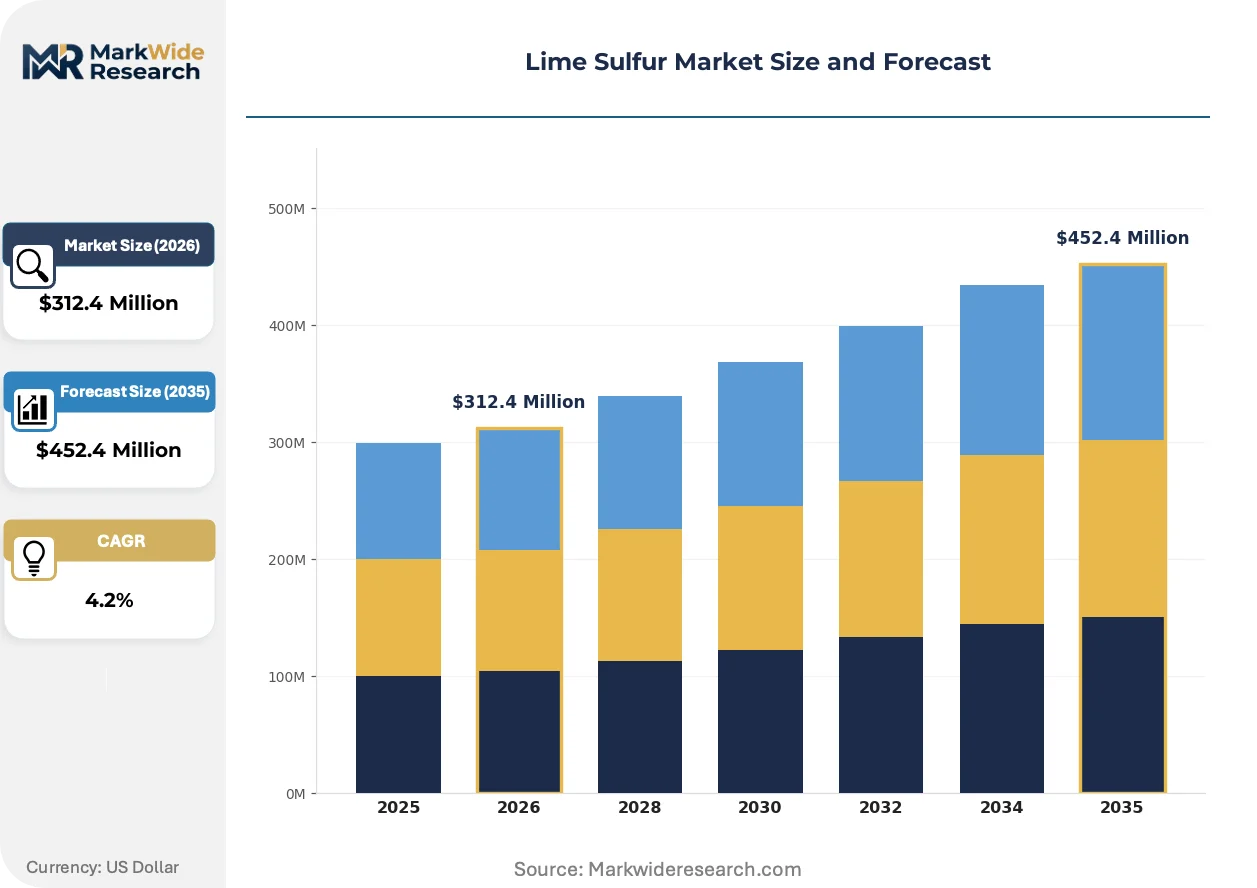
Market Dynamics
California's Central Valley specialty crop growers are driving demand concentration as organic stone fruit production expands, while EPA re-registration reviews for polysulfide fungicides tighten compliance thresholds and reshape manufacturing economics.
Growth Catalysts
- Organic certification mandates:Australia's APVMA registration requirements for export-oriented table grape and almond sectors are pulling residue-compliant lime sulfur into horticultural supply chains.
- Integrated sulfur processing networks:Captive production of calcium hydroxide and elemental sulfur feedstocks is compressing raw material cost volatility for established North American manufacturers.
- Dermatological polysulfide extraction:Pharmaceutical-grade refinement protocols are opening premium positioning channels for aqueous calcium polysulfide solutions in therapeutic applications.
Market Restraints
- Elemental sulfur price volatility:Input cost fluctuations in sulfur mining and refining operations compress formulation margin stability for regional blenders.
- REACH Article 33 disclosure burdens:ECHA substance disclosure mandates are consolidating European supplier bases and raising capital barriers for smaller importers.
- Synthetic fungicide substitution:Triazole and strobilurin chemistry advances in conventional viticulture are displacing lime sulfur in non-organic vineyard protocols.
Strategic Opportunities
- Powder formulation cold-chain bypass:Dry concentrate variants are penetrating emerging market supply chains where liquid logistics infrastructure remains underdeveloped.
- EPA-ECHA harmonization tailwinds:Pending convergence in chronic toxicity testing protocols could unlock transferable compliance investments across transatlantic registration pathways.
- Biological adjacency convergence:Sulfur-based fungicide positioning alongside microbial crop protection products is opening portfolio expansion channels for agrochemical distributors.
Industry Challenges
- Polysulfide chemistry expertise scarcity:Formulation chemists with calcium polysulfide reactor control experience are concentrated among legacy manufacturers, constraining new entrant technical staffing.
- Label retention study timelines:EPA chronic toxicity and environmental fate data requirements are extending registration maintenance cycles and freezing formulation innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lime Sulfur Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $452.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural, Industrial, Pharmaceutical, Cosmetic Application: Pesticide, Fungicide, Soil Treatment, Disinfectant Form: Liquid, Powder, Granule, Emulsion End User: Agriculture, Horticulture, Healthcare, Manufacturing |
| Companies Covered | Tessenderlo Kerley Inc., BASF SE, Syngenta AG, Nufarm Limited, UPL Limited, Miller Chemical and Fertilizer LLC, Or-Cal Inc., Biofa AG, North Country Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lime Sulfur Market Emerging Trajectories
Reactor automation and precision thermal control systems are redefining calcium polysulfide manufacturing consistency, while regulatory data harmonization efforts and shifting procurement accountability models reshape competitive positioning.
Continuous-flow reactor technology is converging with real-time sulfur dissolution monitoring to standardize polysulfide chain length distribution in agricultural formulations. Vineyard cooperatives in France's Bordeaux region are adopting these systems to reduce batch-to-batch efficacy variation. The technology is converging with legacy batch processing infrastructure, compressing quality control labor costs while raising capital intensity barriers for smaller blenders.
REACH Article 33 substance disclosure obligations are compelling full supply chain transparency for sulfur compound importers into European horticultural markets. ECHA enforcement actions against non-compliant distributors are accelerating consolidation among formulation resellers. Specialty crop input retailers in Spain and Italy are responding by vertically integrating into direct manufacturer relationships to secure auditable substance documentation.
Certification-driven procurement accountability is displacing price-primary supplier selection in export-oriented agricultural segments. Australian table grape packers are now mandating residue documentation from lime sulfur providers as a condition of contract eligibility. This behavioral shift is most visible in South Australia's Riverland region, where export certification to Chinese and Japanese phytosanitary standards governs input procurement decisions.
Lime Sulfur Market Segmentation
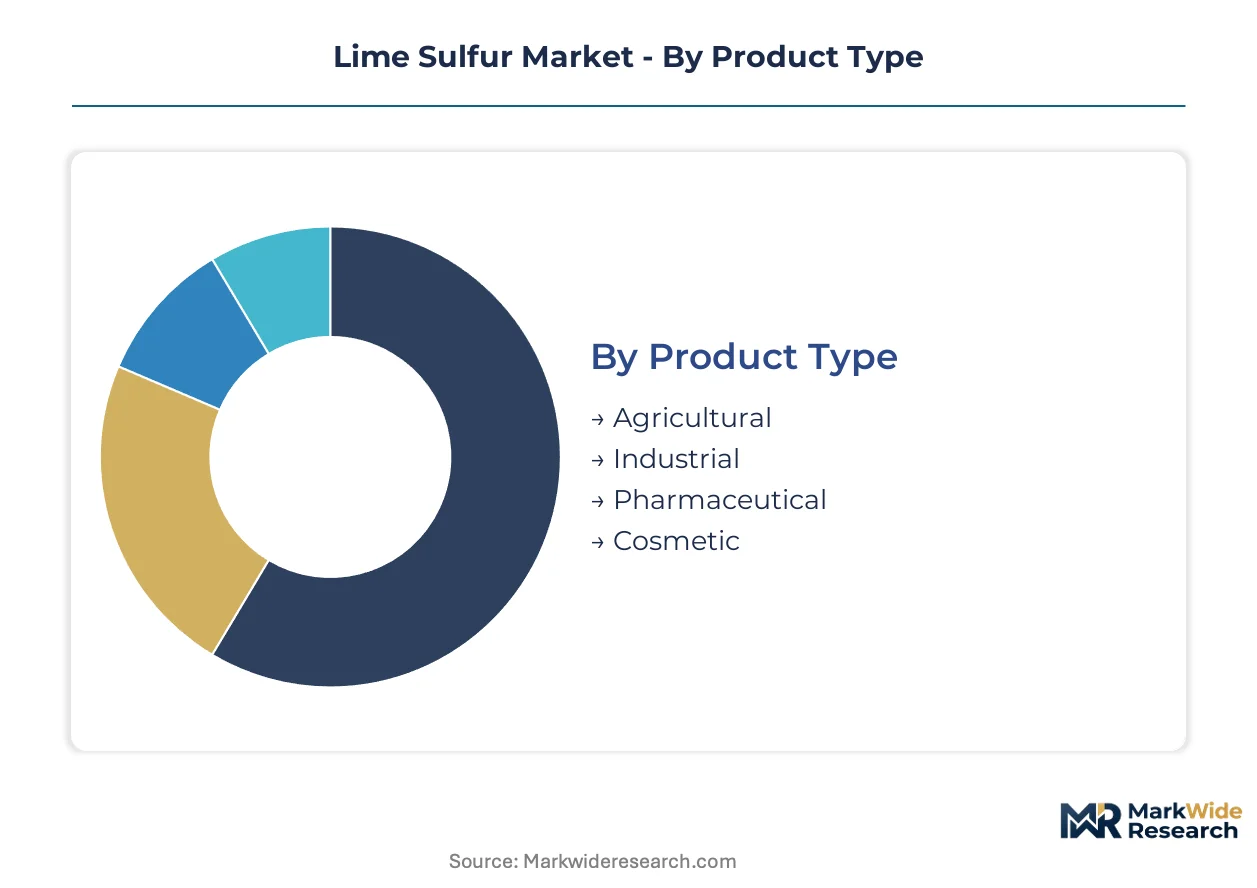
Lime sulfur segmentation reflects divergent compliance burdens across regulatory jurisdictions, with agricultural formulations facing EPA FIFRA re-registration while pharmaceutical grades navigate FDA drug master file requirements. Form factor selection directly determines cold-chain infrastructure needs and REACH Article 33 disclosure obligations.
Product Type:
Agricultural and pharmaceutical grades carry distinct certification architectures, with the former governed by EPA chronic toxicity protocols and the latter subject to FDA current good manufacturing practice standards.
- Agricultural:Formulations containing 22-24 percent sulfur by weight dominate vineyard and orchard spraying protocols across California's Central Valley. Demand concentrates in organic stone fruit production where EPA polysulfide re-registration reviews are tightening manufacturing compliance thresholds.
- Pharmaceutical:Refined calcium polysulfide extracts meeting USP monograph specifications command premium positioning in dermatological therapeutics. Australian TGA registration requirements and FDA drug master file submissions constrain supplier qualification to established chemical processors with dedicated GMP facilities.
- Industrial:Bulk polysulfide solutions serve leather tanning and ore flotation applications with reduced purity specifications.
- Cosmetic:Low-concentration sulfur preparations target topical skin care with cosmetic-grade rather than pharmaceutical-grade certification pathways.
Agricultural sits at the top of the volume ranking, with pharmaceutical climbing the fastest.
Application:
Application selection determines residue tolerance thresholds and export market access, with fungicide registrations facing stricter maximum residue limits than soil treatment formulations.
- Fungicide:Broad-spectrum calcium polysulfide solutions control powdery mildew and black spot in viticulture. France's Bordeaux vineyard cooperatives are adopting continuous-flow reactor technology to standardize batch-to-batch efficacy variation.
- Pesticide:Miticidal and insecticidal applications target dormant season orchard sprays with specific seasonal use windows.
- Soil Treatment:Pre-planting applications reduce fungal inoculum loads in Australia's Riverland table grape districts where APVMA export certification documentation governs input procurement.
- Disinfectant:Veterinary and agricultural facility sanitation uses bypass crop-specific residue testing requirements.
Fungicide captures the largest application share, with soil treatment gaining share fastest in export-oriented horticulture corridors.
Form:
Physical form selection trades logistics infrastructure requirements against dissolution consistency and shelf stability.
- Liquid:Aqueous concentrates sustain the largest share of form factor demand through established vineyard spraying infrastructure. Cold-chain requirements limit penetration in emerging market supply chains where refrigerated transport remains underdeveloped.
- Powder:Dry concentrate variants bypass liquid logistics constraints and extend shelf stability in tropical storage conditions.
- Granule:Slow-release formulations target soil incorporation applications with reduced drift potential.
- Emulsion:Oil-in-water preparations improve foliar adhesion in rainy climates with specific surfactant compatibility requirements.
Liquid maintains volume leadership, with powder expanding most quickly in logistics-constrained emerging markets.
End User:
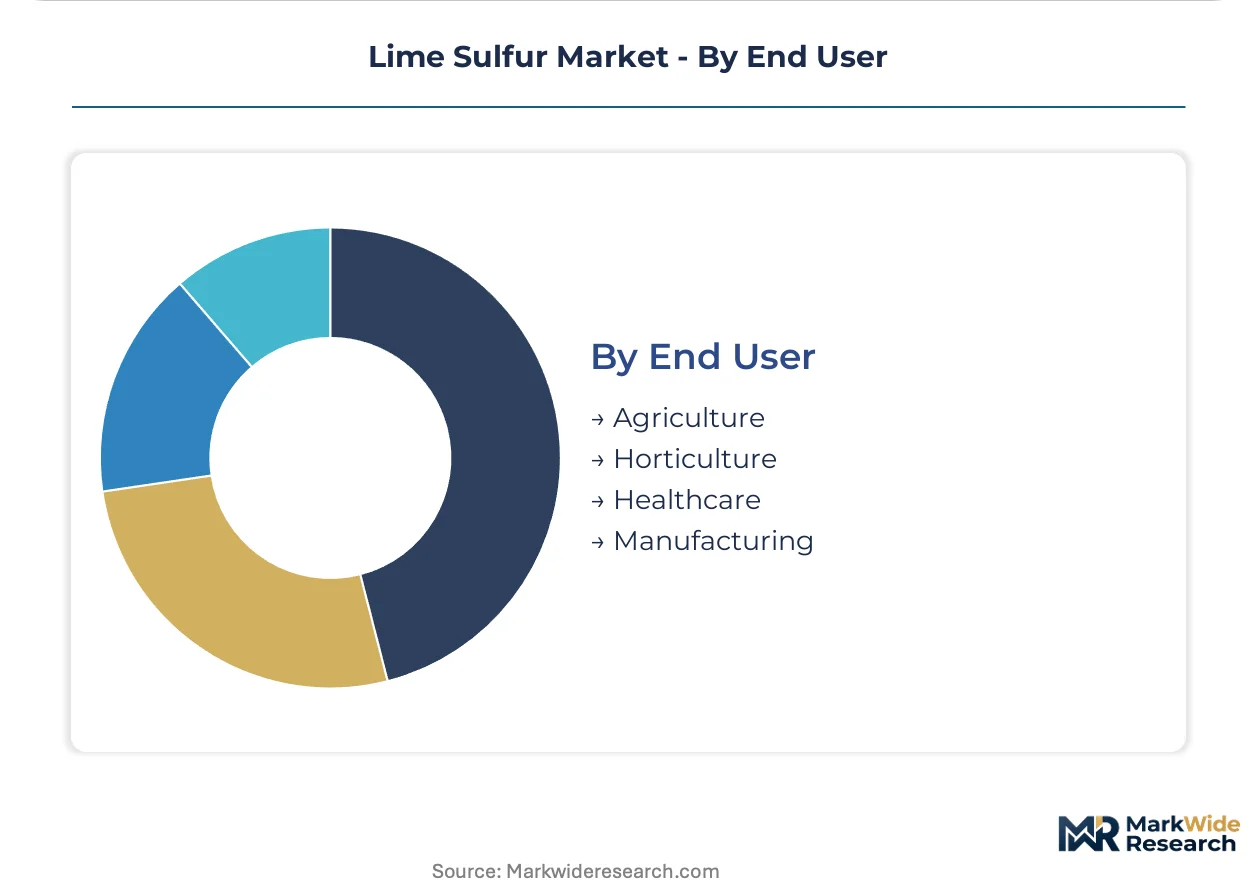
End user category determines procurement accountability intensity, with export-oriented agriculture demanding residue documentation that manufacturing and healthcare segments do not require.
- Agriculture:Large-scale vineyard and orchard operations in Australia's almond and table grape sectors mandate supplier residue documentation as a condition of export certification eligibility.
- Horticulture:Nursery and greenhouse operations favor lower-volume formulations with reduced phytotoxicity risk profiles.
- Healthcare:Dermatological applications require pharmaceutical-grade polysulfide extraction with validated manufacturing processes.
- Manufacturing:Industrial chemical processors consume bulk polysulfide feedstocks with technical-grade rather than agricultural-grade specifications.
Agriculture dominates end user volume, with healthcare showing the steepest expansion trajectory on premium therapeutic positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist formulation chemists with calcium polysulfide reactor expertise concentrate among legacy manufacturers in California, southwestern France, and South Australia's Riverland, anchoring regional production clusters to established agricultural corridors.
United States
California's Central Valley organic stone fruit expansion drives agricultural-grade lime sulfur consumption, while EPA FIFRA re-registration reviews tighten chronic toxicity compliance thresholds. Fresno County vineyard cooperatives and Kern County almond operations mandate residue documentation for export certification eligibility.
France
Bordeaux vineyard cooperatives adopt continuous-flow reactor technology to standardize polysulfide chain length distribution and reduce batch-to-batch efficacy variation. ECHA REACH Article 33 enforcement actions accelerate consolidation among formulation resellers serving French viticulture.
Australia
Riverland table grape packers and Sunraysia almond processors require APVMA-registered lime sulfur with full residue documentation for Chinese and Japanese phytosanitary compliance. South Australia's export-oriented horticulture corridors concentrate procurement accountability among certified suppliers.
Germany
BASF SE's Ludwigshafen polysulfide R&D facilities anchor pharmaceutical-grade calcium polysulfide extraction for dermatological applications. ECHA substance disclosure mandates raise capital barriers for smaller importers serving German specialty crop retailers.
Spain
Valencia citrus cooperatives and Catalonia vineyard associations integrate lime sulfur into integrated pest management protocols for EU export certification. Spanish specialty crop input retailers vertically integrate into direct manufacturer relationships to secure auditable REACH documentation.
Lime Sulfur Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Integrated agrochemical majors leverage captive sulfur processing networks to compress raw material cost volatility, while regional blenders concentrate on formulation flexibility and local registration maintenance. Three archetypes dominate: vertically integrated chemical majors with in-house sulfur feedstock production, specialized agricultural input distributors with deep vineyard and orchard relationships, and pharmaceutical-grade refiners serving dermatological therapeutic channels. Competitive intensity centers on backward integration into elemental sulfur supply and regulatory data package accumulation for label retention.
Among North American integrated processors, Tessenderlo Kerley Inc. exemplifies the captive feedstock archetype through sulfur processing network control. BASF SE anchors the diversified chemical major tier with dedicated polysulfide research infrastructure. Syngenta AG occupies a position bridging conventional crop protection and sulfur-based fungicide adjacencies within biological portfolio expansion strategies.
| Leading Market Players |
|---|
| Tessenderlo Kerley Inc. |
| BASF SE |
| Syngenta AG |
| Nufarm Limited |
| UPL Limited |
| Miller Chemical and Fertilizer LLC |
| Or-Cal Inc. |
| Biofa AG |
| North Country Organics |
| Others |
Supply Flow & Price Mechanics
APVMA residue documentation mandates in Australia gate both qualified supply and premium-tier pricing access, compelling export-oriented table grape packers to pay certification premiums while freezing out undocumented blenders from contract eligibility.
Pricing Analysis
Technical support bundling versus unbundled commodity supply splits the pricing architecture across agricultural lime sulfur procurement. Three-tier pricing structure across pharmaceutical-grade, certified agricultural, and technical-grade industrial levels reflects purity variance and registration maintenance costs. Pricing pressure stems from elemental sulfur feedstock volatility compressing blender margins in liquid concentrate segments. Export certification-driven buyers in Australia's Riverland show lowest price sensitivity, while emerging market powder distributors face acute cost compression.
Supply Chain Analysis
Freight cost differentials between liquid refrigerated tankers and dry container shipping determine form factor penetration across logistics-constrained corridors. Manufacturing concentrates in the United States, France, and Australia where vineyard cooperatives and almond processors anchor regional production clusters. Elemental sulfur, calcium hydroxide, and reactor-grade thermal energy feed production economics. Single-source vulnerability concentrates in Australian APVMA-registered suppliers serving Chinese and Japanese phytosanitary export channels. Distribution runs through agricultural input retailers with direct manufacturer relationships securing auditable REACH documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lime sulfur market compounds steadily as organic certification mandates in export horticulture generate durable, regulation-locked demand with limited synthetic substitution pathways.
For Market Incumbents: Lock in backward integration into elemental sulfur processing to neutralize feedstock volatility threatening formulation margins. Secure APVMA and EPA label retention through accelerated chronic toxicity data submission, preempting registration maintenance cycles that freeze innovation pipelines. Tessenderlo Kerley's captive sulfur network exemplifies the cost-control archetype. For New Entrants and Emerging Players: EPA-ECHA harmonization efforts in chronic toxicity testing protocols open a window for transferable compliance investments across transatlantic registration pathways. Target powder formulation supply to emerging market distributors bypassing cold-chain infrastructure gaps. Lead with residue documentation capabilities to penetrate Australian table grape and almond export corridors where procurement accountability now dominates supplier selection. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with established vineyard relationships because certification-driven procurement consolidation favors scaled documentation capabilities over fragmented local suppliers. Five-to-ten-year viability hinges on regulatory data package accumulation rather than manufacturing scale. Watch EPA FIFRA re-registration timelines as inflection indicators for formulation approval bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstock | Tessenderlo Kerley's captive supply network compresses raw material cost volatility for North American agricultural formulations. |
| Continuous-Flow Reactor Technology Deployment | Bordeaux vineyard cooperatives reduce batch-to-batch efficacy variation through precision thermal control standardization. |
| APVMA Registration Data Package Accumulation | Riverland table grape packers mandate residue documentation from certified suppliers accessing Chinese phytosanitary export channels. |
| Powder Formulation Cold-Chain Bypass | Dry concentrate variants penetrate logistics-constrained emerging markets where refrigerated liquid transport remains underdeveloped. |
| REACH Article 33 Supply Chain Transparency | Spanish specialty crop retailers vertically integrate into direct manufacturer relationships securing auditable substance documentation. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with formulation chemists, agricultural input distributors, vineyard cooperative procurement managers, and regulatory affairs specialists at EPA and ECHA with secondary validation from APVMA registration databases, customs trade flows, and SEC filings of diversified chemical majors. Bottom-up volume triangulation across agricultural, pharmaceutical, and industrial grade segments converges with top-down market sizing.
Rate-of-change decomposition isolates volume drivers from price effects across the projection horizon. Segmentation dimensions modeled include product grade tier, application protocol, physical form factor, and end-user procurement accountability intensity. CAGRs derive from regression against historical vineyard and orchard acreage expansion, organic certification adoption curves, and regulatory registration maintenance timelines. Industry-specific inputs incorporate elemental sulfur price index movements and EPA FIFRA re-registration schedule assumptions.
Revisions become necessary when EPA-ECHA testing protocol harmonization stalls, elemental sulfur supply disruptions materialize, or synthetic fungicide substitution accelerates in conventional viticulture. Forecasts reflect documented assumptions about registration timeline continuity and export certification demand persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Ammonia Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
South Korea Methanol Market
Chemicals
Fluorine Derivatives Market
Chemicals
N-Propanol Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Laboratory Chemicals Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market