
 Petrochemical Catalyst Market | 2026-2036
Petrochemical Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Petrochemical Catalyst Market Analytics
High-activity zeolite formulations is rotating demand toward premium catalyst tiers that deliver higher gasoline yields and lower coke deposition. BASF SE leverages its integrated catalyst and adsorbent portfolio to anchor long-term supply contracts with Middle Eastern refiners. Albemarle Corporation sustains its hydroprocessing leadership through proprietary metal-on-support technologies. Clariant AG specializes in custom FCC additive packages that compete on resid-processing intensity.
Petrochemical catalysts are heterogeneous or homogeneous substances that accelerate hydrocarbon conversion reactions without permanent chemical alteration, typically comprising zeolite frameworks, supported noble metals, or mixed-metal oxides with pore sizes engineered for selective molecular access. Their primary purpose is to maximize yield of high-value products—ethylene, propylene, aromatics, clean fuels—while minimizing energy input and byproduct formation. Zeolite-based technologies dominate volume demand due to their thermal stability and shape-selective cracking behavior, while metal-based systems capture premium pricing in hydrocracking and hydrotreating applications where sulfur and nitrogen removal specifications tighten. Polymer producers represent a fast-growing end-user channel as on-purpose propylene and metallocene polyethylene capacity expands.
EPA fuel sulfur regulations and the EU F-Gas Regulation are forcing refiners to replace legacy catalyst systems with higher-activity alternatives that achieve deeper desulfurization and lower process emissions. China's MEE enforces national VI fuel standards that require upgraded reforming and alkylation catalysts across its teapot and state-run refinery base. Stakeholders must monitor how carbon-border adjustment mechanisms and clean hydrogen mandates reshape catalyst refresh cycles and technology selection criteria.
Market Dynamics
Refinery FCC unit upgrades to heavier crude slates are compressing catalyst refresh cycles and tilting formulation demand toward resid-processing intensification, while REACH and EPA emissions rules harden performance thresholds for sulfur and nitrogen oxide reduction.
Growth Catalysts
- EPA Tier 3 sulfur standards:US refiners must achieve 10 ppm gasoline sulfur limits, forcing wholesale replacement of legacy hydrotreating catalysts with higher-activity metal-on-support systems.
- China's teapot refinery expansion:Private processors in Shandong and Jiangsu provinces are commissioning world-scale ethylene complexes that quadruple FCC additive consumption per barrel.
- Zeolite framework engineering:Advances in mesoporous Y-zeolite architectures enable deeper cracking of vacuum resid without coking penalties, extending catalyst life in high-severity operations.
Market Restraints
- Rare earth supply concentration:Lanthanum and cerium inputs for FCC catalysts source predominantly from Chinese separation facilities, exposing formulators to export quota volatility.
- Hydroprocessing catalyst technical ceiling:Current nickel-molybdenum formulations approach diffusion limits for ultra-deep desulfurization of refractory sulfur species in coker naphtha.
- REACH authorization delays:ECHA substance evaluation timelines for cobalt and nickel compounds extend catalyst registration costs by 18-24 months for European suppliers.
Strategic Opportunities
- India's petrochemical buildout:Reliance Industries and Indian Oil are expanding on-purpose propylene capacity, creating fresh demand for metallocene and Ziegler-Natta polymerization catalysts.
- Clean hydrogen mandates:EU Green Deal hydrogen targets incentivize refinery hydrogen production units, requiring new reforming catalyst formulations with enhanced carbon resistance.
- Digital catalyst monitoring:Integration of inline spectroscopy with machine learning enables predictive regeneration scheduling, opening performance-based service contracts.
Industry Challenges
- Specialized materials science talent scarcity:Formulation chemists with expertise in hierarchical zeolite synthesis command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Legacy refinery catalyst retrofit complexity:Drop-in replacement of fixed-bed hydrotreating systems requires reactor internals modification, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petrochemical Catalyst Market |
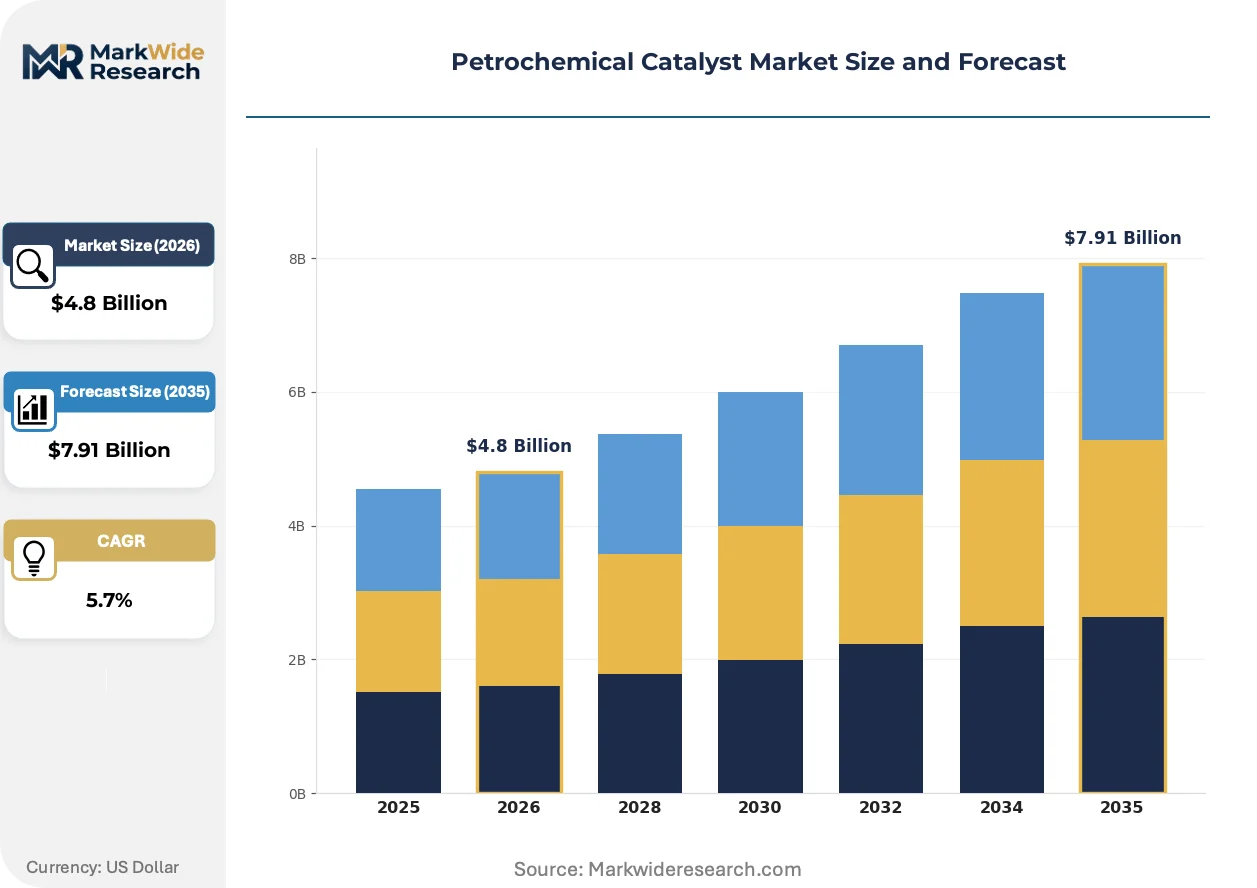
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid Catalytic Cracking, Hydrocracking, Reforming, Alkylation Technology: Zeolite-Based, Metal-Based, Organometallic, Biocatalysts Application: Polyethylene Production, Methanol Production, Benzene Derivatives, Diesel Hydrotreating End User: Refineries, Chemical Manufacturers, Petrochemical Plants, Polymer Producers |
| Companies Covered | BASF SE, Albemarle Corporation, Honeywell International Inc, Exxon Mobil Corporation, Chevron Phillips Chemical Company, Clariant AG, Johnson Matthey, W. R. Grace & Co., Axens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petrochemical Catalyst Market Evolving Landscape
Formulation science and regulatory compliance are compressing product lifecycles while opening premium tiers for catalyst systems that deliver measurable emissions reductions and yield improvements.
Single-site metallocene catalyst technology is bifurcating polyethylene production into narrow-molecular-weight specialty grades and commodity linear low-density segments. Polymer producers in the US Gulf Coast and Middle Eastern export hubs are adopting these systems at accelerated pace for differentiated packaging films. The technology is bifurcating competitive positioning between integrated majors with captive catalyst production and merchant suppliers dependent on licensing arrangements.
EU F-Gas Regulation phase-down schedules are forcing refrigerant producers to abandon hydrofluorocarbon feedstocks, redirecting fluorocarbon catalyst demand toward hydrofluoroolefin synthesis pathways. This regulatory compression affects chlor-alkali and fluoropolymer catalyst suppliers most acutely in German and Belgian chemical clusters. Affected segments are responding by accelerating pilot trials of solid-acid fluorination catalysts that eliminate pre-chlorination steps.
Refinery procurement departments are consolidating catalyst supply agreements under multi-year performance contracts that tie pricing to measurable unit yield improvements and emissions reductions. This contractual evolution displaces traditional spot purchasing through merchant distributors in North American and European markets. The shift is most visible among independent refiners in the US Midwest seeking to lock in FCC additive supply amid volatile rare earth pricing.
Petrochemical Catalyst Market Segmentation
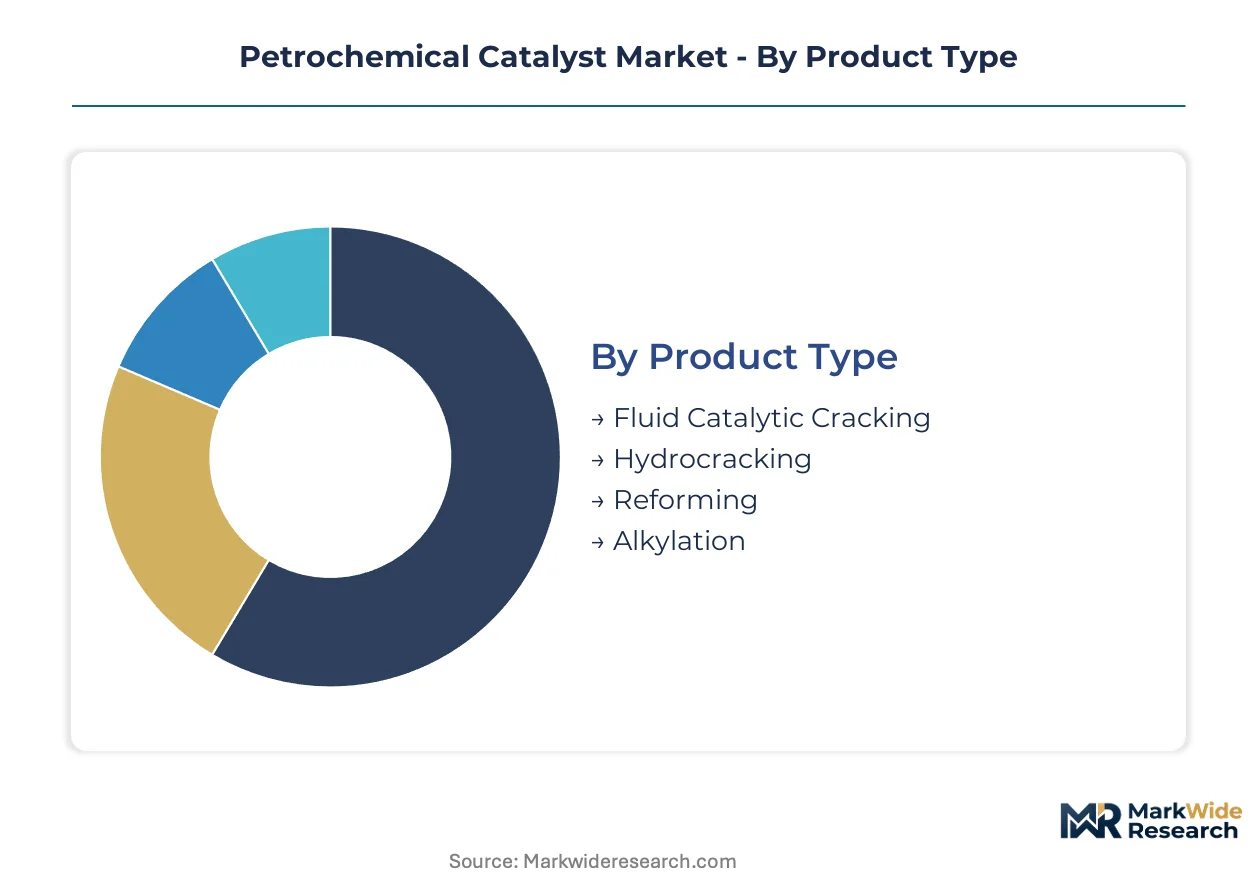
Petrochemical catalyst segmentation reveals distinct margin architectures across formulation technologies and downstream applications. Understanding these stratifications enables suppliers to prioritize R&D investment and align production capacity with the highest-value conversion chemistry.
Product Type:
Margin pools concentrate in resid-processing intensification and ultra-low sulfur fuel pathways, where catalyst refresh cycles compress and performance premiums widen.
- Fluid Catalytic Cracking:Zeolite frameworks with rare earth stabilization dominate volume consumption. China's teapot refiners in Shandong province are expanding FCC additive intensity per barrel to process heavier vacuum resid feedstocks.
- Hydrocracking:Nickel-molybdenum on alumina supports command the steepest pricing tiers due to diffusion-limited desulfurization demands. US Gulf Coast refiners facing EPA Tier 3 mandates are replacing legacy systems with higher-activity metal-on-support alternatives.
- Reforming:Bifunctional platinum-rhenium catalysts enable aromatics production and hydrogen co-generation. European reforming units under EU Green Deal hydrogen targets require enhanced carbon-resistant formulations.
- Alkylation:Solid acid catalysts are displacing liquid acid systems for iso-octane production. Alkylation catalyst demand is climbing fastest in India where Reliance Industries expands clean gasoline capacity.
Fluid Catalytic Cracking holds installed capacity. Alkylation is rotating up the share rankings.
Technology:
Technology selection determines raw material exposure and manufacturing scale economies, with metal-based systems capturing premium pricing against zeolite commodity volumes.
- Zeolite-Based:Mesoporous Y-zeolite architectures enable shape-selective cracking with thermal stability above 700°C. Formulation chemists with hierarchical synthesis expertise command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Metal-Based:Supported noble metals and base metal sulfides dominate hydroprocessing applications. REACH authorization delays for cobalt and nickel compounds extend European registration timelines by 18-24 months.
- Organometallic:Single-site metallocene systems enable narrow-molecular-weight polyethylene grades. US Gulf Coast polymer producers are adopting these for differentiated packaging film applications.
- Biocatalysts:Enzymatic conversion pathways for bio-based feedstock processing remain pre-commercial. Biocatalyst development concentrates in German and Belgian chemical clusters responding to EU F-Gas Regulation phase-down schedules.
Zeolite-Based technology anchors current production. Organometallic is gaining share fastest among specialty polymerization applications.
Application:
Application-level margins diverge between commodity olefin production and specification-driven clean fuel pathways.
- Polyethylene Production:Ziegler-Natta and metallocene catalysts compete across linear low-density and high-density segments. On-purpose propylene expansion in India and the Middle East is rotating demand toward co-product flexible systems.
- Diesel Hydrotreating:Deep desulfurization to 10 ppm sulfur limits drives highest-activity catalyst consumption. US Midwest independent refiners are consolidating supply agreements under multi-year performance contracts.
- Methanol Production:Copper-zinc oxide-alumina catalysts enable syngas conversion to methanol for olefin feedstock. Methanol-to-olefins complexes in China represent concentrated demand clusters.
- Benzene Derivatives:Cyclohexane oxidation and cumene production catalysts serve nylon and phenol value chains. Benzene derivative catalyst demand tracks aromatics complex expansion in South Korea and Saudi Arabia.
Diesel Hydrotreating commands pricing premiums. Polyethylene Production is climbing fastest on metallocene technology diffusion.
End User:
End-user procurement patterns separate integrated majors with captive catalyst production from merchant-dependent processors.
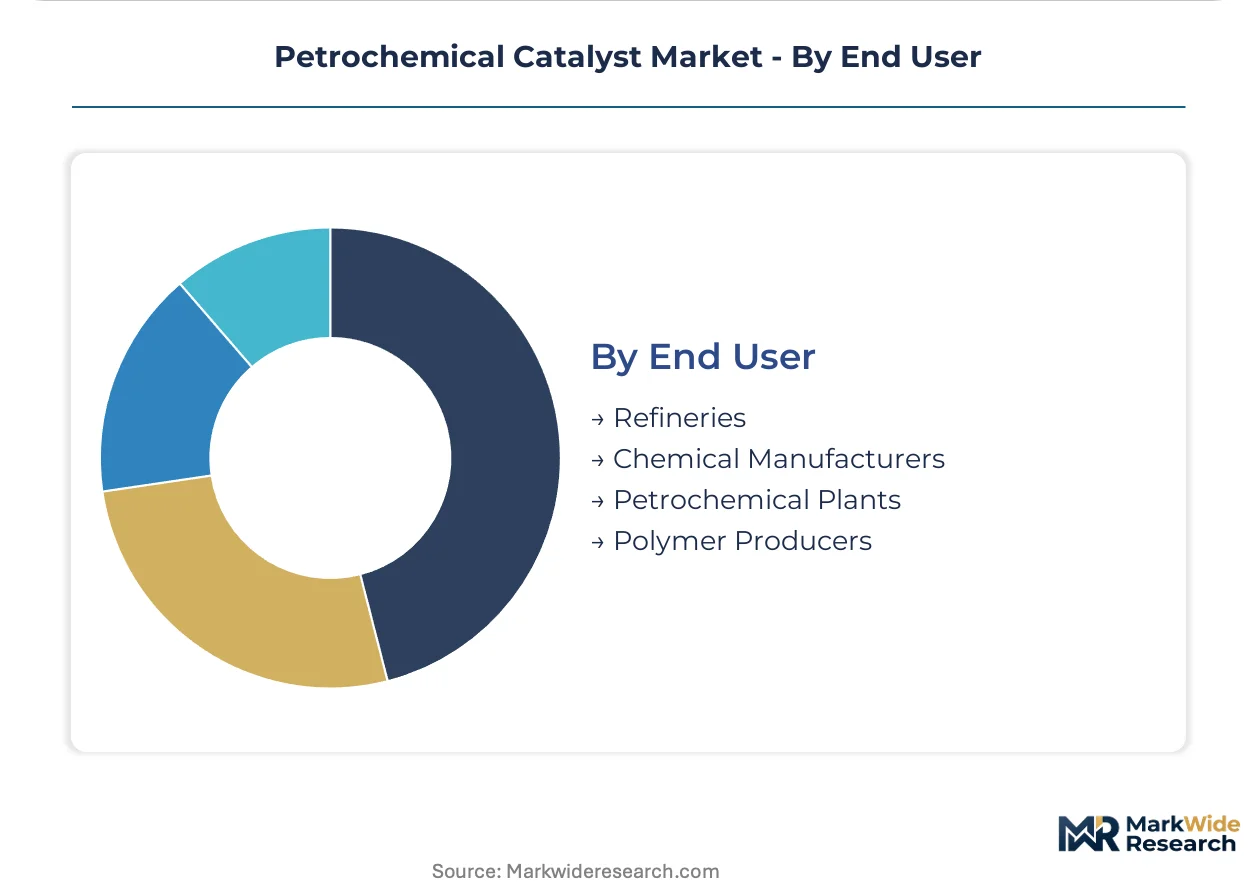
- Refineries:FCC unit upgrades to heavier crude slates compress catalyst refresh cycles. Refinery procurement departments are displacing spot purchasing with yield-tied performance contracts.
- Polymer Producers:Metallocene polyethylene and on-purpose propylene capacity expansion creates fastest-growing catalyst demand channel. Polymer producers require specialized technical service support for catalyst changeout optimization.
- Chemical Manufacturers:Methanol, ammonia, and specialty chemical synthesis drive steady-state catalyst consumption. Chemical manufacturers prioritize catalyst life extension through predictive regeneration scheduling.
- Petrochemical Plants:Integrated olefin-aromatics complexes require coordinated catalyst management across multiple conversion units. Petrochemical plant operators in China's coastal provinces are building world-scale ethylene complexes.
Refineries maintain installed demand base. Polymer Producers is expanding most quickly on differentiated polyethylene capacity buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in petrochemical catalysts tilt toward net-importing regions with expanding downstream capacity. Catalyst formulators concentrate manufacturing in Germany, the United States, and Japan while shipping into China, India, and the Middle East where refinery and polymer investments outpace domestic supply capabilities.
China
Sinopec and private teapot refiners in Shandong province are commissioning world-scale ethylene complexes that quadruple FCC additive consumption per barrel. The Ministry of Ecology and Environment enforces National VI fuel standards requiring upgraded reforming and alkylation catalysts across the state-run and private refinery base. The Yangtze River Delta chemical cluster around Shanghai hosts the country's densest concentration of methanol-to-olefins complexes driving zeolite catalyst demand.
United States
US Gulf Coast refiners facing EPA Tier 3 mandates are replacing legacy hydrotreating catalysts with higher-activity metal-on-support systems to achieve 10 ppm gasoline sulfur limits. The Inflation Reduction Act's clean hydrogen production tax credits incentivize refinery hydrogen unit expansions requiring carbon-resistant reforming catalysts. The Houston Ship Channel petrochemical corridor represents the hemisphere's largest concentration of polyethylene producers adopting metallocene catalyst systems.
Germany
REACH authorization delays for cobalt and nickel compounds extend catalyst registration costs by 18-24 months for European suppliers serving the country's specialty chemical sector. The EU F-Gas Regulation phase-down schedules force fluorocarbon catalyst suppliers in German chemical clusters to redirect toward hydrofluoroolefin synthesis pathways. The BASF Ludwigshafen Verbund site anchors integrated catalyst and adsorbent production for export into Middle Eastern and Asian markets.
India
Reliance Industries and Indian Oil are expanding on-purpose propylene capacity creating fresh demand for metallocene and Ziegler-Natta polymerization catalysts. The Bureau of Indian Standards is tightening fuel quality specifications that will require hydrotreating catalyst upgrades across the country's refining sector. The Gujarat chemical belt around Vadodara and Dahej hosts India's fastest-growing concentration of polymer production facilities importing specialty catalyst systems.
Saudi Arabia
SABIC and downstream joint ventures are building integrated olefin-aromatics complexes requiring coordinated catalyst management across multiple conversion units. The Saudi Food and Drug Authority and national environmental regulators are adopting EU-aligned chemical registration frameworks that will affect catalyst import compliance timelines. The Jubail Industrial City on the Persian Gulf represents the Middle East's largest single-site concentration of petrochemical catalyst consumption.
Petrochemical Catalyst Market Competitive Landscape
Concentration sits with integrated chemical majors possessing captive zeolite synthesis and metal-on-support manufacturing capabilities. The vendor base stratifies into three tiers: global diversified conglomerates with full catalyst portfolios, regional specialists in FCC additives or hydroprocessing systems, and technology licensors monetizing proprietary metallocene or single-site polymerization systems. Dominant competitive moves include backward integration into rare earth separation facilities and multi-year performance contracting that displaces spot purchasing.
Within the integrated chemical major tier, BASF SE and Albemarle Corporation exemplify formulators with captive raw material positions and long-term supply anchoring. Clariant AG occupies a specialist position in custom FCC additive packages competing on resid-processing intensity. These three entities represent the competitive archetypes shaping procurement patterns: diversified conglomerates leveraging portfolio breadth, metal-on-support specialists defending hydroprocessing leadership, and additive-focused players competing on formulation customization.
| Leading Market Players |
|---|
| BASF SE |
| Albemarle Corporation |
| Honeywell International Inc |
| Exxon Mobil Corporation |
| Chevron Phillips Chemical Company |
| Clariant AG |
| Johnson Matthey |
| W. R. Grace & Co. |
| Axens |
| Others |
Value Network & Pricing Analysis
Rare earth substitution in FCC zeolite stabilization is pulling lanthanum sourcing away from Chinese separation facilities toward alternative rare earth processors in Australia and the United States, simultaneously fragmenting supply geography and compressing formulation economics for catalyst producers facing export quota volatility.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on catalyst activity grade and rare earth loading intensity. Price differentiation hinges on certification tier for REACH-compliant metal-on-support systems and volume scale commitments from integrated refinery operators. Cost compression in standard-grade zeolite formulations is intensifying because teapot refiners in Shandong province are consolidating procurement under yield-tied performance contracts. Polymer producers adopting single-site metallocene systems exhibit lowest price sensitivity due to captive technical service requirements, while independent Midwest refiners remain most price-sensitive amid volatile rare earth oxide pricing.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane are extending catalyst additive delivery timelines to German chemical clusters and compressing inventory buffers at formulation facilities. Manufacturing concentrates in Germany, the United States, and Japan, with raw material sourcing drawing from Chinese rare earth separation facilities, South Korean alumina support producers, and Belgian chlor-alkali operations. Single-source vulnerability concentrates in lanthanum and cerium oxide supply from Chinese export quotas. Distribution runs through integrated chemical majors with captive synthesis capabilities and long-term supply anchoring to Middle Eastern and Asian refinery complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petrochemical catalyst market sits in an early-cycle expansion phase where EPA Tier 3 mandates and China's National VI fuel standards are accelerating replacement demand for higher-activity systems across the installed refinery base.
For Market Incumbents: Shield formulation margins by securing captive rare earth oxide supply through backward integration into Australian or North American separation facilities. Deepen technical service capabilities for polymer producers adopting metallocene systems to lock in multi-year performance contracts before merchant suppliers capture share.
For New Entrants and Emerging Players: Differentiate on solid-acid alkylation catalyst technology for India's expanding clean gasoline capacity where Reliance Industries and Indian Oil are commissioning new units. Target the Gujarat chemical belt with localized technical service support for Ziegler-Natta polymerization catalyst changeout optimization.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors mid-tier formulators with hierarchical zeolite synthesis expertise and established REACH registration pathways. Acquisition candidates with proprietary mesoporous Y-zeolite architectures and existing supply relationships with Middle Eastern integrated complexes offer strongest long-term viability. Watch for inflection in EU carbon-border adjustment mechanism implementation timelines that would accelerate catalyst refresh cycles in European refinery operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | Captive lanthanum supply shields BASF and Albemarle from Chinese export quota volatility. |
| Long-term Performance Contracting | Yield-tied agreements with US Midwest independents displace spot purchasing through merchant distributors. |
| Green Manufacturing Transition | Solid-acid fluorination catalysts eliminate pre-chlorination steps for EU F-Gas Regulation compliance. |
| Joint Venture with Polymer Producers | Metallocene technology licensing to US Gulf Coast producers captures specialty polyethylene margin pools. |
| Capacity Expansion in India | Localized Ziegler-Natta production serves Reliance Industries' on-purpose propylene buildout. |
Research Methodology
The analysis maps FCC additive, hydroprocessing catalyst, and polymerization catalyst sub-sectors, each validated through technical R&D directors at formulation facilities, procurement leads at integrated refineries, and plant managers at polymer production complexes. Primary interviews with distribution channel partners and aftermarket service heads combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators across the analysis window.
Outputs were cross-checked against external benchmarks including refinery catalyst consumption intensity metrics and polymer production capacity utilization data. Segmentation modeling incorporated formulation technology, end-use industry, regional production hub, and catalyst activity grade tiers. CAGRs were derived from regression analysis of historical refresh cycle compression and forward projection of regulatory mandate implementation timelines, with specific inputs from EPA compliance deadlines and China's MEE enforcement schedules.
The analysis sits within stated boundaries; outcomes outside sustained refinery utilization rates and stable rare earth oxide pricing would require recalibration. Forecasts reflect assumptions regarding regulatory implementation pace, technology substitution rates, and supply chain disruption frequency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Industrial Catalytic Converters Market
Catalysts
Global Zeolites Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Catalyst Handling Services Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Inorganic Catalyst Market