
 Industrial Catalytic Converters Market | 2026-2036
Industrial Catalytic Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Catalytic Converters Market Analysis
Palladium is expanding its share in gasoline catalyst formulations as platinum retreats from light-duty applications. Johnson Matthey PLC leverages its integrated precious-metal refining to sustain cost advantages across European supply chains. BASF SE anchors its position through membrane-coated catalyst manufacturing at scale in Ludwigshafen. Umicore competes on closed-loop recycling, recovering platinum-group metals from spent industrial units.
Industrial catalytic converters are emission-control devices housing ceramic or metallic substrates coated with platinum-group metals and zeolite promoters, designed to facilitate redox reactions at exhaust temperatures. They abate nitrogen oxides, carbon monoxide, and unburned hydrocarbons from stationary engines, turbines, and process heaters. Diesel oxidation catalyst systems lead the product-type landscape due to entrenched marine and construction equipment fleets, while selective catalytic reduction technology captures expanding share in power generation retrofit cycles. The manufacturing end-user segment concentrates margin pools where long-term service contracts bundle catalyst replacement with remote monitoring.
EPA New Source Performance Standards and EU F-Gas Regulation tighten allowable NOx thresholds for stationary sources, compelling fleet operators to upgrade from oxidation-only to three-way or SCR configurations. China's MEE enforces ultra-low emission standards for industrial boilers, redirecting domestic catalyst demand toward higher-cell-density substrates. Stakeholders must track how REACH authorization timelines for palladium compounds reshape material sourcing strategies and supplier qualification protocols.
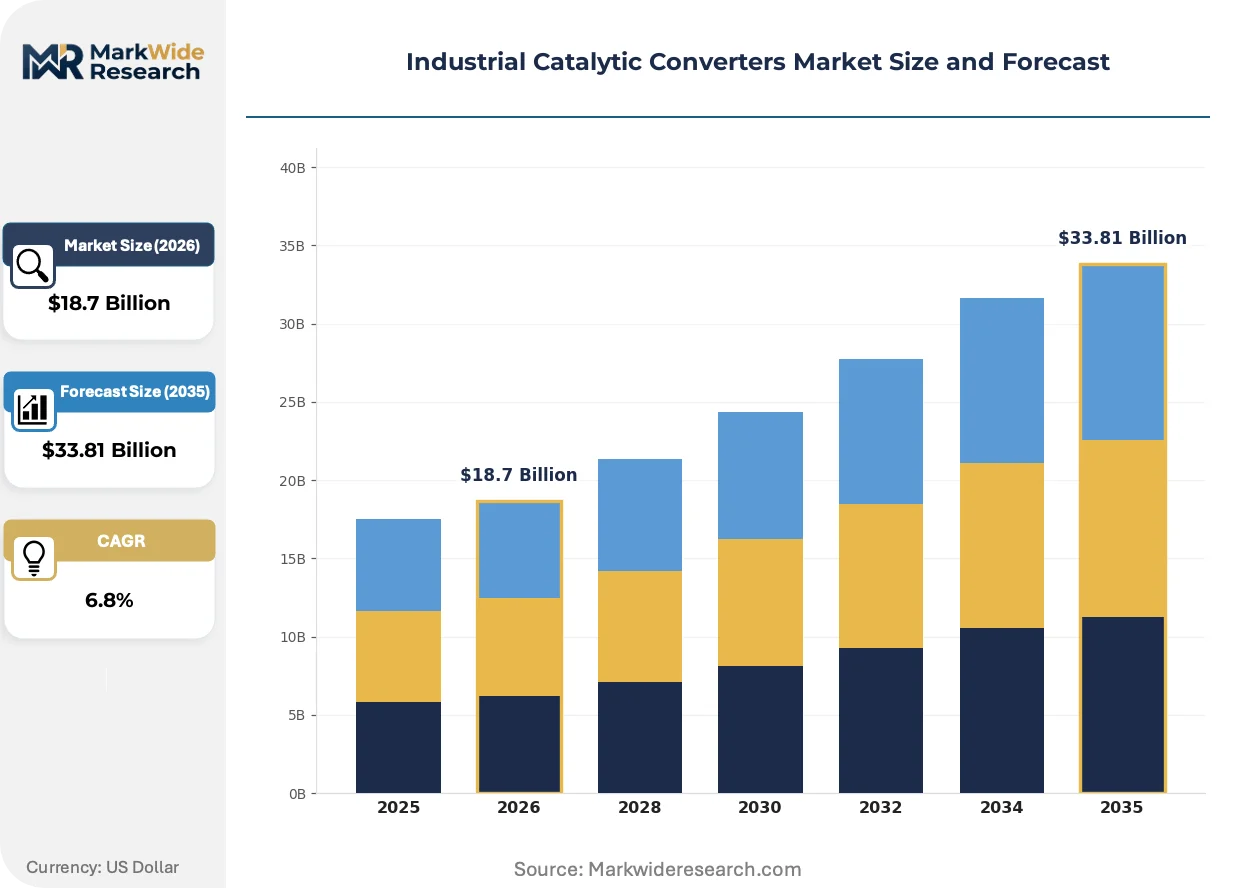
Market Dynamics
Platinum-group metal supply concentration and regulatory ratcheting on NOx thresholds are compressing catalyst formulation flexibility while forcing rapid substrate technology upgrades across power generation and marine engine fleets.
Growth Catalysts
- EPA New Source Performance Standards:Stationary source operators in the United States face tightening NOx ceilings that mandate three-way catalyst retrofits on aging gas turbines and process heaters.
- Coal-to-gas plant conversions:Power generation facilities across India and China retrofit exhaust systems to accommodate cleaner feedstock blends, driving demand for higher-cell-density substrates.
- Zeolite promoter advances:Copper-CHA and iron-ZSM-5 formulations achieve broader temperature windows for SCR reactions, extending catalyst service intervals in intermittent-duty industrial engines.
Market Restraints
- Palladium price volatility:Concentrated South African and Russian mine output exposes catalyst manufacturers to input cost spikes that compress margin on gasoline oxidation formulations.
- REACH authorization timelines:ECHA's staggered approval schedules for palladium compounds create procurement uncertainty and force dual-qualification of supplier bases across European supply chains.
- Ceramic substrate brittleness:Thermal shock failures in high-sulfur exhaust environments limit substrate durability and inflate warranty reserves for marine SCR installations.
Strategic Opportunities
- India's ultra-low emission boiler mandate:MEE enforcement creates first-mover advantage for domestic catalyst producers capable of high-volume manufacturing of coated metallic substrates.
- Hydrogen combustion turbines:Ammonia slip catalyst requirements for hydrogen-blended fuel streams open adjacent product lines for existing SCR technology platforms.
- Closed-loop PGM recovery:Spent catalyst recycling infrastructure in Belgium and Germany yields captive metal supply that insulates against primary market price swings.
Industry Challenges
- Catalyst characterization expertise:Shortage of technicians trained in accelerated aging protocols and surface-area analysis bottlenecks R&D throughput at mid-scale manufacturers.
- Legacy engine integration:Retrofit packaging constraints on 1990s-era diesel gensets demand custom substrate geometries that fragment production runs and inflate tooling amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Catalytic Converters Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Gasoline, LPG, Others Technology: Three-Way Catalyst, Selective Catalytic Reduction, Oxidation Catalyst, Others End User: Manufacturing, Power Generation, Construction, Marine Application: Emission Control, Fuel Efficiency, Noise Reduction, Chemical Processing |
| Companies Covered | Clariant AG, Cormetech, Johnson Matthey PLC, Mitsubishi Power Americas, Cataler Corporation, Umicore, Haldor Topsoe A/S, Tenneco Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Catalytic Converters Market Emerging Trajectories
Active coating deposition methods and real-time exhaust monitoring are collapsing the traditional separation between catalyst manufacturing and fleet performance optimization, binding suppliers into long-term outcome relationships with end-users.
Membrane-coated catalyst manufacturing is modularizing production economics for selective catalytic reduction systems. BASF SE and Umicore have scaled slot-die coating lines that permit rapid formulation switches without full line changeovers. Power plant operators in Germany and the Netherlands now specify modular cartridge designs that cut replacement downtime from days to hours.
EU F-Gas Regulation amendments tighten refrigerant and process emission controls that indirectly elevate thermal oxidizer and catalyst requirements for chemical process industries. The regulation forces adipic acid and caprolactam producers to upgrade from simple oxidation catalysts to integrated SCR-oxidation combinations. Belgian and Dutch chemical clusters have accelerated procurement timelines to meet 2027 compliance windows.
Service unbundling is fragmenting traditional catalyst supply relationships. End-users in marine and construction equipment now separate catalyst procurement from installation and regeneration services, soliciting each element through distinct competitive tenders. Japanese ship operators have pioneered this disaggregation, driving European suppliers to establish independent service subsidiaries or risk margin compression on hardware-only contracts.
Industrial Catalytic Converters Market Segmentation
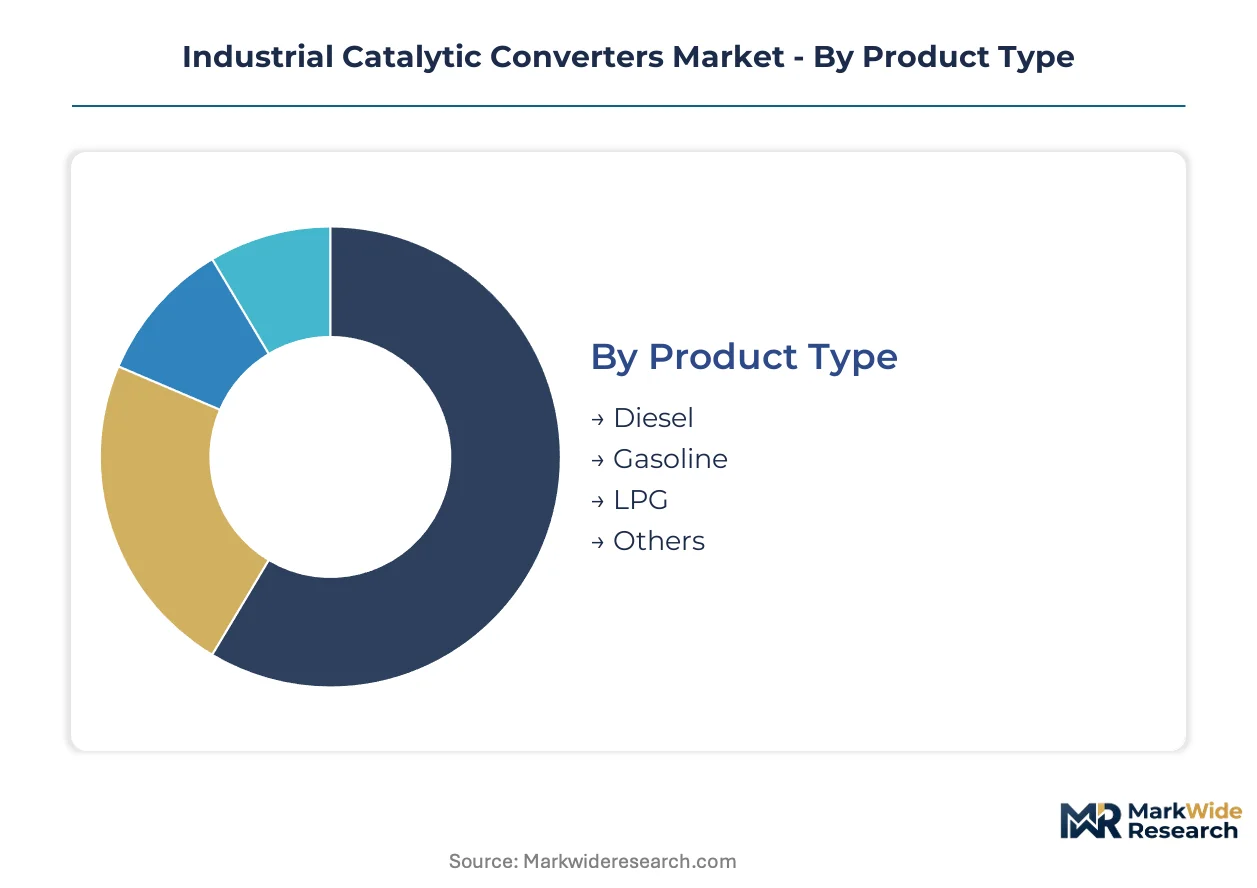
Industrial catalytic converter procurement hinges on matching substrate durability to exhaust chemistry, operating temperature profiles, and regulatory compliance tiers. Buyers segment demand across fuel type, reaction technology, and end-use duty cycles to optimize total cost of ownership across replacement intervals.
Product Type:
Fuel chemistry dictates catalyst formulation complexity and precious metal loading requirements, with sulfur content and combustion temperature ranges driving substrate material selection.
- Diesel:Heavy-duty oxidation catalysts employ platinum-palladium coatings on cordierite substrates to abate particulate matter and NOx from compression-ignition engines. Marine freight operators in Germany and construction equipment fleets across India concentrate procurement on high-cell-density variants that withstand intermittent load cycles.
- Gasoline:Three-way catalyst configurations balance rhodium, palladium, and ceria-zirconia oxygen storage components to simultaneously reduce NOx, CO, and hydrocarbons. Power generation facilities in China retrofitting coal-to-gas turbines drive specification shifts toward higher palladium loadings as platinum retreats from light-duty applications.
- LPG:Lower combustion temperatures favor palladium-only formulations with reduced thermal degradation risk in propane-fueled industrial engines.
- Others:Emerging ammonia and hydrogen combustion systems require specialized slip catalysts for unburned fuel abatement in experimental turbine installations.
Diesel leads on scale; gasoline leads on momentum.
Technology:
Reaction mechanism selection determines whether end-users achieve single-pollutant reduction or simultaneous multi-emission control, with retrofit feasibility and urea infrastructure availability shaping adoption trajectories.
- Three-Way Catalyst:Simultaneous redox reactions across platinum-group metal surfaces achieve stoichiometric exhaust conversion without secondary reductant injection. Stoichiometric gas turbines and process heaters in US manufacturing facilities specify these systems where urea logistics prove uneconomical.
- Selective Catalytic Reduction:Copper-CHA and iron-ZSM-5 zeolite promoters enable ammonia-mediated NOx reduction across broader temperature windows. Coal-to-gas power plant retrofits in India and China drive expanding adoption as operators seek compliance with ultra-low emission mandates.
- Oxidation Catalyst:Platinum-palladium coatings target CO and hydrocarbon conversion without NOx reduction, serving legacy diesel gensets and marine auxiliary engines where space constraints preclude SCR hardware.
- Others:Lean NOx traps and passive regeneration systems address niche applications in high-altitude industrial engines with variable oxygen availability.
Selective catalytic reduction climbs the fastest; oxidation catalyst holds installed base dominance.
End User:
Operating intensity and emission stringency vary sharply across end-use sectors, with continuous-duty applications justifying premium substrate investments and intermittent cycles favoring modular replacement strategies.
- Manufacturing:Chemical process industries and metal fabrication facilities deploy integrated SCR-oxidation combinations to satisfy EU F-Gas Regulation amendments. Adipic acid producers in Belgium and the Netherlands accelerated procurement timelines to meet compliance windows.
- Power Generation:Coal and gas turbine operators across Asia-Pacific retrofit exhaust systems with higher-cell-density substrates as feedstock blends shift toward cleaner gases. Long-term service contracts bundle catalyst replacement with remote monitoring, concentrating margin pools in this segment.
- Construction:Mobile diesel equipment fleets prioritize compact oxidation catalyst geometries that tolerate vibration and thermal shock without ceramic substrate fracture.
- Marine:IMO Tier III compliance drives SCR installations on oceangoing vessels, though ceramic substrate brittleness in high-sulfur exhaust environments inflates warranty reserves for European suppliers.
Power generation commands revenue concentration; manufacturing exhibits steepest specification upgrading.
Application:
Performance outcomes beyond baseline emission control—fuel efficiency recovery, acoustic attenuation, and process chemistry—create adjacent value pools that reshape supplier-customer relationships.
- Emission Control:Core functionality addressing EPA New Source Performance Standards and China's MEE ultra-low emission ceilings for NOx, CO, and hydrocarbon abatement. Stationary source operators face tightening thresholds that mandate technology upgrades from oxidation-only to three-way or SCR configurations.
- Fuel Efficiency:Optimized catalyst formulations reduce exhaust backpressure, recovering turbine output that parasitic losses would otherwise diminish. Combined cycle gas turbine operators in Germany specify low-pressure-drop substrate geometries.
- Noise Reduction:Catalytic converter housings integrate acoustic attenuation media to satisfy occupational exposure limits in enclosed industrial environments.
- Chemical Processing:Thermal oxidizers and catalytic reactors convert process vent streams in specialty chemical manufacturing, with REACH authorization timelines for palladium compounds reshaping material sourcing strategies.
Emission control anchors volume; fuel efficiency gains share fastest as energy costs bite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates German demand for SCR retrofits on aging coal-to-gas turbine installations. Regulatory divergence across major economies is fragmenting procurement specifications and forcing multinational suppliers to maintain parallel product lines.
United States
EPA New Source Performance Standards compel stationary source operators to upgrade oxidation-only systems to three-way catalyst configurations on gas turbines and process heaters. The agency's tightening NOx ceilings for industrial boilers in Texas and Louisiana refineries accelerate replacement cycles. Houston's petrochemical corridor drives specification demand for integrated SCR-oxidation combinations in adipic acid production.
China
MEE ultra-low emission mandates for industrial boilers redirect domestic catalyst procurement toward higher-cell-density metallic substrates. Coal-to-gas conversions across Jiangsu and Shandong provinces retrofit exhaust systems with selective catalytic reduction technology. The Yangtze River Delta manufacturing belt concentrates demand for heavy-duty diesel oxidation systems in construction equipment fleets.
Germany
EU F-Gas Regulation amendments force chemical producers in Ludwigshafen and Antwerp to upgrade thermal oxidizers with integrated SCR-oxidation catalyst combinations. REACH authorization timelines for palladium compounds reshape material sourcing strategies across European supply chains. The BASF Ludwigshafen complex anchors membrane-coated catalyst manufacturing at scale for power generation retrofit cycles.
India
CEA mandates for ultra-low emission standards in thermal power plants drive adoption of selective catalytic reduction systems on coal and gas turbine installations. Coal-to-gas feedstock shifts across Gujarat and Maharashtra power facilities demand higher-cell-density substrate retrofits. The Mundra and Hazira industrial clusters concentrate procurement for heavy-duty diesel oxidation catalysts in marine freight operations.
Japan
METI efficiency standards for industrial engines tighten allowable NOx and particulate thresholds, compelling manufacturing facilities to adopt copper-CHA zeolite promoter formulations. Ship operators in Kobe and Nagoya pioneer service unbundling, separating catalyst procurement from installation and regeneration contracts. The Osaka-Kobe manufacturing belt drives specification demand for modular cartridge designs that minimize replacement downtime.
Industrial Catalytic Converters Market Vendor Landscape
Capacity expansion dominates the current landscape as established suppliers scale membrane-coated catalyst manufacturing to capture power generation retrofit demand. The vendor base concentrates around integrated precious-metal refiners, diversified chemical conglomerates, and specialized ceramic substrate fabricators. Three strategic archetypes define positioning: PGM-integrated refiners with captive metal supply, diversified materials science conglomerates with scale advantages, and closed-loop recycling specialists recovering platinum-group metals from spent units. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers establish regional coating facilities to reduce logistics exposure.
Among European-based integrated suppliers, Johnson Matthey PLC and BASF SE occupy positions that exemplify divergent strategic archetypes. Johnson Matthey leverages its precious-metal refining integration to sustain cost advantages across supply chains exposed to South African and Russian mine output concentration. BASF SE anchors scale-driven manufacturing through its Ludwigshafen membrane-coating operations, serving power plant operators in Germany and the Netherlands with modular cartridge designs. Umicore represents the closed-loop recycling archetype, recovering platinum-group metals from spent industrial units to insulate against primary market price volatility.
| Leading Market Players |
|---|
| Clariant AG |
| Cormetech |
| Johnson Matthey PLC |
| Mitsubishi Power Americas |
| Cataler Corporation |
| Umicore |
| Haldor Topsoe A/S |
| Tenneco Inc. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Integrated precious-metal refiners with captive PGM supply anchor pricing discipline across European supply chains, compressing margin volatility for membrane-coated catalyst manufacturers while fragmenting procurement leverage for oxidation-catalyst specialists dependent on spot metal markets.
Pricing Analysis
Input-cost pass-through from South African and Russian platinum-group metal mine output dominates catalyst formulation economics, with palladium price spikes compressing margin on gasoline oxidation systems faster than SCR zeolite formulations. Three-tier pricing structure across premium membrane-coated, standard ceramic-substrate, and economy metallic-honeycomb levels reflects certification grade and after-sales service bundling. Pricing pressure stems from REACH authorization timelines forcing dual-qualification of supplier bases. Power generation operators exhibit lowest price sensitivity due to long-term service contracts, while marine freight buyers drive hardest bargaining on hardware-only procurement.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian palladium mine output, which feeds catalyst manufacturing concentrated in Germany, Belgium, and China. Raw material dependencies span platinum-group metals, copper-CHA zeolite promoters, and cordierite ceramic substrates. Supply chain risk centers on logistics chokepoints through Rotterdam and Hamburg ports for European coating facilities. Distribution runs through OEM captive supply agreements for power generation retrofits and independent distributors for marine aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where coal-to-gas turbine retrofits redirect procurement toward higher-cell-density substrates with embedded remote monitoring service layers.
For Market Incumbents: Lock in backward integration into precious-metal refining or closed-loop recycling infrastructure to insulate margin from PGM price volatility. Secure long-term service contracts with power generation operators before unbundling fragments traditional supply relationships. Prioritize membrane-coated catalyst capacity expansion in Germany and China to capture SCR retrofit cycles. For New Entrants and Emerging Players: Begin with India's ultra-low emission boiler mandate, where domestic manufacturing gaps create first-mover opportunity for coated metallic substrate specialists. Target marine aftermarket regeneration services in Japan and South Korea, where ship operators have pioneered procurement disaggregation. Pursue technology licensing from established European suppliers rather than greenfield R&D investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ceramic substrate fabricators lacking PGM integration, presenting consolidation targets for diversified materials conglomerates seeking vertical control. Long-term viability hinges on hydrogen combustion turbine catalyst positioning. Watch ammonia slip catalyst procurement timelines as the inflection signal for adjacent product line viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Refining | Captive metal supply insulates Johnson Matthey and Umicore against South African mine output concentration. |
| Membrane-Coated Catalyst Capacity Expansion | BASF's Ludwigshafen slot-die coating lines enable rapid formulation switches for power plant retrofit demand. |
| Closed-Loop Recycling Infrastructure | Belgian and German spent catalyst recovery facilities yield captive platinum-group metal supply. |
| Long-Term Service Contract Bundling | Remote monitoring integration with catalyst replacement concentrates margin pools in power generation. |
| Hydrogen Combustion Catalyst Development | Ammonia slip catalyst requirements for hydrogen-blended turbines open adjacent SCR technology applications. |
Methodological Framework
Bottom-up power generation and marine engine modeling reconciled against top-down PGM supply tracking forms the analytical core, combining primary interviews with catalyst procurement managers, plant engineers at coal-to-gas facilities, marine fleet technical directors, and aftermarket service heads with secondary validation through EPA New Source Performance Standards filings, EU ECHA REACH authorization databases, and customs trade data for platinum-group metal flows. Stakeholder input triangulates against SEC 10-K disclosures from integrated suppliers and capacity announcements from membrane-coating facilities.
Input-output matrix framing connects PGM loading requirements per catalyst unit to installation volumes across diesel, gasoline, and emerging hydrogen combustion applications, with segmentation dimensions spanning fuel chemistry, reaction technology mechanism, end-use duty cycle intensity, and regional regulatory compliance tier. CAGRs derive from modeled replacement intervals and retrofit penetration curves across the analysis window, incorporating coal-to-gas feedstock shift timelines and IMO Tier III marine compliance deadlines as industry-specific forecast inputs.
Caveats apply where palladium price volatility, REACH authorization delays, or ceramic substrate thermal shock failures in high-sulfur exhaust environments could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and power plant operator capital allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
North America Industrial Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Organic Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Refining Catalysts Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Environmental Catalysts Market
Catalysts
CO2 Reforming Catalysts Market