
 Homogeneous Catalyst Market | 2026-2036
Homogeneous Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Homogeneous Catalyst Market Analytics
A shift from single-source to multi-source procurement of precious metal precursors is hardening across the homogeneous catalyst supply base. Johnson Matthey sustains its position through captive rhodium and ruthenium refining operations. BASF SE leverages integrated petrochemical complexes in Germany to secure backward control over metallocene intermediates. Albemarle Corporation anchors its competitiveness in lithium-derived organometallics for polymerization chemistry.
Homogeneous catalysts consist of soluble metal complexes or organometallic compounds that exist in the same phase as reactants, typically operating at 50-200°C with turnover frequencies exceeding 10,000 hr⁻¹ in optimized systems; they enable precise stereoselectivity in hydrogenation, carbonylation, and metathesis reactions for high-value chemical production. Transition metal catalysts dominate value capture due to iridium and palladium loading in pharmaceutical active ingredient synthesis. Acidic catalysts compete on cost in bulk petrochemical streams where selectivity requirements remain moderate. Organocatalysts represent the fastest-expanding category as metal-free synthesis gains traction under green chemistry mandates.
EPA hazardous air pollutant standards and REACH authorization requirements restrict certain chromium and cobalt catalyst formulations, forcing reformulation toward benign ligand architectures. The EU Green Deal's chemical sustainability targets accelerate bio-based solvent systems for aqueous-phase delivery modes. Stakeholders must monitor evolving substance restrictions under ECHA's SVHC candidate list to anticipate catalyst redesign cycles and raw material substitution timelines.
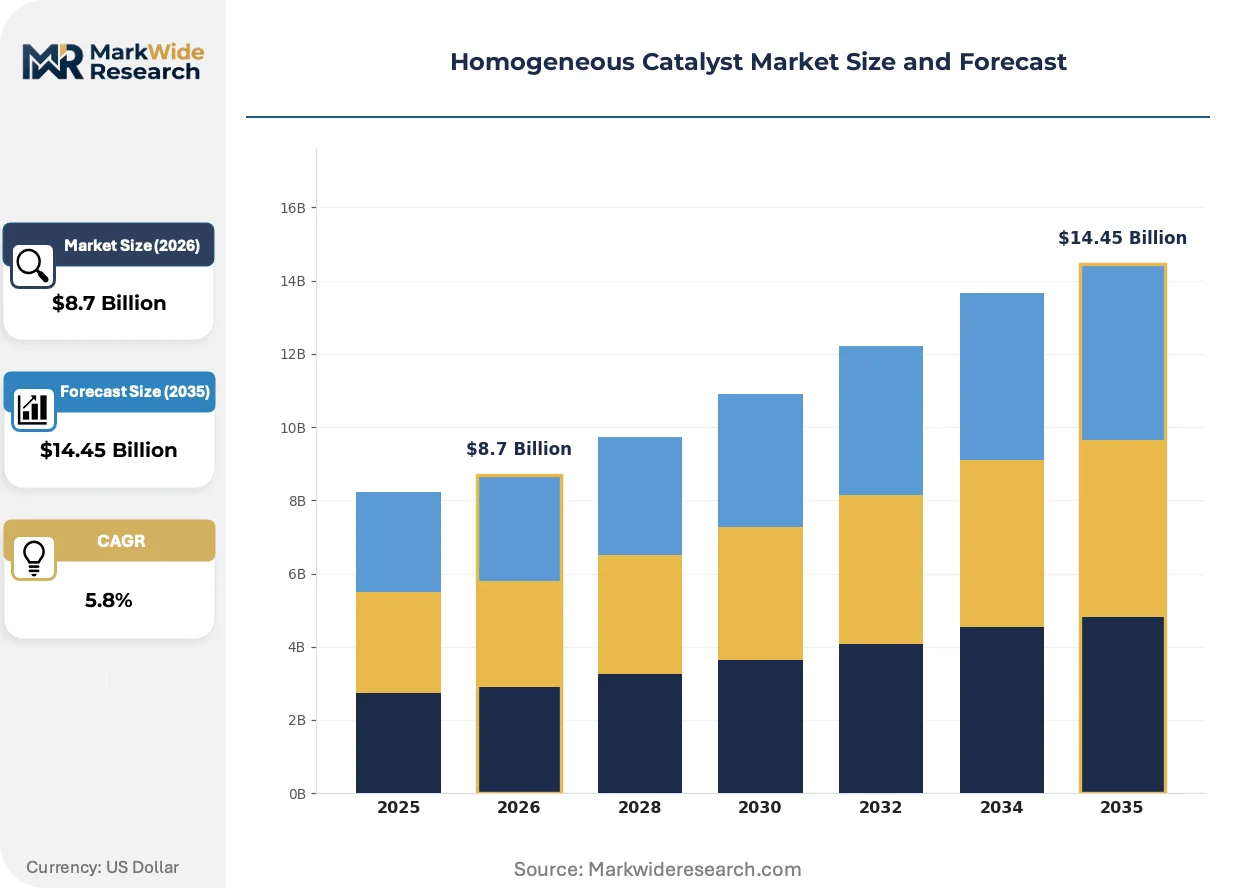
Market Dynamics
REACH authorization requirements and EPA hazardous air pollutant standards are forcing systematic reformulation of chromium and cobalt catalyst architectures, compressing redesign cycles and tightening ligand selection criteria across pharmaceutical and petrochemical applications.
Growth Catalysts
- Asymmetric synthesis demand:Specialty pharmaceutical manufacturers require transition metal catalysts for chiral active ingredient production, with iridium and palladium complexes commanding premium positioning in high-value synthesis workflows.
- EU Green Deal chemical sustainability targets:Bio-based solvent systems for aqueous-phase catalyst delivery are gaining mandated preference, accelerating adoption of water-compatible organometallic formulations.
- German chemical corridor concentration:Ludwigshafen and Leverkusen host integrated petrochemical complexes that generate captive demand for metallocene intermediates and backward-integrated catalyst supply chains.
Market Restraints
- Precious metal price volatility:Rhodium and ruthenium spot markets exhibit sharp fluctuations that compress margin predictability for catalyst formulators dependent on spot procurement.
- Single-source supply concentration:Captive refining operations in South Africa and Russia control substantial primary rhodium extraction, creating geographic chokepoints for precursor security.
- Technical substitution ceiling:Organocatalysts face turnover frequency limitations below 500 hr⁻¹ in hydrogenation applications, constraining displacement of transition metal systems in throughput-sensitive processes.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO regulatory harmonization with ICH standards is attracting active ingredient producers seeking cost-advantaged chiral synthesis capacity.
- Flow chemistry integration:Continuous processing platforms enable homogeneous catalyst immobilization and recovery, converging batch efficiency with homogeneous selectivity advantages.
- US Inflation Reduction Act domestic content incentives:Onshoring provisions for critical chemical intermediates create procurement preference for domestically manufactured catalyst systems in government-contracted pharmaceutical supply chains.
Industry Challenges
- Organometallic synthesis expertise scarcity:Phosphine ligand design and metal-ligand coordination optimization require specialized synthetic chemists, with talent pipelines concentrated in Basel, Boston, and Tokyo metropolitan clusters.
- ECHA SVHC candidate list monitoring burden:Evolving substance restrictions trigger proactive reformulation investments ahead of formal authorization deadlines, straining R&D allocation across product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homogeneous Catalyst Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Transition Metal Catalysts, Acidic Catalysts, Basic Catalysts, Organocatalysts Application: Petrochemicals, Pharmaceuticals, Fine Chemicals, Agrochemicals Delivery Mode: Liquid Phase, Gas Phase, Aqueous Phase, Supercritical Fluid End User: Chemical Manufacturers, Refining Industry, Research Institutions, Academic Institutions |
| Companies Covered | Honeywell International, Albemarle Corporation, BASF SE, Exxon Mobil Corporation, Clariant AG, Johnson Matthey, LyondellBasell Industries, Chevron Phillips Chemical Company, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homogeneous Catalyst Market Evolving Landscape
Computational catalyst design and machine learning screening protocols are compressing development timelines for ligand architectures, while regulatory substance restrictions accelerate metal-free synthesis pathways.
Artificial intelligence-driven density functional theory screening is converging with robotic synthesis platforms to automate ligand discovery cycles. Pharmaceutical contract manufacturers in Switzerland and Massachusetts are deploying these integrated systems to reduce catalyst optimization from 18-month cycles to 8-week iterations. The structural consequence is compressing competitive moats around proprietary ligand libraries as computational access democratizes.
REACH authorization requirements for cobalt dichloride and hexavalent chromium compounds are eliminating legacy catalyst formulations from EU supply chains. Formulators must redesign hydrogenation systems around manganese and iron alternatives that meet ECHA substitution mandates. Specialty chemical producers in Germany and the Netherlands are accelerating pilot-scale validation of bioinspired coordination complexes to maintain market access.
Multi-year offtake agreements with precious metal refiners are displacing spot-market procurement patterns among mid-scale catalyst consumers. Pharmaceutical active ingredient manufacturers are consolidating supplier relationships to secure rhodium and iridium allocation certainty. This behavioral shift is most pronounced in Basel's pharmaceutical cluster and North Carolina's Research Triangle, where supply security now outweighs price optimization in sourcing criteria.
Homogeneous Catalyst Market Segmentation
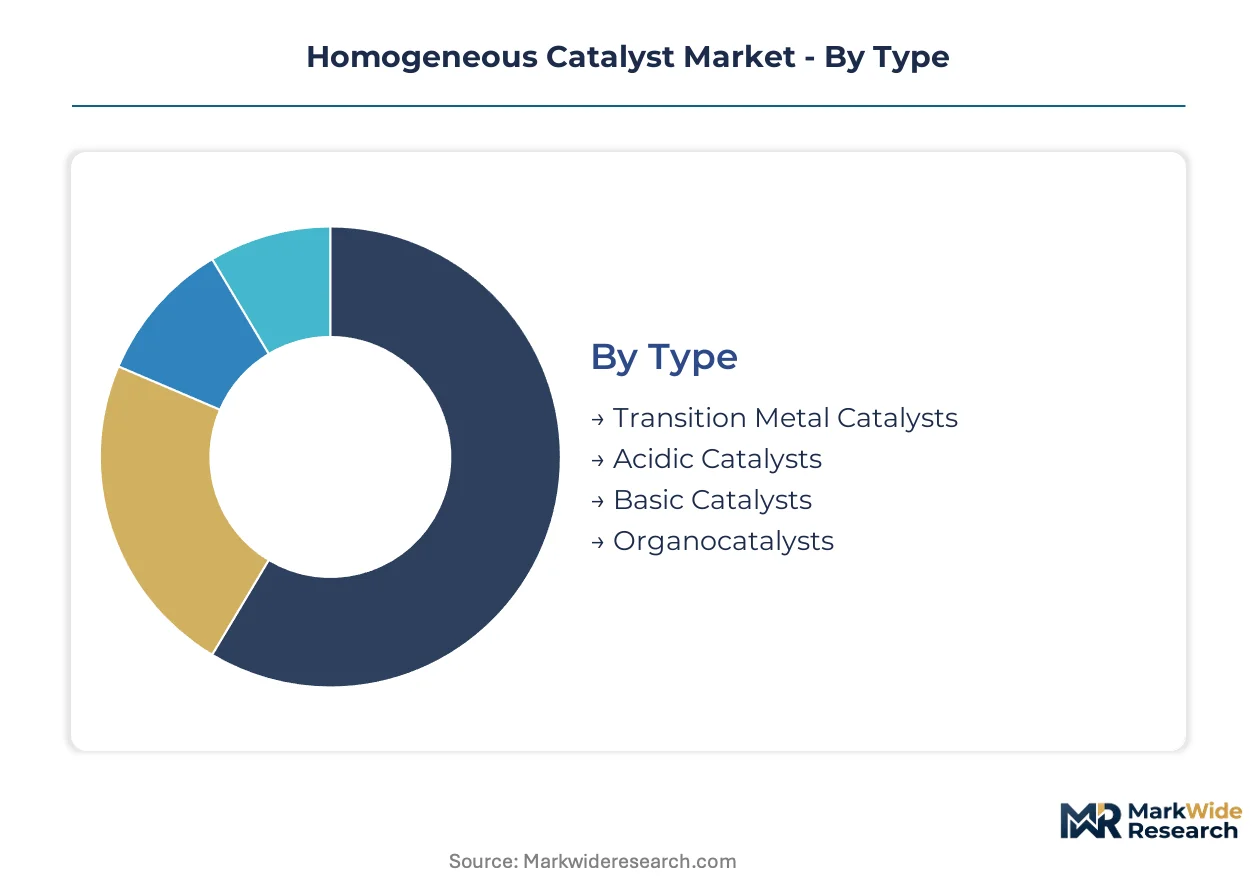
Homogeneous catalyst procurement patterns diverge sharply across type, application, and delivery mode boundaries. Supply chain configuration and regulatory exposure vary by segment, forcing distinct sourcing strategies from pharmaceutical formulators and petrochemical operators.
Type:
Supply concentration for precursor metals and ligand architectures determines competitive positioning within each catalyst category.
- Transition Metal Catalysts:Iridium and palladium complexes enable precise stereoselectivity in chiral hydrogenation and carbonylation reactions. Pharmaceutical manufacturers in Basel and Boston concentrate procurement of these systems for active ingredient synthesis, driven by FDA and EMA purity mandates that tolerate premium metal loadings.
- Acidic Catalysts:Sulfonic acid and phosphoric acid derivatives operate at lower cost in bulk petrochemical streams. Refining complexes along the US Gulf Coast and Germany's chemical corridor deploy these systems where moderate selectivity requirements align with throughput economics.
- Basic Catalysts:Alkoxide and amine-based systems serve polymerization and transesterification applications. Chemical manufacturers in Japan and South Korea favor these formulations for specialty polymer production.
- Organocatalysts:Metal-free small-molecule architectures gain traction under REACH and EPA green chemistry mandates. Biocatalysis startups in the Netherlands and California pilot these systems to eliminate heavy metal contamination risks in pharmaceutical waste streams.
Transition metal catalysts absorb the bulk of installed capacity; organocatalysts are expanding most quickly.
Application:
End-use value concentration and regulatory stringency segment demand across chemical processing verticals.
- Petrochemicals:Fluid catalytic cracking and hydroprocessing operations consume homogeneous acid systems at scale. Integrated complexes in Ludwigshafen and Houston prioritize catalyst longevity and regeneration economics over absolute selectivity.
- Pharmaceuticals:Asymmetric synthesis of chiral active ingredients demands iridium-catalyzed hydrogenation and palladium-mediated cross-coupling. CDSCO harmonization with ICH standards in India is attracting contract manufacturers seeking cost-advantaged capacity without sacrificing regulatory compliance.
- Fine Chemicals:Low-volume, high-margin specialty intermediates require rapid catalyst optimization cycles. Swiss and Massachusetts contract manufacturers deploy machine learning screening to compress ligand development timelines.
- Agrochemicals:Herbicide and fungicide precursors utilize metallocene-mediated olefin metathesis. Brazilian and Australian formulators face residue limits from ANVISA and APVMA that constrain catalyst metal leaching.
Petrochemical applications anchor volume demand; pharmaceutical synthesis commands the steepest expansion trajectory.
Delivery Mode:
Phase compatibility with reactor design and solvent regulatory status shapes procurement decisions.
- Liquid Phase:Organic solvent systems dominate legacy pharmaceutical batch operations. REACH restrictions on chlorinated solvents are forcing reformulation toward acetonitrile and ethyl acetate alternatives.
- Gas Phase:Vapor-phase homogeneous catalysis enables continuous processing in petrochemical crackers. Gulf Coast refiners favor these systems for integration with existing distillation infrastructure.
- Aqueous Phase:Water-compatible organometallics align with EU Green Deal sustainability targets. German and Dutch producers pilot bio-based solvent systems to maintain market access under tightening ECHA substance restrictions.
- Supercritical Fluid:Carbon dioxide-based delivery eliminates solvent waste entirely. Academic consortia in Switzerland and Japan lead scale-up validation for commercial pharmaceutical applications.
Liquid phase systems retain the largest installed base; aqueous phase formulations are gaining share fastest.
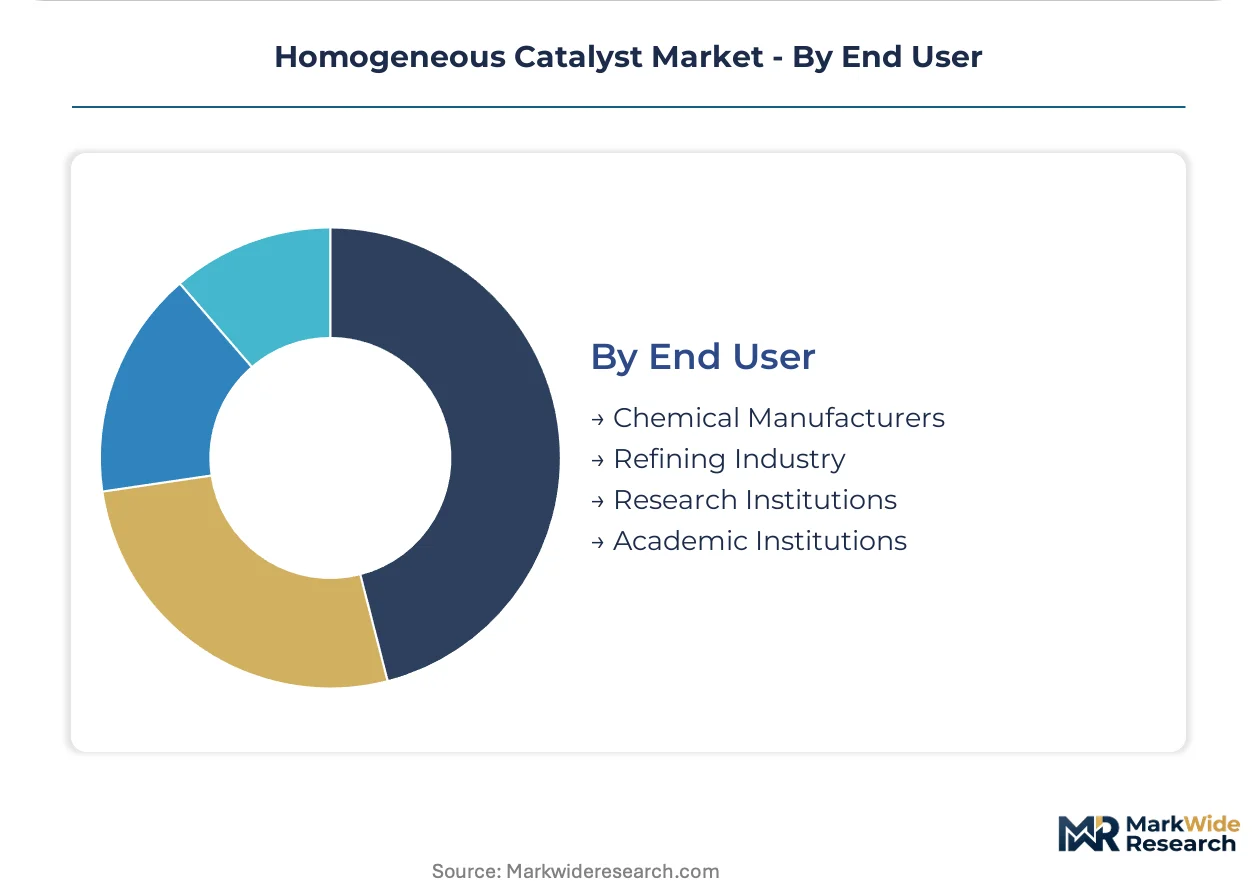
End User:
Technical capability and procurement scale differentiate catalyst consumers across the value chain.
- Chemical Manufacturers:Integrated producers with captive organometallic synthesis expertise secure backward control over ligand supply. BASF SE and Johnson Matthey maintain proprietary phosphine libraries that lock in formulation advantages.
- Refining Industry:Hydrogenation and hydrocracking operators prioritize catalyst regeneration and metal recovery economics. Multi-year offtake agreements with South African and Russian refiners secure rhodium allocation certainty.
- Research Institutions:National laboratories and corporate R&D centers drive early-stage ligand discovery. MIT and ETH Zurich host specialized synthetic chemist talent pipelines concentrated in Basel, Boston, and Tokyo clusters.
- Academic Institutions:University chemistry departments validate mechanistic hypotheses and train specialized personnel. Flow chemistry integration research at Cambridge and Caltech is converging batch efficiency with homogeneous selectivity advantages.
Chemical manufacturers deploy the greatest catalyst volumes; research institutions are expanding experimental throughput most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical manufacturers concentrate procurement of iridium and palladium complexes in three distinct geographic clusters. German chemical complexes around Ludwigshafen generate captive demand for metallocene intermediates. REACH authorization requirements and EPA hazardous air pollutant standards reshape formulation priorities across all major production centers.
Germany
Ludwigshafen and Leverkusen host integrated petrochemical complexes that backward-integrate into metallocene intermediate production. REACH authorization requirements for cobalt dichloride and hexavalent chromium compounds eliminate legacy catalyst formulations from EU supply chains. BASF SE maintains proprietary phosphine libraries that lock in formulation advantages for hydrogenation systems.
United States
EPA hazardous air pollutant standards tighten catalyst selectivity requirements for pharmaceutical and petrochemical applications. The Inflation Reduction Act's domestic content incentives create procurement preference for domestically manufactured catalyst systems in government-contracted pharmaceutical supply chains. North Carolina's Research Triangle concentrates multi-year offtake agreements with precious metal refiners.
Switzerland
Basel's pharmaceutical cluster consolidates supplier relationships to secure rhodium and iridium allocation certainty. Swissmedic purity mandates tolerate premium metal loadings in chiral active ingredient synthesis. ETH Zurich hosts specialized synthetic chemist talent pipelines that compress ligand development timelines through machine learning screening.
India
CDSCO regulatory harmonization with ICH standards attracts active ingredient producers seeking cost-advantaged chiral synthesis capacity. The country's national pharmaceutical regulator enforces residue limits that constrain catalyst metal leaching in export-oriented production. Maharashtra and Gujarat host contract manufacturing organizations expanding asymmetric synthesis capabilities.
Japan
METI chemical sustainability targets accelerate bio-based solvent systems for aqueous-phase catalyst delivery. PMDA purity mandates drive iridium-catalyzed hydrogenation in high-value pharmaceutical workflows. The Kansai region around Osaka concentrates alkoxide and amine-based systems for specialty polymer production.
Homogeneous Catalyst Market Competitive Landscape
Multi-year offtake agreements with precious metal refiners dominate the current landscape as supply security displaces price optimization in sourcing criteria. The vendor base organizes around three strategic archetypes: integrated petrochemical complexes with captive organometallic synthesis, specialized precious metal refiners with rhodium and ruthenium operations, and pharmaceutical-focused formulators with proprietary ligand libraries. Competitive positioning hardens through backward integration into metallocene intermediates and strategic partnerships with national laboratories for early-stage ligand discovery.
Among Germany-based integrated producers, BASF SE exemplifies the petrochemical complex archetype through Ludwigshafen operations. Johnson Matthey represents the precious metal refining specialist model with captive rhodium operations. Albemarle Corporation anchors the lithium-derived organometallics segment for polymerization chemistry. These three entities occupy positions that reflect distinct supply chain control points rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Honeywell International |
| Albemarle Corporation |
| BASF SE |
| Exxon Mobil Corporation |
| Clariant AG |
| Johnson Matthey |
| LyondellBasell Industries |
| Chevron Phillips Chemical Company |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Specialized synthetic chemist clusters in Basel, Boston, and Tokyo create labor-cost differentials that widen pricing-tier spreads between premium iridium-complex formulations and commodity acidic catalysts. REACH compliance investments and precious metal volatility further stratify procurement economics across pharmaceutical and petrochemical buyer archetypes.
Pricing Analysis
After-sales service bundling separates premium catalyst suppliers offering dedicated technical support and ligand customization from unbundled commodity vendors. Three-tier pricing structure across premium, standard, and economy levels reflects metal loading purity, FDA/EMA certification grade, and volume scale commitments. Cost compression in the standard tier is intensifying as Indian contract manufacturers scale asymmetric synthesis capacity. Pharmaceutical active ingredient producers exhibit lowest price sensitivity due to regulatory purity mandates, while bulk petrochemical operators prioritize regeneration economics over upfront catalyst cost.
Supply Chain Analysis
ISO 9001 and REACH registration certification gating restricts qualified suppliers for pharmaceutical-grade organometallics to a narrow vendor base. Primary rhodium extraction concentrates in South Africa and Russia, with metallocene intermediate production anchored in Germany and the United States. The supply chain draws from iridium sponge, phosphine ligands, and bio-based solvent feedstocks. Single-source vulnerability around South African refining operations creates allocation uncertainty during spot market disruptions. Distribution runs through direct long-term offtake agreements with precious metal refiners rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward control over metallocene intermediates and captive rhodium refining operations determines competitive durability. Players are pursuing upstream leverage through multi-year precious metal offtake agreements and proprietary ligand library development.
For Market Incumbents: Hedge against organocatalyst substitution by accelerating aqueous-phase organometallic R&D while locking in multi-year iridium allocation through South African refiner partnerships. BASF SE and Johnson Matthey demonstrate the defensive value of captive phosphine synthesis and rhodium refining operations that insulate margin structures from spot volatility. Capacity addition in India's pharmaceutical corridor offers geographic diversification against REACH-driven reformulation costs in Europe. For New Entrants and Emerging Players: CDSCO harmonization with ICH standards in India opens a window for cost-advantaged chiral synthesis capacity serving export-oriented pharmaceutical manufacturers. Machine learning-driven ligand discovery platforms present the most penetrable technology wedge against incumbent proprietary libraries. Flow chemistry integration for continuous homogeneous catalysis offers a differentiated go-to-market angle for mid-scale contract manufacturers seeking throughput advantages without batch infrastructure investment. For Investors and Strategic Acquirers: Re-rating potential sits with lithium-derived organometallic specialists given polymerization chemistry demand from electric vehicle battery materials. Long-term viability over a five-to-ten year horizon favors targets with established REACH registration portfolios and aqueous-phase formulation pipelines. The signal to watch as inflection indicator is ECHA's SVHC candidate list expansion pace, which accelerates catalyst redesign cycles and concentrates procurement among compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Intermediates | BASF SE's Ludwigshafen complex secures ligand supply control against volatile precursor markets. |
| Long-term Precious Metal Offtake Agreements | Johnson Matthey's South African rhodium operations eliminate spot procurement risk for pharmaceutical clients. |
| Machine Learning-Driven Ligand Discovery | ETH Zurich's robotic synthesis platforms compress development timelines from eighteen-month cycles to eight-week iterations. |
| Aqueous-Phase Catalyst Reformulation | German producers pilot bio-based solvent systems to maintain EU market access under tightening ECHA restrictions. |
| Flow Chemistry Platform Integration | Continuous processing enables homogeneous catalyst immobilization and recovery for pharmaceutical contract manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with catalyst formulators, pharmaceutical procurement directors, petrochemical plant managers, and precious metal refinery executives. ECHA authorization databases, EPA hazardous air pollutant compliance filings, and CDSCO regulatory harmonization documents provided secondary validation. Bottom-up segmentation modeling triangulated against top-down industry association aggregates from Cefic and the American Chemistry Council.
Data-stream reconciliation across catalyst type, application vertical, delivery mode, and end-user technical capability dimensions produced volume and value estimates across the analysis window. CAGRs derived from segment-level growth rate convergence around macroeconomic drivers and regulatory implementation timelines. Precious metal price trajectory assumptions and REACH authorization rollout schedules constituted industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for organocatalyst turnover frequency improvement would alter the outlook. Forecasts reflect assumptions regarding ECHA substance restriction timelines and South African rhodium supply stability. A model refresh is warranted upon material change in REACH authorization scope or precious metal extraction geopolitics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Catalyst Market
Catalysts
North America Industrial Catalyst Market
Catalysts
Catalase Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Catalyst Handling Services Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Steam Methane Reforming Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Chemical Processing Catalysts Market