
 Catalyst Handling Services Market | 2026-2036
Catalyst Handling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Catalyst Handling Services Market Analysis
Ceramic-based support media is pivoting toward advanced alumina formulations in regeneration services, cutting replacement frequency by half. Mourik leverages proprietary vacuum-transfer systems to anchor its position in European refinery turnarounds. BASF SE sustains deep integration between catalyst manufacturing and handling logistics, while Johnson Matthey PLC dominates hydrogen-production catalyst swaps through specialized reactor-entry protocols.
Catalyst handling services encompass the mechanical extraction, transport, regeneration, and reinstallation of spent catalytic materials from fixed-bed and fluidized reactors, typically operating under nitrogen-inerted conditions at temperatures below sixty degrees Celsius to preserve catalytic activity. The primary purpose centers on minimizing refinery downtime while recovering valuable metals such as platinum, palladium, and cobalt from deactivated catalyst beds. Regeneration services capture the largest margin pool as refiners prioritize metal recovery over fresh catalyst purchases, while robotic solutions within the technology dimension represent the fastest-expanding segment as operators seek to eliminate confined-space entry for personnel. Manual handling persists across laboratory catalyst applications where batch sizes remain too small to justify automated capital deployment.
EPA Tier 3 sulfur regulations and OSHA Process Safety Management standards jointly compel U.S. refiners to outsource catalyst handling to certified specialists rather than maintain in-house teams. The EU F-Gas Regulation and REACH compliance frameworks in Europe similarly restrict on-site catalyst disposal, channeling demand toward licensed regeneration providers. Stakeholders must monitor how carbon-border adjustment mechanisms reshape the economics of cross-border catalyst regeneration versus domestic replacement.
Market Dynamics
Refinery operators are outsourcing catalyst handling to certified specialists as nitrogen-inerted reactor entry protocols grow too complex for in-house maintenance teams. EPA Tier 3 sulfur mandates and OSHA Process Safety Management standards jointly compress turnaround windows, forcing specialized service contracts.
Growth Catalysts
- EPA Tier 3 sulfur regulations:U.S. refiners face mandatory sulfur-reduction targets that accelerate catalyst changeout cycles. Turnaround frequency has doubled across Gulf Coast facilities since implementation.
- Hydrogen production expansion:Blue and green hydrogen projects require specialized catalyst swaps for reforming and water-gas shift reactors. Johnson Matthey protocols dominate this emerging demand vertical.
- Advanced alumina formulations:Ceramic support media regeneration now cuts replacement frequency by half. Service providers capture extended maintenance contracts through materials innovation.
Market Restraints
- Platinum group metal volatility:Spent catalyst recovery economics swing with palladium and rhodium price instability. Regeneration margins compress when metal markets crater.
- European licensed-provider concentration:EU F-Gas Regulation and REACH compliance restrict disposal to a narrow pool of certified handlers. Cross-border service competition remains structurally limited.
- Reactor-access robotics capex:Automated confined-space entry systems require seven-figure capital deployment. Mid-size refiners delay adoption despite safety incentives.
Strategic Opportunities
- Carbon-border adjustment mechanisms:EU CBAM reshapes economics of cross-border catalyst regeneration versus domestic replacement. Licensed European providers gain structural advantage.
- Small-batch laboratory automation:Manual handling persists in R&D catalyst applications. Miniaturized robotic systems could capture this underserved segment.
- India petrochemical cluster buildout:Reliance Industries and Nayara Energy expand refining capacity along the Gujarat coast. Turnaround service demand outpaces domestic specialist supply.
Industry Challenges
- Confined-space entry certification pipelines:OSHA-qualified reactor-entry technicians face 18-month training timelines. Labor scarcity extends turnaround scheduling windows.
- Legacy DCS integration friction:Robotic handling systems must interface with decades-old distributed control architectures. Custom protocol bridging delays deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalyst Handling Services Market |
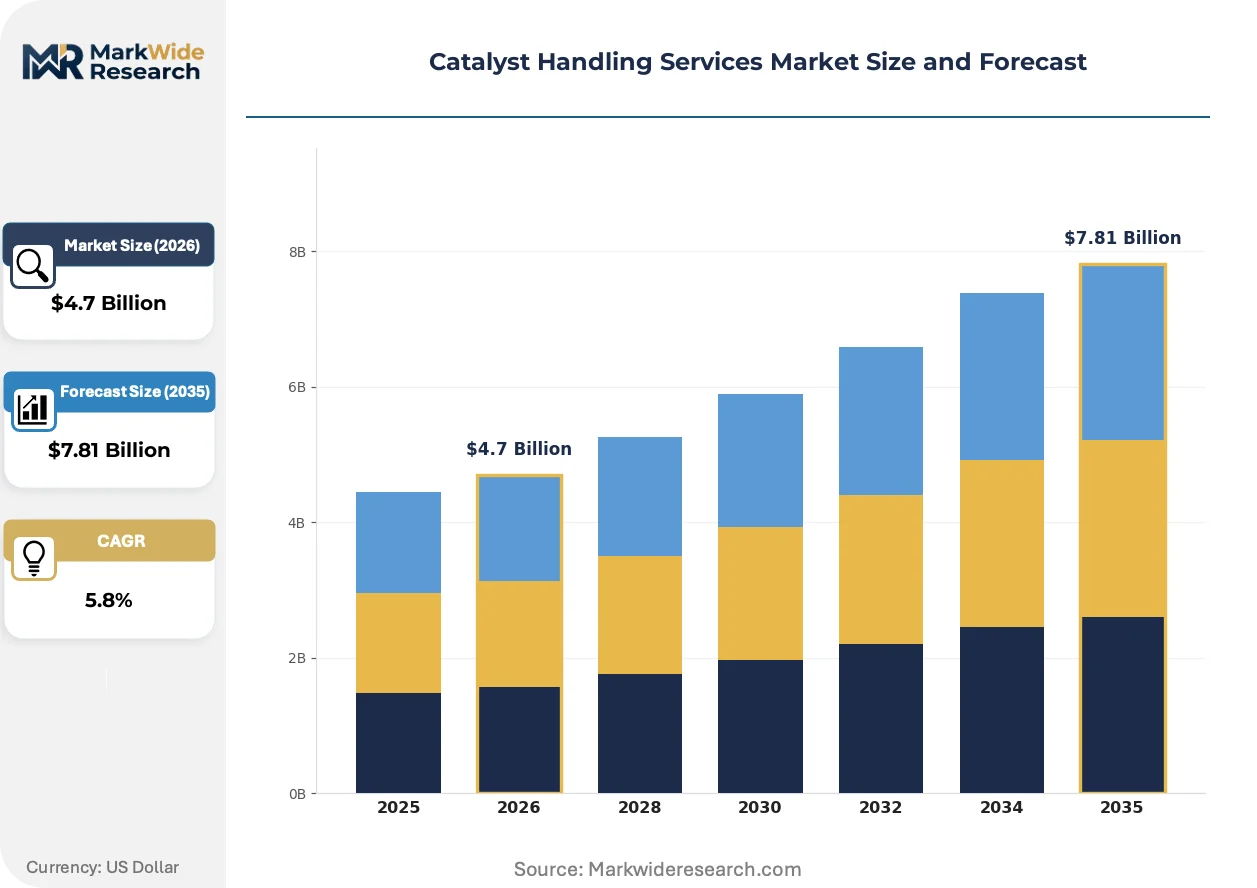
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Maintenance, Regeneration, Replacement Industry Vertical: Chemicals, Petrochemicals, Refining, Pharmaceuticals Technology: Manual Handling, Automated Systems, Robotic Solutions, Safety Equipment Application: Specialty Catalysts, Process Catalysts, Laboratory Catalysts, Industrial Catalysts |
| Companies Covered | W. R. Grace & Co.–Conn., Mourik, Johnson Matthey PLC, CR3, ANABEEB, BASF SE, Albemarle Corporation, Dickinson Group of Companies, Shell Catalysts & Technologies B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalyst Handling Services Market Emerging Trajectories
Service providers are reconfiguring equipment architectures around modularity and remote operability. Turnaround economics now favor capital-light deployment models over permanent on-site infrastructure.
Vacuum-transfer catalyst extraction technology is modularizing across European refinery contracts. Mourik deploys containerized suction systems that relocate between Rotterdam, Antwerp, and Hamburg facilities without permanent installation. This architecture compresses mobilization timelines from weeks to days while eliminating fixed infrastructure depreciation.
REACH authorization requirements for cobalt and nickel compounds are tightening spent catalyst tracking obligations. ECHA mandates cradle-to-grave documentation that extends liability to handling contractors. Regeneration specialists in Germany and the Netherlands are responding by integrating blockchain-based chain-of-custody systems into logistics operations.
Refinery procurement teams are unbundling catalyst supply from handling services. BASF and Johnson Matthey historically bundled fresh catalyst delivery with changeout execution. Buyers now tender these separately, awarding handling contracts to Mourik and specialized independents while maintaining OEM supply relationships. This bifurcation is most advanced among ARAMCO-operated and European majors with centralized procurement functions.
Catalyst Handling Services Market Segmentation
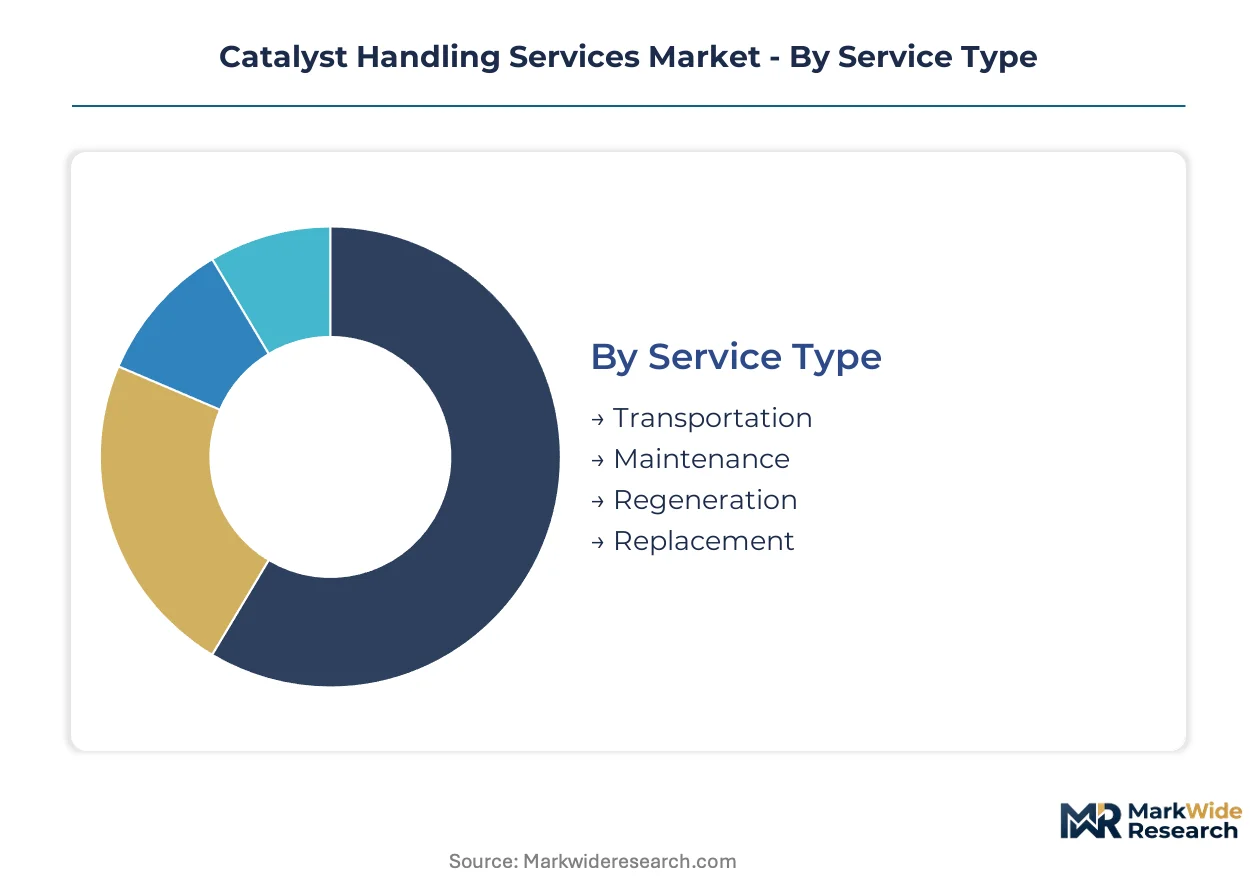
Service differentiation in catalyst handling hinges on reactor complexity, metal recovery economics, and regulatory compliance intensity. Procurement teams now unbundle supply from execution, creating distinct competitive arenas across service tiers and technology modalities.
Service Type:
Vacuum-transfer extraction systems and nitrogen-inerted protocols define technical capability differentiation across service tiers.
- Regeneration:Metal recovery from spent catalyst beds captures the highest margin pool through platinum, palladium, and cobalt reclamation. Gulf Coast refiners prioritize regeneration over fresh catalyst purchases as EPA Tier 3 mandates compress turnaround cycles.
- Replacement:Fresh catalyst installation demands precise reactor-entry protocols and confined-space certification. Labor scarcity among OSHA-qualified technicians extends scheduling windows across Texas and Louisiana petrochemical clusters.
- Transportation:Cradle-to-grave documentation requirements under REACH and ECHA tighten logistics obligations for cobalt and nickel compounds.
- Maintenance:Preventive reactor inspections and catalyst bed monitoring support extended operational runs between full changeouts.
Mature deployment sits with Regeneration. Newer deployment is concentrated in Replacement as turnaround frequency doubles.
Industry Vertical:
End-use concentration patterns reflect regional refining capacity and hydrogen infrastructure buildout trajectories.
- Refining:Hydrotreating and hydrocracking units drive continuous demand for sulfur-reduction catalyst swaps. ARAMCO-operated and European majors with centralized procurement unbundle handling from catalyst supply.
- Petrochemicals:Steam cracker and reformer catalyst changeouts align with olefin production cycles. Reliance Industries and Nayara Energy expansion along India's Gujarat coast outpaces domestic specialist supply.
- Chemicals:Ammonia and methanol synthesis catalyst handling requires specialized water-gas shift reactor protocols.
- Pharmaceuticals:Small-batch R&D catalyst applications persist with manual handling where automation capital cannot be justified.
Volume concentration centers on Refining. Margin expansion is climbing the fastest in Petrochemicals.
Technology:
Capital deployment intensity and safety certification requirements stratify competitive positioning across handling modalities.
- Robotic Solutions:Automated confined-space entry eliminates personnel exposure to nitrogen-inerted reactors. Seven-figure capital requirements delay adoption among mid-size refiners despite OSHA compliance incentives.
- Automated Systems:Vacuum-transfer and containerized suction architectures enable capital-light mobilization between Rotterdam, Antwerp, and Hamburg facilities.
- Safety Equipment:Breathing apparatus and gas detection systems support technician certification compliance under Process Safety Management standards.
- Manual Handling:Laboratory-scale catalyst batches and legacy reactor designs without robotic interface compatibility sustain this tier.
Adoption leadership sits with Robotic Solutions. Deployment friction is concentrated in Manual Handling.
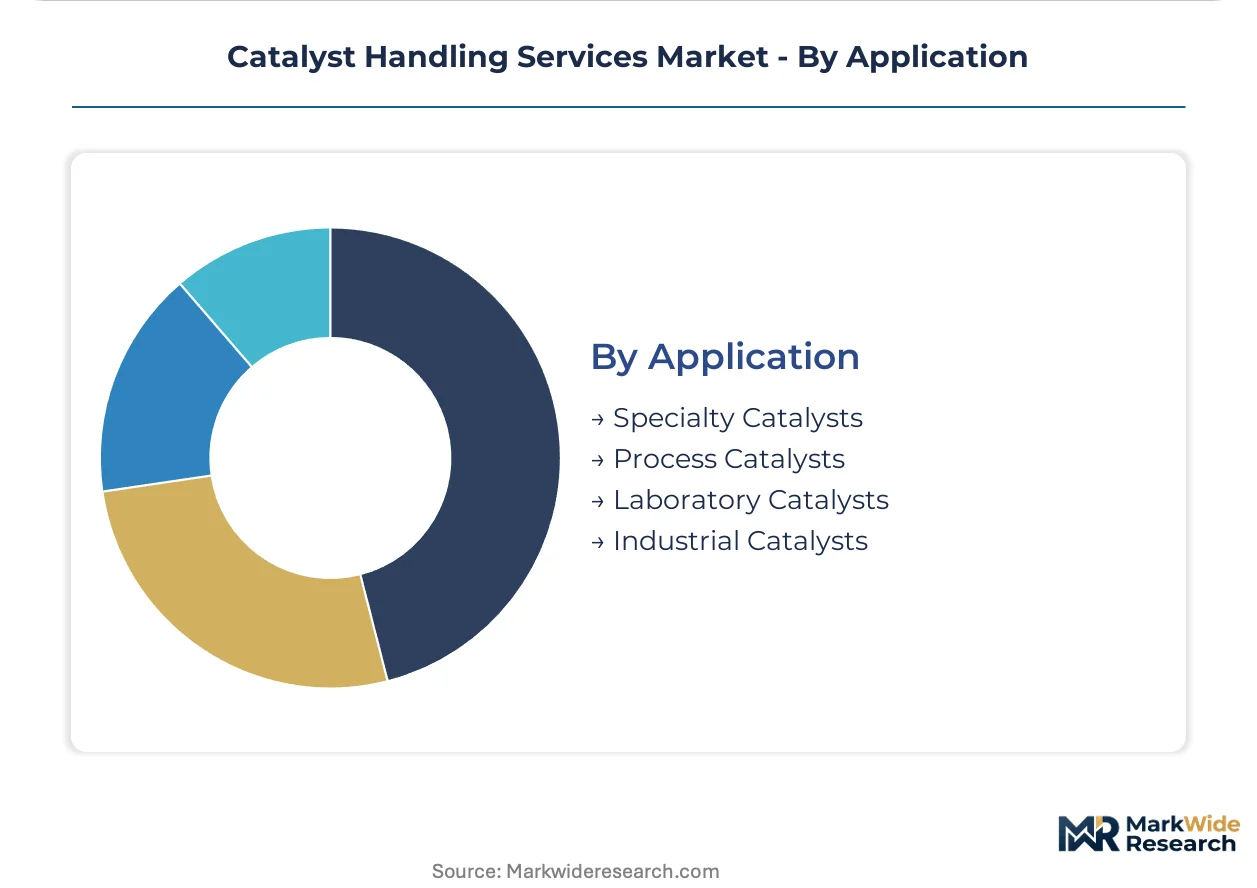
Application:
Catalyst function and batch scale determine handling protocol selection and automation economics.
- Process Catalysts:Fixed-bed and fluidized reactor extraction at industrial scale drives standardized regeneration workflows. Ceramic support media innovation cuts replacement frequency through advanced alumina formulations.
- Industrial Catalysts:Large-volume petrochemical and refining applications justify permanent on-site handling infrastructure or dedicated service contracts.
- Specialty Catalysts:Custom formulations for fine chemical synthesis require tailored extraction protocols and metal recovery tracking.
- Laboratory Catalysts:R&D batch sizes remain below automation threshold, sustaining manual protocols and creating underserved demand for miniaturized robotic systems.
Scale efficiency sits with Process Catalysts. Technology gap is widest in Laboratory Catalysts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the Gujarat coast concentrate new petrochemical buildout, while Gulf Coast refining corridors sustain mature catalyst service demand. Tax incentives in Saudi Arabia's Eastern Province and India's Petroleum, Chemicals and Petrochemicals Investment Regions redirect capital toward integrated refining-petrochemical hubs.
United States
Hydrotreating unit expansions along the Texas-Louisiana corridor accelerate turnaround frequency under EPA Tier 3 sulfur mandates. OSHA Process Safety Management standards compel outsourcing to certified specialists rather than in-house maintenance teams. The Port Arthur and Lake Charles petrochemical clusters generate continuous demand for nitrogen-inerted reactor entry protocols.
India
Reliance Industries and Nayara Energy expand refining capacity along the Gujarat coast, outpacing domestic specialist supply. The Petroleum, Chemicals and Petrochemicals Investment Region offers tax holidays and duty exemptions for catalyst-intensive process units. Dahej and Hazira industrial zones anchor the fastest-growing demand vertical for hydrogen-production catalyst swaps.
Germany
REACH authorization requirements for cobalt and nickel compounds tighten spent catalyst tracking obligations across the Rhine-Ruhr chemical corridor. ECHA mandates cradle-to-grave documentation that extends liability to handling contractors. The Antwerp-Rotterdam-Rhine-Ruhr cluster integrates blockchain-based chain-of-custody systems into logistics operations.
Saudi Arabia
ARAMCO-operated facilities with centralized procurement functions unbundle catalyst supply from handling services. The country's national industrial regulator enforces sulfur-reduction targets aligned with refined product export specifications. The Jubail and Yanbu industrial cities sustain demand for specialized reactor-entry protocols in hydrocracking and reforming units.
Netherlands
Vacuum-transfer catalyst extraction technology modularizes across Rotterdam and Antwerp refinery contracts. EU F-Gas Regulation and REACH compliance restrict disposal to licensed regeneration providers. The Port of Rotterdam chemical cluster enables capital-light mobilization of containerized suction systems between facilities.
Catalyst Handling Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated catalyst producers historically bundling supply and handling while independent service providers capture unbundled procurement contracts. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive handling divisions, regional specialists with proprietary extraction technologies, and asset-light contractors competing on mobilization speed. Market consolidation proceeds through strategic partnerships between equipment technology licensors and field service operators, while geographic expansion targets underpenetrated petrochemical clusters.
Within the multinational integrated tier, BASF SE and Johnson Matthey PLC exemplify archetypes that combine catalyst manufacturing with handling logistics. Mourik occupies a position among European specialists deploying proprietary vacuum-transfer systems. Dickinson Group of Companies and ANABEEB represent regional contractors competing on turnaround mobilization timelines across Middle Eastern and African refining corridors.
| Leading Market Players |
|---|
| W. R. Grace & Co.–Conn. |
| Mourik |
| Johnson Matthey PLC |
| CR3 |
| ANABEEB |
| BASF SE |
| Albemarle Corporation |
| Dickinson Group of Companies |
| Shell Catalysts & Technologies B.V. |
| Others |
Supply Flow & Price Mechanics
Platinum group metal volatility cascades through catalyst handling contract structures, with spot palladium and rhodium price swings forcing service providers to index regeneration fees against London Metal Exchange benchmarks. Turnaround procurement teams at Gulf Coast refiners now negotiate cost-plus arrangements that transfer metal recovery risk to handling contractors, compressing margins when commodity markets crater while rewarding specialists with integrated reclamation capabilities.
Pricing Analysis
Premium pricing attaches to guaranteed turnaround windows under seventy-two hours, while standard-rate contracts accommodate flexible scheduling with thirty-day mobilization horizons. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—OSHA Process Safety Management compliance and confined-space entry protocols command tier-one positioning. Cost compression in mid-tier regeneration services is intensifying because European licensed-provider concentration under REACH restricts cross-border competition. Small-batch laboratory handling shows highest price sensitivity as R&D budgets face fixed overhead allocation pressures.
Supply Chain Analysis
India's Petroleum, Chemicals and Petrochemicals Investment Region local-content mandates are reshaping sourcing, requiring foreign handling specialists to partner with domestic contractors for tax-exempt project eligibility. Equipment fabrication draws from Germany, the Netherlands, and the United States, where vacuum-transfer system engineering expertise concentrates. Ceramic alumina support media and nitrogen-inerting gas supply chains face single-source vulnerability from specialty chemical producers in the Antwerp-Rotterdam-Rhine-Ruhr cluster. Distribution runs through regional service hubs that mobilize containerized extraction systems between Rotterdam, Hamburg, and Gulf Coast ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catalyst handling services are becoming a vertical-integration race as OEM catalyst manufacturers pursue captive control over changeout execution to defend bundled margin pools. Backward integration into metal reclamation and regeneration infrastructure represents the decisive upstream lever.
For Market Incumbents: Cement market position by acquiring certified regional contractors in India's Gujarat corridor before domestic specialist supply catches up with Reliance Industries and Nayara Energy expansion. Invest in blockchain-based chain-of-custody systems to preempt ECHA documentation mandates that extend liability to handling contractors. Vertical integration into robotic confined-space entry technology defends against safety-equipment vendors encroaching on service margins. For New Entrants and Emerging Players: Miniaturized robotic extraction systems for laboratory catalyst applications offer a technology-first wedge into an underserved segment where manual handling persists due to sub-economic batch scales. Target pharmaceutical R&D clusters in Switzerland and Massachusetts where specialized catalyst formulations command handling premiums. Pursue licensing arrangements with vacuum-transfer equipment fabricators rather than seven-figure capex deployment. For Investors and Strategic Acquirers: ARAMCO-operated facilities unbundling catalyst supply from handling services is the leading indicator that procurement bifurcation will spread to European majors with centralized purchasing functions. Mid-size specialists with proprietary reactor-entry protocols and established OSHA technician pipelines represent prime acquisition archetypes over the coming decade. Watch for carbon-border adjustment mechanism implementation timing as the inflection signal that will structurally advantage licensed European regeneration providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Reclamation | Captures platinum and palladium recovery margins that currently leak to third-party refiners. |
| Robotic Confined-Space Entry Deployment | Eliminates OSHA technician scarcity constraints while commanding safety-premium contract pricing. |
| Blockchain Chain-of-Custody Implementation | Satisfies ECHA cradle-to-grave documentation mandates before competitors achieve compliance. |
| Regional Hub Modularization | Enables capital-light mobilization between Rotterdam, Antwerp, and Hamburg without fixed infrastructure. |
| Laboratory-Scale Automation Development | Addresses R&D catalyst handling white space where batch sizes resist standard robotic economics. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across refinery turnaround managers, catalyst procurement leads, and regeneration facility operators. ECHA authorization databases, EPA compliance disclosures, and SEC 10-K filings provided downstream demand validation. Bottom-up service contract aggregation and top-down refining capacity modeling enabled triangulation across geographic clusters.
Granularity-level framing applied service-type segmentation by regeneration, replacement, transportation, and maintenance modalities, with technology tiering across robotic, automated, safety-equipment, and manual handling protocols. End-use verticals modeled at refinery, petrochemical, chemical, and pharmaceutical levels. CAGRs derived from weighted capacity expansion pipelines and mandated turnaround frequency shifts. Hydrogen production catalyst swap demand and alumina formulation replacement cycles served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including force-majeure disruption to platinum group metal supply chains and unanticipated regulatory relaxation of sulfur-reduction mandates. Forecasts reflect assumptions about technician certification pipeline throughput and robotic adoption curves among mid-size refiners. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Chemical Processing Catalysts Market
Catalysts
Environmental Catalysts Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Organic Catalyst Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Global Zeolites Market