
 Natural Zeolites Market | 2026-2036
Natural Zeolites Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Zeolites Market Intelligence
Long-term supply agreements for clinoptilolite feedstock is pivoting how producers secure margin stability. International Zeolite Corp. anchors its position through direct mining control in British Columbia. Imerys leverages its industrial minerals portfolio to cross-sell zeolites into construction and filtration channels. Zeotech Corporation specializes in synthetic-natural hybrid materials for advanced separation applications.
Natural zeolites are hydrated aluminosilicate minerals with microporous crystalline structures, typically exhibiting pore diameters between 0.3 and 2 nanometers and cation-exchange capacities reaching 200-400 meq per 100 grams. These properties enable selective adsorption of gases, liquids, and ionic species across water purification, soil amendment, and gas separation processes. Clinoptilolite dominates volume flows due to its abundance in sedimentary deposits and proven efficacy in ammonia capture, while water treatment applications command premium pricing from municipal and industrial end users facing tighter effluent mandates. Construction applications remain mature with steady offtake for lightweight aggregate and pozzolanic cement additives.
EPA discharge regulations under the Clean Water Act compel utilities to upgrade ammonia and heavy metal removal systems, directly expanding clinoptilolite procurement. REACH registration requirements in Europe restrict synthetic alternatives in certain consumer-facing applications, reinforcing natural zeolite positioning. USDA organic certification standards for soil amendments create a regulated channel where only unmodified mineral products qualify. Stakeholders must track evolving state-level PFAS treatment mandates to anticipate which zeolite functionalities will command priority investment.
Market Dynamics
EPA ammonia discharge limits under the Clean Water Act are forcing municipal water utilities to retrofit legacy filtration infrastructure with clinoptilolite-based ion exchange systems, compressing procurement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- Clean Water Act compliance mandates:EPA discharge standards for ammonia and heavy metals compel utilities across the United States to deploy clinoptilolite filtration, creating sustained procurement pull from municipal treatment plants.
- USDA organic certification pathways:Soil amendment producers qualify for premium agricultural channels by using unmodified natural zeolites, locking out synthetic competitors from certified organic supply chains.
- Turkey's Anatolian deposit concentration:The world's largest accessible clinoptilolite reserves enable Turkish exporters to anchor long-term feedstock contracts with European and Asian water treatment integrators.
Market Restraints
- Energy-intensive thermal activation:Natural zeolites require calcination at 400-600°C to optimize cation-exchange capacity, exposing producers to natural gas price volatility and carbon cost exposure under EU ETS mechanisms.
- Deposit geographic concentration:Clinoptilolite supply concentrates in Turkey, the United States, and China, creating single-source vulnerability for processors without backward integration into captive mining assets.
- Synthetic zeolite substitution:Uniform pore-size synthetic variants manufactured by petrochemical and detergent chemical producers threaten natural zeolite positioning in gas separation and catalysis applications.
Strategic Opportunities
- PFAS remediation mandates:Emerging state-level regulations in the United States targeting per- and polyfluoroalkyl substances create demand for modified natural zeolites with enhanced fluorocarbon adsorption capacity.
- Carbon capture integration:Post-combustion carbon dioxide separation systems are absorbing natural zeolite membranes as lower-energy alternatives to amine scrubbing, opening industrial gas processing channels.
- Direct-to-farm distribution platforms:Agricultural input marketplaces bypass traditional wholesale distributors, enabling zeolite producers to capture margin from precision agriculture adopters in Australia's wheat belt and California's Central Valley.
Industry Challenges
- REACH registration timelines:European Chemicals Agency dossier preparation for modified zeolite products extends 18-24 months, delaying market entry for functionalized grades targeting pharmaceutical and food-contact applications.
- Process engineering talent scarcity:Ion exchange system design expertise concentrates among legacy water treatment engineering firms, constraining zeolite producers' ability to offer integrated solution packages without partnership dependency.
- Legacy infrastructure retrofit complexity:Municipal utilities operate sand filtration and activated carbon systems with decades of depreciation remaining, requiring zeolite suppliers to finance demonstration pilots to overcome incumbent asset inertia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Zeolites Market |
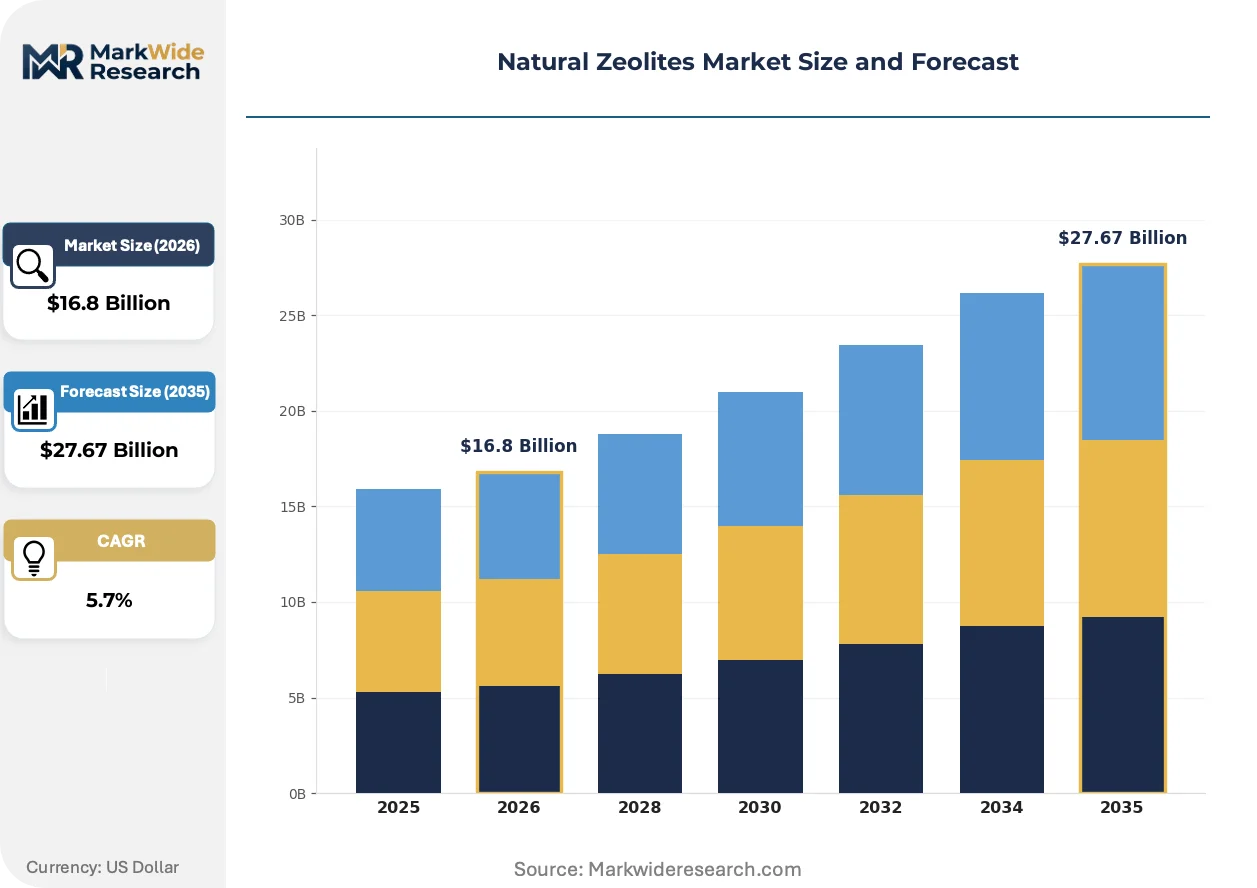
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinoptilolite, Mordenite, Faujasite, Chabazite Application: Agriculture, Water Treatment, Construction, Animal Feed End User: Agriculturists, Environmentalists, Construction Firms, Feed Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | International Zeolite Corp., ZEOCEM a.s., Imerys, KMI Zeolite Inc., Zeotech Corporation, Bear River Zeolite Co., St. Cloud Mining, Rota Mining Corporation, Maruti Mineral Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Zeolites Market Strategic Shifts & Innovations
Surface functionalization chemistry and hybrid synthetic-natural composite structures are absorbing capital allocation from major industrial mineral processors, compressing the performance gap between commodity clinoptilolite and engineered adsorbents.
Hybrid clinoptilolite-silica composites are absorbing research investment from separation technology developers seeking to combine natural zeolite cost structures with synthetic material pore uniformity. Municipal water utilities in Germany and the Netherlands pilot these materials for simultaneous ammonia and micropollutant removal. The technology is absorbing market share from standalone activated carbon in multi-contaminant treatment trains by reducing bed volume requirements and regeneration frequency.
REACH restrictions on synthetic zeolite precursors in consumer-facing applications are redirecting formulation chemists toward unmodified natural grades for detergent builders and odor control products. ECHA substance evaluation dossiers on sodium aluminosilicates have triggered substitution planning across European household chemical manufacturers. Personal care and home care brands now specify natural zeolite certificates of analysis to preempt regulatory friction and satisfy retailer sustainability scorecards.
Long-term offtake contracting is displacing spot purchasing among North American municipal utilities seeking price predictability through multi-year clinoptilolite supply agreements. Procurement departments negotiate five-to-seven-year indexed contracts directly with mine operators, bypassing traditional distributor intermediaries. California and Texas water authorities lead this pattern, using master service agreements to lock in activated zeolite volumes against construction cost escalation in treatment plant expansion projects.
Natural Zeolites Market Segmentation
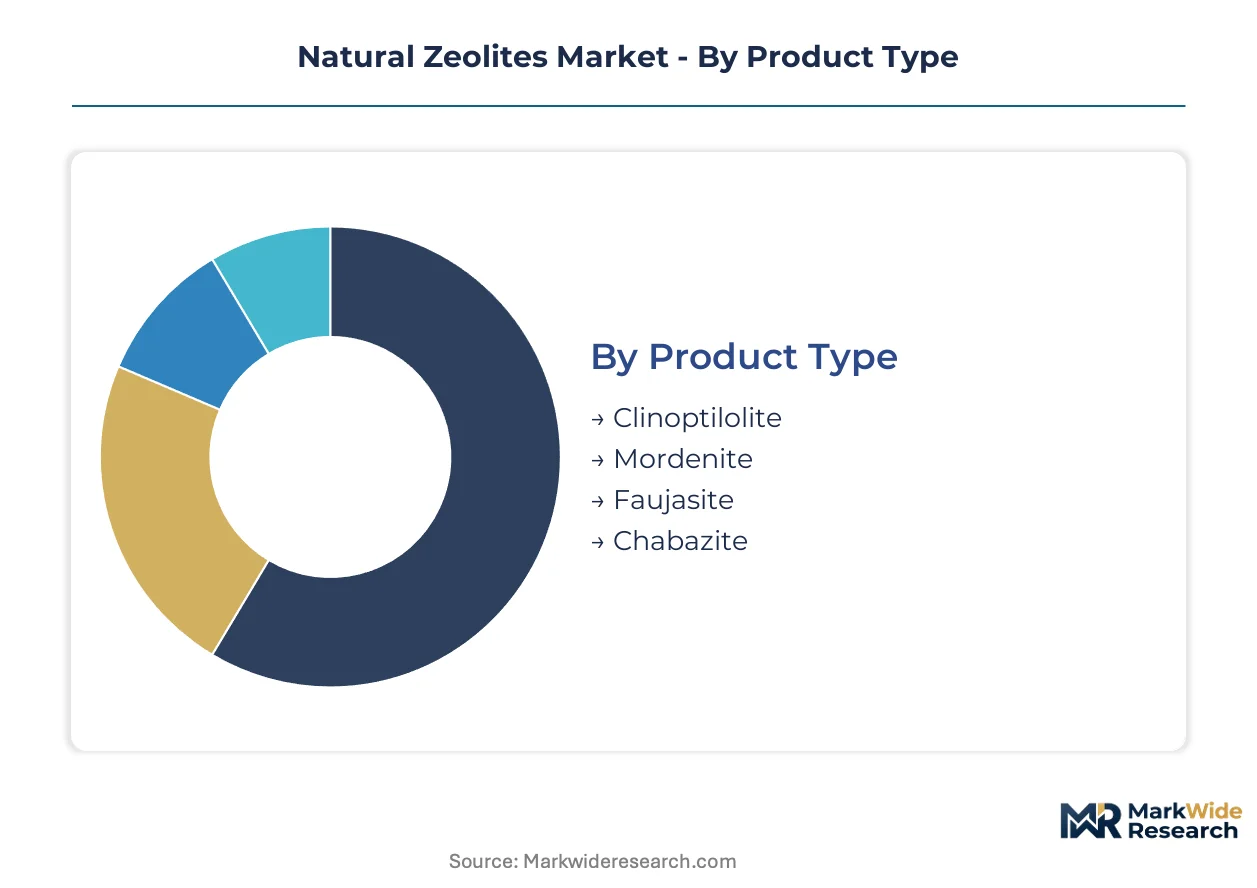
Segmentation in natural zeolites tracks how mineral grades map to regulatory thresholds across water treatment, agriculture, and construction channels. Product certification requirements vary sharply by end-use, creating tiered margin structures that reward compliant producers.
Product Type:
Certification burdens cluster around cation-exchange capacity testing for water treatment grades, with agriculture-facing segments requiring USDA organic compliance and construction applications demanding ASTM pozzolanic certification.
- Clinoptilolite:Sedimentary-origin zeolite with 2.2-4.4 Å channel apertures and 220 meq/100g cation-exchange capacity. Municipal utilities in California and Texas specify this grade for ammonia removal under EPA Clean Water Act discharge permits.
- Mordenite:Fibrous crystalline structure with higher thermal stability than clinoptilolite variants. Industrial gas separation applications in Germany and Japan absorb mordenite for acid gas scrubbing where synthetic zeolite costs prove prohibitive.
- Faujasite:Large-pore framework (7.4 Å supercage) suited for hydrocarbon cracking catalyst precursors. Petrochemical refiners in the US Gulf Coast and Rotterdam harbor zone source faujasite for fluid catalytic cracking unit feedstock.
- Chabazite:Small-pore rhombohedral structure with selective CO2 adsorption properties. Post-combustion carbon capture pilot projects in Norway and Canada trial chabazite membranes against amine-based scrubbing systems.
Clinoptilolite sits at the top of the volume ranking, with chabazite climbing the fastest on carbon capture pilot demand.
Application:
Cost tiering separates premium-priced water treatment grades from commodity construction aggregates, with agricultural amendments occupying a mid-tier pricing band tied to organic certification premiums.
- Water Treatment:EPA ammonia discharge limits compel municipal utilities to deploy clinoptilolite ion exchange systems. German and Dutch utilities pilot hybrid clinoptilolite-silica composites for simultaneous ammonia and micropollutant removal.
- Agriculture:Soil amendment producers qualify for USDA organic certification channels using unmodified natural zeolites. Australia's wheat belt and California's Central Valley drive precision agriculture demand through direct-to-farm distribution platforms.
- Construction:Lightweight aggregate and pozzolanic cement additive applications absorb steady offtake. Turkish exporters anchor long-term supply contracts with European construction integrators seeking ASTM C618-compliant supplementary cementitious materials.
- Animal Feed:Mycotoxin binding and ammonia control in livestock operations. Feed manufacturers in Brazil and Vietnam specify zeolite grades for poultry and swine ration formulations under national veterinary feed directive compliance.
Water treatment commands the steepest expansion trajectory, while construction maintains the largest installed base.
End User:
Customer type determines procurement sophistication, with municipal utilities negotiating multi-year indexed contracts and agricultural operators shifting toward spot purchasing through digital marketplaces.
- Agriculturists:Organic-certified crop producers and precision agriculture adopters. Australian broadacre wheat farmers and California almond growers purchase clinoptilolite soil amendments through direct-to-farm platforms bypassing traditional wholesale distributors.
- Environmentalists:Remediation contractors and conservation NGOs. PFAS treatment mandates in US state-level regulations drive demand for surface-functionalized zeolites with enhanced fluorocarbon adsorption capacity.
- Construction Firms:Ready-mix concrete producers and infrastructure contractors. Turkish, Chinese, and US Gulf Coast construction markets absorb clinoptilolite lightweight aggregate for structural concrete density reduction.
- Feed Manufacturers:Compound feed mills and premix blenders. Brazilian and Southeast Asian poultry integrators specify zeolite inclusion rates for aflatoxin binding under national feed safety regulations.
Environmentalists represent the fastest-growing customer category, with construction firms holding the deepest procurement volumes.
Distribution Channel:
Supply chain configuration separates bulk mineral handlers from specialized technical distributors, with channel choice correlating to end-user technical support requirements and order scale thresholds.
- Direct Sales:Mine operators contract directly with municipal utilities and large agricultural cooperatives. California and Texas water authorities negotiate five-to-seven-year master service agreements locking in activated zeolite volumes.
- Online Retail:Agricultural input marketplaces and industrial mineral platforms. Australian and US Midwest farmers purchase bagged soil amendments through digital channels with certificate-of-analysis transparency.
- Distributors:Technical chemical distributors serving water treatment engineering firms. REACH-registered zeolite grades flow through European specialty chemical distributors with ECHA dossier compliance documentation.
- Wholesale:Construction aggregate dealers and feed ingredient traders. Bulk clinoptilolite moves through Turkish mineral exporters to Middle East and Asian construction markets via commodity trading houses.
Direct sales capture the largest transaction values, with online retail gaining share fastest among agricultural end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey clinoptilolite exports outpace United States domestic consumption volumes, while Chinese processors absorb expanding shares of Asia-Pacific water treatment procurement.
United States
California and Texas municipal utilities deploy clinoptilolite ion exchange systems for EPA Clean Water Act ammonia discharge compliance. The EPA's tightening effluent standards compress procurement cycles for activated zeolite volumes. Denver-based Bear River Zeolite Co. anchors supply contracts with Mountain West water authorities retrofitting legacy sand filtration infrastructure.
Turkey
The Anatolian zeolite belt hosts the world's largest accessible clinoptilolite sedimentary deposits. Turkish exporters leverage this geological concentration to lock multi-year feedstock agreements with European water treatment integrators. İzmir and Eskişehir processing clusters supply activated grades to German and Dutch utilities piloting hybrid clinoptilolite-silica composites.
Germany
Municipal utilities in the Rhine-Ruhr and Bavaria regions pilot hybrid clinoptilolite-silica materials for simultaneous ammonia and micropollutant removal. ECHA REACH registration requirements restrict synthetic zeolite alternatives in consumer-facing detergent formulations. Cologne-area chemical distributors channel REACH-registered natural grades into household product supply chains.
China
Industrial gas separation applications in the Yangtze River Delta absorb mordenite for acid gas scrubbing where synthetic zeolite costs prove prohibitive. The Ministry of Ecology and Environment enforces tightening wastewater discharge standards across manufacturing zones. Shandong Province zeolite processors supply activated clinoptilolite to municipal utilities in the Beijing-Tianjin-Hebei corridor.
Australia
Broadacre wheat farmers in New South Wales and Victoria purchase clinoptilolite soil amendments through direct-to-farm digital platforms bypassing wholesale distributors. The country's organic certification standards create regulated channels where unmodified mineral products qualify for premium agricultural inputs. Perth-based technical distributors serve precision agriculture adopters in the Western Australia wheat belt.
Natural Zeolites Market Key Industry Players
Top-tier vendors anchor long-term municipal utility contracts, while mid-tier processors compete on agricultural amendment spot pricing. Supply-side concentration centers on Turkish mining assets and North American sedimentary deposits. Three strategic archetypes dominate: captive mine operators with direct sales channels, industrial mineral conglomerates cross-selling construction and filtration grades, and synthetic-natural hybrid specialists targeting advanced separation. Competitive moves concentrate on backward integration into mining assets and five-to-seven-year indexed offtake contracting with water authorities.
Within the captive mining tier, International Zeolite Corp. and Bear River Zeolite Co. exemplify North American operators securing margin stability through direct deposit control. Imerys occupies a position representing the industrial mineral conglomerate archetype, leveraging cross-channel portfolio breadth. Zeotech Corporation anchors the hybrid specialist vector, targeting functionalized grades for emerging PFAS and carbon capture applications. These three company types collectively illustrate how procurement sophistication separates municipal utility direct contracting from agricultural spot purchasing.
| Leading Market Players |
|---|
| International Zeolite Corp. |
| ZEOCEM a.s. |
| Imerys |
| KMI Zeolite Inc. |
| Zeotech Corporation |
| Bear River Zeolite Co. |
| St. Cloud Mining |
| Rota Mining Corporation |
| Maruti Mineral Industries |
| Others |
Cost & Logistics Intelligence
Natural gas futures pricing at Henry Hub cascades through clinoptilolite activation costs, compressing margins for processors without captive thermal assets while Turkish exporters exploit Anatolian deposit proximity to European buyers.
Pricing Analysis
Capacity additions in Turkey are reshaping price floors for standard-grade clinoptilolite, forcing North American producers toward premium-certified water treatment tiers. Contract-based long-term offtake dominates municipal procurement, with price differentiation driven by cation-exchange capacity certification and volume scale. Cost compression in agricultural amendments intensifies as Australian direct-to-farm platforms bypass distributor markups. Feed manufacturers in Brazil exhibit highest price sensitivity; German utilities piloting hybrid composites show least.
Supply Chain Analysis
Dual-sourcing requirements from California and Texas water authorities mandate Turkish and domestic supplier qualification, fragmenting procurement leverage. Geographic supply concentrates in Turkey, the United States, and China. Raw material flows draw from sedimentary clinoptilolite deposits, natural gas for thermal activation, and silica precursors for hybrid composites. Single-source vulnerability threatens processors without backward integration into captive mining assets. Distribution runs through direct sales channels for municipal utilities and technical distributors for REACH-registered European grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Natural Zeolites Market functions as a geographic-arbitrage play: Turkish mining costs undercut North American thermal activation expenses, while EPA discharge mandates in the United States sustain premium pricing for compliant grades.
For Market Incumbents: Acquire sedimentary deposit assets in British Columbia or the Mountain West to anchor feedstock security against Turkish export pricing pressure. Secure five-to-seven-year indexed master service agreements with California and Texas water authorities before synthetic zeolite substitution threats intensify in gas separation applications.
For New Entrants and Emerging Players: EPA state-level PFAS mandates in the United States open a window for surface-functionalized clinoptilolite grades with enhanced fluorocarbon adsorption. Target environmental remediation contractors as the most penetrable segment, leveraging direct technical sales to bypass entrenched distributor relationships with municipal utilities.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid synthetic-natural specialists holding functionalization IP for carbon capture membranes. Five-to-ten year viability hinges on post-combustion CO2 separation pilot scale-up. Watch Norwegian and Canadian chabazite membrane demonstration results as the inflection signal for industrial gas processing channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive Anatolian or British Columbia deposits secure margin stability against feedstock volatility. |
| Long-term Supply Agreement | Five-to-seven-year indexed contracts with California water authorities lock in activated zeolite volumes. |
| Green Manufacturing Transition | Renewable thermal energy for clinoptilolite calcination reduces EU ETS carbon cost exposure. |
| Joint Venture | Hybrid clinoptilolite-silica partnerships with German utilities accelerate micropollutant removal adoption. |
| Capacity Expansion | Shandong Province activation facilities serve Beijing-Tianjin-Hebei corridor wastewater compliance demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with mine operators, municipal water utility procurement officers, agricultural cooperative managers, and REACH compliance consultants with secondary validation. Trade data from Turkish Mineral Exporters Association records, EPA enforcement and compliance databases, ECHA substance evaluation dossiers, and SEC filings from industrial mineral conglomerates anchored volume estimates. Bottom-up clinoptilolite shipment tallies triangulated against top-down water treatment capital expenditure surveys.
Historical reference periods anchored the projection horizon to observed procurement cycle compression following EPA Clean Water Act enforcement waves. Segmentation modeling tracked product type, application channel, end-user sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to municipal utility retrofit timelines and agricultural amendment adoption rates. Forecast inputs incorporated natural gas price volatility coefficients and state-level PFAS mandate implementation schedules.
Revisions become necessary when EU ETS carbon cost thresholds trigger activation facility closures or when Turkish export licensing restrictions materialize. Deviation in EPA effluent standard enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Catalyst Regeneration Market
Catalysts
Industrial Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Europe PGM Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
North America Industrial Catalyst Market
Catalysts
Polyolefin Catalyst Market