
 Pulmonary Embolism Market | 2026-2036
Pulmonary Embolism Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Embolism Market Intelligence
Hospital procurement of pulmonary embolism devices is tilting toward integrated thrombectomy platforms that combine aspiration and mechanical removal. Boehringer Ingelheim International GmbH leverages its anticoagulant portfolio to anchor long-term hospital contracts. Inari Medical Inc. specializes in catheter-based mechanical thrombectomy systems that compete directly with traditional lytic therapy. Pfizer Inc. extends its presence through direct-to-hospital distribution networks for parenteral anticoagulants.
Pulmonary embolism refers to the obstruction of pulmonary arteries by thrombi, typically originating from deep vein thrombosis in the lower extremities, with clinical severity classified by hemodynamic impact and right ventricular strain markers. The condition demands rapid therapeutic intervention to restore perfusion, prevent right heart failure, and reduce mortality in acute and subacute presentations. Anticoagulants occupy the largest revenue pool due to chronic outpatient maintenance requirements following index events. Surgical devices represent the fastest-expanding segment as interventional pulmonology programs proliferate across tertiary centers. Diagnostic imaging generates stable procedural volumes tied to emergency department chest pain protocols and CT pulmonary angiography utilization.
FDA 510(k) and PMA pathways govern device commercialization while EMA's MDR framework shapes European market access for thrombectomy systems and implantable filters. The EU AI Act introduces conformity requirements for AI-enabled diagnostic algorithms used in CT angiography interpretation, affecting software deployment across member states. Stakeholders must monitor evolving reimbursement thresholds for catheter-directed therapy versus systemic lysis as health technology assessments tighten across major markets.
Market Dynamics
Catheter-directed mechanical thrombectomy is displacing systemic fibrinolysis as the preferred intervention for intermediate-risk pulmonary embolism, forcing hospital systems to reconfigure interventional capabilities and procurement priorities around integrated aspiration platforms.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for catheter-based devices enable faster commercialization of next-generation thrombectomy systems, reducing time-to-revenue for device manufacturers targeting acute care settings.
- Interventional pulmonology program expansion:Tertiary centers in the United States, Germany, and Japan are scaling dedicated pulmonary embolism response teams, creating concentrated demand hubs for specialized equipment and training protocols.
- CT pulmonary angiography protocol standardization:Emergency department chest pain pathways now mandate rapid imaging workflows, expanding the addressable patient pool eligible for catheter-directed intervention before hemodynamic collapse.
Market Restraints
- Reimbursement compression for catheter-directed therapy:Health technology assessments in Germany and Japan are tightening payment thresholds relative to systemic lysis, constraining hospital margins on high-acuity procedures.
- Specialized operator scarcity:The limited pipeline of interventional radiologists and pulmonologists trained in mechanical thrombectomy creates procedural bottlenecks even where capital equipment exists.
- Anticoagulant maintenance economics:Chronic outpatient therapy with direct oral anticoagulants dominates lifetime cost curves, diverting capital budgets away from acute interventional device procurement.
Strategic Opportunities
- Submassive PE risk stratification algorithms:AI-enabled CT interpretation tools qualifying under the EU AI Act conformity framework create software-hardware bundling potential for integrated diagnostic-interventional platforms.
- Ambulatory thrombectomy centers:Freestanding interventional facilities in the United States are emerging as alternative sites of care, bypassing traditional hospital capital allocation cycles for device placement.
- Japan's aging-related DVT burden:Demographic compression in the Asia-Pacific's largest geriatric population is expanding the incident PE cohort faster than interventional capacity, creating supply-demand asymmetry.
Industry Challenges
- Proctoring and credentialing timelines:Hospital privileging requirements for mechanical thrombectomy extend 12-18 months, delaying device utilization post-purchase and complicating sales cycle forecasting.
- Legacy lytic therapy infrastructure:Existing pharmacy contracts and nursing protocols for systemic thrombolysis create organizational inertia against catheter-based protocol adoption despite superior safety profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Embolism Market |
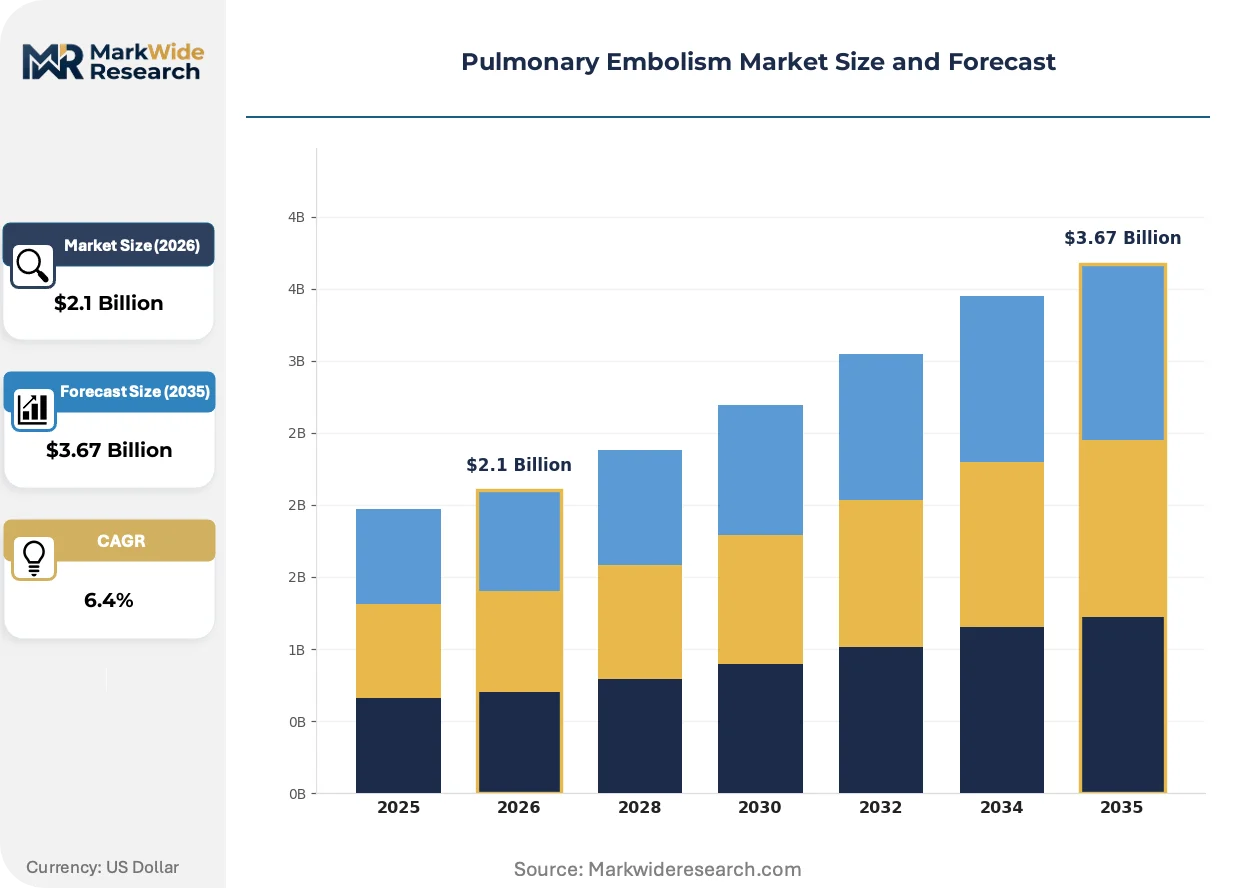
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Thrombolytics, Surgical Devices, Diagnostic Imaging Application: Prevention, Treatment, Diagnosis, Monitoring End User: Hospitals, Outpatient Clinics, Emergency Rooms, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation |
| Companies Covered | Merck & Co. Inc., Boehringer Ingelheim International GmbH, Pfizer Inc., Sanofi S.A., Bristol Myers Squibb Company, Johnson & Johnson, Bayer AG, Inari Medical Inc., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Embolism Market Strategic Shifts & Innovations
Device architectures are converging around single-session clot removal, compressing the traditional multi-day treatment arc and reshaping how hospitals value speed versus completeness of revascularization.
Next-generation aspiration catheters incorporate proximal flow interruption and large-bore extraction lumens. Interventional teams at high-volume centers are migrating from standalone mechanical devices to hybrid platforms combining aspiration with maceration. This technological convergence is compressing the addressable market for pure lytic therapy while expanding the procedural envelope to submassive presentations previously managed medically.
The EU AI Act introduces conformity requirements for machine-learning algorithms deployed in CT pulmonary angiography interpretation. Software vendors must now document training data provenance and performance validation across member-state populations. Diagnostic imaging segments with EU market exposure are restructuring quality management systems to satisfy notified body scrutiny of algorithmic decision support.
Hospital purchasing committees are consolidating vendor relationships around full-procedure platforms rather than discrete device categories. Integrated contracts spanning diagnostic imaging, interventional catheters, and post-procedure monitoring are displacing fragmented procurement of individual components. This behavioral shift concentrates account control with manufacturers capable of bundling hardware, software, and clinical support services.
Pulmonary Embolism Market Segmentation
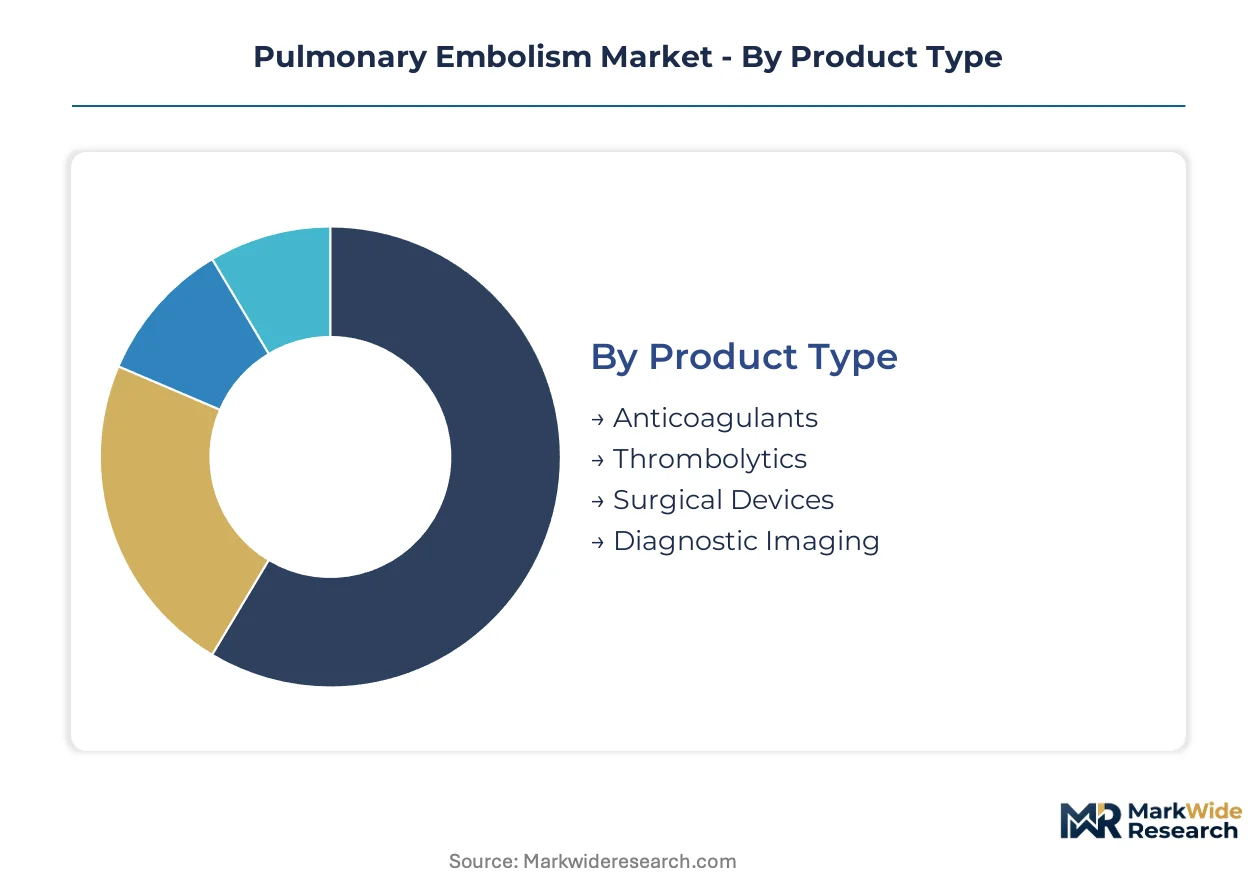
Pulmonary embolism care pathways fragment across acute intervention, chronic maintenance, and diagnostic triage. Each segment carries distinct procurement cycles, reimbursement logic, and clinical stakeholder ownership that shape vendor access strategies.
Product Type:
Cost tier differentiation separates chronic pharmaceutical maintenance from capital-intensive acute interventions.
- Anticoagulants:Direct oral anticoagulants and parenteral heparins dominate lifetime therapy costs across outpatient settings. Chronic prescription volumes in the United States and Germany anchor manufacturer revenue stability through pharmacy benefit contracts.
- Thrombolytics:Systemic fibrinolytic agents face utilization pressure as mechanical thrombectomy displaces lytic-first protocols. Demand concentrates in emergency departments without interventional radiology coverage.
- Surgical Devices:Catheter-based mechanical thrombectomy systems and aspiration platforms are expanding most quickly as tertiary centers scale PE response teams. Device procurement cycles align with interventional program buildouts.
- Diagnostic Imaging:CT pulmonary angiography protocols and AI-enabled interpretation software generate stable procedural volumes tied to emergency chest pain pathways.
Anticoagulants hold installed capacity. Surgical devices are rotating up the share rankings.
Application:
Clinical workflow position determines technology selection and purchasing authority.
- Prevention:Pharmacologic prophylaxis in post-surgical and immobilized patients drives anticoagulant prescribing in hospital discharge protocols. United States health system formularies prioritize DOACs over warfarin for VTE prevention.
- Treatment:Acute intervention spans systemic lysis, catheter-directed therapy, and surgical embolectomy based on hemodynamic stratification. Japan's aging population is expanding the submassive PE cohort eligible for mechanical thrombectomy.
- Diagnosis:D-dimer testing and CT angiography form the diagnostic backbone, with AI algorithms qualifying under EU AI Act conformity requirements.
- Monitoring:Anticoagulant therapeutic drug monitoring and post-discharge surveillance programs create recurring revenue streams for laboratory services and remote patient monitoring platforms.
Treatment commands capital budgets. Prevention absorbs pharmaceutical spend.
End User:
Customer type dictates contract structure and sales cycle complexity.
- Hospitals:Integrated delivery networks consolidate procurement of thrombectomy platforms, diagnostic imaging, and anticoagulant formularies through value analysis committees. Germany's DRG-based reimbursement shapes device selection for intermediate-risk PE.
- Outpatient Clinics:Anticoagulation management and follow-up imaging generate recurring visit volumes in cardiology and hematology practices. United States Medicare reimbursement for office-based ultrasound supports DVT surveillance.
- Emergency Rooms:Chest pain protocol standardization and rapid CT availability determine PE detection rates and downstream intervention eligibility.
- Rehabilitation Centers:Post-acute facilities manage ambulatory anticoagulation and functional recovery following massive PE events.
Hospitals anchor device revenue. Outpatient clinics are rotating up the share rankings.
Delivery Mode:
Route of administration shapes manufacturing scale, distribution requirements, and patient compliance economics.
- Oral:Direct oral anticoagulants eliminate monitoring requirements and dietary restrictions of warfarin, capturing outpatient maintenance prescriptions. Patient adherence programs target Germany and Japan's elderly populations.
- Intravenous:Unfractionated heparin and thrombolytic infusion remain essential for acute inpatient management and peri-procedural bridging. United States hospital pharmacy contracts favor concentrated heparin formulations.
- Subcutaneous:Low-molecular-weight heparin and fondaparinux serve bridging therapy and outpatient prophylaxis where oral agents are contraindicated.
- Inhalation:Investigational inhaled anticoagulants and thrombolytics target localized pulmonary delivery with reduced systemic bleeding risk.
Oral formulations hold installed capacity. Intravenous delivery maintains acute care indispensability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor the United States as the dominant geography, with EMA's MDR framework and Japan's PMDA shaping complementary demand centers. Hospital procurement patterns diverge across these three markets based on reimbursement structure and interventional capacity.
United States
Integrated delivery networks in Texas and Florida are consolidating thrombectomy platform procurement through value analysis committees. Medicare reimbursement adjustments for catheter-directed therapy influence hospital capital allocation priorities. The Cleveland Clinic and Mayo Clinic anchor high-volume PE response team development in the Midwest.
Germany
DRG-based reimbursement for intermediate-risk PE tightens payment thresholds relative to systemic lysis, compressing hospital margins on mechanical procedures. EMA's MDR framework governs device commercialization timelines for thrombectomy systems. Berlin and Munich tertiary centers are scaling dedicated interventional pulmonology programs.
Japan
Demographic compression expands the incident PE cohort faster than interventional capacity, creating supply-demand asymmetry in Kanto and Kansai regions. PMDA regulatory pathways shape market entry for aspiration catheter platforms. Osaka University Hospital anchors training protocol standardization for mechanical thrombectomy.
United Kingdom
NICE health technology assessments scrutinize cost-effectiveness of catheter-directed therapy versus standard care in NHS trusts. London and Manchester academic medical centers are piloting AI-enabled CT interpretation workflows under emerging conformity requirements. Regional procurement collaboratives consolidate anticoagulant formulary decisions.
Australia
TGA regulatory timelines influence device commercialization sequencing for Asia-Pacific expansion strategies. Melbourne and Sydney teaching hospitals are building PE response team capabilities aligned with US protocol models. Private hospital chains are bypassing public sector capital constraints through direct device procurement.
Pulmonary Embolism Market Key Industry Players
Pharmaceutical incumbents and interventional device specialists split the market across chronic maintenance and acute intervention vectors. Anticoagulant manufacturers leverage pharmacy benefit contracts to anchor recurring revenue streams. Device vendors compete for capital budget allocation against established lytic therapy infrastructure. Consolidation activity concentrates among catheter-based platform developers seeking integrated diagnostic-interventional positioning.
Among established pharmaceutical manufacturers, Boehringer Ingelheim International GmbH and Pfizer Inc. exemplify the chronic therapy anchoring archetype through anticoagulant portfolio depth. Inari Medical Inc. occupies a specialized position representing the interventional device vector. These three entities collectively illustrate the competitive tension between pharmaceutical maintenance economics and acute procedural platform capture.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Boehringer Ingelheim International GmbH |
| Pfizer Inc. |
| Sanofi S.A. |
| Bristol Myers Squibb Company |
| Johnson & Johnson |
| Bayer AG |
| Inari Medical Inc. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Cost & Logistics Intelligence
Minneapolis-based thrombectomy device manufacturing clusters anchor North American supply capacity, with their production scale directly translating into pricing leverage over hospital purchasing committees negotiating integrated platform contracts.
Pricing Analysis
United States-Germany price spreads for catheter-directed thrombectomy systems reach three-to-one multiples, reflecting divergent reimbursement frameworks and capital budget cycles. Three-tier pricing structure across premium aspiration platforms, standard mechanical devices, and economy lytic alternatives dominates procurement negotiations. Pricing pressure stems from DRG-based payment compression in German tertiary centers, forcing margin concessions on intermediate-risk PE procedures. Emergency departments without interventional radiology coverage exhibit highest price sensitivity, while academic medical centers with dedicated PE response teams prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for nitinol catheter components and precision aspiration lumens. Manufacturing concentration in United States, Germany, and Japan feeds global device availability, with each hub serving distinct regulatory certification requirements. Raw material dependencies on medical-grade polymers, shape-memory alloys, and sterile packaging materials create input cost volatility. Single-source vulnerability persists for specialized catheter extrusion capabilities. Distribution runs through hospital value analysis committees and group purchasing organizations, with direct-to-hospital contracting gaining share among integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
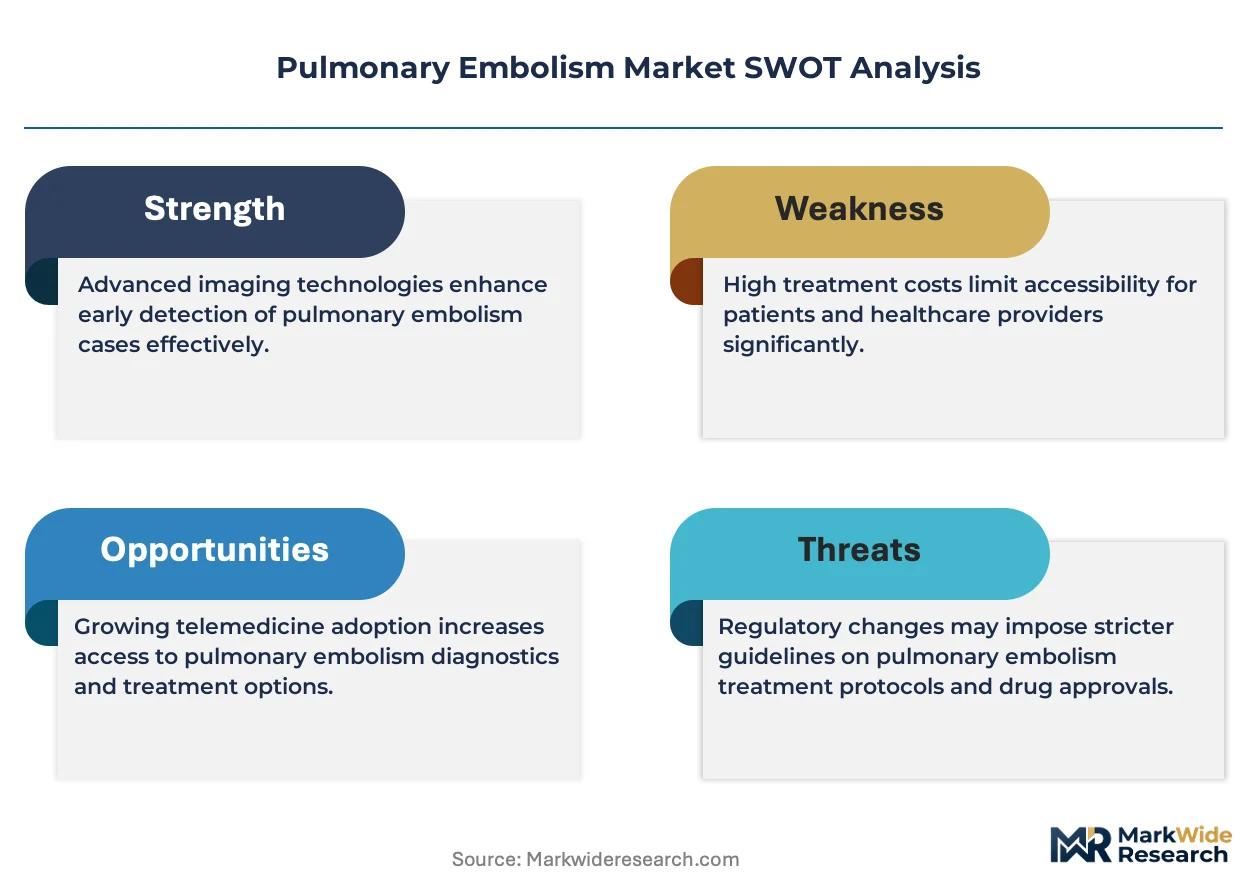
This market exhibits defensive-moat characteristics anchored in FDA 510(k) regulatory entrenchment, where clearance timelines and clinical data requirements create substantial barriers to rapid competitive replication.
For Market Incumbents: Build switching-cost moats through long-term hospital system partnerships that embed training protocols and proctoring services into device contracts. Anchor procurement relationships via integrated diagnostic-interventional platform bundling that raises replacement costs for competitors. Deepen backward integration into catheter manufacturing to secure nitinol supply against tariff volatility. Counter emerging mechanical thrombectomy specialists by accelerating software companion development for AI-enabled CT interpretation workflows. For New Entrants and Emerging Players: Japan's Kansai region presents acute supply-demand asymmetry where interventional capacity lags incident PE growth, creating white-space opportunity for catheter platform placement. Freestanding ambulatory thrombectomy centers in United States Sun Belt states offer bypass around traditional hospital capital allocation cycles. Target emergency departments lacking interventional radiology coverage with hybrid lytic-mechanical protocols that require lower operator credentialing thresholds. Pursue reimbursement strategy investments ahead of device commercialization to secure favorable DRG positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors catheter-based platform developers with demonstrated clinical outcomes data and established hospital training infrastructures. Long-term viability hinges on consolidation economics as integrated diagnostic-interventional suites displace fragmented device procurement. Acquisition target archetype: mid-cap mechanical thrombectomy specialists with FDA-cleared aspiration systems and underexploited European market presence. Signal to watch: NICE health technology assessment decisions on catheter-directed therapy cost-effectiveness that would validate premium pricing sustainability across NHS trusts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines enable faster commercialization of next-generation aspiration catheter architectures. |
| Hospital System Partnership | Integrated delivery network contracts embed device platforms into PE response team infrastructure and training protocols. |
| CE Marking Pathway Investment | EMA MDR conformity positions manufacturers for DRG-based reimbursement access across German tertiary centers. |
| Software Companion Development | AI-enabled CT interpretation tools satisfy EU AI Act requirements while creating diagnostic-interventional bundling potential. |
| Reimbursement Strategy | Favorable DRG positioning for catheter-directed therapy versus systemic lysis secures hospital margin protection and procurement priority. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers inform demand-side validation. Regulatory affairs specialists at thrombectomy device manufacturers and formulary directors at integrated delivery networks anchor supply-side perspectives. Bottom-up patient volume modeling triangulates against top-down market sizing from anticoagulant prescription data and catheter shipment records.
Forecast inputs span procedural volume trajectories, reimbursement threshold evolution, and interventional program expansion rates across the projection horizon. Segmentation dimensions include product type, clinical application, end-user facility category, and delivery mode. Patient risk stratification protocols and operator training pipeline constraints inform adoption curve assumptions. CAGRs derive from regression analysis of historical device placement against interventional capacity buildouts, adjusted for regulatory clearance timing and health technology assessment outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by emerging mechanical thrombectomy specialists or accelerated FDA breakthrough designations for novel catheter architectures would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Stroke Management Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market