
 Cystic Acne Market | 2026-2036
Cystic Acne Market Size, Share, and Industry Trends Forecast 2026-2036
Cystic Acne Market Analysis
Retinoid-based formulations is rebalancing the economics of severe acne management as dermatologists shift from prolonged antibiotic courses toward targeted topical and oral vitamin A derivatives. Galderma leverages its integrated pipeline across adapalene and trifarotene portfolios to sustain European market presence. Pfizer anchors its position through manufacturing scale in oral antibiotic supply. Sun Pharmaceutical Industries competes aggressively on cost in emerging markets with its generic isotretinoin capacity.
Cystic acne represents a deep inflammatory condition of the pilosebaceous unit characterized by nodules and abscesses exceeding five millimeters in diameter, with lesions persisting for weeks to months and frequently producing permanent scarring; its primary commercial purpose centers on preventing dermal destruction and psychological morbidity through early intervention. Oral medications command the deepest margin pools due to mandatory physician oversight and REMS-linked distribution constraints, while topical treatments dominate volume through over-the-counter retinol and benzoyl peroxide access. Light therapy segments are expanding fastest as at-home LED devices gain channel placement in dermatology clinics seeking ancillary revenue streams.
The FDA oversees isotretinoin through its iPLEDGE risk management program, while the EMA's pharmacovigilance framework tracks retinoid teratogenicity across European member states, and both bodies are tightening post-market surveillance for oral antibiotic resistance patterns. These regulatory architectures elevate compliance costs for manufacturers but simultaneously protect premium-priced branded therapies from commoditization. Stakeholders must monitor how payer formularies reconcile escalating biologic interest against established small-molecule maintenance protocols.
Market Dynamics
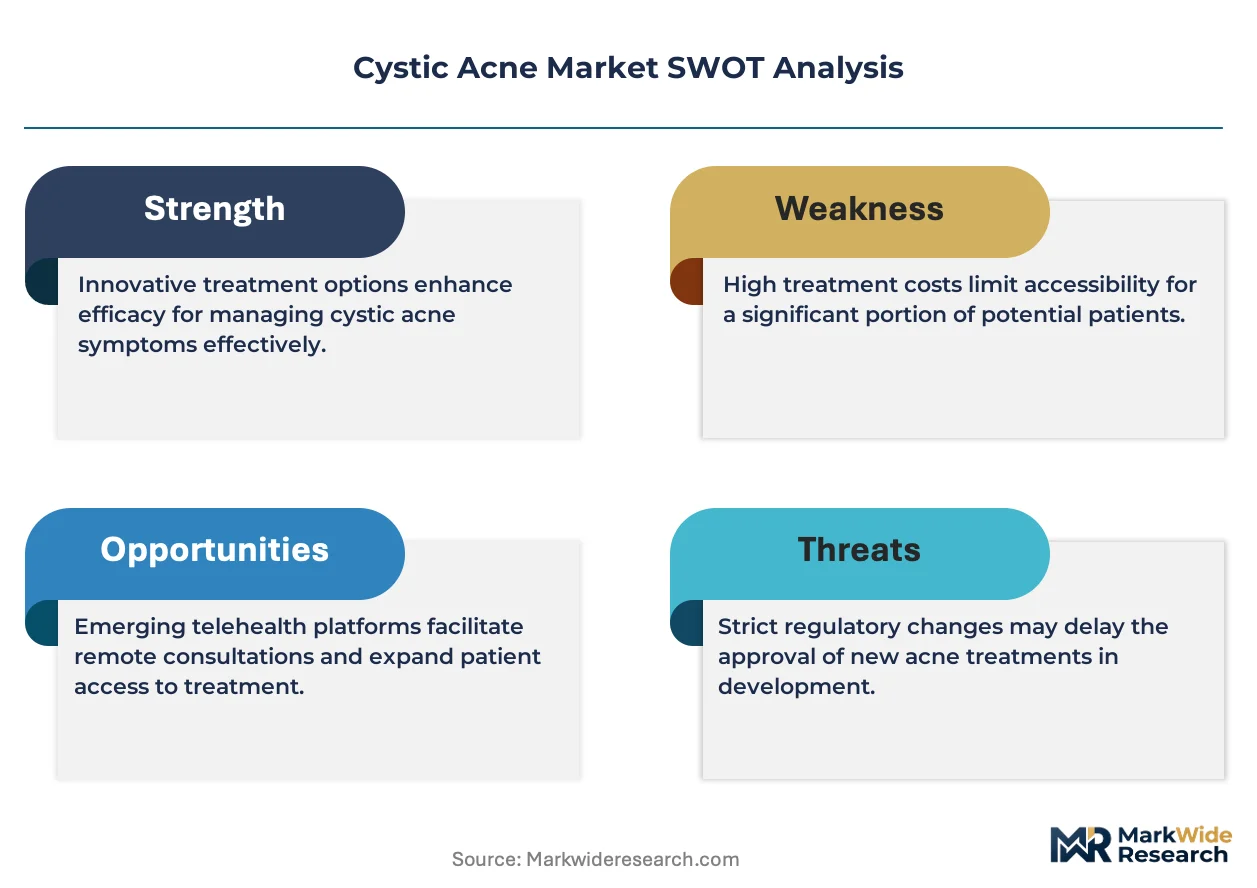
The FDA's iPLEDGE risk management program for isotretinoin distribution is restructuring patient access protocols and elevating compliance costs for prescribers and manufacturers alike. This regulatory architecture is concentrating margin pools around oral medications with mandatory physician oversight while compressing channels for generic substitution.
Growth Catalysts
- Telehealth routing infrastructure:Direct-to-consumer platforms in the United States are channeling patients into specialized acne care workflows, expanding addressable patient populations beyond traditional dermatology clinic catchments.
- EMA pharmacovigilance framework:Tightened post-market surveillance for retinoid teratogenicity across European member states is protecting premium-priced branded therapies from rapid commoditization.
- Combination therapy protocols:Dermatology clinics are expanding procedural menus to integrate light-based adjuncts with pharmacological regimens for severe nodular cases.
Market Restraints
- REMS-linked distribution constraints:Mandatory physician oversight for oral isotretinoin limits prescriber pool expansion and creates geographic access deserts in rural areas.
- Active pharmaceutical ingredient concentration:Generic isotretinoin manufacturing clusters in India create supply vulnerability to export restriction shocks and quality enforcement actions.
- Antibiotic resistance surveillance:The FDA's tightened labeling requirements for oral antibiotic courses are shortening permissible treatment durations and compressing volume per patient.
Strategic Opportunities
- At-home LED device channels:Light therapy segments are gaining placement in dermatology clinics seeking ancillary revenue streams beyond procedural fees.
- Generic penetration in emerging markets:Cost-competitive manufacturing capacity in India offers volume expansion pathways as branded retinoid pricing faces payer pressure.
- Integrated adapalene-trifarotene portfolios:European market presence can be sustained through pipeline breadth spanning multiple retinoid generations and formulation types.
Industry Challenges
- REMS program administration burden:Prescriber certification and patient counseling requirements create workflow friction that limits practice capacity expansion.
- Teratogenic risk management complexity:Pregnancy prevention program compliance across multiple regulatory jurisdictions demands specialized pharmacovigilance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystic Acne Market |
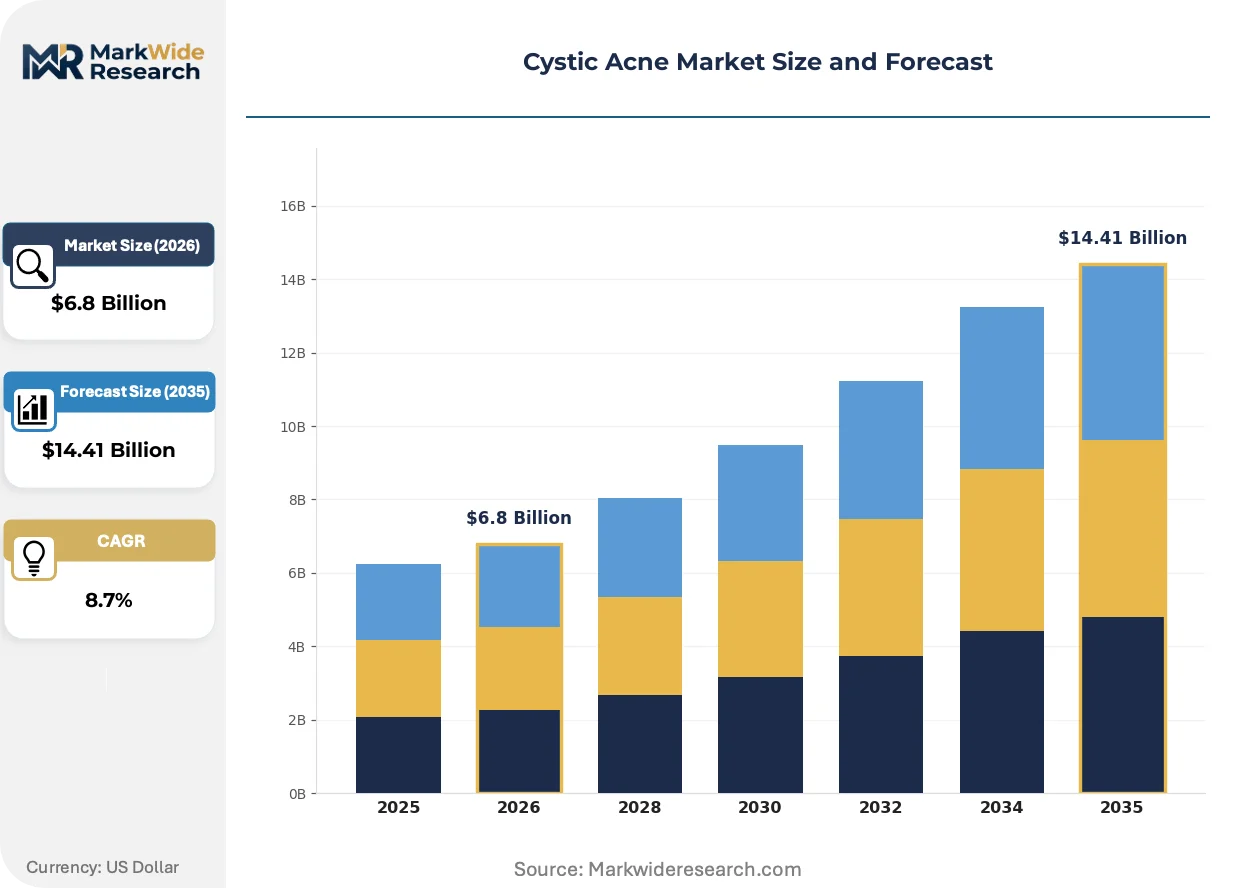
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Light Therapy, Chemical Peels End User: Dermatology Clinics, Spas, Homecare, Hospitals Treatment Stage: Acute, Maintenance, Preventive, Severe Active Ingredient: Salicylic Acid, Benzoyl Peroxide, Retinoids, Antibiotics |
| Companies Covered | Galderma, Pfizer, GlaxoSmithKline, Sun Pharmaceutical Industries, Allergan (AbbVie), Teva Pharmaceuticals, Abbott Laboratories, Bausch Health, Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystic Acne Market Emerging Trajectories
Retinoid-based formulations are rebalancing severe acne management economics as prescribers shift from prolonged antibiotic exposure toward targeted vitamin A derivatives with superior scar prevention profiles.
At-home LED phototherapy devices are expanding into dermatology clinic retail channels and direct-to-consumer platforms, with 415nm blue-light and 630nm red-light configurations targeting Cutibacterium acnes reduction and inflammation modulation. Aesthetic practices and telehealth-integrated retailers are adopting these devices as patient retention tools between pharmaceutical refill cycles. The technology is expanding into maintenance-phase revenue models that previously relied solely on topical prescription adherence.
The FDA's iPLEDGE program modifications are tightening prescriber registration requirements and patient consent documentation standards, elevating administrative burden but simultaneously reinforcing branded isotretinoin market segmentation. Manufacturers are responding with specialized compliance service offerings that generic competitors cannot replicate at equivalent scale. Oral medication segments face the most acute operational impact, with distribution logistics now requiring certified pharmacy verification at every dispensing node.
Patient acquisition patterns are rotating toward telehealth-integrated platforms that bundle initial consultation, prescription routing, and follow-up monitoring into subscription workflows. Traditional dermatology practices are losing first-contact patient volume to these vertically integrated channels, particularly among younger demographics seeking rapid appointment access. This channel shift is most visible in the United States, where regulatory frameworks permit asynchronous prescribing for established drug classes with well-characterized safety profiles.
Cystic Acne Market Segmentation
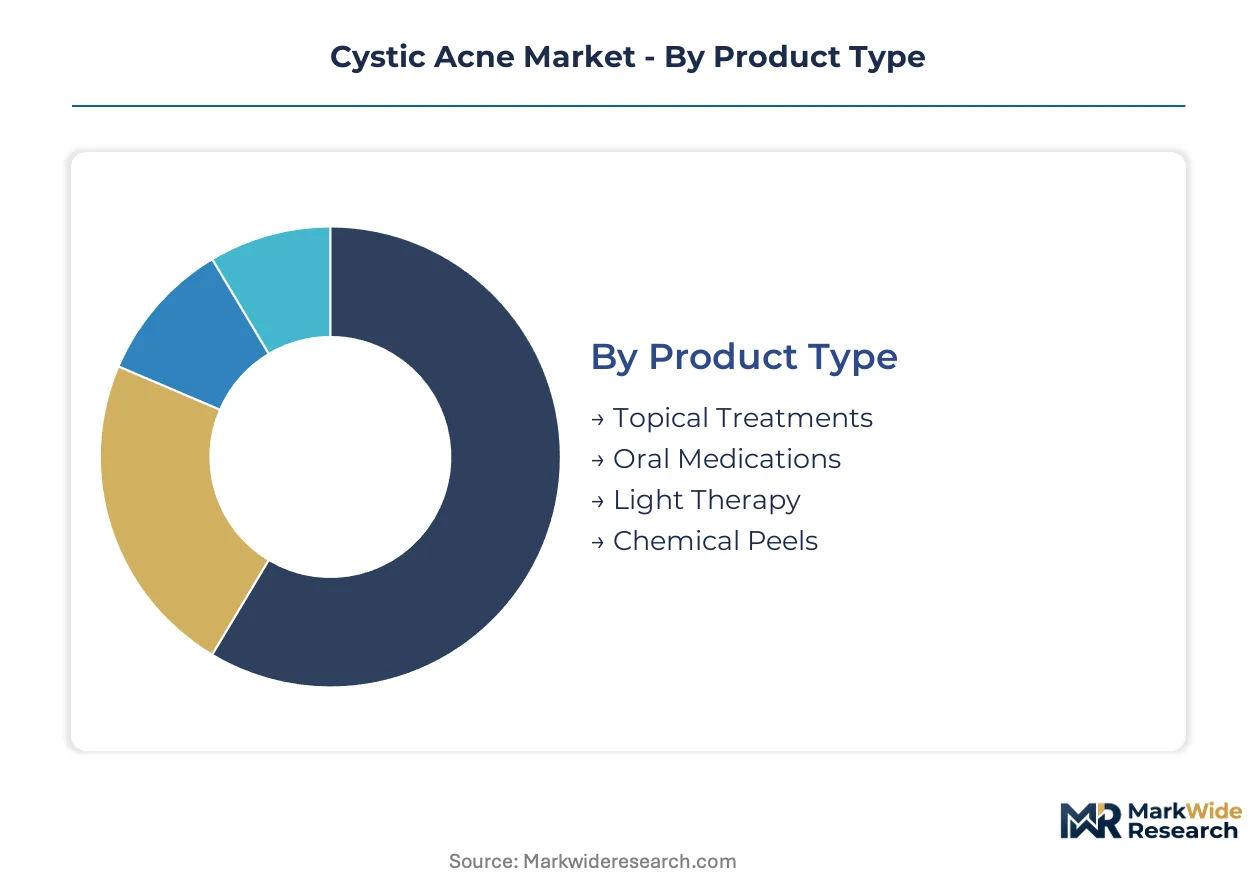
Cystic acne therapeutics fragment across four intersecting dimensions that determine pricing power, regulatory burden, and patient access pathways. Product formulation dictates reimbursement tiers while end-user channel shapes compliance infrastructure requirements.
Product Type:
Retinoid chemistry and delivery mechanism separate segments by margin structure and prescriber oversight intensity.
- Topical Treatments:Adapalene, tazarotene, and trifarotene formulations penetrate the pilosebaceous duct with localized keratolytic action. Demand clusters in the United States through direct-to-consumer telehealth platforms that bypass traditional dermatology queues for first-line prescriptions.
- Oral Medications:Isotretinoin and antibiotic courses target deep nodular lesions through systemic circulation with mandatory REMS-linked distribution. The FDA's iPLEDGE program restricts dispensing to certified pharmacies, elevating compliance costs that protect branded margins from generic substitution.
- Light Therapy:LED devices at 415nm blue and 630nm red wavelengths target Cutibacterium acnes through photodynamic action without systemic exposure.
- Chemical Peels:Trichloroacetic acid and phenol formulations resurface dermal layers for post-inflammatory hyperpigmentation correction.
Oral medications lead on scale; light therapy leads on momentum.
End User:
Channel economics diverge sharply between institutional oversight requirements and at-home convenience premiums.
- Dermatology Clinics:Board-certified practices combine prescription authority with procedural revenue from adjunct light therapy and chemical peel administration. The channel captures highest-value patients through iPLEDGE compliance infrastructure that telehealth competitors struggle to replicate.
- Homecare:Over-the-counter retinol, benzoyl peroxide, and LED devices bypass prescriber bottlenecks entirely. Younger demographics in the United States rotate toward subscription-based telehealth platforms that bundle asynchronous consultation with automated refill routing.
- Spas:Aesthetic practices position chemical peels and light therapy as wellness services outside insurance reimbursement pathways.
- Hospitals:Emergency departments manage acute abscess drainage and secondary infection complications from ruptured nodules.
Dermatology clinics command margin concentration; homecare channels expand patient volume fastest.
Treatment Stage:
Disease progression timing determines therapeutic intensity and duration economics.
- Severe:Nodular and conglobate presentations exceeding five millimeters demand isotretinoin courses with mandatory pregnancy prevention protocols.
- Acute:Active inflammatory flares require rapid bacterial load reduction through short-course oral antibiotics or intralesional corticosteroid injection.
- Maintenance:Low-dose topical retinoid regimens prevent follicular plugging recurrence after successful acute resolution.
- Preventive:Pre-adolescent screening and early comedonal intervention aim to interrupt progression toward scarring phenotypes.
Severe stage concentrates revenue per patient; maintenance stage extends lifetime value through adherence persistence.
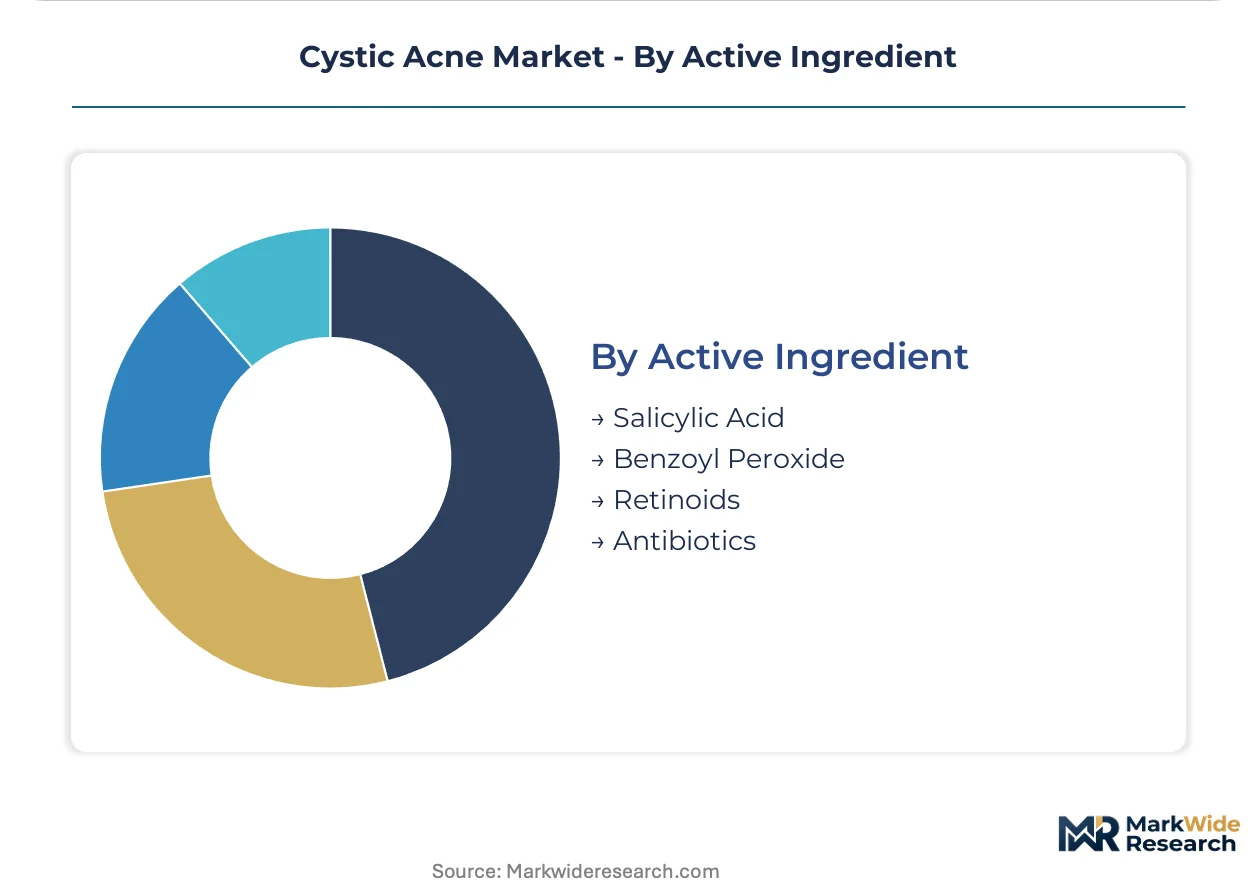
Active Ingredient:
Molecular mechanism and resistance profile shape formulary positioning across payer categories.
- Retinoids:Vitamin A derivatives normalize keratinization and suppress sebum output through nuclear receptor modulation. European dermatology practices favor adapalene-trifarotene portfolios for their teratogenicity documentation and tolerability profiles under EMA pharmacovigilance frameworks.
- Antibiotics:Doxycycline and minocycline target Cutibacterium acnes proliferation with anti-inflammatory side benefits. The FDA's tightened labeling requirements for oral antibiotic courses are shortening permissible treatment durations and compressing volume per patient as resistance surveillance intensifies.
- Benzoyl Peroxide:Oxidative bacterial killing without documented resistance patterns supports over-the-counter placement and combination therapy anchoring.
- Salicylic Acid:Beta-hydroxy acid exfoliation penetrates oil-laden follicles for mild comedonal presentations.
Retinoids lead on pricing power; antibiotics face steepest volume pressure from regulatory resistance monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dermatology corridor anchors pharmaceutical development and telehealth integration for severe acne therapeutics. Demand concentrates in metropolitan healthcare clusters where iPLEDGE-certified prescribers maintain compliance infrastructure.
United States
Telehealth platforms route patients into specialized acne workflows, bypassing traditional dermatology queues for rapid retinoid access. The FDA's iPLEDGE program mandates certified pharmacy verification at every dispensing node, elevating administrative burden. Boston and New York clusters host concentration of board-certified practices combining prescription authority with procedural revenue.
Germany
EMA pharmacovigilance frameworks track retinoid teratogenicity across member states, protecting premium-priced branded therapies. German dermatology practices favor adapalene-trifarotene portfolios under tightened post-market surveillance. The Rhine-Ruhr metropolitan region concentrates manufacturing scale for oral antibiotic supply.
India
Generic isotretinoin manufacturing clusters create cost-competitive supply for emerging market expansion. CDSCO tracks quality enforcement actions against export-oriented API facilities. Mumbai and Hyderabad house concentration of contract manufacturing organizations serving international distribution.
Japan
PMDA oversight maintains stringent labeling requirements for oral retinoid prescriptions, limiting prescriber pool expansion. Tokyo and Osaka metropolitan areas concentrate aesthetic practices positioning light therapy as wellness services. Maintenance-phase revenue models integrate at-home LED devices between pharmaceutical cycles.
Brazil
ANVISA registration pathways for generic isotretinoin accelerate market penetration as branded pricing faces payer pressure. São Paulo state anchors dermatology clinic density and procedural menu expansion. Rio de Janeiro clusters concentrate telehealth-integrated platforms routing patients into subscription workflows.
Cystic Acne Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers expand across retinoid generations and formulation types. The market structure concentrates around integrated pharmaceutical conglomerates with dermatology specialization and generic manufacturers competing on cost. Three archetypes define positioning: branded retinoid specialists with compliance service offerings, scale-driven oral antibiotic suppliers, and emerging market generic producers. M&A activity and strategic licensing agreements represent the dominant competitive moves as firms seek pipeline breadth.
Within the branded formulation tier, Galderma and Hoffmann-La Roche exemplify integrated portfolio strategies spanning multiple retinoid generations. Sun Pharmaceutical Industries occupies a position representing cost-competitive manufacturing capacity in generic isotretinoin supply.
| Leading Market Players |
|---|
| Galderma |
| Pfizer |
| GlaxoSmithKline |
| Sun Pharmaceutical Industries |
| Allergan (AbbVie) |
| Teva Pharmaceuticals |
| Abbott Laboratories |
| Bausch Health |
| Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up dermatology clinic networks in the United States anchor pricing discipline through captive patient flow and procedural bundling, while simultaneously compressing generic isotretinoin margins through consolidated procurement power and preferred pharmacy steering.
Pricing Analysis
Active pharmaceutical ingredient costs pass through unevenly across formulation tiers, with oral isotretinoin bearing the steepest markups due to iPLEDGE compliance infrastructure and certified pharmacy verification requirements. Three-tier pricing structure across premium branded retinoids, standard generic oral medications, and economy topical OTC segments separates patients by prescriber oversight intensity. Pricing pressure stems from telehealth platforms undercutting traditional dermatology consultation fees through subscription workflows. Hospital emergency departments show least price sensitivity for acute abscess management; homecare OTC buyers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Mumbai, Hyderabad, and Ahmedabad form hub-and-spoke patterns radiating generic API to European and North American formulation facilities. Manufacturing concentration in India, China, and the United States creates dependencies on isotretinoin precursor chemicals, retinol feedstocks, and LED device semiconductor components. Single-source vulnerability runs through Indian API clusters exposed to CDSCO quality enforcement actions and export restriction shocks. Distribution runs through certified pharmacy networks for oral medications and direct-to-consumer platforms for homecare devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient acquisition costs and compliance infrastructure separate viable operators from marginal players, justified by demand rotation toward iPLEDGE-certified prescribers and procedural combination therapies that command premium positioning.
For Market Incumbents: Deploy compliance service offerings as a defensive moat against generic substitution, deepening prescriber certification support and patient counseling infrastructure that competitors cannot replicate at equivalent scale. Anchor capacity addition in United States metropolitan clusters where iPLEDGE infrastructure concentrates patient flow and procedural revenue. Counter the threat of telehealth platform disintermediation by integrating at-home LED devices into maintenance-phase subscription workflows that extend lifetime value beyond pharmaceutical refill cycles. For New Entrants and Emerging Players: Capture white-space in emerging market generic manufacturing through cost-competitive isotretinoin capacity serving price-sensitive geographies outside REMS jurisdictions. Target Brazil and India where ANVISA and CDSCO registration pathways accelerate market penetration against branded pricing pressure. Penetrate the at-home LED device segment through direct-to-consumer channels and dermatology clinic retail placement, leveraging wellness positioning that bypasses prescription bottlenecks entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among generic API manufacturers with export-oriented capacity and underutilized compliance infrastructure for REMS-linked distribution. Long-term viability over the next decade hinges on portfolio breadth spanning retinoid generations and formulation types rather than single-molecule dependence. Watch FDA iPLEDGE program modifications as the inflection signal: tightening prescriber requirements concentrate margin pools around branded players with specialized service capabilities, while relaxation would accelerate generic substitution.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Service Expansion | Specialized iPLEDGE infrastructure protects branded isotretinoin margins from generic competitors. |
| Telehealth Platform Integration | Vertically integrated patient routing captures volume from traditional dermatology first-contact loss. |
| At-Home LED Device Channel Placement | Dermatology clinic retail adoption creates ancillary revenue between pharmaceutical refill cycles. |
| Generic API Manufacturing Scale-Up | Indian CDSCO-registered capacity serves emerging market price sensitivity against branded pressure. |
| Adapalene-Trifarotene Portfolio Diversification | Multiple retinoid generations sustain European EMA pharmacovigilance positioning. |
Methodological Framework
Direct dialogue with dermatology practice managers, iPLEDGE-certified prescribers, pharmaceutical regulatory affairs leads, and telehealth platform operators grounded qualitative findings in operational realities. Secondary validation drew from FDA iPLEDGE program documentation, EMA pharmacovigilance frameworks, CDSCO enforcement records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across the analysis window.
Bottom-up volume builds tracked prescription dispensing nodes, telehealth consultation volumes, and LED device unit placements by channel. Top-down market sizing reconciled manufacturer revenue disclosures against payer formulary positioning and treatment duration assumptions. Segmentation dimensions spanned formulation type, end-user channel, disease severity stage, and active ingredient mechanism. CAGRs derived from patient population growth, regulatory access expansion, and therapy mix shift toward retinoid-first protocols.
Underlying measurement precision varies by segment; oral medication volumes carry tighter precision due to REMS-linked dispensing data, while homecare OTC estimates reflect broader sampling variance. Forecasts reflect documented assumptions regarding iPLEDGE program stability, antibiotic resistance surveillance intensity, and telehealth regulatory permissiveness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Europe Functional Cosmetics Market
Skincare
Exfoliators and Scrubs Market
Skincare
US Acne Treatment Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Global Eczema Skin-Care Products Market
Skincare
Skin Care Body Products Market
Skincare
Revitalizing Skin Wands Market
Skincare
CBD Skin Care Market
Skincare
Sheet Face Mask Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Personalized Skin Care Products Market
Skincare
Dermal Regeneration Market
Skincare
Skin Care Supplements Market
Skincare
Global Anti-Aging Market
Skincare
Tinted Sunscreen Market
Skincare
Bangladesh Skin Care Products Market