
 China Fertility Services Market | 2026-2036
China Fertility Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Fertility Services Market Outlook
Aftermarket service revenue from cryopreservation storage and genetic counseling is fragmenting across hospital-affiliated and independent clinic networks. Peking University Third Hospital leverages its pioneering IVF laboratory credentials to anchor high-complexity case flows. Citic-Xiangya Reproductive & Genetic Hospital sustains dominance in central China through captive genetic testing capacity. Shenzhen Zhongshan Urology Hospital competes on urological-male infertility integration, a narrower specialization that deflects direct price pressure from full-service rivals.
China fertility services encompass clinical procedures, laboratory diagnostics, and cryobiological preservation aimed at overcoming infertility through medical intervention, with IVF cycles typically involving controlled ovarian stimulation, oocyte retrieval, fertilization in vitro, and embryo transfer within forty-eight to one hundred twenty hours. The primary purpose is to establish viable pregnancies for individuals or couples where natural conception fails due to anatomical, endocrine, or genetic barriers. Assisted reproductive technology commands the dominant margin pool as IVF and ICSI cycles generate recurring medication, laboratory, and physician fees across multiple visits. Preimplantation genetic testing represents the fastest-expanding technology segment as chromosomal screening becomes standard for older maternal-age patients seeking to reduce aneuploidy risk. Cryopreservation matures into a steady revenue layer as egg and embryo banking extends treatment timelines and defers transfer decisions.
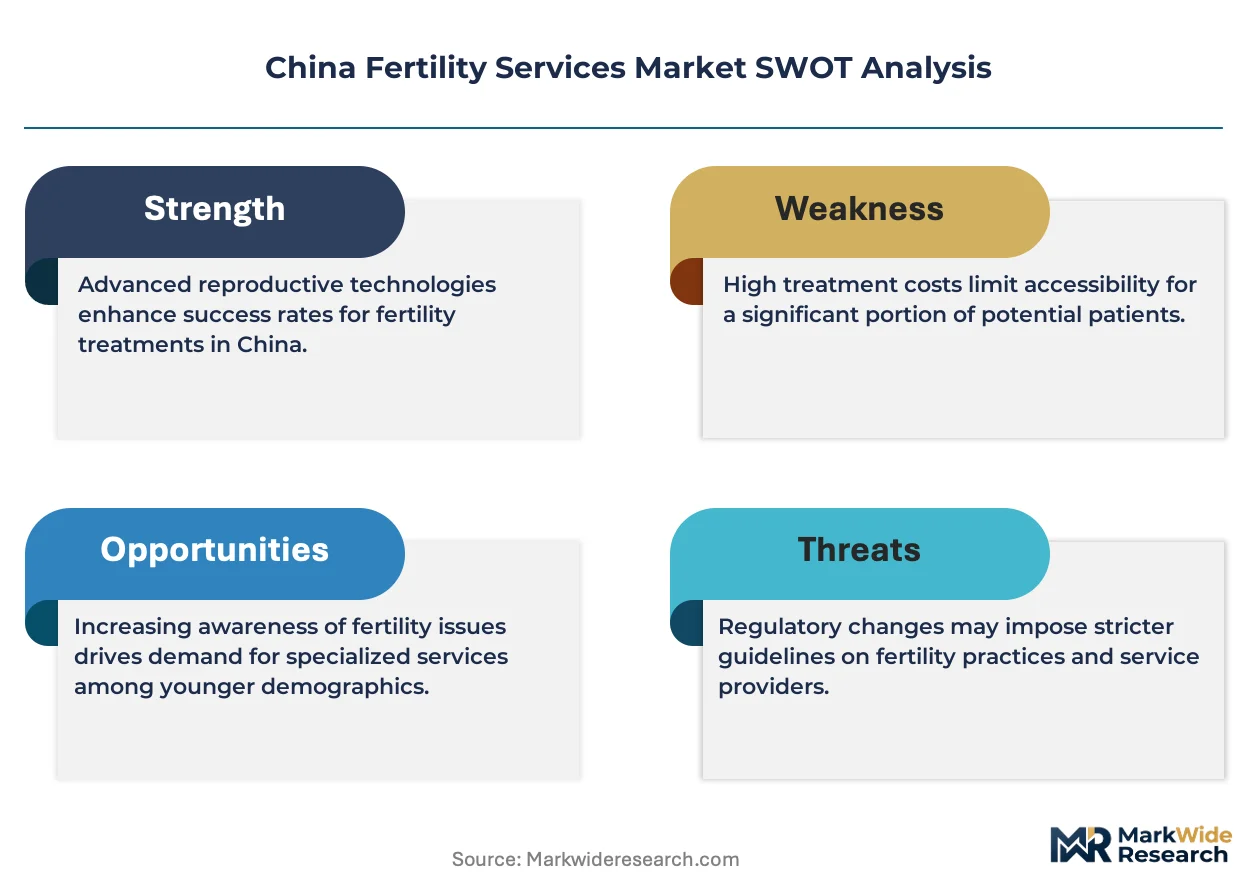
NMPA oversight of implantation devices and culture media shapes product registration timelines and clinic procurement standards, while provincial health commissions under the National Health Commission enforce facility licensing and physician certification quotas that directly constrain market capacity. The country's national pharmaceutical regulator monitors gonadotropin and other hormonal drug approvals, creating supply bottlenecks when batch release delays coincide with peak treatment seasons. Stakeholders must monitor how municipal governments in Beijing and Shanghai experiment with partial public insurance reimbursement pilots, as these local programs could redistribute patient flows and force pricing transparency before national standardization arrives.
Market Dynamics
Provincial physician certification quotas enforced by the National Health Commission constrain clinic expansion faster than capital can deploy, creating artificial scarcity in high-complexity reproductive medicine across China's tier-one hospital systems.
Growth Catalysts
- Three-child policy expansion:Beijing's relaxation of family planning limits generates new patient cohorts previously ineligible for subsidized fertility consultations, redirecting demand toward licensed reproductive centers.
- National Reimbursement Drug List inclusion:Gonadotropin and hormonal stimulation medications now carry partial public insurance coverage, reducing out-of-pocket burdens that previously blocked treatment initiation for price-sensitive couples.
- Preimplantation genetic testing:Chromosomal screening protocols are migrating from experimental protocols to standard-of-care for maternal-age patients, expanding laboratory revenue per IVF cycle.
Market Restraints
- Batch release bottlenecks:NMPA hormonal drug approvals face seasonal delays that coincide with peak ovarian stimulation windows, forcing cycle postponements and patient attrition.
- Physician supply concentration:Reproductive endocrinology specialists cluster in Beijing, Shanghai, and Guangzhou tertiary hospitals, leaving central and western provinces underserved despite facility construction.
- Cryopreservation cost structures:Liquid nitrogen supply chains and specialized storage infrastructure require sustained operational expenditure that independent clinics struggle to amortize against irregular patient flows.
Strategic Opportunities
- Municipal reimbursement pilots:Shanghai and Beijing experiments with partial public insurance coverage for IVF cycles could normalize pricing transparency and redistribute patient flows before national standardization.
- Urological-male infertility integration:Shenzhen Zhongshan Urology Hospital's specialized model demonstrates how narrower clinical focus deflects direct price pressure from full-service reproductive rivals.
- Genetic counseling networks:Aftermarket service revenue from cryopreservation storage and hereditary risk assessment fragments across hospital-affiliated and independent clinic networks, creating partnership white space.
Industry Challenges
- Embryologist training pipelines:IVF laboratory credentialing requires supervised case volumes that exceed current mentorship capacity at Peking University Third Hospital and other pioneering centers.
- Culture media procurement standardization:NMPA implantation device registration timelines create product approval lags that disrupt clinic supply agreements and force temporary protocol substitutions.
- Cross-provincial patient management:Tier-one hospital systems attract complex cases from distant provinces, straining coordination between referring physicians and centralized reproductive specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fertility Services Market |
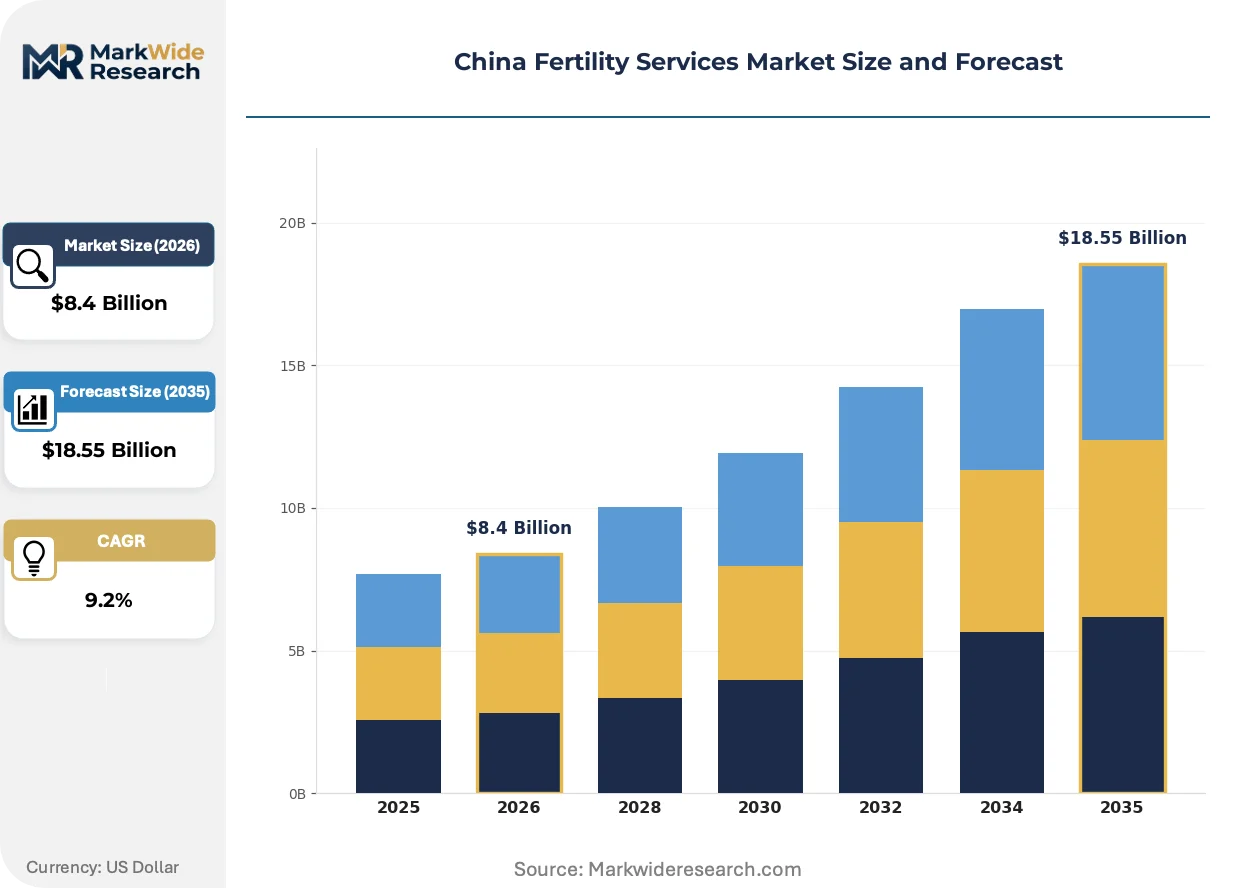
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IVF, ICSI, IUI, Egg Donation Technology: Assisted Reproductive Technology, Cryopreservation, Preimplantation Genetic Testing, Sperm Retrieval End User: Individuals, Couples, Clinics, Hospitals Insurance Coverage: Private Insurance, Public Insurance, Out-of-Pocket, Employer-Sponsored |
| Companies Covered | Jinqi (Shanghai) Medical Investment Co., Shanghai Ninth People's Hospital, Citic-Xiangya Reproductive & Genetic Hospital, Shenzhen Zhongshan Urology Hospital, Guangzhou Women and Children’s Medical Center, Beijing AmCare Women’s & Children’s Hospital, Peking University Third Hospital, Zhongshan Hospital Fudan University, Yanda International Hospital, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fertility Services Market Strategic Shifts
Clinical workflow digitization and genetic screening automation are compressing treatment timelines while expanding addressable patient populations beyond traditional infertility diagnoses.
Time-lapse embryo imaging is migrating from boutique laboratory upgrades to standard incubator configurations. Tier-one reproductive centers in Beijing and Shanghai deploy continuous monitoring systems that capture morphokinetic development markers without disturbing culture conditions. This technology is migrating from high-complexity case differentiation toward baseline laboratory infrastructure, compressing the competitive advantage window for early adopters.
NMPA oversight of implantation devices and culture media shapes product registration timelines and clinic procurement standards. Provincial health commissions under the National Health Commission enforce facility licensing quotas that directly constrain market capacity. The regulatory friction most affects independent clinic networks attempting to expand beyond their original municipal licenses into adjacent provinces.
Patient acquisition patterns are fragmenting across digital health platforms and hospital-affiliated referral networks. Younger couples in Guangzhou and Shenzhen increasingly initiate consultations through telemedicine triage before committing to in-person ovarian stimulation protocols. This channel shift is most visible among dual-income professional households seeking scheduling flexibility around work constraints.
China Fertility Services Market Segmentation
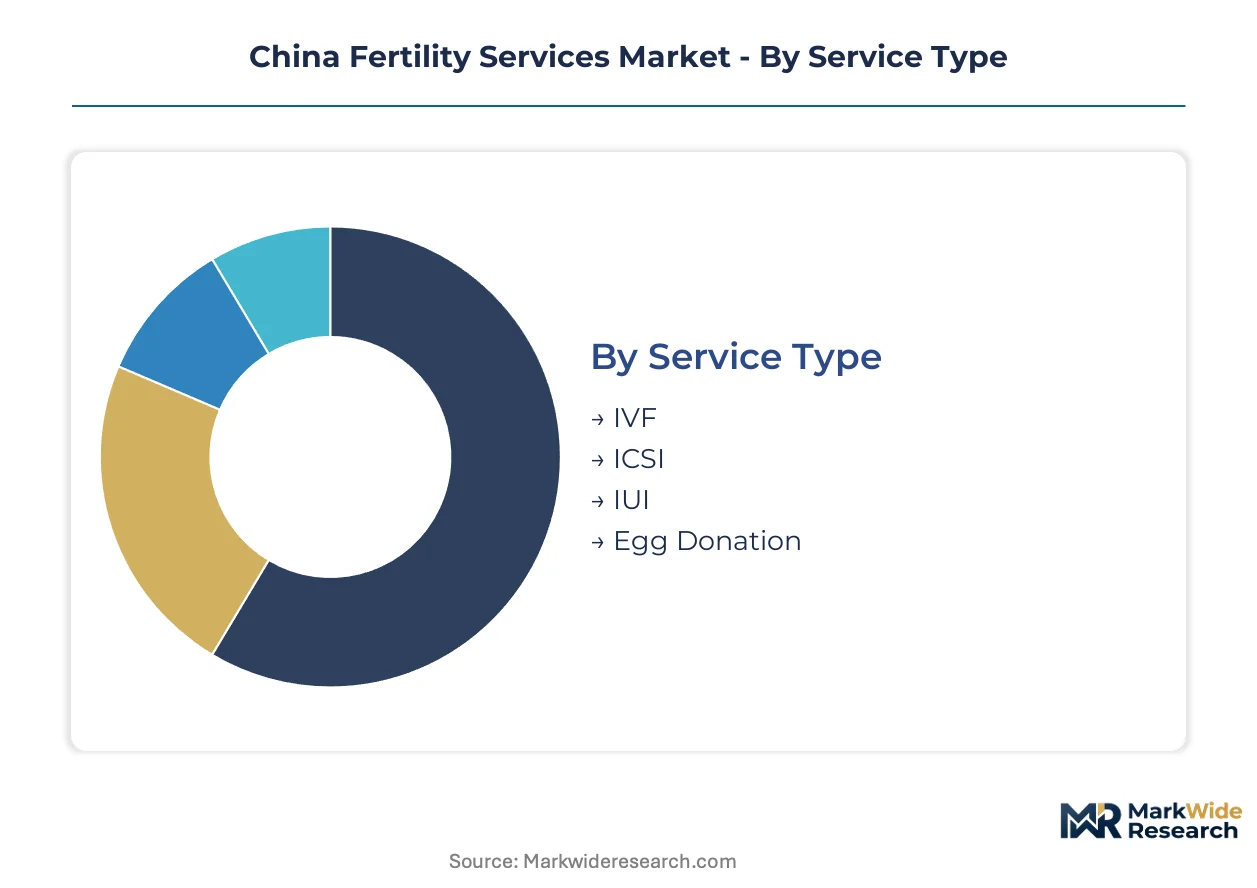
China's fertility services market fragments across clinical procedure types, laboratory technologies, patient payment structures, and institutional delivery settings. Understanding these segment boundaries clarifies where NMPA regulatory friction concentrates and which patient cohorts drive revenue per cycle.
Service Type:
Clinical procedure selection maps directly to infertility diagnosis complexity and male-factor involvement, spanning four distinct intervention tiers.
- IVF:Controlled ovarian stimulation with laboratory fertilization and embryo transfer commands the highest revenue per initiated cycle. Demand concentrates in Beijing and Shanghai tertiary hospitals where embryologist certification quotas limit throughput despite patient queues.
- ICSI:Intracytoplasmic sperm injection addresses male-factor infertility through direct oocyte penetration, adding laboratory complexity and consumable cost to standard IVF protocols. Shenzhen Zhongshan Urology Hospital anchors regional demand through urological-male infertility integration.
- IUI:Intrauterine insemination offers lower-cost first-line intervention for unexplained infertility, typically performed in hospital-affiliated clinics with simpler credentialing requirements.
- Egg Donation:Third-party oocyte provision serves poor ovarian reserve patients, operating under strict NHC facility licensing and donor anonymity protocols that constrain supply expansion.
The dominant share belongs to IVF, while ICSI is closing the gap fastest as male-factor diagnosis rates climb in tier-one cities.
Technology:
Revenue pools and margin structures diverge sharply between clinical intervention tools and biological preservation systems.
- Assisted Reproductive Technology:The umbrella category encompassing IVF, ICSI, and laboratory infrastructure generates recurring medication, physician, and embryologist fees. Peking University Third Hospital leverages its pioneering laboratory credentials to capture complex case flows from across northern China.
- Cryopreservation:Vitrification-based egg and embryo banking extends treatment timelines and creates steady storage revenue streams. Liquid nitrogen supply chain constraints and specialized infrastructure requirements limit independent clinic participation in this segment.
- Preimplantation Genetic Testing:Chromosomal screening reduces aneuploidy risk for maternal-age patients. Citic-Xiangya Reproductive & Genetic Hospital sustains central China dominance through captive genetic testing capacity.
- Sperm Retrieval:Surgical extraction techniques address azoospermia cases, typically integrated with urological services rather than standalone reproductive centers.
Assisted Reproductive Technology retains the largest revenue footprint, though Preimplantation Genetic Testing is expanding most quickly as screening protocols standardize.
End User:
Patient and institutional demand profiles shape service configuration, pricing tolerance, and referral pathway design.
- Couples:Dual-income professional households in Guangzhou and Shenzhen drive demand for scheduling flexibility and telemedicine triage before committing to stimulation protocols.
- Individuals:Single women pursuing fertility preservation generate emerging demand for egg banking services, though regulatory frameworks lag patient interest.
- Hospitals:Tertiary hospital reproductive centers anchor high-complexity case flows and embryologist training pipelines, constrained by National Health Commission certification quotas.
- Clinics:Independent and hospital-affiliated clinics compete on accessibility and price transparency, fragmented across municipal licensing boundaries.
Couples represent the fastest-expanding buyer segment, while Hospitals capture the highest complexity cases and associated margins.
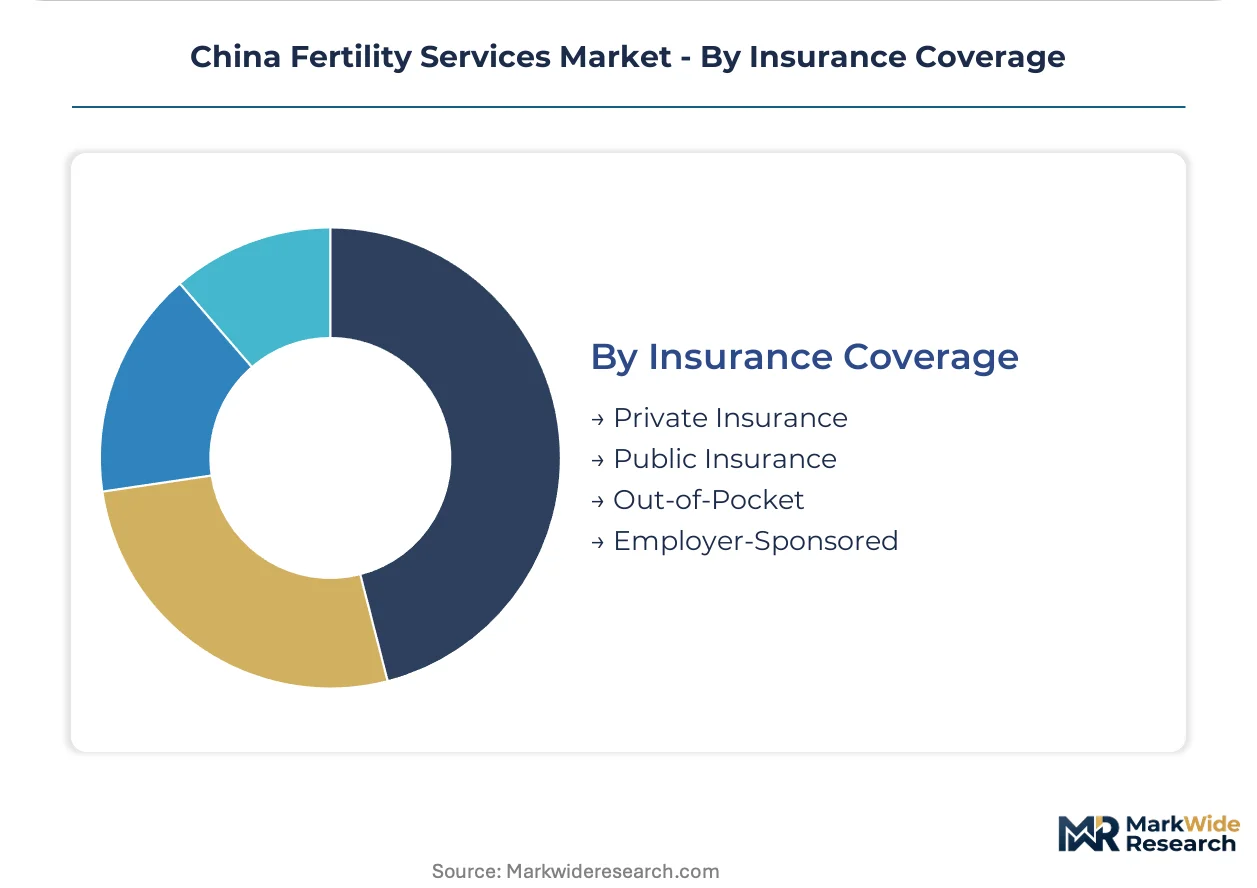
Insurance Coverage:
Payment structure segmentation reveals how public policy shifts are redistributing patient access and clinic revenue stability.
- Out-of-Pocket:Self-funded cycles dominate historical payment patterns, creating price sensitivity that blocks treatment initiation for middle-income couples.
- Public Insurance:National Reimbursement Drug List inclusion for gonadotropin and hormonal medications now reduces out-of-pocket burdens, with Beijing and Shanghai piloting expanded IVF cycle coverage.
- Private Insurance:Commercial fertility riders remain limited in penetration, concentrated among multinational employer benefit packages in tier-one cities.
- Employer-Sponsored:Corporate fertility benefits emerge in technology and financial services sectors, though coverage depth varies significantly.
Out-of-Pocket still accounts for the largest transaction volume, yet Public Insurance is gaining share fastest as municipal reimbursement pilots expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in fertility services varies sharply across China's urban hierarchy, with tier-two and tier-three city patients abandoning cycles at higher rates when out-of-pocket burdens spike, while Beijing and Shanghai households demonstrate markedly lower elasticity to stimulation medication costs.
Beijing-Tianjin-Hebei
Capital-region demand concentrates among dual-income professional households seeking high-complexity reproductive interventions. NHC facility licensing quotas constrain embryologist certification throughput at tertiary hospital systems. Peking University Third Hospital anchors northern China's case flow through its pioneering IVF laboratory credentials.
Yangtze River Delta
Shanghai's municipal reimbursement pilots for IVF cycles are redistributing patient flows from Jiangsu and Zhejiang provinces. SAMR oversight of hormonal drug batch releases creates seasonal supply bottlenecks that coincide with peak ovarian stimulation windows. Citic-Xiangya maintains central China reach through captive genetic testing capacity.
Pearl River Delta
Shenzhen and Guangzhou drive demand for telemedicine triage and scheduling flexibility among younger professional couples. Guangdong provincial health commissions enforce physician certification quotas that limit clinic expansion despite capital availability. Shenzhen Zhongshan Urology Hospital competes through urological-male infertility integration.
Sichuan-Chongqing
Western China's underserved reproductive medicine market attracts cross-provincial patients from tier-one hospital systems. NMPA culture media registration timelines disrupt clinic supply agreements and force temporary protocol substitutions. Chongqing's municipal health bureau experiments with expanded public insurance pilots for gonadotropin coverage.
Shandong Peninsula
Shandong's aging demographic profile accelerates demand for preimplantation genetic testing among maternal-age patients. Provincial health commissions under NHC enforce strict donor anonymity protocols for third-party oocyte provision. Qingdao and Jinan reproductive centers compete on price transparency against Beijing referral flows.
China Fertility Services Market Competitive Environment
Capability concentration sits with hospital-affiliated tertiary centers possessing embryologist training pipelines; scale advantage sits with independent clinic networks pursuing municipal license expansion. The market structures around tiered credentialing scarcity rather than capital deployment speed. Two strategic archetypes dominate: pioneering academic medical centers leveraging laboratory reputation for complex case capture, and specialized urological-reproductive integrators deflecting price pressure through narrower clinical focus. Competitive moves concentrate on municipal reimbursement pilot positioning and genetic counseling network partnerships.
Within the academic medical center tier, Peking University Third Hospital and Shanghai Ninth People's Hospital exemplify credential-driven case flow concentration. Citic-Xiangya Reproductive & Genetic Hospital occupies a position bridging central China geographic coverage with captive genetic testing capacity. Shenzhen Zhongshan Urology Hospital represents the specialization archetype, anchoring regional demand through urological-male infertility integration rather than full-service reproductive competition.
| Leading Market Players |
|---|
| Jinqi (Shanghai) Medical Investment Co. |
| Shanghai Ninth People's Hospital |
| Citic-Xiangya Reproductive & Genetic Hospital |
| Shenzhen Zhongshan Urology Hospital |
| Guangzhou Women and Children's Medical Center |
| Beijing AmCare Women's & Children's Hospital |
| Peking University Third Hospital |
| Zhongshan Hospital Fudan University |
| Yanda International Hospital |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in embryologist certification pipelines across Beijing and Shanghai tertiary hospitals drives both supplier scarcity and premium pricing power for high-complexity IVF cycles, compressing margins at independent clinics while concentrating revenue at credentialed academic medical centers.
Pricing Analysis
Cryopreservation storage and genetic counseling after-sales revenue drives lifetime patient value beyond initial cycle fees. Three-tier pricing structure across premium, standard, and economy levels separates Peking University Third Hospital's complex case premiums from municipal clinic base rates and telemedicine triage entry points. Pricing pressure stems from NMPA hormonal drug batch release delays that force cycle postponements and patient attrition. Out-of-pocket couples in tier-two cities demonstrate highest price sensitivity, while Beijing dual-income households show lowest elasticity to stimulation medication costs.
Supply Chain Analysis
Upstream gonadotropin and culture media feedstock production concentrates in China, Switzerland, and Japan pharmaceutical manufacturing bases. Liquid nitrogen supply chains and specialized incubator equipment draw from cryobiology equipment specialists in Germany, USA, and domestic Chinese suppliers. Single-source vulnerability runs through NMPA implantation device registration timelines that disrupt clinic procurement agreements. Distribution runs through hospital-affiliated procurement committees and independent clinic network purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in aftermarket service networks as genetic counseling and cryopreservation storage demand fragments across hospital-affiliated and independent clinic channels, creating partnership white space for specialized service integrators.
For Market Incumbents: Entrench laboratory credentialing advantages by expanding embryologist training pipelines at Peking University Third Hospital and Shanghai Ninth People's Hospital to defend against independent clinic network scale plays. Deepen backward integration into captive genetic testing capacity following Citic-Xiangya's central China model. Prioritize municipal reimbursement pilot positioning in Beijing and Shanghai before national standardization redistributes patient flows. For New Entrants and Emerging Players: Central and western province underpenetration offers the most accessible expansion corridor, with Sichuan-Chongqing reproductive medicine markets attracting cross-provincial patients from distant tier-one hospital systems. Target urological-male infertility integration following Shenzhen Zhongshan Urology Hospital's specialized deflection strategy. Pursue telemedicine triage partnerships with dual-income professional households in Guangzhou and Shenzhen as the lowest-friction patient acquisition channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryopreservation infrastructure as liquid nitrogen supply chains and specialized storage requirements favor scaled operators over independent clinic networks. Acquisition target archetypes include municipal-licensed independent clinics with embryologist certification quotas already secured. Monitor NHC physician certification quota expansion announcements as the critical inflection signal for capacity-constrained market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Reimbursement Pilot Positioning | Beijing and Shanghai insurance experiments redistribute patient flows before national standardization arrives. |
| Captive Genetic Testing Capacity Buildout | Citic-Xiangya's central China dominance demonstrates laboratory integration defends regional market share. |
| Telemedicine Triage Platform Development | Guangzhou and Shenzhen younger couples increasingly initiate consultations through digital health channels. |
| Embryologist Training Pipeline Expansion | Peking University Third Hospital's credential scarcity anchors high-complexity case flow concentration. |
| Urological-Male Infertility Integration | Shenzhen Zhongshan Urology Hospital's narrower focus deflects direct price pressure from full-service rivals. |
Study Parameters
The analysis maps clinical procedure tiers, laboratory technology segments, patient payment structures, and institutional delivery settings, each validated through reproductive endocrinologists, hospital procurement managers, provincial health commission officials, and independent clinic operators. Primary interview findings triangulate against NMPA drug approval databases, National Health Commission facility licensing records, provincial reimbursement policy documents, and tertiary hospital reproductive center annual reports. Bottom-up cycle volume estimates and top-down market value reconstructions converge through iterative stakeholder validation.
Assumptions hold NHC physician certification quotas and NMPA regulatory timelines within observed enforcement patterns while varying municipal reimbursement pilot expansion rates and genetic testing protocol adoption curves across the projection horizon. Segmentation dimensions model service type complexity, technology maturity tiers, insurance coverage evolution, and regional patient flow patterns. CAGRs derive from cycle initiation volume trajectories, revenue per case expansion from genetic testing penetration, and price elasticity differentials across urban tiers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by hospital-affiliated networks or rapid private insurance penetration would shift outcomes beyond modeled ranges. Cross-checking against provincial health commission licensing announcements and SAMR hormonal drug batch release schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Concierge Medicine Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Private Healthcare Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Global Offsite Medical Case Management Market