
 South Korea Healthcare Cold Chain Logistics Market | 2026-2036
South Korea Healthcare Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Healthcare Cold Chain Logistics Market Intelligence
Buyer concentration among South Korean biopharmaceutical manufacturers is decoupling from traditional logistics providers as specialized cold chain requirements fragment procurement across niche operators. Samsung SDS leverages its domestic IT infrastructure and pharmaceutical tracking platforms to anchor high-value vaccine distribution contracts. CJ Logistics competes through integrated warehousing and last-mile delivery networks spanning the Seoul-Busan corridor. Korean Air Cargo dominates temperature-controlled air freight capacity at Incheon International Airport, controlling critical export lanes for temperature-sensitive biologics.
Healthcare cold chain logistics encompasses the temperature-controlled storage, handling, and transportation of pharmaceutical products, biological specimens, and medical supplies requiring maintenance within validated thermal parameters typically between 2°C and 8°C for refrigerated goods or below -20°C for frozen materials, utilizing insulated containers, active refrigeration units, and real-time environmental monitoring systems to preserve product efficacy and patient safety. The pharmaceuticals segment sustains the largest volume share as domestic production of biologics and biosimilars expands under government industrial policy, while the cryogenic temperature range segment leads growth acceleration driven by cell and gene therapy clinical trials. Air freight occupies the premium margin pool for time-critical vaccine and plasma shipments, whereas road transport anchors routine hospital and pharmacy replenishment cycles.
MFDS enforces Good Distribution Practice standards that mandate continuous temperature documentation and deviation reporting for all pharmaceutical shipments, while KFDA-aligned cold chain guidelines shape facility certification requirements for third-party logistics providers. The Ministry of Environment regulates refrigerant emissions from transport refrigeration units, forcing fleet operators toward lower-global-warming-potential cooling technologies. Stakeholders must monitor evolving MFDS traceability mandates and assess whether existing monitoring infrastructure satisfies impending real-time data submission requirements.
Market Dynamics
MFDS serialization mandates and real-time traceability requirements are compressing operational margins while forcing wholesale infrastructure upgrades across South Korea's pharmaceutical distribution network. Biopharmaceutical manufacturers now demand continuous temperature verification from production through last-mile delivery, eliminating legacy batch-documentation approaches.
Growth Catalysts
- Cell and gene therapy pipeline expansion:Domestic clinical trials for CAR-T therapies and regenerative medicines require cryogenic logistics infrastructure that did not exist in Korea five years ago.
- MFDS Good Distribution Practice enforcement:Mandatory deviation reporting and continuous temperature documentation for all pharmaceutical shipments are professionalizing third-party logistics provider capabilities.
- Seoul metropolitan corridor concentration:Major hospital clusters and pharmaceutical headquarters clustering in Gyeonggi Province create dense demand nodes that justify dedicated cold chain investments.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic logistics dependence on a limited number of industrial gas suppliers creates input cost volatility and availability risk for cell therapy shippers.
- Incheon air freight capacity constraints:Temperature-controlled cargo space allocation at Korea's primary international gateway remains concentrated among flag carrier operations, limiting export flexibility.
- Refrigerant transition costs:Ministry of Environment mandates phasing out high-global-warming-potential cooling technologies, forcing fleet operators into premature equipment replacement cycles.
Strategic Opportunities
- Busan-Gyeongnam pharmaceutical manufacturing belt:Emerging biologics production facilities outside Seoul create demand for temperature-controlled distribution infrastructure in currently underserved southern corridors.
- IoT sensor and blockchain convergence:Real-time environmental monitoring combined with immutable chain-of-custody records enables premium service tiers for high-value biosimilar exports.
- MFDS real-time data submission mandates:Impending regulatory requirements for live temperature data transmission create first-mover advantage for logistics providers with integrated digital platforms.
Industry Challenges
- Cryogenic handling technician scarcity:Specialized competencies for liquid nitrogen systems and ultra-low temperature equipment maintenance remain concentrated among a limited workforce pool.
- Legacy warehouse retrofitting complexity:Existing pharmaceutical storage facilities face extended downtime and certification delays when upgrading to validated cold rooms with redundant backup systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Healthcare Cold Chain Logistics Market |
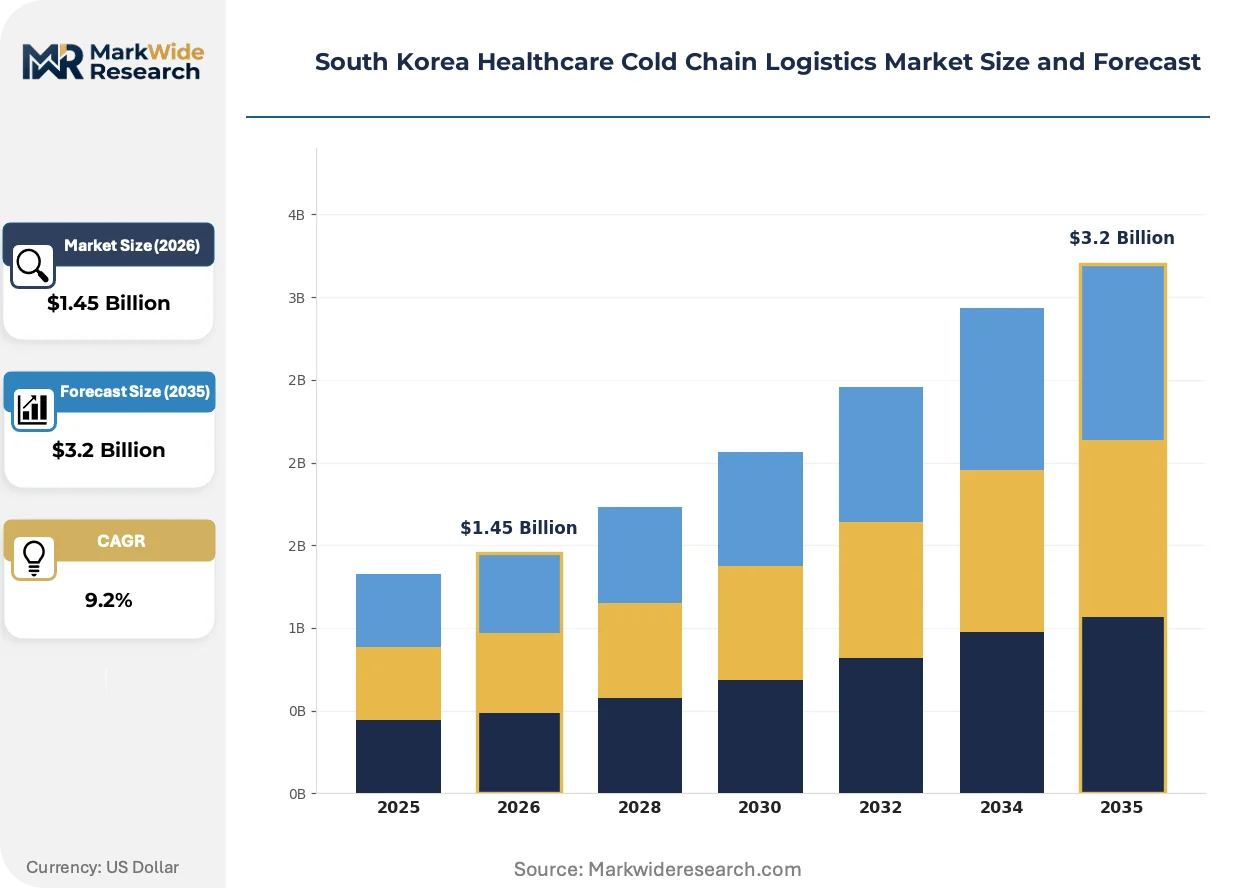
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
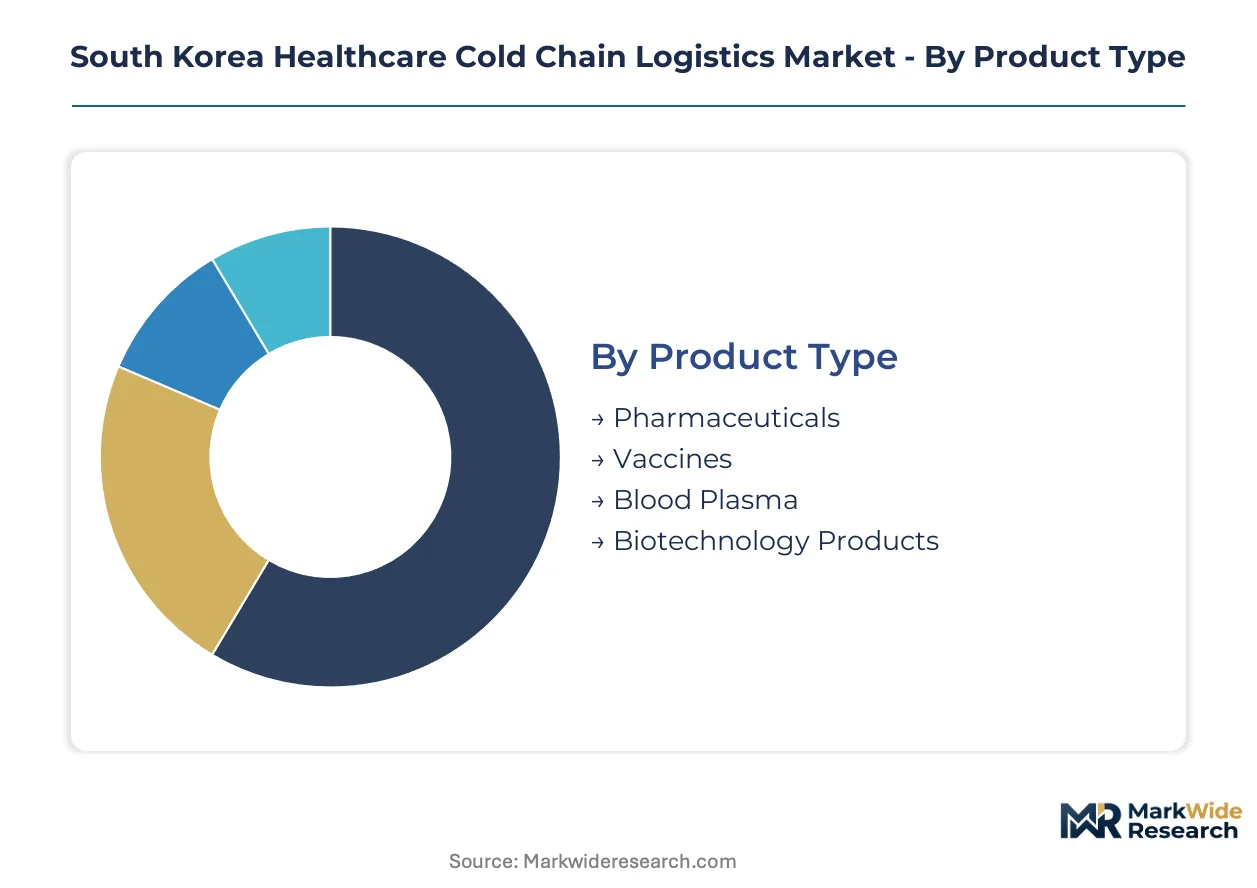
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Blood Plasma, Biotechnology Products Delivery Mode: Air Freight, Sea Freight, Road Transport, Rail Transport Temperature Range: Refrigerated, Frozen, Ambient, Cryogenic End User: Hospitals, Pharmacies, Clinics, Research Institutes |
| Companies Covered | FedEx Corporation, Geodis, Samsung SDS, DB Schenker, Korean Air Cargo, DHL Supply Chain, Nippon Express, Kuehne + Nagel International, CJ Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Healthcare Cold Chain Logistics Market Strategic Shifts & Innovations
Digital traceability infrastructure is displacing paper-based documentation across South Korea's pharmaceutical supply chain, with real-time monitoring systems now treated as competitive table stakes rather than premium add-ons. Three developments are compressing implementation timelines and reshaping vendor selection criteria.
Blockchain-enabled temperature logging is integrating pharmaceutical shipment data across manufacturer, logistics provider, and hospital pharmacy systems. Domestic biopharmaceutical producers are adopting these platforms at contract renewal cycles to satisfy MFDS audit requirements. The technology is compressing dispute resolution timelines and reducing insurance premiums for high-value biologics shipments.
MFDS serialization mandates are tightening documentation standards for all temperature-controlled pharmaceutical movements. The regulation requires unique product identifiers and environmental history for every salable unit. Vaccine and plasma distributors face the steepest compliance ramps, with many outsourcing validation to specialized third-party logistics providers rather than building in-house capabilities.
Hospital pharmacy consolidation is concentrating procurement authority among regional health networks in Seoul, Daegu, and Busan. These integrated delivery networks are displacing fragmented purchasing arrangements with long-term cold chain service contracts. The shift is most visible in oncology and immunology therapeutic categories, where temperature excursions carry the highest patient safety liabilities.
South Korea Healthcare Cold Chain Logistics Market Segmentation
Cold chain logistics procurement in South Korea fragments across product risk profiles, transport urgency, and end-user compliance requirements. Each segmentation axis reveals distinct margin pools and infrastructure investment priorities for specialized operators.
Product Type:
Biopharmaceutical manufacturers differentiate procurement by product stability windows and regulatory classification, with high-value biologics commanding dedicated temperature-controlled infrastructure.
- Pharmaceuticals:Domestic production of biosimilars and small-molecule drugs drives routine refrigerated distribution volumes. Seoul-Gyeonggi hospital networks absorb the majority of palletized shipments through contracted third-party logistics providers.
- Vaccines:Time-sensitive immunization products require continuous cold chain verification from MFDS-certified manufacturing through last-mile clinic delivery. Government immunization programs and private hospital procurement create dual demand channels with divergent documentation requirements.
- Blood Plasma:Fractionated plasma derivatives demand frozen transport corridors linking domestic collection centers to processing facilities.
- Biotechnology Products:Cell therapies and regenerative medicines utilize cryogenic logistics infrastructure concentrated among specialized operators.
Volume sits with Pharmaceuticals; growth tilts toward Biotechnology Products.
Delivery Mode:
Transport mode selection hinges on shipment value density, delivery window constraints, and temperature excursion tolerance thresholds.
- Air Freight:Korean Air Cargo and Asiana Airlines control temperature-controlled belly capacity at Incheon International Airport for time-critical vaccine and plasma exports. Premium pricing reflects limited pallet positions and pharmaceutical certification requirements.
- Road Transport:CJ Logistics and Samsung SDS operate validated refrigerated fleets along the Seoul-Busan expressway corridor for hospital replenishment cycles. Dense metropolitan demand nodes justify dedicated cold storage depots in Gyeonggi and Busan.
- Sea Freight:Reefer container movements handle bulk pharmaceutical ingredients with extended stability windows.
- Rail Transport:Limited pharmaceutical-specific cold chain deployment concentrates on intercity bulk movements.
Margin concentrates in Air Freight; expansion tilts toward Road Transport.
Temperature Range:
Equipment specifications and monitoring protocols stratify by thermal parameter stringency, with cryogenic segments demanding specialized technician competencies.
- Cryogenic:Liquid nitrogen vapor-phase systems support CAR-T therapy clinical trials and stem cell logistics. Industrial gas supply concentration in Ulsan and Yeosu creates geographic dependency for ultra-low temperature shippers.
- Refrigerated:Standard 2°C to 8°C parameters dominate vaccine and insulin distribution. MFDS Good Distribution Practice mandates redundant backup systems and continuous data logging.
- Frozen:Plasma derivatives and certain biologics require -20°C to -40°C maintenance.
- Ambient:Controlled room temperature segments handle packaging materials and stable excipients.
Refrigerated commands current volume; cryogenic infrastructure expands most quickly.
End User:
Facility certification requirements and procurement authority concentration shape service contract structures across healthcare provider categories.
- Hospitals:Major medical centers in Seoul, Daegu, and Busan consolidate cold chain procurement through integrated delivery networks. Oncology and immunology therapeutic categories drive premium service tier demand.
- Pharmacies:Community and hospital outpatient dispensaries require frequent small-lot replenishment with validated last-mile handoff protocols.
- Clinics:Primary care and specialty injection centers manage limited on-site cold storage capacity.
- Research Institutes:Academic medical centers and contract research organizations handle clinical trial materials with chain-of-custody documentation.
Hospitals anchor current revenue; Research Institutes gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial gas supply concentration in Ulsan and Yeosu anchors cryogenic logistics capacity for South Korea's cell therapy sector. Temperature-controlled distribution networks radiate from three distinct manufacturing belts with divergent infrastructure maturity.
Seoul Capital Area
Seoul Capital Area concentrates biopharmaceutical headquarters and major hospital clusters in Gyeonggi Province. MFDS Good Distribution Practice enforcement tightens facility certification requirements for third-party logistics providers operating validated cold rooms. Songdo International Business District hosts specialized temperature-controlled warehousing serving clinical trial material flows.
Busan-Ulsan
Busan-Ulsan corridor leverages deep-water port access and industrial gas production infrastructure for cryogenic logistics. Emerging biologics manufacturing facilities in Gyeongnam Province create demand for temperature-controlled distribution currently served by road transport from Seoul. Korean Air Cargo maintains temperature-controlled belly capacity at Gimhae International Airport for regional biologics exports.
Daegu-Gyeongbuk
Daegu-Gyeongbuk region anchors pharmaceutical manufacturing with growing cold chain requirements for biosimilar production. Ministry of Environment refrigerant transition mandates accelerate fleet replacement among regional road transport operators. Daegu's medical device cluster generates adjacent demand for controlled-temperature component logistics.
Daejeon-Sejong
Daejeon-Sejong corridor hosts government research institutes and regulatory science centers shaping MFDS cold chain guidelines. Korea Research Institute of Bioscience and Biotechnology facilities require specialized cryogenic specimen handling. Public-sector procurement concentrates temperature-controlled logistics demand among accredited national laboratory networks.
Gwangju-Honam
Gwangju-Honam region exhibits underdeveloped pharmaceutical cold chain infrastructure relative to national manufacturing output. Agricultural biotechnology and food-grade cold storage dominate regional temperature-controlled logistics capacity. Biopharmaceutical manufacturers face extended replenishment cycles from Seoul-based distribution centers.
South Korea Healthcare Cold Chain Logistics Market Key Industry Players
Established logistics conglomerates occupy the standard tier; emerging cryogenic specialists pursue cell therapy clinical trial contracts. Domestic players leverage government industrial policy support and geographic proximity to Seoul hospital networks. Three archetypes define competitive positioning: integrated conglomerates with validated pharmaceutical platforms, airline-affiliated cargo operators controlling temperature-controlled air freight capacity, and specialized cold chain boutiques serving biotechnology research institutes. Capacity expansion and digital platform integration constitute the dominant competitive vectors.
Among integrated logistics providers, Samsung SDS and CJ Logistics exemplify archetypes combining domestic IT infrastructure with pharmaceutical-grade warehousing. Korean Air Cargo anchors the airline-affiliated tier through temperature-controlled belly capacity at Incheon International Airport. These three entities represent distinct strategic positions: technology-integrated platform operators, expressway-corridor road transport specialists, and export-gateway air freight controllers.
| Leading Market Players |
|---|
| FedEx Corporation |
| Geodis |
| Samsung SDS |
| DB Schenker |
| Korean Air Cargo |
| DHL Supply Chain |
| Nippon Express |
| Kuehne + Nagel International |
| CJ Logistics |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between MFDS-validated cold chain operators and uncertified general freight carriers manifests in both rate premiums and procurement channel segregation. Pharmaceutical manufacturers now bundle continuous temperature monitoring and deviation insurance into contract terms, compressing margins for providers lacking integrated digital platforms while rewarding specialized operators with multi-year service agreements.
Pricing Analysis
Real-time environmental monitoring and automated deviation reporting are increasingly bundled rather than offered as unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels reflects certification status and backup system redundancy. Price differentiation rests on MFDS audit compliance and IoT sensor density per shipment. Pricing pressure stems from hospital procurement consolidation in Seoul-Gyeonggi, where integrated delivery networks leverage volume scale. Community pharmacies exhibit highest price sensitivity; cell therapy sponsors show lowest sensitivity due to product value density.
Supply Chain Analysis
Single-source vulnerability sits with liquid nitrogen supply concentrated in Ulsan and Yeosu industrial zones. Active refrigeration equipment draws from South Korean, German, and Japanese component suppliers. Dry ice and phase-change materials rest on petrochemical feedstock availability. Tariff exposure runs through imported monitoring hardware from Taiwan and sensor assemblies from China. Distribution runs through Seoul-Gyeonggi hub-and-spoke configurations radiating to Busan and Daegu hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's healthcare cold chain logistics sector is undergoing a technology-transition phase as blockchain-enabled temperature logging displaces paper-based batch documentation. Legacy documentation approaches are losing contract renewals to providers with integrated digital traceability platforms.
For Market Incumbents: Extend validated cold room capacity along the Busan-Gyeongnam pharmaceutical manufacturing belt before competitor depot establishment. Incumbents should deepen backward integration into IoT sensor maintenance capabilities to reduce third-party platform dependency. Samsung SDS and CJ Logistics face emerging cryogenic specialists capturing cell therapy clinical trial contracts through technician certification advantages.
For New Entrants and Emerging Players: Begin with cryogenic logistics services for CAR-T therapy sponsors in Songdo International Business District, where established providers lack liquid nitrogen vapor-phase expertise. The Gwangju-Honam region offers white-space opportunity for temperature-controlled distribution given current reliance on Seoul-based replenishment cycles. A go-to-market angle emphasizing MFDS real-time data submission readiness captures first-mover advantage ahead of impending regulatory mandates.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized cold chain boutiques given IoT-blockchain convergence catalysts accelerating contract win rates against generalist logistics providers. Long-term viability favors operators with captive cryogenic technician training pipelines and redundant liquid nitrogen sourcing arrangements. Watch for MFDS real-time traceability mandate announcement timing as inflection indicator for digital platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Real-Time Data Platform Deployment | First-mover advantage in vaccine distribution contracts as MFDS mandates live temperature transmission. |
| Cryogenic Technician Certification Program | Captures cell therapy logistics market as CAR-T clinical trials expand domestic pipeline. |
| Busan-Gyeongnam Cold Depot Establishment | Serves emerging biologics manufacturing belt currently dependent on Seoul-based distribution. |
| Blockchain Temperature Logging Integration | Reduces insurance premiums and dispute resolution timelines for high-value biologics exports. |
| Liquid Nitrogen Supply Diversification | Mitigates input cost volatility from Ulsan-Yeosu industrial gas concentration. |
Research Approach
MFDS regulatory filings, Korean pharmaceutical industry association reports, and Incheon International Airport cargo statistics formed the secondary backbone for this analysis. Primary interviews with cold chain operations managers at biopharmaceutical manufacturers, MFDS compliance officers, hospital pharmacy procurement directors, and third-party logistics provider executives validated demand assumptions. Bottom-up facility capacity assessments and top-down pharmaceutical production value estimates were triangulated to anchor market sizing.
Historical temperature-controlled logistics expenditure patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, temperature range, delivery mode, and end-user facility tier. CAGRs were derived from pharmaceutical production growth trajectories, MFDS enforcement intensity indices, and clinical trial pipeline expansion rates. Forecast inputs incorporated cell therapy pipeline stage transitions and refrigerant transition cost assumptions.
Underlying measurement precision varies by segment; cryogenic logistics carry tighter precision than ambient-controlled segments given limited operator universe. Forecasts reflect documented assumptions regarding MFDS mandate implementation timing and biopharmaceutical production capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Audiology Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Funeral Goods and Services Market