
 US Healthcare Staffing Market | 2026-2036
US Healthcare Staffing Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Staffing Market Intelligence
Joint Commission certification is reorganizing competitive access in US healthcare staffing by mandating standardized credentialing verification for agency-supplied clinicians. AMN Healthcare leverages national scale and proprietary vendor management systems to dominate enterprise hospital contracts. Cross Country Healthcare sustains geographic density through regional branch networks focused on Sun Belt markets. Aya Healthcare differentiates through technology-driven workforce marketplaces that reduce fill times for travel nursing assignments.
Healthcare staffing encompasses the recruitment, credentialing, and deployment of licensed clinical and administrative personnel to healthcare facilities on temporary, permanent, or contract bases, with placement cycles typically requiring 14 to 45 days depending on specialty and verification complexity. Its primary commercial purpose is to bridge workforce gaps caused by seasonal demand surges, permanent staff turnover, or specialized skill shortages without fixed labor cost expansion. Travel nursing commands the largest revenue pool within service type segments due to premium billing rates and extended assignment durations, while locum tenens exhibits the fastest structural growth as rural hospitals and outpatient surgery centers confront physician scarcity. Permanent placement retains mature margin characteristics with lower working capital intensity but faces compression from in-house hospital recruiting investments.
FDA oversight of clinician scope-of-practice in specialized settings, state board of nursing compact agreements, and CMS conditions of participation collectively determine which staffing agencies can supply personnel to Medicare-certified facilities. OSHA bloodborne pathogen standards and state-specific safe staffing ratio laws further constrain pool eligibility and shape liability insurance requirements for staffing firms. Stakeholders must monitor interstate licensure compact expansions and CMS site-neutral payment proposals that could redraw where contingent clinical labor delivers the highest returns.
Market Dynamics
Hospital systems are consolidating vendor relationships under single-source enterprise contracts, compressing the number of approved staffing agencies while demanding real-time workforce analytics and guaranteed fill-rate commitments from remaining suppliers.
Growth Catalysts
- Nurse Licensure Compact Expansion:Interstate mobility agreements now cover forty states, enabling rapid deployment of travel nurses across state lines without redundant credentialing delays.
- CMS Site-Neutral Payment Reforms:Reimbursement parity between hospital outpatient departments and ambulatory surgery centers is redirecting surgical volume to lower-cost settings that rely heavily on per-diem staffing.
- Telehealth Infrastructure:Remote patient monitoring platforms are creating hybrid staffing models where nurses supervise multiple facilities simultaneously from centralized command centers.
Market Restraints
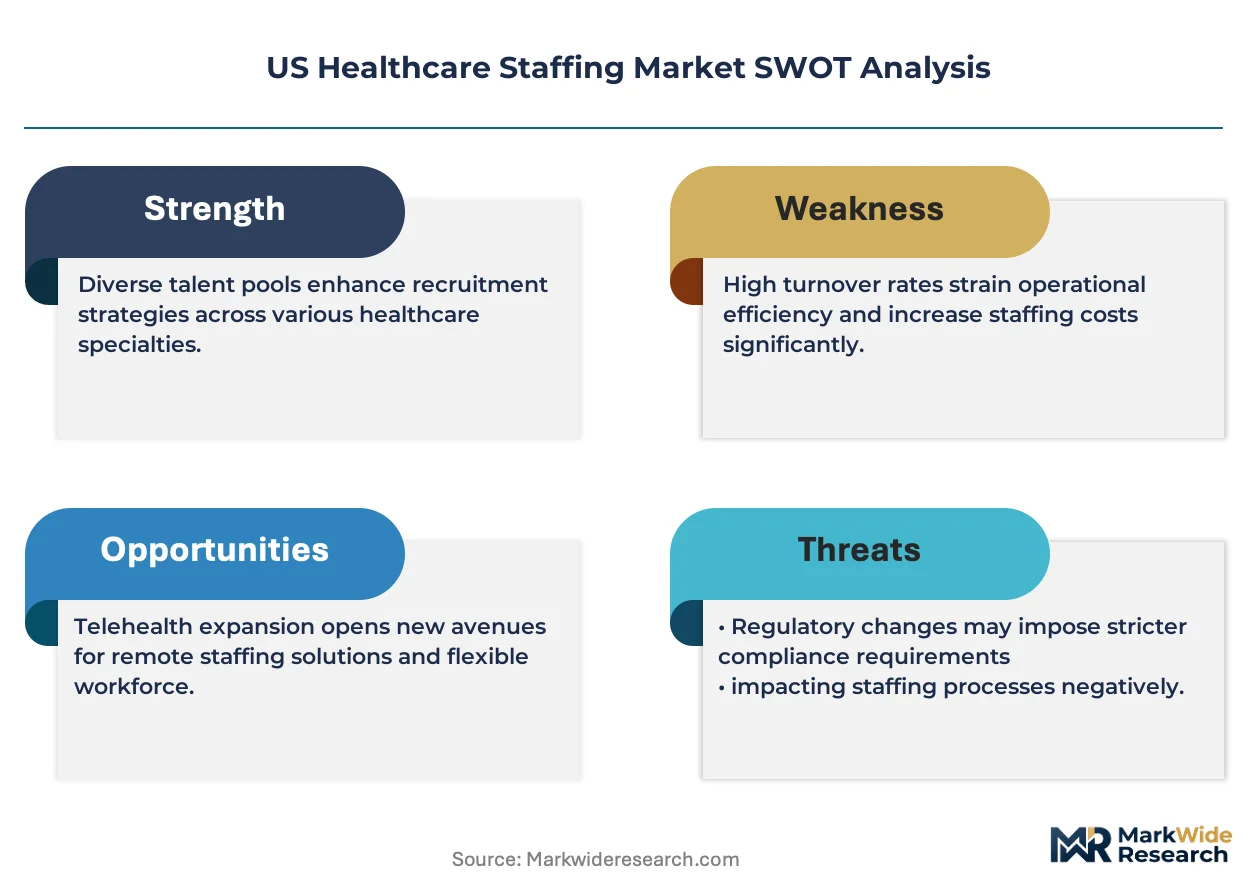
- Malpractice Insurance Concentration:Three national carriers dominate coverage for agency-placed clinicians, with premium spikes of thirty percent in high-risk specialties limiting agency margin flexibility.
- Joint Commission Audit Burden:Recertification cycles now require quarterly primary source verification updates, consuming administrative resources equivalent to fifteen percent of operating overhead.
- Permanent Staff Wage Compression:Hospital systems are raising internal nurse salaries to match travel rates, narrowing the billing spread that sustains agency profitability.
Strategic Opportunities
- Allied Health Specialization:Respiratory therapists, surgical technologists, and imaging specialists remain undersupplied relative to nursing, offering premium rate capture with lower competitive density.
- App-Based Per-Diem Platforms:Smartphone scheduling systems are displacing traditional branch-based dispatch for daily shift fill, reducing overhead per placement by eliminating physical office infrastructure.
- Behavioral Health Integration:Psychiatric nurse practitioners and licensed clinical social workers face severe shortage as Medicaid expansion broadens mental health coverage eligibility.
Industry Challenges
- Credential Verification Bottlenecks:Primary source confirmation for out-of-state licenses, certifications, and employment history extends onboarding timelines beyond client tolerance thresholds.
- EMR System Fragmentation:Agency clinicians must navigate disparate electronic medical record platforms across assignments, with Epic, Cerner, and MEDITECH variants requiring facility-specific training modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Staffing Market |
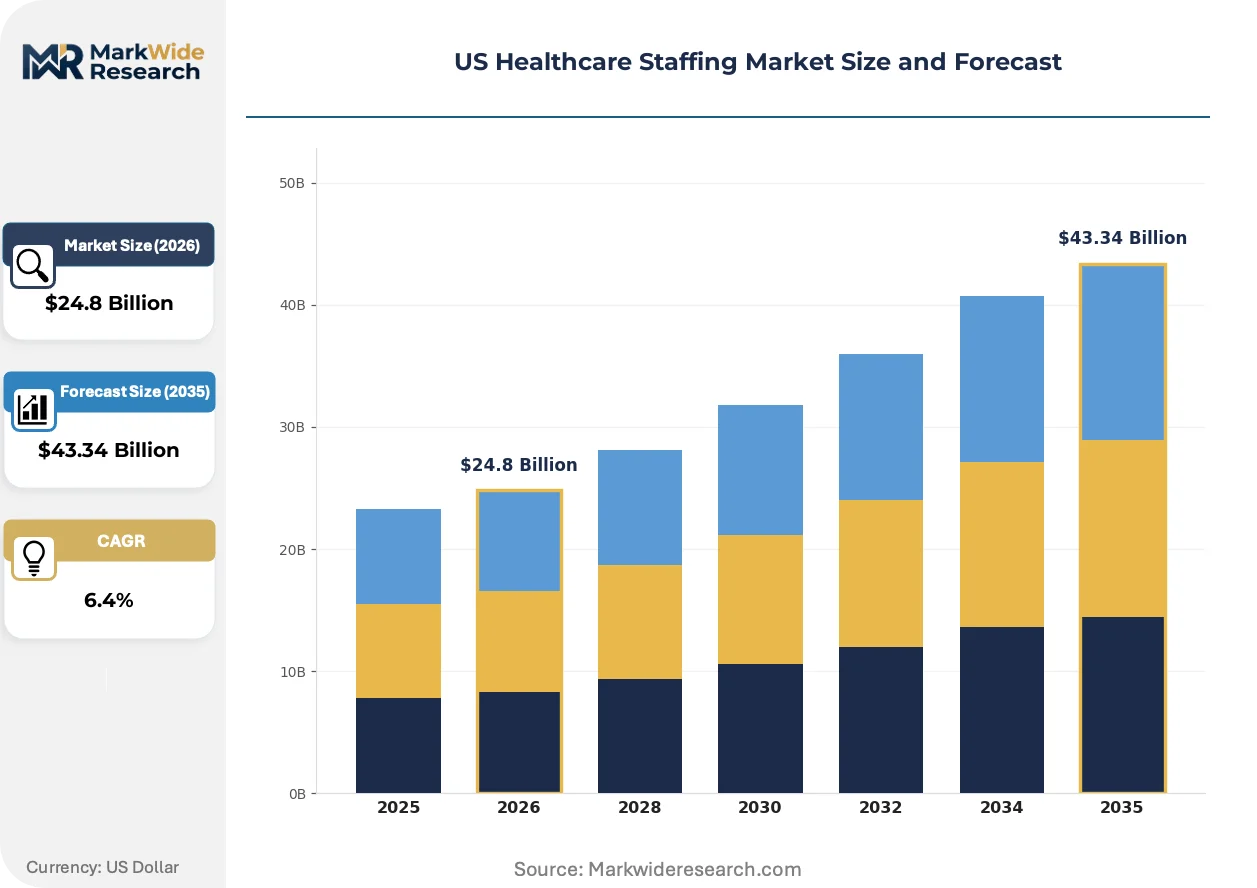
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Travel Nursing, Permanent Placement, Locum Tenens, Per Diem Staffing End User: Hospitals, Clinics, Long-Term Care Facilities, Home Healthcare Healthcare Role: Nurses, Physicians, Therapists, Administrative Staff Contract Type: Full-Time, Part-Time, Temporary, Contract |
| Companies Covered | Cross Country Healthcare, Envision Healthcare Corporation, AMN Healthcare, HealthTrust Workforce Solutions, TeamHealth, CHG Management, Maxim Healthcare Group, Prolink Staffing, Aya Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Staffing Market Strategic Shifts & Innovations
Workforce deployment models are fragmenting between high-touch enterprise partnerships and automated gig-economy platforms, with technology determining which agencies capture marginal volume growth.
Artificial intelligence-driven matching engines are bifurcating the travel nursing segment. These systems parse clinician preference data against facility need profiles to predict assignment fit and reduce early-termination rates. Large hospital networks are adopting proprietary algorithms to bypass traditional agency intermediaries, while independent platforms aggregate floating nurse pools for direct-to-facility contracting.
OSHA's updated bloodborne pathogen enforcement memorandum is tightening exposure control documentation requirements for temporary staff. Staffing agencies must now maintain site-specific exposure control plans for every placement location, with audit failures triggering debarment from facility vendor lists. California and Washington state occupational safety agencies are implementing parallel inspection protocols that exceed federal baselines.
Shift bidding platforms are replacing fixed-rate card systems as the dominant channel for per-diem nurse allocation. Clinicians now post availability windows and reserve rates, with facilities accepting or countering through mobile interfaces. This reverse-auction dynamic concentrates in Sun Belt metropolitan areas where nurse supply density supports competitive liquidity pools.
US Healthcare Staffing Market Segmentation
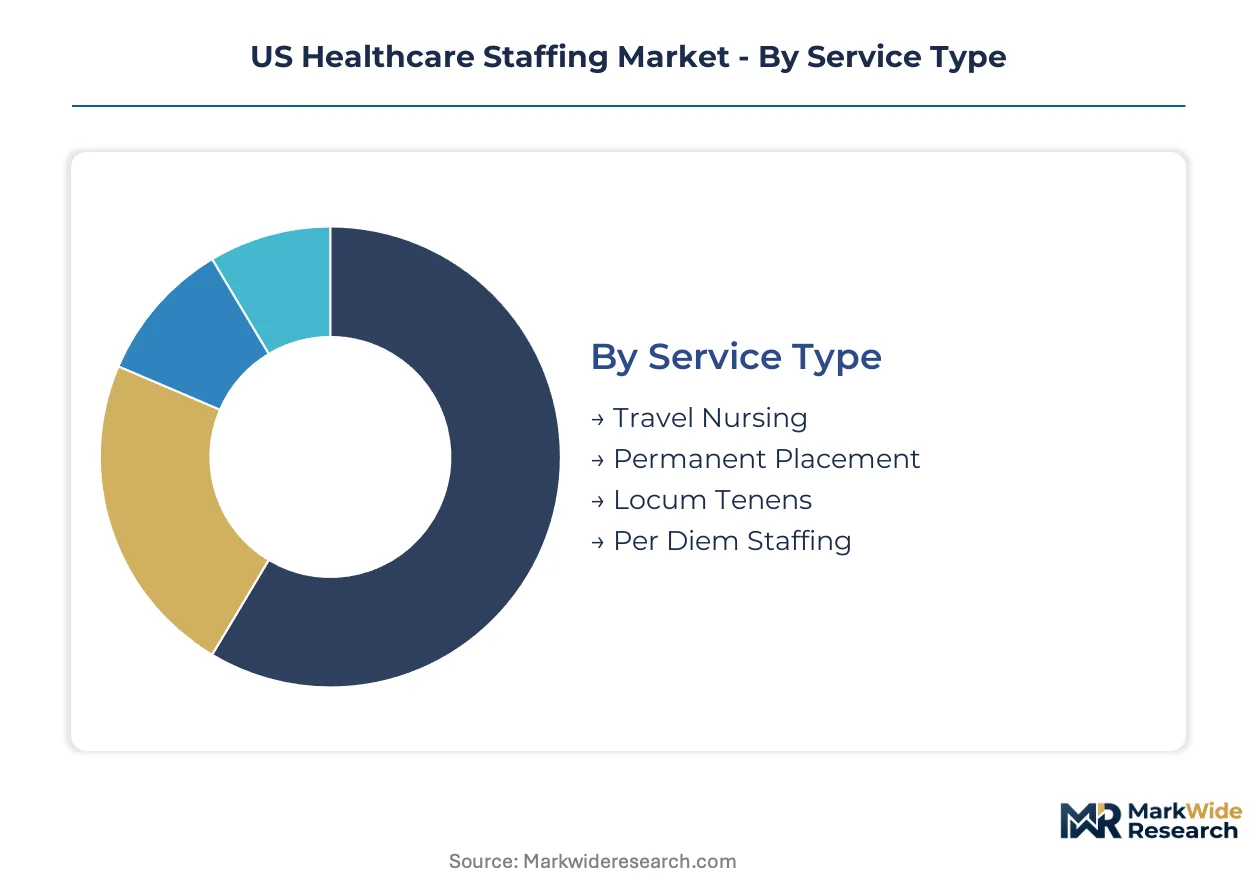
Healthcare staffing segments flow through distinct commercial channels that determine pricing power and working capital intensity. Travel nursing and locum tenens route through specialized agencies with credentialing infrastructure, while permanent placement and per-diem models compete with hospital in-house recruiting and gig-economy platforms respectively.
Service Type:
Channel economics vary sharply across service models, with enterprise VMS contracts capturing high-volume hospital relationships and app-based platforms disrupting daily shift allocation.
- Travel Nursing:Multi-week assignments with premium billing rates cover geographic shortages and seasonal census spikes. Texas, Florida, and California absorb the highest deployment volumes as Medicaid expansion and aging demographics strain permanent workforces.
- Locum Tenens:Temporary physician coverage spans rural hospitals and outpatient surgery centers confronting specialist scarcity. CMS site-neutral payment reforms accelerate surgical volume migration to ambulatory settings dependent on per-diem clinical labor.
- Permanent Placement:Lower working capital requirements and mature margin profiles characterize this segment, though hospital systems raising internal salaries compress agency fee spreads.
- Per Diem Staffing:Smartphone scheduling platforms displace branch-based dispatch, eliminating physical office overhead for daily shift fill in metropolitan markets with sufficient nurse liquidity.
By volume, travel nursing leads. By growth pace, locum tenens is expanding most quickly.
End User:
Facility type determines contract structure, with acute care hospitals demanding guaranteed fill-rate commitments and long-term care accepting higher clinician turnover.
- Hospitals:Enterprise vendor consolidation under single-source contracts compresses approved agency pools while mandating real-time workforce analytics. Joint Commission recertification requirements now demand quarterly primary source verification updates.
- Clinics:Outpatient settings rely heavily on per-diem staffing as CMS reimbursement parity redirects surgical volume from hospital outpatient departments.
- Long-Term Care Facilities:Medicaid reimbursement constraints limit rate flexibility for agency labor, driving reliance on lower-cost part-time and contract arrangements.
- Home Healthcare:Remote patient monitoring platforms enable hybrid models where nurses supervise multiple patients simultaneously from centralized command centers.
By revenue concentration, hospitals dominate. By structural shift, home healthcare shows the steepest trajectory change.
Healthcare Role:
Credentialing complexity and malpractice exposure stratify profitability across clinical disciplines, with specialized therapists offering premium capture relative to competitive density.
- Nurses:Licensure compact coverage across forty states enables rapid interstate deployment without redundant verification delays. OSHA bloodborne pathogen enforcement tightening raises exposure control documentation burdens for temporary placements.
- Physicians:Malpractice insurance concentration among three national carriers limits agency margin flexibility, with premium spikes of thirty percent in high-risk specialties.
- Therapists:Respiratory therapists, surgical technologists, and imaging specialists remain undersupplied relative to nursing, offering rate premiums with lower competitive density.
- Administrative Staff:EMR system fragmentation across Epic, Cerner, and MEDITECH variants requires facility-specific training modules that extend onboarding timelines.
By headcount, nurses comprise the largest pool. By supply-demand imbalance, therapists command the strongest pricing leverage.
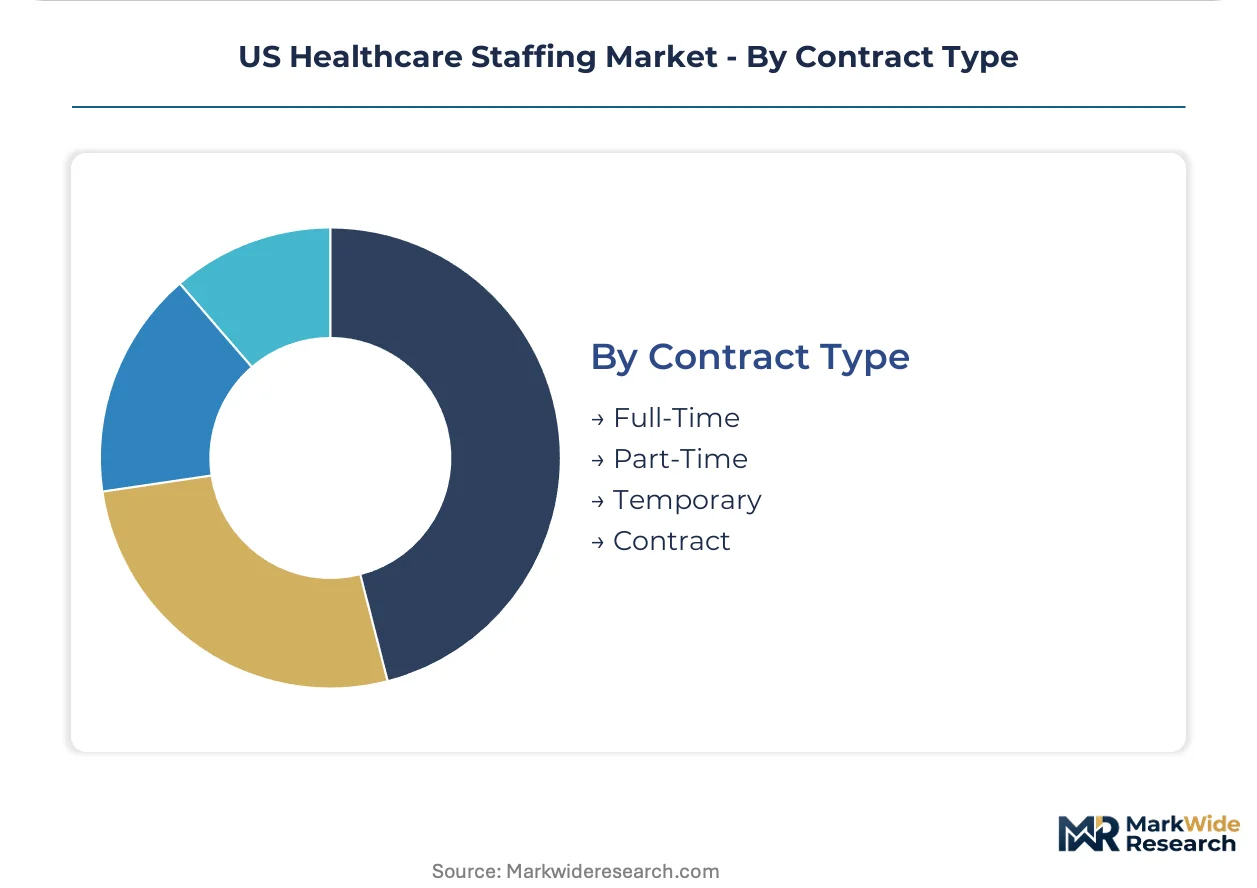
Contract Type:
Labor classification shapes regulatory exposure and benefits obligations, with temporary arrangements capturing volatility-driven demand spikes.
- Full-Time:Permanent hospital employment competes directly with agency placement as systems raise internal salaries to match travel rates.
- Part-Time:Flexible scheduling accommodates workforce retention in high-turnover clinical environments.
- Temporary:Fourteen to forty-five day placement cycles bridge seasonal demand surges without fixed labor cost expansion.
- Contract:Defined-duration agreements align clinician supply with specific project timelines or facility openings.
By assignment volume, temporary contracts lead. By strategic priority, full-time conversion efforts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid expansion and aging demographics are redirecting staffing demand toward Sun Belt states with the highest patient census volatility. Texas, Florida, and California absorb disproportionate placement volumes as rural hospitals and urban medical centers alike confront permanent workforce attrition.
Texas
Medicaid expansion under the Affordable Care Act has swollen eligible patient populations across Houston and Dallas-Fort Worth metropolitan corridors. The Texas Board of Nursing maintains streamlined endorsement pathways for compact-licensed nurses, accelerating agency deployment timelines. San Antonio and Austin medical districts report sustained demand for travel nursing contracts during winter respiratory surge seasons.
Florida
Snowbird migration patterns generate predictable census spikes in Palm Beach and Broward County hospital systems each November through April. Florida's participation in the Nurse Licensure Compact enables same-day credentialing verification for out-of-state clinicians. Tampa Bay and Orlando health networks are consolidating vendor relationships under single-source enterprise contracts with guaranteed fill-rate commitments.
California
OSHA's bloodborne pathogen enforcement memorandum imposes site-specific exposure control documentation requirements that extend agency onboarding timelines. Los Angeles County and Bay Area hospital systems confront the nation's most acute nursing shortage ratios relative to patient beds. Sacramento-based health plans are piloting hybrid staffing models where nurses supervise multiple facilities through centralized command centers.
Arizona
Retiree population concentration in Maricopa County drives year-round demand for per-diem clinical labor in skilled nursing facilities. The Arizona State Board of Nursing coordinates with compact administrators to expedite multistate license verification for travel nurses. Phoenix metropolitan hospitals are adopting app-based shift bidding platforms to displace traditional branch-based dispatch systems.
North Carolina
Research Triangle Park medical centers compete for specialized allied health talent against Atlanta and Nashville markets. The North Carolina Board of Nursing enforces continuing education requirements that agency credentialing departments must verify quarterly. Charlotte and Raleigh-Durham health systems are raising internal nurse salaries to narrow billing spreads with travel rates.
US Healthcare Staffing Market Key Industry Players
Player mix skews toward national-scale agencies with proprietary vendor management systems and regional specialists with dense branch networks. Market structure concentrates around three operational tiers: enterprise contractors serving integrated delivery networks, technology platforms aggregating clinician supply pools, and specialty boutiques focused on high-credentialling disciplines. Dominant competitive moves include M&A consolidation of regional agencies and backward integration into credentialing verification infrastructure to compress placement cycle times.
Among publicly traded staffing enterprises, AMN Healthcare and Cross Country Healthcare exemplify divergent scale strategies. AMN anchors the enterprise-contract tier through national coverage and integrated workforce analytics. Cross Country Healthcare occupies a position within the regional density archetype, sustaining Sun Belt market presence through metropolitan branch networks. Aya Healthcare represents the technology-platform vector, deploying algorithmic matching engines to reduce travel nursing fill times. These three entities collectively illustrate how vendor consolidation, geographic specialization, and automation are bifurcating competitive positioning across hospital system procurement channels.
| Leading Market Players |
|---|
| Cross Country Healthcare |
| Envision Healthcare Corporation |
| AMN Healthcare |
| HealthTrust Workforce Solutions |
| TeamHealth |
| CHG Management |
| Maxim Healthcare Group |
| Prolink Staffing |
| Aya Healthcare |
| Others |
Cost & Logistics Intelligence
Fourteen-to-forty-five day placement cycles from credential initiation to clinician deployment tether pricing power to verification speed, compressing margins for agencies with slower primary-source confirmation workflows while rewarding those with integrated digital credentialing infrastructure. This lead-time band structures how hospital systems evaluate vendor proposals, privileging suppliers that collapse onboarding timelines below client tolerance thresholds.
Pricing Analysis
Joint Commission certification level creates the primary spread between premium and standard agency tiers, with enterprise-contract holders commanding rate premiums over regional boutiques. Three-tier pricing structure across premium, standard, and economy levels reflects fill-rate guarantee strength, real-time analytics provision, and credentialing automation depth. Cost compression in the standard tier is intensifying because hospital systems are raising internal nurse salaries to match travel rates. Price-sensitive buyers cluster in long-term care facilities facing Medicaid reimbursement constraints, while acute care hospitals demonstrate lower sensitivity due to census volatility penalties.
Supply Chain Analysis
The United States anchors clinician talent pools, with Texas, Florida, and California producing the highest deployment volumes as Medicaid expansion and aging demographics strain permanent workforces. The supply chain draws from state nursing boards, compact licensure administrators, and specialized allied health training programs for respiratory therapists and surgical technologists. Single-source vulnerability concentrates in malpractice insurance, where three national carriers dominate coverage for agency-placed clinicians. Distribution runs through enterprise vendor management systems for hospital networks and app-based platforms for per-diem shift allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where workforce marketplace interoperability is displacing traditional branch-based dispatch, with API-connected credentialing systems enabling direct-to-facility contracting that bypasses legacy agency intermediaries.
For Market Incumbents: Shield enterprise contract positions by backward integration into proprietary credentialing verification infrastructure that compresses placement cycle times below competitor benchmarks. Defend against technology-platform entrants by embedding real-time workforce analytics into vendor management system dashboards that hospital procurement committees cannot easily replicate. Prioritize certification investment in Joint Commission primary-source verification automation to absorb quarterly update burdens that consume fifteen percent of rival operating overhead. For New Entrants and Emerging Players: Lead with allied health specialization targeting respiratory therapists, surgical technologists, and imaging specialists where supply-demand imbalances offer premium rate capture with lower competitive density than nursing saturation. Target behavioral health integration white space, as psychiatric nurse practitioners and licensed clinical social workers face severe shortage amid Medicaid expansion. Pursue app-based per-diem platforms in Sun Belt metropolitan areas where nurse supply density supports competitive liquidity pools and smartphone scheduling eliminates physical office infrastructure costs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor relationship compression under single-source enterprise contracts favors national-scale agencies with integrated workforce analytics over fragmented regional operators. Acquisition target archetype: technology-enabled platforms with algorithmic matching engines and compact-licensed clinician pools that reduce fill times for travel nursing assignments. Watch interstate licensure compact expansion as the signal indicating where contingent clinical labor delivers the highest returns.| Strategic Initiative | Industry Significance |
|---|---|
| Credentialing Automation Investment | Joint Commission quarterly verification requirements consume fifteen percent of operating overhead for manual processors. |
| Allied Health Specialization | Respiratory therapists and imaging specialists command premium rates with lower competitive density than saturated nursing segments. |
| Enterprise VMS Integration | Hospital procurement committees demand real-time workforce analytics and guaranteed fill-rate commitments from approved suppliers. |
| Compact Licensure Expansion | Forty-state Nurse Licensure Compact coverage enables rapid interstate deployment without redundant verification delays. |
| App-Based Per-Diem Platform Launch | Smartphone scheduling systems reduce overhead per placement by eliminating physical office infrastructure in metropolitan markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, staffing agency operations executives, state nursing board administrators, and GPO contracts managers; and secondary validation against CMS Medicare reimbursement data, hospital procurement databases, Joint Commission certification records, and state licensure compact administrative filings. Bottom-up clinician placement volume estimates triangulated against top-down hospital staffing expenditure patterns.
Across the modeling period, the analytical framework segmented by service type, healthcare role, contract classification, and end-user facility category to isolate demand drivers. CAGRs were derived from trend extrapolation of placement volumes and billing rate movements, with cross-reference to Medicaid expansion timelines and CMS site-neutral payment reform implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained Nurse Licensure Compact participation, stable malpractice insurance carrier capacity, or unchanged Joint Commission audit intensity would require recalibration. Forecasts reflect assumptions regarding hospital vendor consolidation velocity and technology-platform penetration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Acute Care Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Outpatient Clinics Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Healthcare Transportation Services Market