
 Inhalation CDMO Market | 2026-2036
Inhalation CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Inhalation CDMO Market Insights
Hydrofluoroalkane (HFA) propellant chemistry is realigning metered dose inhaler economics as manufacturers phase out older chlorofluorocarbon formulations. Lonza Group AG leverages integrated API-to-device capabilities across Swiss and US sites. Catalent anchors North American clinical-to-commercial respiratory manufacturing with specialized blow-fill-seal expertise. Hovione differentiates through proprietary particle engineering platforms for dry powder inhaler formulations.
An inhalation CDMO provides outsourced development, manufacturing, and regulatory services for drug products delivered via the pulmonary or nasal route, requiring aerodynamic particle size distributions typically between one and five micrometers to achieve deep lung deposition. The service type dimension spans formulation development through commercial manufacturing, with analytical testing and regulatory support capturing disproportionate margin pools as complexity rises. Product type demand tilts toward dry powder inhalers and soft mist inhalers where device innovation outpaces generic commoditization, while metered dose inhalers retain volume leadership through established asthma and COPD portfolios.
FDA's Quality by Design mandates and EMA's Medical Device Regulation convergence with pharmaceutical oversight reshape validation requirements for combination products, elevating compliance costs for sponsors. China's NMPA implements GB standards for inhaled generics that demand local bioequivalence studies, creating market access barriers for foreign-developed assets. Stakeholders must weigh captive capacity investments against partnership models as regulatory divergence between major agencies intensifies.
Market Dynamics
HFA propellant transition and FDA Quality by Design mandates are compressing sponsor timelines while elevating technical barriers for respiratory combination products. CDMOs must now integrate device engineering with formulation science under converging pharmaceutical and medical device oversight.
Growth Catalysts
- EMA Medical Device Regulation convergence:Pharmaceutical sponsors now require partners with dual competency in drug substance and device validation, expanding addressable contract services.
- Chronic respiratory disease prevalence:Asthma and COPD patient populations in the United States, Germany, and China sustain demand for scalable manufacturing of inhaled corticosteroids and bronchodilators.
- Soft mist inhaler technology maturation:Device innovation beyond traditional pressurized systems creates formulation complexity that biopharmaceutical companies outsource to specialized CDMOs.
Market Restraints
- API supply concentration:Corticosteroid and beta-agonist active pharmaceutical ingredients concentrate among Indian and Chinese suppliers, exposing sponsors to geopolitical and quality disruption risks.
- Specialized analytical infrastructure:Cascade impaction and laser diffraction particle sizing equipment requires capital outlays that smaller CDMOs cannot absorb.
- Propellant cost volatility:HFA-134a and HFA-227 pricing fluctuates with fluorochemical feedstock markets, compressing margins on established metered dose inhaler programs.
Strategic Opportunities
- NMPA GB standard localization:Foreign sponsors seeking China market access must replicate bioequivalence studies domestically, creating demand for local CDMO partnerships.
- Biologic dry powder inhaler expansion:Monoclonal antibodies and peptide therapeutics for pulmonary delivery require novel spray-drying and particle engineering capabilities.
- Continuous manufacturing adoption:FDA guidance on advanced manufacturing technologies incentivizes sponsors to replace batch processing with integrated powder-to-device production lines.
Industry Challenges
- Aerosol science talent scarcity:Formulation scientists with pulmonary pharmacokinetics expertise command premium compensation, constraining CDMO hiring pipelines.
- Combination product validation timelines:FDA pre-submission meetings and design verification protocols extend development cycles beyond traditional oral solid dosage programs.
- Legacy device platform integration:Sponsors with established inhaler portfolios face technical debt when migrating to next-generation connected or breath-actuated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhalation CDMO Market |
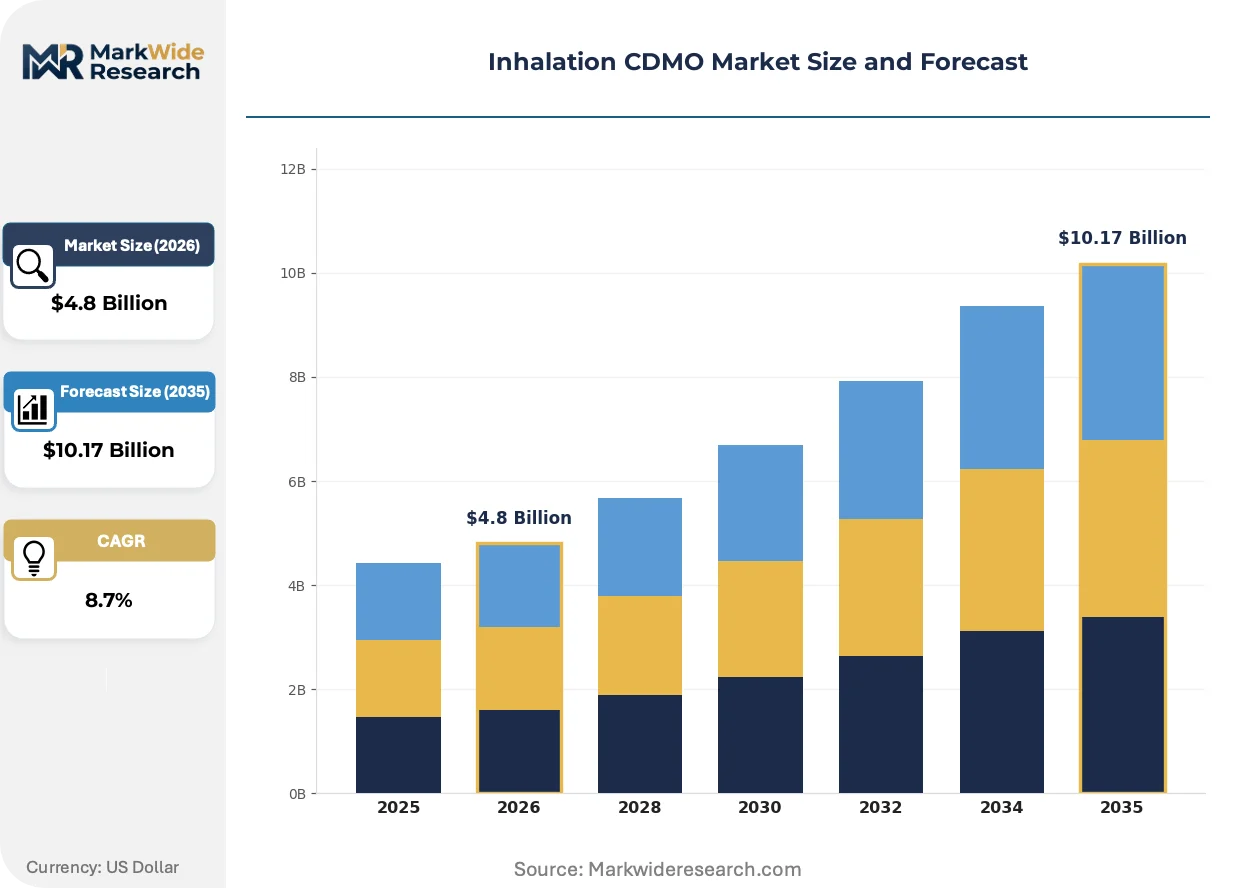
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Analytical Testing, Clinical Trial Material Manufacturing, Commercial Manufacturing, Regulatory Support Product Type: Dry Powder Inhalers, Metered Dose Inhalers, Nebulizers, Soft Mist Inhalers, Nasal Sprays Therapy Area: Respiratory Disorders, Infectious Diseases, Cardiovascular Conditions, Central Nervous System, Metabolic Disorders End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Government Agencies, Contract Research Organizations |
| Companies Covered | Lonza Group AG, Catalent, Recipharm AB, Hovione, Kindeva Drug Delivery, AptarGroup, Vectura Group, Nemera, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhalation CDMO Market Trends and Innovations
Digitalization of inhaler devices and advanced particle engineering platforms are redefining competitive differentiation beyond conventional manufacturing scale. Sponsors now prioritize partners with integrated analytical and regulatory capabilities spanning multiple jurisdictions.
Connected inhaler technology is decentralizing clinical trial data collection and post-market surveillance. Pharmaceutical sponsors in the United States and Germany embed sensors and wireless modules into dry powder and soft mist devices. This capability compresses pharmacovigilance timelines while enabling real-world evidence generation that FDA and EMA now accept for label expansion.
REACH F-Gas Regulation phase-down is forcing reformulation of HFA propellant blends across European manufacturing networks. EMA marketing authorization holders must demonstrate environmental sustainability credentials alongside clinical efficacy. Metered dose inhaler portfolios face accelerated redevelopment timelines as fluorinated gas quotas tighten through 2030.
Biopharmaceutical procurement departments now bundle device development with commercial manufacturing under single-source arrangements. Traditional arm's-length relationships between formulation scientists and device engineers are dissolving. United States-based sponsors particularly favor CDMOs offering co-located analytical, regulatory, and scaled production capabilities under unified quality systems.
Inhalation CDMO Market Segmentation
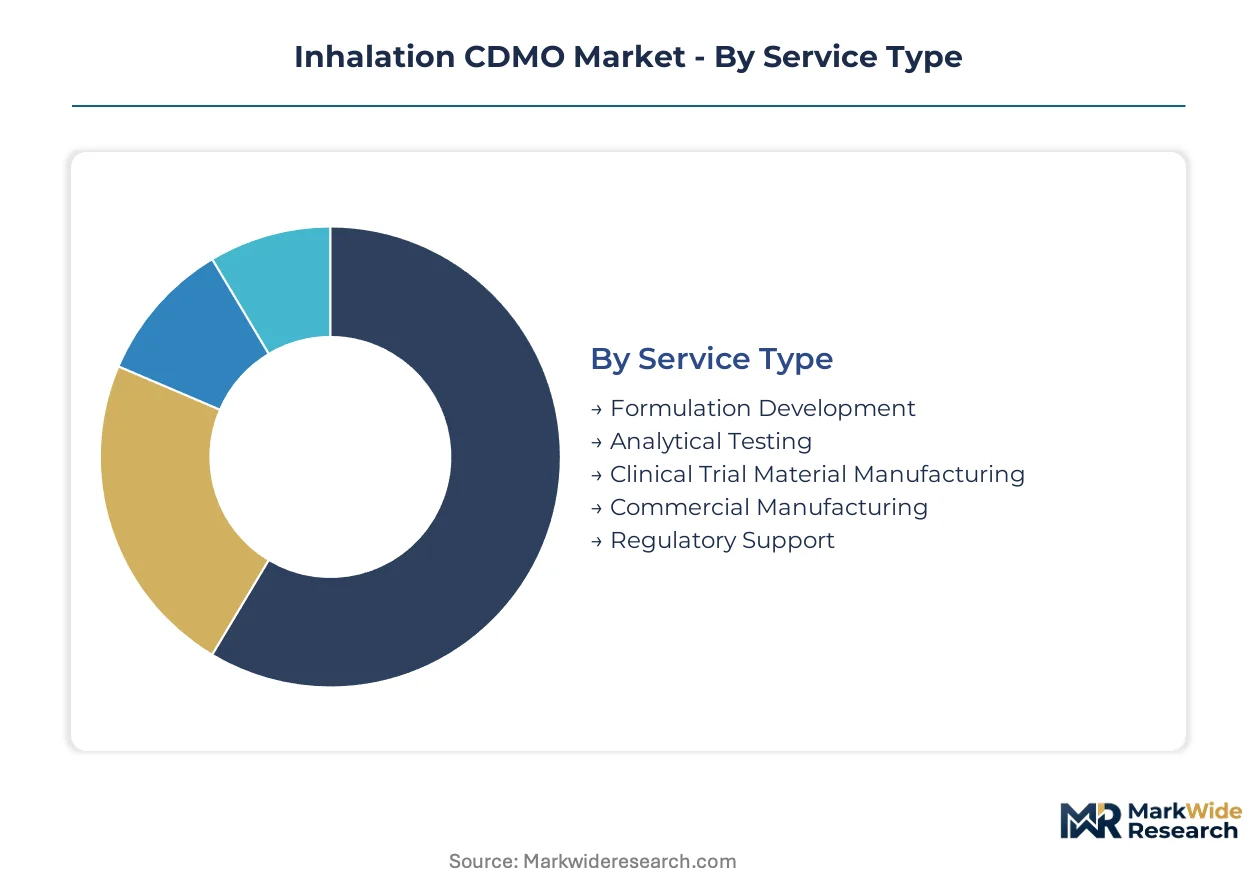
Segmentation in the inhalation CDMO market reveals distinct capability requirements across service types and product formats. Pharmaceutical sponsors select partners based on technical specialization, regulatory geography, and the complexity of drug-device integration demanded by specific therapeutic programs.
Service Type:
Upgrade cycles in inhalation manufacturing now center on integrated service bundles that compress development timelines from formulation through commercial launch.
- Formulation Development:Particle engineering for aerodynamic performance between one and five micrometers demands spray-drying, micronization, and co-spray expertise. United States sponsors prioritize partners with FDA Quality by Design documentation capabilities for IND-enabling studies.
- Analytical Testing:Cascade impaction, laser diffraction, and delivered dose uniformity testing require specialized infrastructure that smaller CDMOs cannot replicate. Germany and Switzerland host concentrated analytical capacity serving EMA-regulated programs.
- Clinical Trial Material Manufacturing:GMP batches for Phase I-III respiratory studies with device assembly and labeling under single quality systems.
- Commercial Manufacturing:Scaled production lines with automated assembly, testing, and serialization for market supply.
- Regulatory Support:Dossier preparation and agency correspondence for FDA, EMA, and NMPA combination product submissions.
Commercial Manufacturing sits at the top of the volume ranking, with Regulatory Support climbing the fastest as convergence between pharmaceutical and medical device oversight intensifies.
Product Type:
Cost tier differentiation separates legacy pressurized systems from higher-margin device innovations requiring novel formulation platforms.
- Dry Powder Inhalers:Device-reservoir or capsule-based systems demanding precise powder flow properties and moisture protection. United States and German sponsors drive demand for breath-actuated and connected variants that integrate sensors for adherence monitoring.
- Metered Dose Inhalers:HFA-propelled formulations transitioning from chlorofluorocarbon legacy chemistries. China NMPA GB standards for inhaled generics require local bioequivalence studies, reshaping sourcing patterns for multinational sponsors.
- Nebulizers:Compressor and mesh-based systems for hospital and home care delivery of bronchodilators and antibiotics.
- Soft Mist Inhalers:Mechanical spring-driven devices generating slow-moving aerosol clouds with reduced oropharyngeal deposition.
- Nasal Sprays:Pump and pressurized systems for local and systemic delivery via the nasal mucosa.
Metered Dose Inhalers capture the largest share of current programs, while Soft Mist Inhalers gain share fastest as device innovation outpaces generic commoditization in established categories.
Therapy Area:
Application concentration in chronic respiratory disease creates volume anchors, while emerging therapeutic classes expand addressable scope.
- Respiratory Disorders:Asthma and COPD maintenance therapies comprising inhaled corticosteroids, long-acting beta-agonists, and combination bronchodilators. United States patient populations and reimbursement structures sustain the largest commercial manufacturing volumes.
- Infectious Diseases:Antibiotic and antiviral aerosol delivery for resistant pathogens, with nebulized formulations for hospital-acquired pneumonia.
- Cardiovascular Conditions:Pulmonary arterial hypertension therapies requiring precise dosing and deep lung deposition.
- Central Nervous System:Migraine and Parkinson's disease candidates exploiting blood-brain barrier penetration via olfactory transport.
- Metabolic Disorders:Inhaled insulin and peptide hormones for diabetes management.
Respiratory Disorders anchor current demand, with Central Nervous System applications expanding most quickly as biologic delivery platforms mature.
End User:
Customer type determines contract structure, with pharmaceutical procurement departments now bundling development and manufacturing under unified partnerships.
- Pharmaceutical Companies:Large-cap sponsors with established respiratory portfolios outsourcing capacity expansion and device innovation programs. United States-based firms favor single-source CDMO relationships spanning Swiss and North American sites.
- Biotechnology Firms:Venture-backed developers of monoclonal antibody and peptide dry powder formulations requiring novel particle engineering capabilities.
- Research Institutions:Academic centers conducting NIH-funded pulmonary pharmacokinetics studies with small-scale manufacturing needs.
- Government Agencies:Stockpile and biodefense programs for mass casualty respiratory countermeasures.
- Contract Research Organizations:Clinical service providers subcontracting manufacturing for respiratory trial execution.
Pharmaceutical Companies dominate contract value, with Biotechnology Firms posting the steepest expansion trajectory as pulmonary biologic pipelines advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New Jersey-Philadelphia corridor anchors North American inhalation manufacturing capacity, with FDA-regulated sites serving sponsors pursuing IND-enabling studies through commercial launch. Contract development activity clusters where regulatory expertise, specialized analytical infrastructure, and device engineering capabilities converge.
United States
FDA Quality by Design mandates and combination product pre-submission requirements drive sponsor outsourcing to CDMOs with integrated regulatory capabilities. The agency's Center for Drug Evaluation and Research maintains stringent aerodynamic particle size validation protocols for inhaled generics. Massachusetts and North Carolina host concentrated biotechnology sponsor demand for monoclonal antibody dry powder formulations.
Germany
EMA Medical Device Regulation convergence with pharmaceutical oversight elevates compliance costs for respiratory combination products. The Federal Institute for Drugs and Medical Devices enforces post-market surveillance requirements for connected inhaler devices. The Rhine-Main and Bavarian regions concentrate analytical testing capacity serving EMA-regulated development programs.
China
NMPA GB standards for inhaled generics mandate local bioequivalence studies, creating market access barriers for foreign-developed assets. The National Medical Products Administration implements dual carbon goals that reshape propellant chemistry requirements. Shanghai and Suzhou industrial parks attract multinational CDMO investments targeting domestic bioequivalence capabilities.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines marketing authorization for respiratory combination products. The country's pharmaceutical cluster benefits from proximity to European device engineering expertise. Basel and Zurich host integrated API-to-device manufacturing platforms serving global sponsor portfolios.
United Kingdom
Medicines and Healthcare products Regulatory Agency post-Brexit divergence from EMA procedures creates parallel submission requirements for inhaled therapeutics. The MHRA maintains recognition agreements with FDA and Swissmedic that facilitate multinational development strategies. Cambridge and Oxfordshire concentrate early-stage biotechnology sponsor demand for novel pulmonary delivery platforms.
Inhalation CDMO Market Competitive Landscape
Global majors compete with regional champions across regulatory geography and device technology specialization, producing a tiered structure where scale-driven integrated players coexist with focused analytical and formulation specialists. Market concentration elevates around sponsors demanding single-source partnerships spanning Swiss and North American quality systems. Three archetypes dominate: full-service respiratory CDMOs with captive device capabilities, specialized particle engineering platforms, and regional analytical testing laboratories. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as sponsors consolidate vendor relationships.
Within the integrated service tier, Lonza Group AG and Catalent exemplify archetypes of global-scale respiratory manufacturing with cross-continental site networks. Hovione occupies a specialist position in proprietary particle engineering for dry powder inhaler applications. These three anchors demonstrate how CDMOs differentiate through either geographic coverage breadth or technical depth in specific formulation modalities.
| Leading Market Players |
|---|
| Lonza Group AG |
| Catalent |
| Recipharm AB |
| Hovione |
| Kindeva Drug Delivery |
| AptarGroup |
| Vectura Group |
| Nemera |
| Stevanato Group |
| Others |
Pricing and Supply Chain Analysis
REACH F-Gas Regulation phase-down gates qualified supply for European metered dose inhaler programs and anchors premium-tier pricing access for sponsors demonstrating environmental compliance credentials alongside clinical performance. HFA-134a and HFA-227 propellant cost volatility feeds directly into contract manufacturing economics, compressing margins on established portfolios while rewarding CDMOs with backward integration into fluorochemical sourcing.
Pricing Analysis
Input-cost pass-through from HFA propellant markets shapes contract manufacturing economics, with pricing stratifying across integrated regulatory-premium, standard compliance, and economy generic tiers. Price differentiation rests on FDA Quality by Design documentation depth and EMA Medical Device Regulation certification status. Cost compression in economy-tier metered dose inhaler programs is intensifying because Indian and Chinese API suppliers face escalating environmental compliance costs. Biotechnology sponsors with monoclonal antibody dry powder programs exhibit lowest price sensitivity, while generic sponsors in China demonstrate highest sensitivity to per-unit manufacturing costs.
Supply Chain Analysis
Freight cost escalation for temperature-controlled active pharmaceutical ingredient shipments from India and China to United States and European manufacturing sites is reshaping regional sourcing strategies. Corticosteroid and beta-agonist API production concentrates in India, China, and Italy, while device engineering capabilities cluster in Germany, Switzerland, and the United States. Specialized analytical equipment including cascade impactors and laser diffraction systems draws from German, Swiss, and United States suppliers. Single-source vulnerability permeates HFA propellant feedstock markets. Distribution runs through qualified GMP warehousing networks with regional serialization compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inhalation CDMO market reads as a late-cycle quality story where sponsor procurement departments now bundle device development with commercial manufacturing under unified partnerships, shifting demand toward CDMOs with co-located analytical, regulatory, and scaled production capabilities.
For Market Incumbents: To counter biologic dry powder inhaler specialists capturing biotechnology sponsor relationships, full-service respiratory CDMOs must deepen particle engineering capabilities through captive spray-drying platform investments and expand regulatory support bandwidth for NMPA GB standard localization requirements in China. For New Entrants and Emerging Players: Regional analytical testing laboratories represent the most penetrable entry point, particularly for sponsors seeking EMA-regulated programs requiring cascade impaction and delivered dose uniformity validation. Target hospital-focused nebulized antibiotic programs in Germany and the United Kingdom where device innovation lags behind dry powder and soft mist categories. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap CDMOs with proprietary particle engineering platforms because sponsor consolidation of vendor relationships favors technical depth over geographic coverage alone. Long-term viability centers on biologic dry powder inhaler expansion over the next decade. Watch FDA pre-submission meeting volume for combination products as the inflection indicator for regulatory service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Support Expansion | NMPA GB standard localization capabilities unlock China market access for foreign sponsors. |
| Particle Engineering Platform Investment | Spray-drying and micronization capabilities capture biologic dry powder inhaler demand from biotechnology sponsors. |
| Backward Integration into HFA Propellant Supply | Captive fluorochemical sourcing insulates margins from REACH F-Gas Regulation quota volatility. |
| Connected Inhaler Device Development | Sensor integration capabilities compress pharmacovigilance timelines for FDA and EMA real-world evidence programs. |
| Continuous Manufacturing Adoption | Integrated powder-to-device production lines align with FDA advanced manufacturing technology guidance. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CDMO commercial operations directors, alongside secondary validation against FDA 510(k) filings, EMA centralized procedure databases, and NMPA drug approval records — were reconciled through bottom-up and top-down triangulation. Supply-side assessment incorporated facility inspection data and manufacturing capacity disclosures. Demand-side validation drew from sponsor pipeline databases and clinical trial registration records.
Data-stream reconciliation across service type, product format, therapy area, and regional regulatory cluster dimensions produced volume and value estimates across the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis. Forecast inputs incorporated HFA propellant cost trajectory assumptions, chronic respiratory disease prevalence projections, and regulatory divergence scenarios between FDA, EMA, and NMPA oversight frameworks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH F-Gas Regulation enforcement stringency, NMPA bioequivalence study requirement evolution, and biotechnology sponsor funding availability for pulmonary biologic programs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Lyophilization Equipment Market