
 Oral Dosing Cups Market | 2026-2036
Oral Dosing Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Dosing Cups Market Analytics
Hospital procurement channels is reconfiguring how oral dosing cups reach end users, with group purchasing organizations consolidating supplier rosters and favoring manufacturers with multi-site distribution capability. Comar leverages its blow-molding expertise to supply calibrated plastic dosing vessels directly to institutional buyers. Gerresheimer AG anchors European pharmacy supply through its glass and polymer primary packaging division. Medline Industries competes on logistics scale, using its direct-to-facility distribution network to bypass traditional wholesale tiers.
Oral dosing cups are precision-measured vessels, typically polypropylene or polystyrene molded to ±5% volumetric accuracy, designed for safe liquid medication measurement and administration in clinical and domestic settings. Graduated cups dominate pharmacy dispensing due to their dual-scale markings in milliliters and teaspoons, while child-resistant cups command premium positioning as regulatory mandates expand. Single-use plastic variants sustain volume leadership in hospital infection-control protocols, whereas biodegradable materials are gaining traction in European retail pharmacy chains seeking to preempt packaging waste directives.
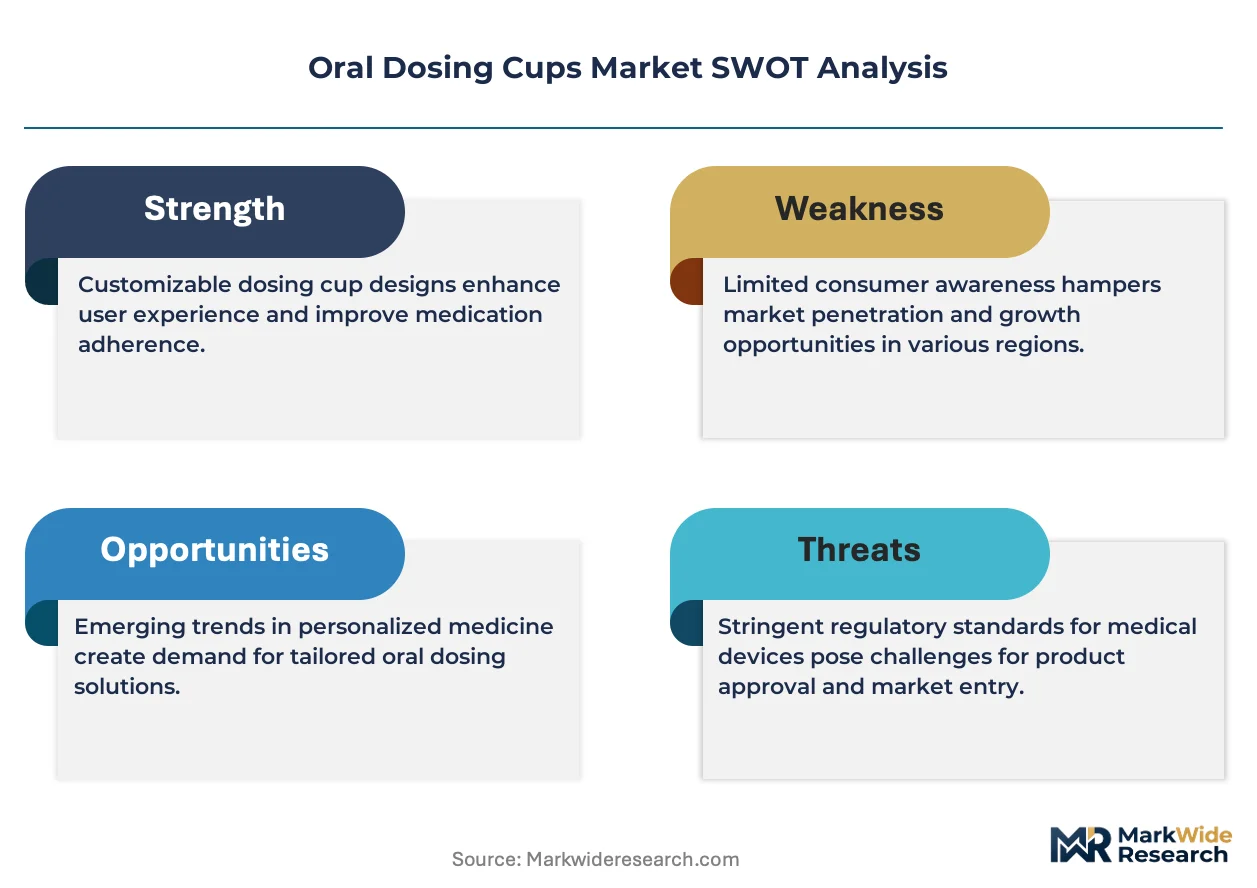
FDA enforces child-resistant packaging standards under 16 CFR 1700, while USP Chapter 1051 governs graduated-dose accuracy for oral dispensers, and the EU MDR tightens material biocompatibility documentation for devices contacting pharmaceuticals. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established testing protocols and regulatory dossiers. Stakeholders must monitor evolving state-level pharmaceutical waste regulations and pediatric dosing accuracy litigation trends to anticipate product liability and material specification shifts.
Market Dynamics
Group purchasing organizations are consolidating supplier rosters and favoring manufacturers with multi-site distribution capability, reconfiguring how oral dosing cups reach institutional end users.
Growth Catalysts
- FDA child-resistant packaging mandates:16 CFR 1700 standards expand addressable market for safety-engineered cup designs in US retail pharmacy channels.
- Homecare pediatric administration:Post-acute care expansion drives calibrated vessel demand for domestic medication management of liquid formulations.
- Polylactic acid material substitution:Biodegradable polymers gain formulation stability, enabling European pharmacy chains to preempt packaging waste directives.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings compress molding margins and destabilize contract pricing for high-volume hospital supply agreements.
- Single-source calibration equipment:Precision volumetric testing apparatus concentrates among German and Swiss metrology suppliers, creating bottleneck risk.
- Glass-to-plastic substitution ceiling:USP Chapter 1051 accuracy requirements prevent full displacement of borosilicate glass in high-precision liquid oncology dosing.
Strategic Opportunities
- Indian generic drug distribution scale-up:CDSCO streamlined pharmacy licensing expands addressable base for graduated dispensing vessels in outpatient settings.
- Smart packaging integration:Near-field communication tags and temperature indicators converge with molded cups for cold-chain biologic administration.
- Amazon Pharmacy direct-to-patient:E-commerce prescription fulfillment creates channel bypass opportunity outside traditional wholesale tiers.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical packaging quality management system audits extend 14-18 months, delaying new entrant market access.
- Legacy ERP integration:Hospital procurement systems require EDI compatibility and lot-level traceability modules that smaller molders lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Dosing Cups Market |
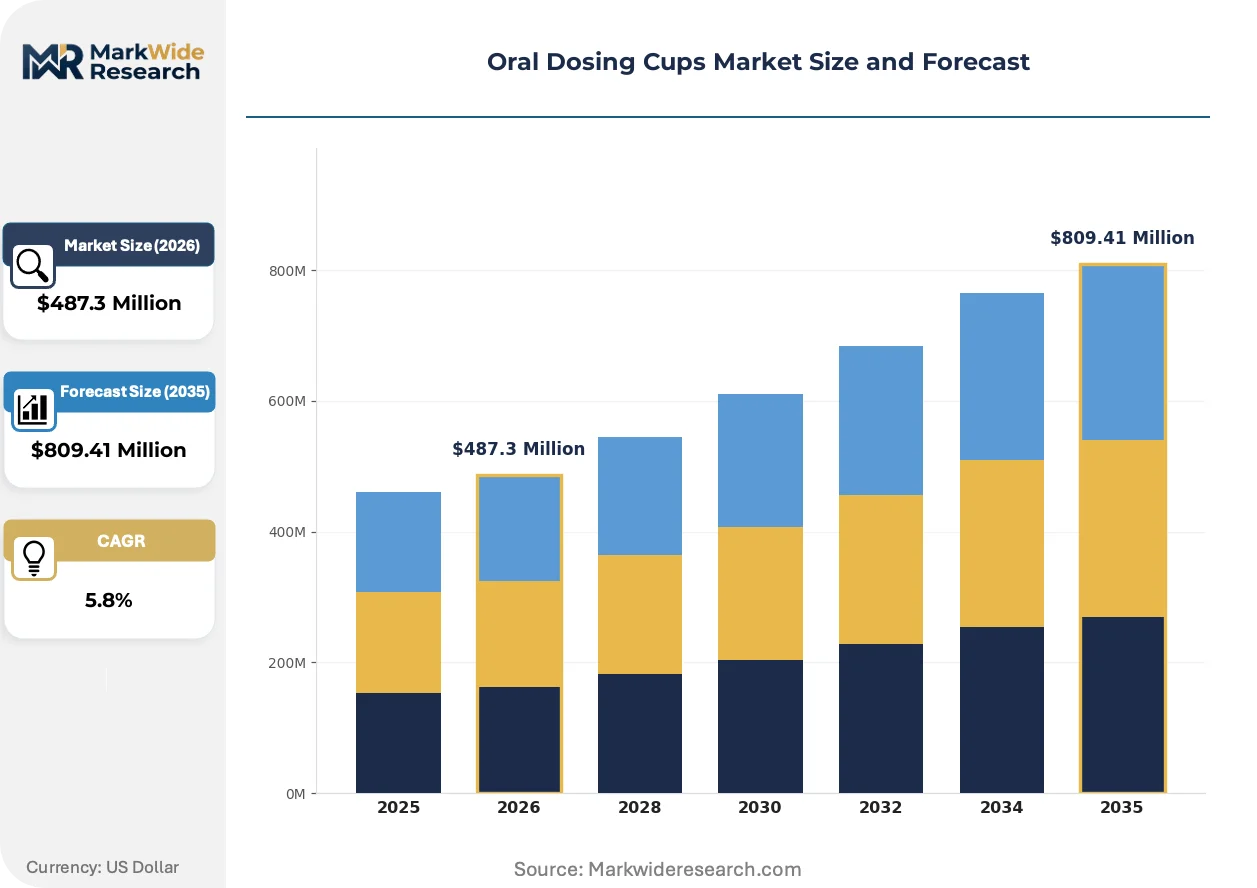
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Cups, Reusable Cups, Graduated Cups, Child-Resistant Cups Material: Plastic, Glass, Silicone, Biodegradable Material End User: Hospitals, Pharmacies, Homecare, Laboratories Capacity: 5ml, 10ml, 20ml, 50ml |
| Companies Covered | Comar, Qosina, Lyne Laboratories, O.Berk, Healthmark, Medline Industries, Origin Pharma Packaging, Gerresheimer AG, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Dosing Cups Market Evolving Landscape
Digital traceability and material science advances are compressing quality assurance cycles while expanding the functional perimeter of disposable medication vessels beyond simple measurement.
Embedded RFID and printed sensor technologies are virtualizing supply chain verification for oral dosing cups. Hospital systems in Germany now pilot lot-tracked vessels that authenticate medication origin at point of administration. This virtualization is compressing recall response windows from weeks to hours while raising mold-level capital requirements.
EU MDR biocompatibility documentation mandates are tightening material dossier requirements for polymer primary packaging. Manufacturers must now submit extractables and leachables data for all resin grades contacting liquid pharmaceuticals. Glass-transition testing protocols are extending product development cycles by 8-12 months for European market entry.
Direct contracting between health systems and molders is displacing traditional pharmaceutical wholesale distribution for high-volume SKUs. Integrated delivery networks in the United States now negotiate multi-year supply agreements that bundle calibrated cups with formulary commitment. This channel compression is most visible in pediatric hospital consignment models where inventory risk shifts entirely to manufacturers.
Oral Dosing Cups Market Segmentation
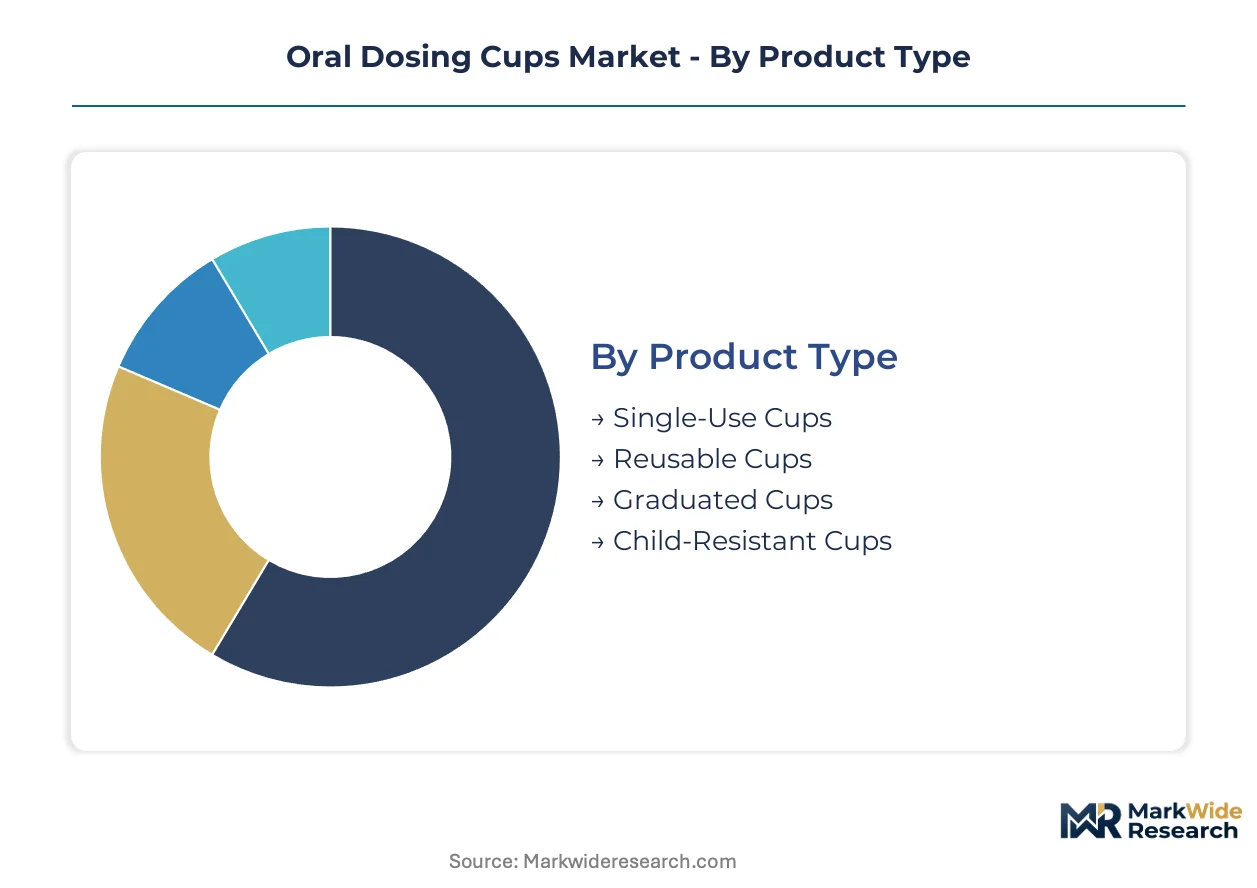
Segmentation in oral dosing cups reveals divergent velocity profiles across product lifecycles, material substitution curves, and procurement channel preferences. Manufacturers must align mold configurations and inventory turns to the specific rhythm of each segment cluster.
Product Type:
Cycle times compress from months for reusable hospital inventory to days for single-use infection-control protocols, with child-resistant engineering extending development horizons.
- Single-Use Cups:Polypropylene vessels molded to tight tolerances for immediate disposal after liquid medication administration. Hospital infection-control mandates in the United States and Germany sustain demand concentration, though resin price volatility squeezes contract margins.
- Child-Resistant Cups:Safety-engineered designs incorporating push-and-turn or squeeze-and-turn mechanisms compliant with FDA 16 CFR 1700. US retail pharmacy channels drive specification intensity as litigation risk elevates precision requirements for pediatric liquid formulations.
- Reusable Cups:Autoclavable polymer or glass vessels for institutional settings with sterilization infrastructure.
- Graduated Cups:Dual-scale markings in milliliters and household units for pharmacy dispensing accuracy.
Single-use variants dominate installed base volume. Child-resistant engineering is where expansion concentrates fastest.
Material:
Cost tiers stratify sharply between commodity resin supply and certified biocompatibility documentation for European market entry.
- Plastic:Polypropylene and polystyrene resins delivering ±5% volumetric accuracy through injection or blow molding. German and Indian hospital procurement channels anchor volume demand, though feedstock cost swings destabilize long-term supply agreements.
- Biodegradable Material:Polylactic acid formulations gaining formulation stability for liquid pharmaceutical contact. European pharmacy chains in Germany and France preempt packaging waste directives through pilot procurement programs.
- Glass:Borosilicate vessels retained for high-precision oncology dosing where USP Chapter 1051 accuracy thresholds exclude polymer substitution.
- Silicone:Flexible medical-grade formulations for specialized pediatric or geriatric administration.
Plastic commands current volume leadership. Biodegradable alternatives are climbing the fastest.
End User:
Customer type determines specification intensity, with hospitals demanding lot-level traceability and homecare prioritizing intuitive graduated markings.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year supply agreements bundling calibrated cups with formulary commitment. Group purchasing organization consolidation favors molders with multi-site distribution capability and EDI-compatible ERP systems.
- Homecare:Post-acute pediatric medication administration drives demand for intuitive graduated vessels with household unit markings. Expansion concentrates in United States and Indian outpatient settings as generic drug distribution scales.
- Pharmacies:Retail and institutional dispensing operations requiring USP-compliant accuracy for liquid formulations.
- Laboratories:Research and quality control applications with specialized volumetric precision requirements.
Hospitals represent the deepest specification tier. Homecare is gaining share fastest.
Capacity:
Volume concentration aligns with pediatric formulation prevalence versus adult oncology dosing requirements.
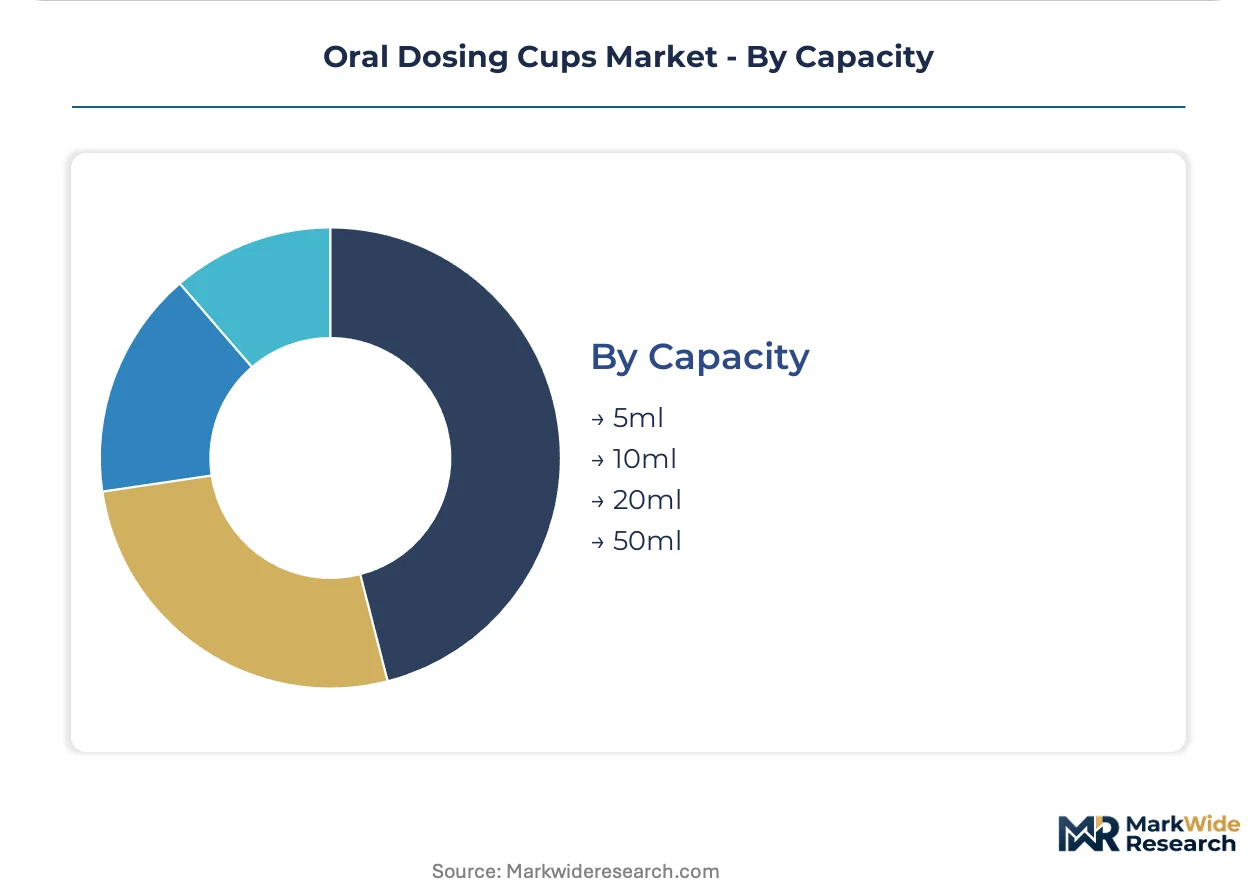
- 10ml:Standard pediatric liquid medication volumes with dual-scale milliliter and teaspoon markings. United States pharmacy dispensing and Indian generic drug distribution anchor demand concentration.
- 5ml:Neonatal and concentrated pediatric formulations requiring highest precision graduation.
- 20ml:Adult liquid medication and cough-cold formulations.
- 50ml:Large-volume suspensions and hospital enteral feeding applications.
10ml vessels dominate current dispensing protocols. 5ml precision formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution dominance for calibrated dosing vessels, while Indian generic drug export corridors through Mumbai and Chennai anchor Asia-Pacific volume expansion.
United States
Post-acute pediatric homecare expansion and Amazon Pharmacy direct-to-patient fulfillment drive calibrated vessel demand. FDA 16 CFR 1700 child-resistant packaging mandates tighten specification requirements for retail pharmacy channels. Integrated delivery networks in Texas and Florida negotiate multi-year supply agreements bundling graduated cups with formulary commitment.
Germany
Hospital infection-control protocols and EU MDR biocompatibility documentation requirements sustain precision-molded demand. ECHA REACH compliance for polymer extractables and leachables extends product development cycles. The Rhine-Ruhr industrial corridor hosts blow-molding specialists serving institutional procurement channels with lot-level traceability systems.
India
CDSCO streamlined pharmacy licensing and generic drug distribution scale-up expand outpatient dispensing vessel requirements. The country's national pharmaceutical regulator enforces graduated-dose accuracy standards aligned with USP Chapter 1051. Maharashtra's Mumbai-Pune pharmaceutical belt concentrates blow-molding capacity for domestic and export markets.
United Kingdom
NHS procurement consolidation favors suppliers with multi-site distribution capability and EDI-compatible ERP systems. The Medicines and Healthcare products Regulatory Agency enforces packaging material safety standards for liquid pharmaceutical contact. The Midlands manufacturing cluster hosts molders supplying hospital consignment models with inventory risk shifted to manufacturers.
Japan
PMDA quality management system requirements and aging-population medication adherence programs sustain demand for precision-graduated vessels. METI industrial standards govern polymer biocompatibility for primary pharmaceutical packaging. The Kansai Osaka-Kobe corridor anchors domestic molding capacity serving hospital and retail pharmacy networks.
Oral Dosing Cups Market Competitive Landscape
On the supply side, the industry is moderately consolidated around packaging specialists with pharmaceutical-grade certification and blow-molding technical capability. Tier-one players combine multi-site distribution networks with ISO 15378 quality management systems, while mid-cap molders compete on regional logistics proximity. Three strategic archetypes dominate: integrated packaging conglomerates with polymer science divisions, specialized pharmaceutical primary packaging firms, and diversified medical supply distributors with captive molding capacity. Competitive intensity centers on M&A-driven geographic expansion and strategic partnerships with group purchasing organizations.
Among integrated packaging specialists, Gerresheimer AG and Comar exemplify the polymer and glass primary packaging archetype serving institutional procurement channels. Medline Industries occupies a position within the diversified medical supply distribution tier, leveraging direct-to-facility logistics networks. ALPLA represents the global blow-molding scale category with pharmaceutical-grade manufacturing capabilities.
| Leading Market Players |
|---|
| Comar |
| Qosina |
| Lyne Laboratories |
| O.Berk |
| Healthmark |
| Medline Industries |
| Origin Pharma Packaging |
| Gerresheimer AG |
| ALPLA |
| Others |
Value Network & Pricing Analysis
German and Swiss metrology equipment suppliers concentrate precision volumetric testing apparatus, anchoring margin capture in the calibration tier while polypropylene resin arbitrage shapes contract pricing volatility downstream. Hospital group purchasing organizations exploit this upstream concentration to extract volume commitments from molders, compressing tier-two supplier margins while ISO 15378-certified incumbents defend premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified child-resistant cups from generic graduated vessels and commodity single-use variants. Certification grade and volume scale drive price differentiation, with FDA 16 CFR 1700 compliance commanding 15-25% premiums in US retail pharmacy channels. Cost compression in standard-tier polypropylene molding is intensifying because feedstock volatility destabilizes long-term hospital supply agreements. Homecare segments exhibit highest price sensitivity due to out-of-pocket procurement, while integrated delivery networks leverage formulary bundling to negotiate least-sensitive contract terms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for injection-molded dosing vessels, though German and Indian blow-molding capacity provides partial geographic diversification. Raw material dependencies center on polypropylene resin, polystyrene formulations, and precision calibration equipment sourced from Swiss metrology specialists. Single-source vulnerability concentrates in volumetric testing apparatus, creating bottleneck risk for new entrant certification timelines. Distribution runs through group purchasing organization consolidated rosters, with direct-to-facility logistics networks displacing traditional pharmaceutical wholesale tiers for high-volume SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart packaging integration with near-field communication tags and temperature indicators is disrupting traditional molded vessel commoditization, creating value-capture opportunities beyond volumetric accuracy alone. FDA child-resistant packaging mandates and EU MDR biocompatibility documentation requirements are accelerating technical differentiation timelines.
For Market Incumbents: Entrench multi-site distribution capability to defend against Amazon Pharmacy direct-to-patient channel bypass threats, while deepening backward integration into blow-molding capacity across the Rhine-Ruhr and Mumbai-Pune corridors. ISO 15378 certification investment represents the critical lever for maintaining GPO roster positions as procurement consolidation intensifies. For New Entrants and Emerging Players: Biodegradable polylactic acid formulations for European pharmacy chains represent the most penetrable entry point, given packaging waste directive preemption demand and incumbent capacity gaps in certified compostable polymers. CDSCO streamlined licensing in Indian outpatient settings offers secondary white-space access. Target hospital consignment models with inventory risk transfer as the go-to-market angle to bypass entrenched supplier relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap molders with captive ISO 15378 quality systems and established EDI-compatible ERP infrastructure, as these assets command scarcity premiums in procurement consolidation environments. Long-term viability hinges on smart packaging integration capability and biopolymer formulation stability. The signal to watch is pediatric dosing accuracy litigation trends, which could accelerate regulatory specification intensity and reshape material substitution curves.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Packaging Integration | Embedded RFID tags enable lot-level traceability for hospital infection-control protocols. |
| Biopolymer Capacity Expansion | Polylactic acid formulation stability unlocks European pharmacy chain procurement channels. |
| Backward Integration into Blow-Molding | In-house production of calibrated vessels defends margins against resin price volatility. |
| Hospital System Partnership | Direct contracting with integrated delivery networks bypasses traditional wholesale tiers. |
| Regulatory Certification Investment | ISO 15378 quality management system audits secure GPO roster positions. |
Research Methodology
Desk research of FDA 510(k) filings, USP Chapter 1051 documentation, and EU MDR guidance documents preceded structured interviews with blow-molding operations directors, hospital GPO contracts managers, and pharmacy procurement leads. Primary fieldwork with pharmaceutical packaging quality assurance officers and resin formulation specialists combined with secondary validation against customs trade data and hospital supply chain databases. Bottom-up capacity modeling and top-down demand estimation were triangulated to derive market sizing.
Assumptions regarding FDA child-resistant packaging mandate enforcement timelines and EU packaging waste directive implementation schedules were held fixed across baseline scenarios, while polypropylene resin price trajectories and smart packaging adoption curves were stress-tested under sensitivity variants. Segmentation dimensions modeled included product type, material grade, end-user procurement channel, and geographic regulatory cluster. CAGRs were computed from normalized baseline values through iterative convergence of demand-side and supply-side indicators, with pediatric homecare expansion rates and generic drug distribution scale serving as key forecast inputs.
Practitioners should monitor CDSCO enforcement patterns and state-level pharmaceutical waste litigation for early signals of specification intensity shifts. Forecasts reflect documented assumptions regarding regulatory timeline adherence and material substitution technical feasibility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Catgut Sutures Market