
 Sperm Density Testing Market | 2026-2036
Sperm Density Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Sperm Density Testing Market Analytics
Trained andrologists and laboratory technicians is redrawing competitive boundaries in sperm density testing. Hamilton Thorne leverages proprietary image analysis algorithms to sustain technology leadership in automated semen assessment. Medical Electronic Systems anchors its position through manufacturing scale across North American fertility clinic networks. ExSeed Health differentiates by occupying the direct-to-consumer home testing channel with smartphone-integrated hardware.
Sperm density testing measures spermatozoa concentration per milliliter of ejaculate, typically employing hemocytometer counting chambers, computer-assisted sperm analysis (CASA) systems, or disposable counting slides with optical magnification. The procedure serves diagnostic screening for male factor infertility, post-vasectomy confirmation, and cryopreservation quality control. Automated Systems within the technology dimension command premium pricing due to reproducibility advantages over manual techniques, while Point of Care delivery mode is expanding fastest as clinics seek same-day diagnostic workflows. Laboratory Equipment among product types retains the largest installed base, though Diagnostic Devices capture growing share through portable form factors.
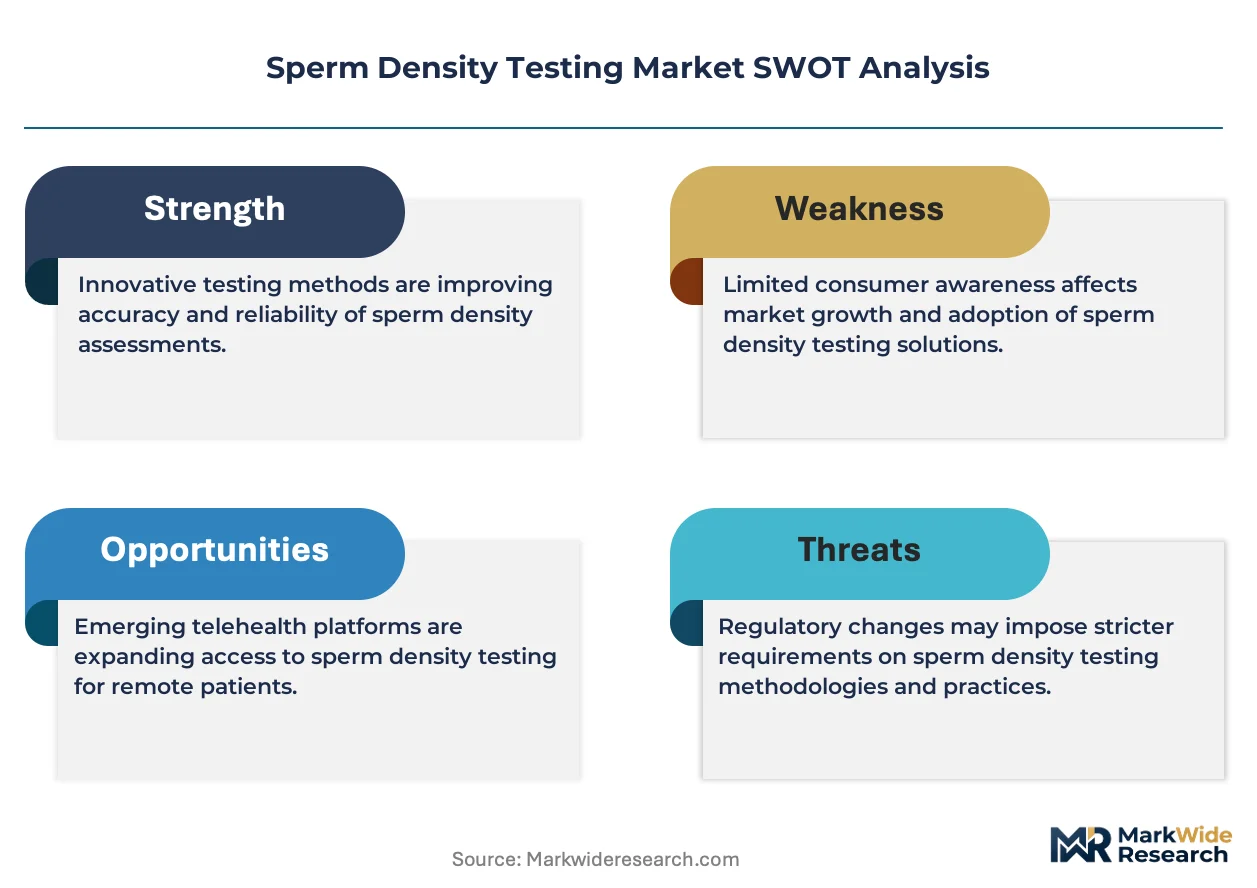
FDA Class II device regulations mandate 510(k) premarket notification for new sperm analyzers, elevating barriers for entrants without established quality management systems. The EU Medical Device Regulation (MDR) requires notified body involvement for in vitro diagnostic semen analysis products, extending conformity assessment timelines. ISO 13485 certification has become table stakes for supply contracts with hospital purchasing groups. Stakeholders must monitor evolving reimbursement codes for male infertility diagnostics as payers recalibrate coverage policies for at-home versus clinic-based testing pathways.
Market Dynamics
Automated computer-assisted sperm analysis (CASA) systems are compressing testing turnaround times from hours to minutes, forcing fertility clinics to retire manual hemocytometer workflows or lose patient throughput to rivals with same-day diagnostic capabilities.
Growth Catalysts
- Delayed Parenthood Demographics:Men in the United States, Germany, and Japan are fathering children at progressively later ages, expanding the addressable patient pool for male factor infertility screening.
- EU Medical Device Regulation (MDR):Stricter conformity assessment timelines for in vitro diagnostic semen analysis products are filtering out marginal competitors and consolidating procurement toward ISO 13485-certified suppliers.
- Smartphone-Integrated Hardware:Direct-to-consumer channels are capturing patients who bypass traditional clinic referrals, extending testing access to rural and underserved populations.
Market Restraints
- Optical Component Supply Concentration:Precision microscope objectives and CMOS sensors concentrate among Japanese and German optical manufacturers, exposing analyzer producers to lead time volatility.
- FDA 510(k) Pathway Friction:Premarket notification requirements for Class II semen analysis devices extend product development cycles by 12-18 months for entrants without established quality management systems.
- Manual Technique Persistence:Cost-sensitive public health laboratories in emerging markets continue relying on disposable counting slides, limiting automated system penetration.
Strategic Opportunities
- Home Testing Channel Expansion:Brazil and Mexico present underpenetrated direct-to-consumer markets where smartphone-connected devices can bypass constrained fertility clinic infrastructure.
- Cryopreservation Quality Control:Sperm banking networks require standardized density verification for frozen sample viability, creating recurring revenue streams beyond initial diagnostic testing.
- Artificial Intelligence Convergence:Machine learning classification of sperm morphology is reducing inter-technician variability, enabling laboratories to redeploy skilled andrologists to complex case consultation.
Industry Challenges
- Andrologist Training Pipeline:Accredited clinical laboratory science programs produce insufficient specialists in semen analysis, constraining fertility center expansion plans.
- Legacy LIS Integration Complexity:Automated analyzers must interface with disparate laboratory information systems through HL7 or proprietary protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sperm Density Testing Market |
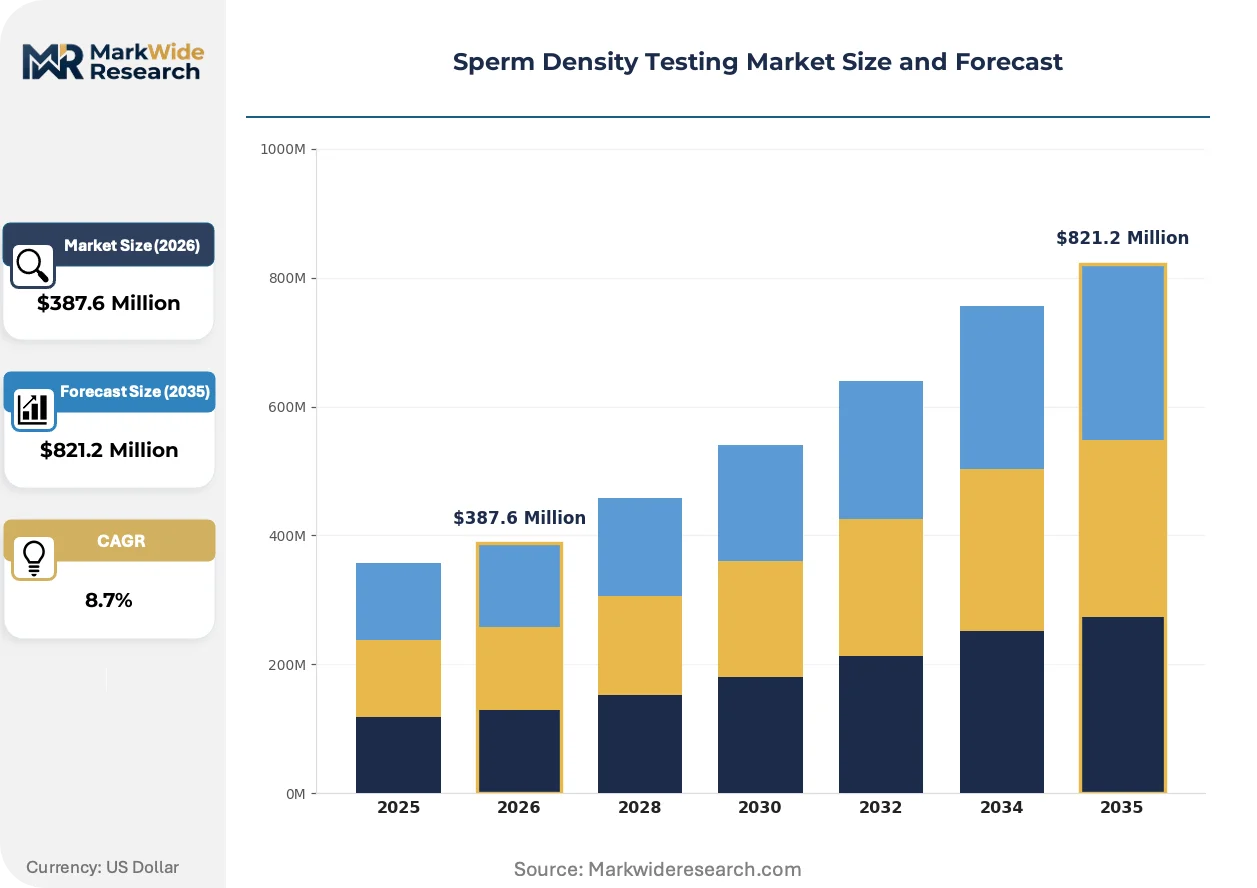
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semen Analysis Kits, Sperm Count Counters, Laboratory Equipment, Diagnostic Devices End User: Clinics, Hospitals, Fertility Centers, Research Laboratories Technology: Manual Techniques, Automated Systems, Optical Methods, Computerized Analysis Delivery Mode: Point of Care, Laboratory Services, Home Testing, Online Services |
| Companies Covered | Hamilton Thorne, Medical Electronic Systems, ExSeed Health, Vitrolife AB, Fertility Focus Inc, Andrology Solutions, Microptic, Sandstone Diagnostics, DxNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sperm Density Testing Market Evolving Landscape
Deep learning image recognition and miniaturized optical sensors are converging to collapse the cost and skill barriers that historically separated clinical-grade sperm analysis from consumer-accessible alternatives.
Deep convolutional neural networks trained on annotated sperm motility datasets are supplanting rule-based computer vision algorithms in high-volume fertility laboratories. Large clinic networks in California and Texas are deploying these systems to standardize morphology assessments across multiple sites. The technology is compressing the competitive advantage of centralized reference laboratories by enabling equivalent diagnostic accuracy at point-of-care locations.
EU MDR Article 10 technical documentation requirements for in vitro diagnostic devices are extending conformity assessment timelines for semen analysis products by 9-14 months. Notified body capacity constraints are creating bottlenecks that favor incumbent manufacturers with established regulatory affairs infrastructure. European fertility clinics are responding by consolidating procurement toward suppliers with multiple MDR-certified product lines.
Subscription-based reagent and calibration service contracts are displacing capital-intensive analyzer purchases in mid-sized fertility practices. North American clinic networks are adopting per-test pricing models that bundle hardware, consumables, and cloud-based quality assurance. This shift is most visible among multi-site reproductive medicine groups seeking to standardize operational costs across state-level expansions.
Sperm Density Testing Market Segmentation
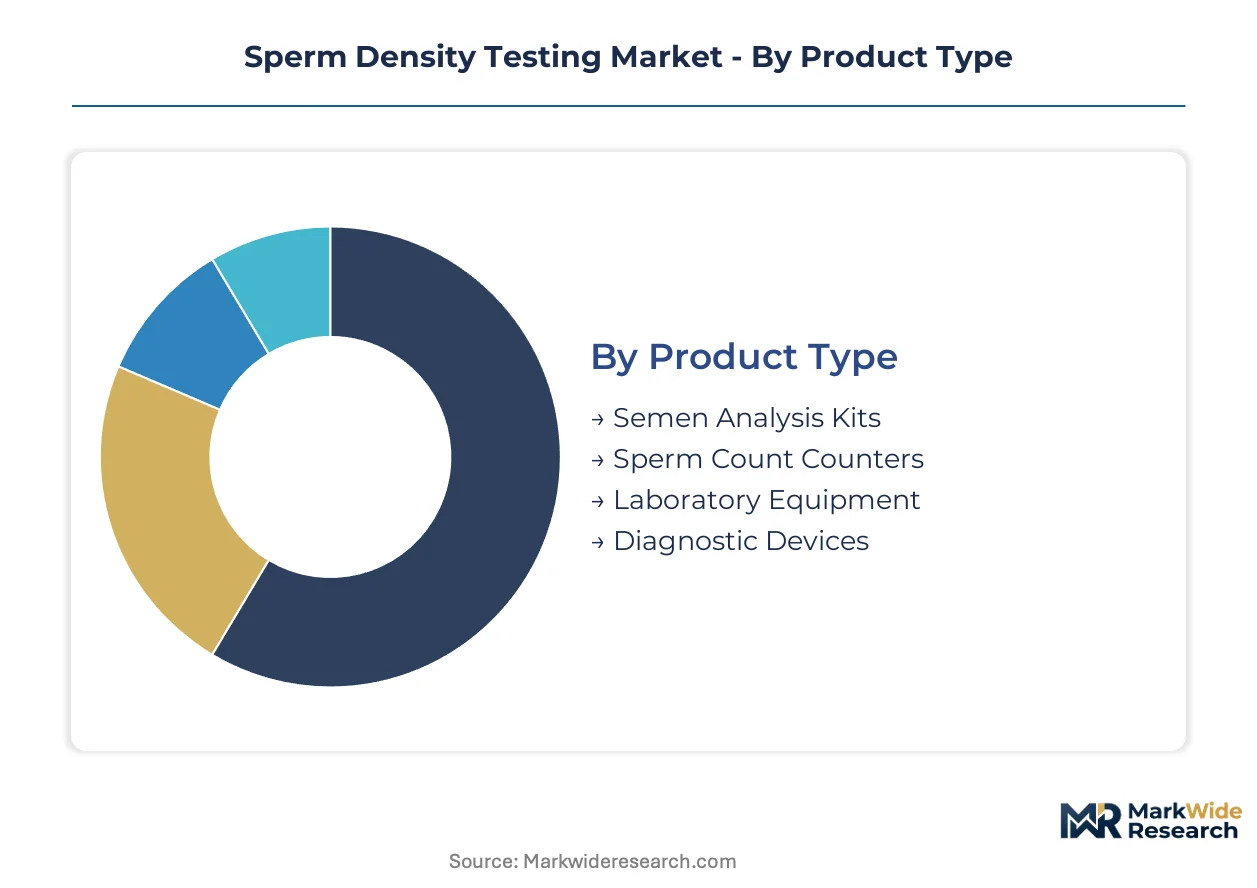
Sperm density testing spans distinct product architectures, user environments, and technical methodologies that shape procurement patterns across fertility care networks. Channel dynamics vary sharply between institutional laboratory sales and direct-to-consumer pathways, requiring suppliers to maintain parallel go-to-market capabilities.
Product Type:
Channel distribution splits between capital equipment sold through distributor networks and consumable kits moving through clinical supply chains.
- Semen Analysis Kits:Disposable reagent sets and prepared counting chambers enable standardized sample processing across multiple testing sites. Fertility center networks in the United States and Germany favor kit-based workflows to reduce inter-site variability. Demand concentrates where clinic chains pursue operational uniformity across state or national boundaries.
- Sperm Count Counters:Dedicated enumeration instruments combine optical magnification with digital readout for rapid concentration assessment. Mid-sized fertility practices in Japan deploy these units to balance throughput needs against capital constraints. Procurement favors devices with minimal calibration requirements.
- Laboratory Equipment:Integrated analyzer platforms serve high-volume reference laboratories with multi-parameter semen assessment capabilities.
- Diagnostic Devices:Portable form factors support point-of-care deployment and home testing channels with smartphone connectivity.
Laboratory Equipment dominates installed base. Diagnostic Devices is where expansion concentrates.
End User:
Customer type determines pricing tolerance, with hospital systems negotiating enterprise contracts while research laboratories prioritize technical specifications.
- Fertility Centers:Specialized reproductive medicine clinics generate concentrated testing volumes and demand rapid turnaround capabilities. California and Texas clinic networks are deploying automated systems to standardize morphology assessments across multi-site operations. These facilities represent the primary demand pool for premium analyzer platforms.
- Clinics:General urology and men's health practices perform initial screening before referral to specialized centers. Urban clinic clusters in Germany integrate sperm density testing into broader male health screening protocols. Volume per site remains modest but network density creates aggregate opportunity.
- Hospitals:Academic medical centers and community hospitals maintain andrology laboratories for inpatient and outpatient services.
- Research Laboratories:Academic and pharmaceutical research facilities employ semen analysis for toxicology and fertility studies.
Fertility Centers command premium pricing. Clinics are expanding most quickly as primary care integration deepens.
Technology:
Technical approach dictates regulatory pathway and skill requirements, with automated platforms requiring FDA 510(k) clearance while manual methods face lighter oversight.
- Automated Systems:Computer-assisted sperm analysis platforms employ image processing algorithms for objective motility and morphology classification. Large laboratory networks are adopting these systems to reduce technician-to-technician variability. The technology enables equivalent diagnostic accuracy at distributed point-of-care locations.
- Manual Techniques:Hemocytometer counting and wet mount microscopy remain prevalent in cost-constrained settings and training environments. Public health laboratories in emerging markets continue relying on disposable counting slides. Limited capital requirements sustain penetration where reimbursement rates suppress equipment investment.
- Optical Methods:Phase-contrast and dark-field microscopy configurations support specialized morphological assessment.
- Computerized Analysis:Software-based image interpretation augments conventional microscopy with quantitative metrics.
Manual Techniques retain volume leadership in emerging markets. Automated Systems is climbing the fastest as laboratory consolidation proceeds.
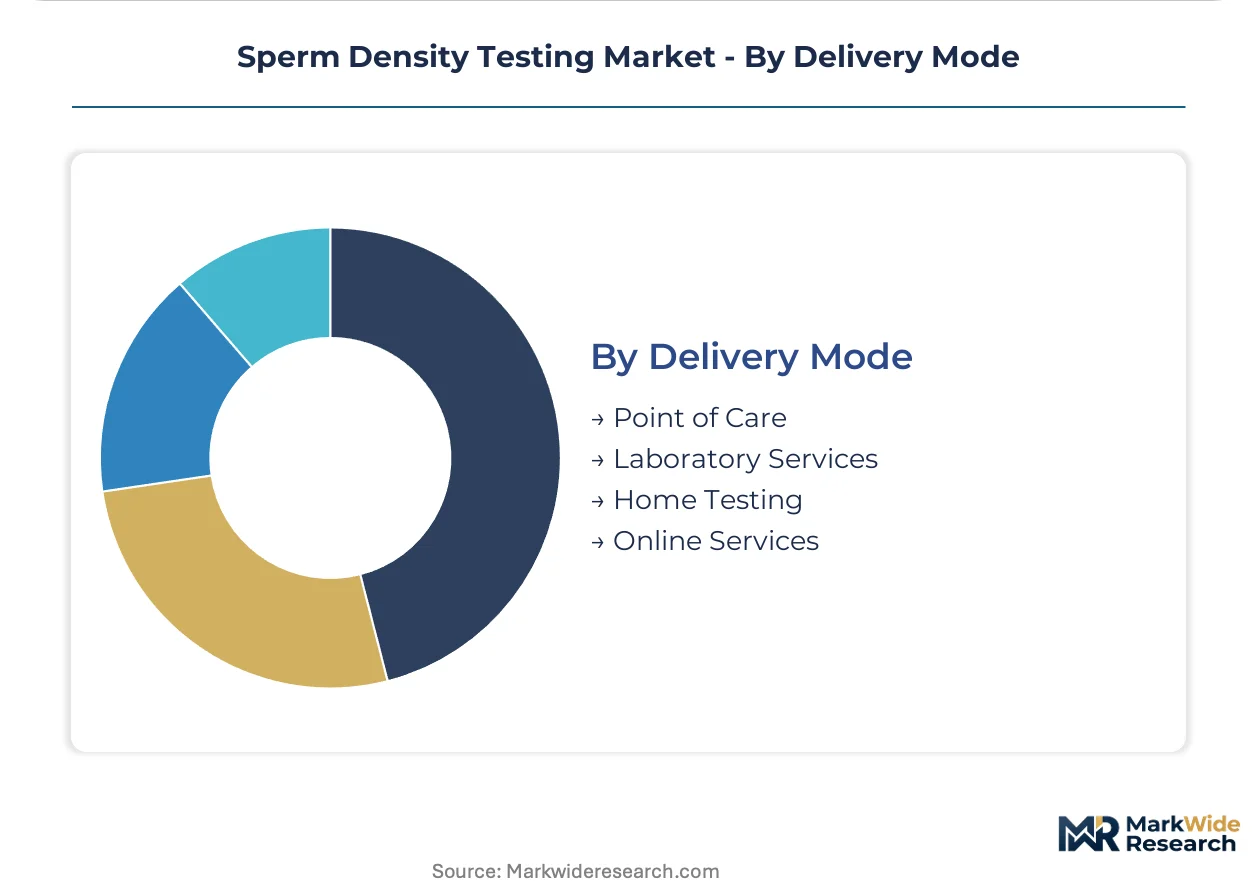
Delivery Mode:
Service configuration shapes margin structure, with laboratory services capturing recurring revenue while home testing requires hardware subsidy models.
- Laboratory Services:Centralized reference laboratories process samples shipped from collection sites with standardized reporting protocols. Fertility clinic networks in the United States outsource complex morphology assessments to specialized reference facilities. This model concentrates technical expertise while extending geographic reach.
- Home Testing:Direct-to-consumer channels ship collection devices and enable smartphone-based result interpretation. Brazil and Mexico present underpenetrated markets where smartphone-connected devices bypass constrained clinic infrastructure. Regulatory frameworks for home diagnostic devices vary sharply by national jurisdiction.
- Point of Care:Same-day diagnostic workflows within clinical settings support immediate consultation and treatment planning.
- Online Services:Telehealth-integrated platforms combine remote consultation with mail-in sample processing.
Laboratory Services maintains revenue concentration. Home Testing is gaining share fastest as consumer channel investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class II device regulations in the United States establish the baseline compliance framework that shapes product development timelines across developed markets. National regulators in Germany and Japan impose parallel conformity burdens that filter market entry toward established quality management systems.
United States
Delayed parenthood demographics in California and Texas are expanding fertility clinic networks and driving adoption of automated analysis systems. The FDA's 510(k) premarket notification pathway for semen analysis devices extends development cycles by 12-18 months for new entrants. Large clinic networks in the Pacific Northwest are deploying standardized morphology assessment platforms across multi-site operations.
Germany
Urban clinic clusters in Bavaria and North Rhine-Westphalia are integrating sperm density testing into broader male health screening protocols. The EU Medical Device Regulation requires notified body involvement for in vitro diagnostic semen analysis products, extending conformity assessment timelines. Academic medical centers in Baden-Württemberg maintain reference laboratories serving cross-border fertility networks.
Japan
Aging populations in Tokyo and Osaka are elevating clinical testing volumes for male factor infertility screening. METI standards for medical device quality systems intersect with PMDA marketing authorization requirements for automated analyzers. Precision optical component manufacturers in Nagoya supply microscope objectives to domestic analyzer producers.
Brazil
Underpenetrated direct-to-consumer channels in São Paulo and Rio de Janeiro present expansion opportunities for smartphone-connected testing devices. ANVISA medical device registration requirements create compliance barriers that favor suppliers with established Latin American regulatory affairs infrastructure. Fertility clinic infrastructure constraints in Minas Gerais are accelerating demand for home-based collection alternatives.
United Kingdom
NHS procurement frameworks in London and the Southeast are consolidating fertility service contracts toward ISO 13485-certified diagnostic suppliers. MHRA post-market surveillance requirements for in vitro diagnostic devices elevate ongoing compliance obligations. Research laboratories in Cambridge and Oxford employ semen analysis platforms for toxicology and pharmaceutical fertility studies.
Sperm Density Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics rather than direct confrontation. The vendor base clusters around three strategic positions: automated platform specialists commanding premium pricing through proprietary algorithms, manufacturing-scale suppliers anchoring North American clinic networks, and direct-to-consumer entrants collapsing distribution layers through smartphone integration. Dominant competitive moves include geographic expansion into underpenetrated Latin American markets and portfolio diversification toward cryopreservation quality control services.
Within the technology-specialist tier, Hamilton Thorne occupies a position exemplifying proprietary image analysis capabilities, while Medical Electronic Systems anchors the manufacturing-scale archetype through distributor network presence. ExSeed Health represents the direct-to-consumer channel disruption, collapsing traditional clinic referral pathways through smartphone-integrated hardware deployment.
| Leading Market Players |
|---|
| Hamilton Thorne |
| Medical Electronic Systems |
| ExSeed Health |
| Vitrolife AB |
| Fertility Focus Inc |
| Andrology Solutions |
| Microptic |
| Sandstone Diagnostics |
| DxNow |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification gates supplier qualification for hospital purchasing groups while simultaneously enabling tiered price premiums between certified and non-certified equipment tiers. Fertility centers in Germany and Japan negotiate enterprise contracts that bundle hardware, consumables, and cloud-based quality assurance, compressing margins for standalone analyzer vendors.
Pricing Analysis
Price spreads of 40-60% separate automated CASA platforms in California from manual counting systems in Brazilian public health laboratories. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, optical resolution specifications, and after-sales calibration bundling. Cost compression in the mid-tier intensifies as subscription-based per-test models displace capital purchases. Public health laboratories in emerging markets exhibit highest price sensitivity; multi-site fertility networks in Texas and Germany demonstrate lowest sensitivity due to operational standardization requirements.
Supply Chain Analysis
Precision microscope objective manufacturing concentrates in Nagoya and Jena, creating single-source vulnerability for analyzer producers dependent on phase-contrast optics. CMOS sensor fabrication draws from Taiwanese and South Korean foundries, while disposable counting slide polymer supply rests on German and Japanese chemical processors. Tariff exposure runs through optical component imports into North American assembly facilities. Distribution runs through specialized fertility clinic distributor networks in the United States and direct hospital procurement frameworks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-integrated sperm analysis hardware represents a high-growth disruption, with FDA's evolving classification of direct-to-consumer diagnostic devices creating regulatory inflection points that will reshape competitive boundaries.
For Market Incumbents: Shield proprietary algorithm portfolios through accelerated patent filing in morphology classification and motility tracking. Deepen backward integration into precision optical component supply to mitigate Japanese and German supplier concentration risk. Consolidate procurement relationships with multi-site fertility networks in California and Texas before subscription-based per-test models fully displace capital sales. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest clearance routes for smartphone-connected devices with predicate device alignment. Target underpenetrated direct-to-consumer channels in São Paulo and Rio de Janeiro where clinic infrastructure constraints accelerate home testing adoption. Pursue telehealth-integrated distribution partnerships that bypass traditional fertility center referral gatekeepers. For Investors and Strategic Acquirers: EU MDR Article 10 technical documentation requirements reshape the acquisition landscape toward incumbent manufacturers with established notified body relationships and multiple MDR-certified product lines. Long-term viability centers on software-enabled recurring revenue models rather than capital equipment cycles. Monitor ANVISA registration progress in Brazil as signal for Latin American direct-to-consumer market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines compress competitive entry barriers for algorithm-enabled devices. |
| EU MDR Certification Expansion | Notified body capacity constraints favor early movers with established technical documentation infrastructure. |
| Subscription Revenue Model Migration | Per-test pricing bundles hardware, consumables, and cloud quality assurance across North American clinic networks. |
| Direct-to-Consumer Channel Development | Smartphone-integrated hardware bypasses constrained fertility clinic infrastructure in Brazilian and Mexican markets. |
| Cryopreservation Quality Control Services | Standardized density verification for sperm banking networks creates recurring revenue beyond initial diagnostic testing. |
Research Methodology
Initial hypotheses were tested against primary input from andrology laboratory directors, fertility clinic procurement managers, biomedical engineers, and regulatory affairs specialists at IVD manufacturers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital GPO contract records, and ISO 13485 certification registries. Bottom-up demand modeling across product type, end user, technology, and delivery mode segments was triangulated with top-down market sizing.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within automated systems, manual techniques, laboratory equipment, and diagnostic device categories. CAGRs were derived from installed base evolution, replacement cycle analysis, and penetration rate trajectories. Forecast inputs incorporated delayed parenthood demographic shifts, reimbursement code evolution for male infertility diagnostics, and optical component supply lead time volatility.
Underlying assumptions cover regulatory clearance timelines, reimbursement stability, and optical component supply continuity, with deviation risk concentrated in EU MDR notified body capacity constraints and FDA classification shifts for direct-to-consumer devices. Practitioners should keep alternative scenarios live as home testing regulatory frameworks and payer coverage policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market