
 Asia-Pacific Molecular Diagnostics Market | 2026-2036
Asia-Pacific Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Molecular Diagnostics Market Insights
Japan's PMDA revised quality management system requirements for in vitro diagnostics is repositioning compliance costs upward for multinational assay suppliers. F. Hoffmann-La Roche Ltd leverages its centralized manufacturing footprint in Singapore to sustain margin stability across ASEAN tender markets. Danaher anchors its regional position through Beckman Coulter's localized instrument service networks in Australia and South Korea. Qiagen NV competes on sample preparation automation, a segment where technical support proximity matters more than kit pricing alone.
Molecular diagnostics encompasses nucleic acid amplification, hybridization, and sequencing techniques that detect genetic material from pathogens or patient samples with analytical sensitivity reaching single-copy detection thresholds. The primary commercial purpose centers on infectious disease identification, oncogenic mutation profiling, and inherited disorder screening where speed and specificity determine clinical utility. Reagents and assays command the dominant share of product-level revenue because consumable pull-through ties directly to installed instrument bases. Oncology applications attract premium pricing due to companion diagnostic requirements for targeted therapeutics, while infectious disease panels generate volume through standardized hospital protocols. PCR technology retains the largest installed base, though next-generation sequencing is displacing single-gene testing in tertiary oncology centers across Australia and Japan.
China's NMPA implements stricter clinical validation standards for imported molecular diagnostic kits, extending registration timelines and favoring domestic manufacturers with established trial networks. Australia's TGA aligns with EU MDR convergence pathways, creating dual-compliance efficiencies for European suppliers already holding CE-IVD certifications. India's CDSCO mandates local adverse event reporting for all licensed IVDs, a requirement that shapes distributor selection and post-market surveillance investment. Stakeholders must monitor how Japan's revised reimbursement categories for precision oncology tests redirect hospital capital toward integrated NGS platforms versus modular PCR upgrades.
Market Dynamics
Centralized municipal procurement frameworks across China's tier-one cities are consolidating hospital laboratory purchasing power, compressing assay kit margins while favoring suppliers with localized manufacturing footprints and integrated service networks.
Growth Catalysts
- Companion diagnostic mandates:Oncology targeted therapy protocols in Japan and South Korea now require mutation profiling before reimbursement approval, creating procedural pull-through for NGS panels.
- Infectious disease surveillance expansion:Southeast Asian hospital laboratories are accelerating PCR panel deployment for respiratory and bloodstream pathogen detection under national AMR containment programs.
- CDSCO quality benchmark elevation:India's tightened IVD import regulations are filtering substandard assay kits, improving clinical confidence and replacement rates for validated alternatives.
Market Restraints
- Reagent supply concentration:Critical enzymes and fluorescent probes for PCR workflows originate from a narrow base of specialized chemical suppliers, exposing assay manufacturers to input volatility.
- NMPA registration timeline extension:China's stricter clinical validation requirements for imported molecular diagnostic kits are stretching approval cycles and freezing market entry for non-domestic players.
- Technical substitution pressure:CRISPR-based diagnostic platforms are emerging as lower-cost alternatives to quantitative PCR for point-of-care infectious disease screening in resource-limited settings.
Strategic Opportunities
- Tier-two and tier-three China penetration:Municipal health bureau consolidation is extending beyond Beijing, Shanghai, and Guangzhou into provincial capitals where diagnostic infrastructure remains underdeveloped.
- Sample preparation automation:Pre-analytical workflow bottlenecks in high-throughput laboratories are creating demand for robotic nucleic acid extraction systems integrated with downstream analytical platforms.
- Australia TGA-EU MDR convergence:Dual-compliance pathway efficiencies are reducing regulatory duplication costs for European IVD suppliers already holding CE-IVD certifications.
Industry Challenges
- Bioinformatics pipeline integration:NGS platform adoption in tertiary oncology centers is outpacing hospital IT capacity to deploy variant interpretation workflows and clinical decision support interfaces.
- Field service engineer scarcity:Complex instrument maintenance requirements for automated sample preparation systems are outpacing trained technician supply in Australia's decentralized healthcare geography.
- Adverse event reporting infrastructure:India's CDSCO mandate for local post-market surveillance is forcing distributor restructuring and investment in pharmacovigilance capabilities that many regional partners lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Molecular Diagnostics Market |
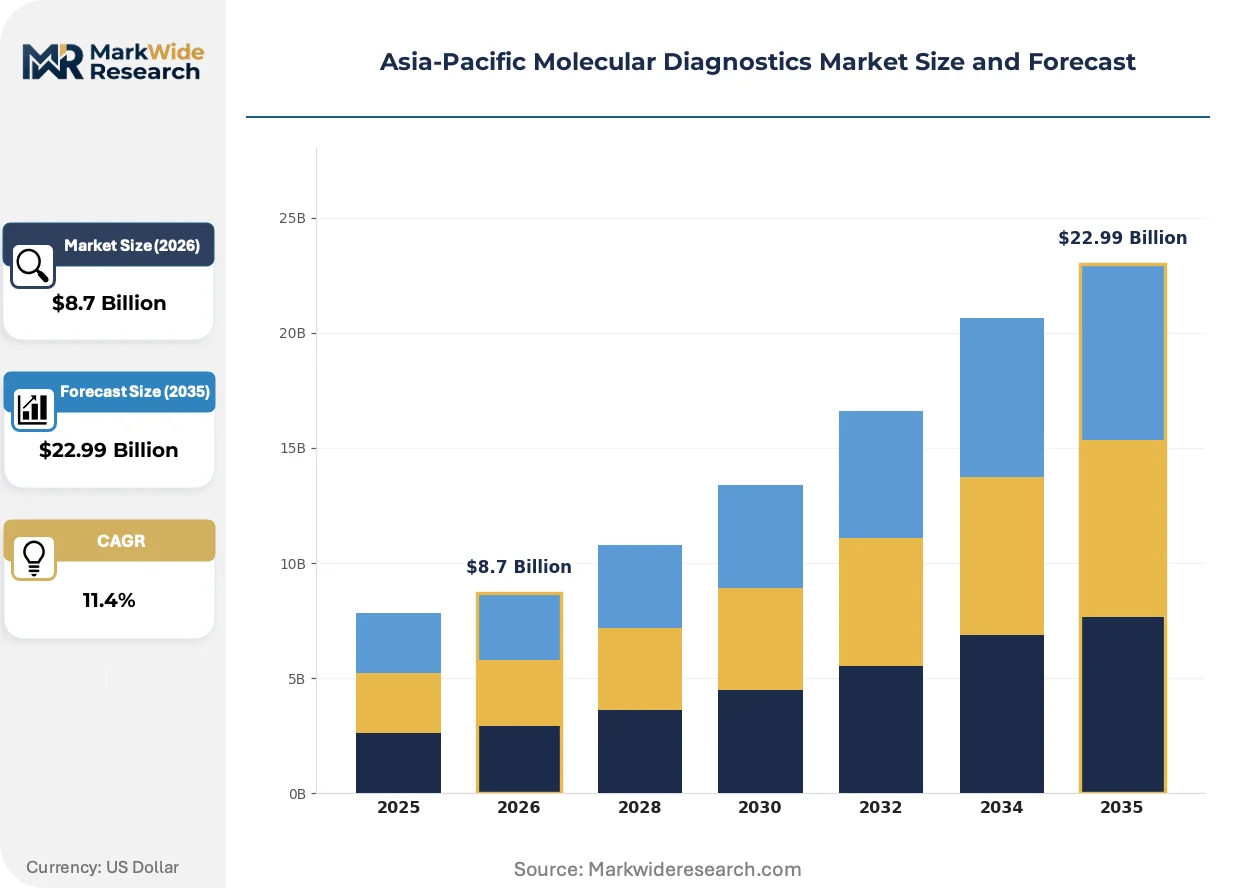
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Assays Application: Oncology, Infectious Diseases, Genetic Testing, Autoimmune Disorders End User: Hospitals, Laboratories, Research Institutes, Clinics Technology: PCR, Next-Generation Sequencing, Microarray, Sanger Sequencing |
| Companies Covered | F. Hoffmann-La Roche Ltd, bioMerieux SA, Abbott Laboratories, Danaher, Illumina Inc, Agilent Technologies Inc, Qiagen NV, Siemens Healthineers AG, Thermo Fisher Scientific Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Molecular Diagnostics Market Trends and Innovations
Workflow integration and pre-analytical automation are compressing turnaround times while regulatory convergence and procurement centralization are rewriting competitive access rules across the Asia-Pacific molecular diagnostics landscape.
Automated nucleic acid extraction platforms are modularizing laboratory workflows by decoupling sample preparation from analytical detection. Mid-sized hospital laboratories in South Korea and Australia are adopting these systems to offset technician shortages. This modularization is enabling plug-and-play compatibility between extraction robotics and multiple downstream PCR or NGS instruments, reducing vendor lock-in and accelerating platform switching cycles.
PMDA's revised quality management system requirements for in vitro diagnostics are elevating documentation and audit standards for multinational assay suppliers serving Japan. The industrial consequence is a compliance cost burden that favors larger manufacturers with dedicated regulatory affairs infrastructure. Premium oncology companion diagnostic segments are absorbing these costs through pricing power, while infectious disease panel suppliers face margin compression.
Consolidated tender frameworks are replacing hospital-level purchasing autonomy across China's provincial health systems. Municipal health bureaus in Jiangsu and Zhejiang are aggregating demand into multi-year supply agreements that bundle reagent consumption commitments with instrument placement. This concentration is visible most acutely in infectious disease screening programs where standardized protocols enable volume-based procurement leverage.
Asia-Pacific Molecular Diagnostics Market Segmentation
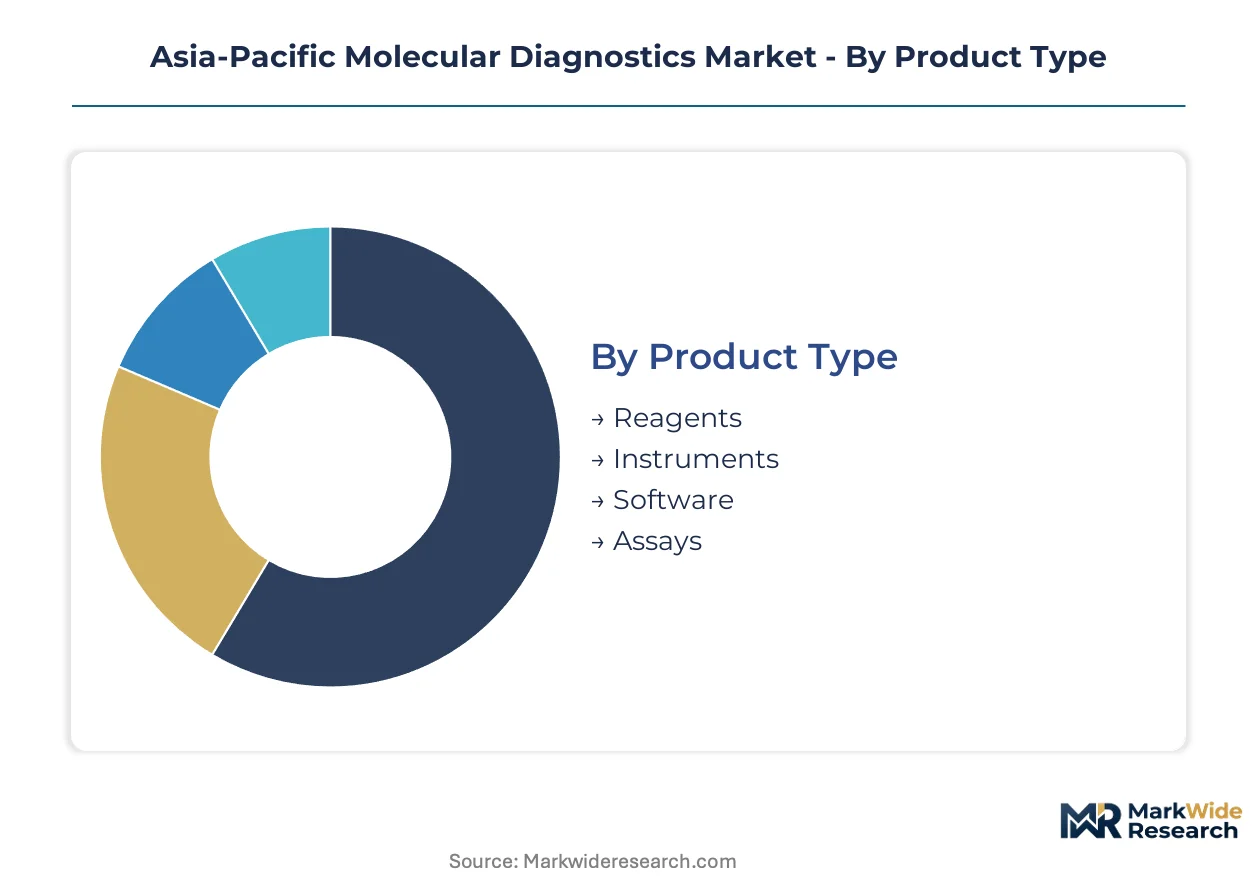
Segmentation in molecular diagnostics reveals how purchasing decisions fragment across technical specifications, clinical workflows, and regulatory compliance requirements. Buyers prioritize consumable reliability, platform interoperability, and service proximity over upfront instrument costs. Understanding these decision hierarchies exposes where suppliers can defend margin versus where volume aggregation dominates.
Product Type:
Procurement economics favor recurring consumable commitments over capital equipment outlays, reshaping supplier revenue stability and customer lifetime value calculations.
- Reagents:Enzymes, buffers, fluorescent probes, and master mixes constitute the recurring consumable base tied to installed instrument footprints. Hospital laboratories in China's tier-one cities negotiate multi-year reagent supply bundles under municipal procurement frameworks, locking in volume commitments that compress per-test margins while securing predictable demand pipelines.
- Instruments:Thermal cyclers, automated extraction platforms, and NGS sequencers represent capital-intensive anchor purchases with 5-7 year replacement cycles. Australia's decentralized healthcare geography creates field service engineer scarcity that shapes instrument vendor selection toward suppliers with localized technical support networks.
- Software:Bioinformatics pipelines for variant interpretation and laboratory information management systems bridge analytical output to clinical decision-making. Integration complexity with hospital IT infrastructure limits standalone software purchases.
- Assays:Pre-validated test kits for specific pathogen detection or mutation profiling reduce in-house development burden. CDSCO's tightened IVD quality benchmarks in India are filtering substandard imported assays, elevating demand for validated alternatives.
Volume sits with Reagents; growth tilts toward Assays as regulatory validation requirements steepen.
Application:
Reimbursement policy and therapy protocol mandates determine where diagnostic testing commands premium pricing versus standardized panel deployment.
- Oncology:Companion diagnostic requirements for targeted therapeutics in Japan and South Korea mandate mutation profiling before reimbursement approval. PMDA's revised quality management system requirements elevate compliance documentation burdens that favor larger manufacturers with dedicated regulatory infrastructure.
- Infectious Diseases:Respiratory and bloodstream pathogen detection panels generate standardized hospital protocol volume across Southeast Asia under national AMR containment programs. Municipal health bureaus in China aggregate demand into multi-year supply agreements that bundle reagent consumption with instrument placement.
- Genetic Testing:Inherited disorder screening applications face variable reimbursement coverage across Asia-Pacific markets. Pre-analytical workflow bottlenecks in high-throughput laboratories create demand for automated nucleic acid extraction integration.
- Autoimmune Disorders:Molecular diagnostic penetration remains limited compared to serological methods. Technical substitution pressure from emerging CRISCR-based platforms constrains investment in conventional assay development.
Revenue concentration favors Oncology; expansion velocity is strongest in Infectious Diseases as surveillance infrastructure scales.
End User:
Customer scale and technical sophistication determine whether procurement emphasizes integrated service networks or price-optimized commodity supply.
- Hospitals:Tertiary oncology centers in Australia and Japan are displacing single-gene testing with integrated NGS platforms. Bioinformatics pipeline integration challenges outpace hospital IT capacity for variant interpretation workflow deployment.
- Laboratories:Mid-sized hospital laboratories in South Korea adopt modular sample preparation automation to offset technician shortages. Beckman Coulter's localized instrument service networks anchor regional competitive positioning.
- Research Institutes:Academic and translational research facilities drive early adoption of emerging sequencing technologies. Funding cyclicality and publication-driven demand create volatile purchasing patterns.
- Clinics:Point-of-care molecular diagnostic deployment remains constrained by regulatory complexity and reimbursement uncertainty. CRISPR-based diagnostic platforms are emerging as lower-cost alternatives to quantitative PCR in resource-limited settings.
Installed base dominance rests with Hospitals; point-of-care accessibility is expanding fastest in Clinics as platform miniaturization advances.
Technology:
Platform selection balances analytical sensitivity requirements against workflow integration complexity and total cost of ownership.
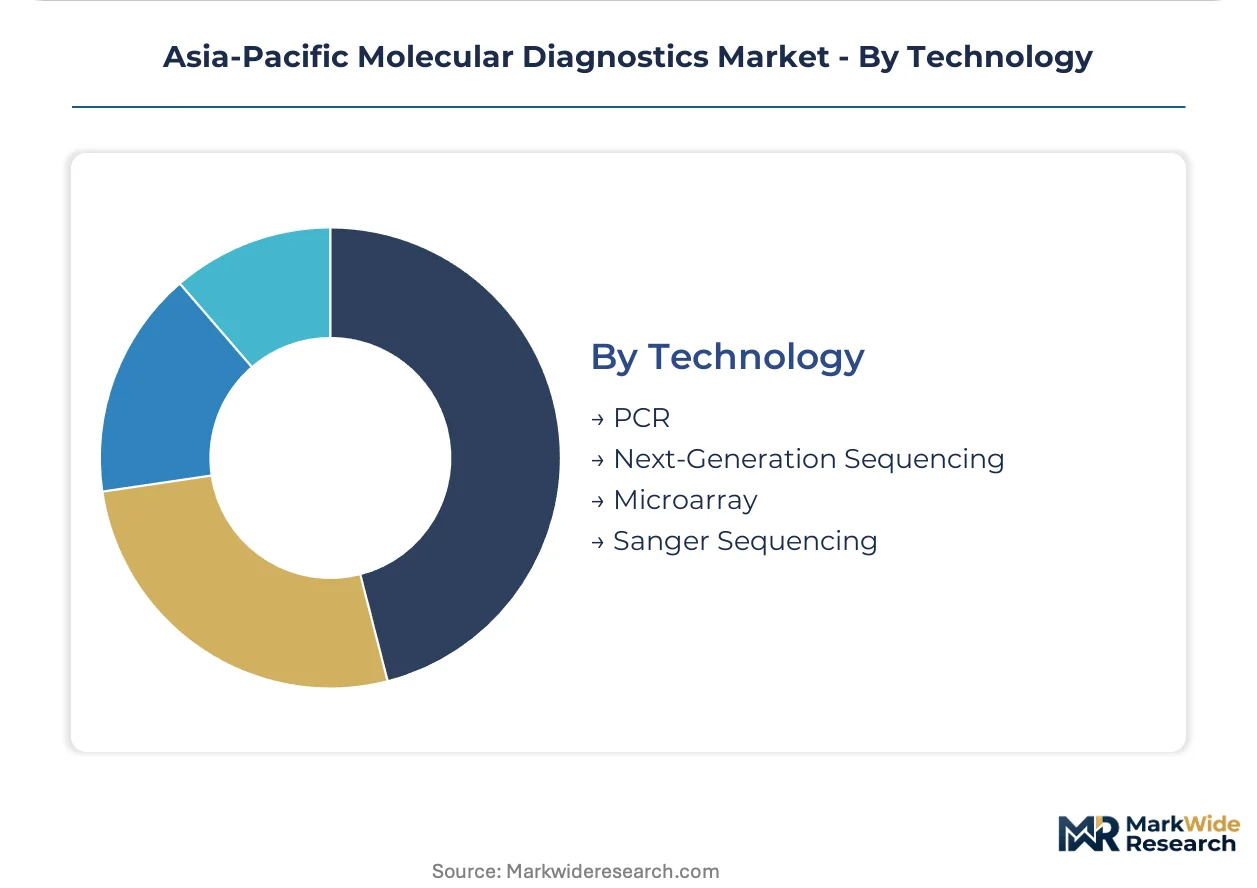
- PCR:Quantitative and digital PCR retain the largest installed base across Asia-Pacific hospital laboratories. Singapore's centralized manufacturing footprint sustains margin stability for multinational suppliers across ASEAN tender markets.
- Next-Generation Sequencing:NGS is displacing single-gene testing in tertiary oncology centers where companion diagnostic mandates create procedural pull-through for comprehensive mutation profiling. Qiagen NV competes on sample preparation automation where technical support proximity outweighs kit pricing alone.
- Microarray:Comparative genomic hybridization and SNP arrays maintain niche applications in cytogenetic analysis. Cost per data point disadvantages limit expansion against sequencing-based alternatives.
- Sanger Sequencing:First-generation sequencing persists for targeted validation of NGS findings and low-complexity genetic tests. Capital depreciation cycles and reagent supply concentration constrain replacement demand.
Installed volume concentrates in PCR; capability investment is shifting most aggressively toward Next-Generation Sequencing as precision oncology protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratory procurement across Asia-Pacific concentrates in China's tier-one cities, where municipal health bureaus aggregate diagnostic demand into multi-year supply agreements. Japan and South Korea drive precision oncology adoption through companion diagnostic mandates. Southeast Asian markets expand infectious disease surveillance infrastructure under national AMR programs.
China
Tier-one municipal health bureaus in Beijing, Shanghai, and Guangzhou consolidate hospital laboratory purchasing into centralized bidding frameworks. NMPA's stricter clinical validation standards for imported molecular diagnostic kits extend registration timelines and favor domestic manufacturers with established trial networks. Provincial capitals in Jiangsu and Zhejiang are extending procurement consolidation, bundling reagent consumption commitments with instrument placement.
Japan
Companion diagnostic requirements for targeted oncology therapeutics mandate mutation profiling before reimbursement approval, creating procedural pull-through for NGS panels. PMDA's revised quality management system requirements elevate documentation and audit standards for multinational assay suppliers. Tertiary oncology centers in Tokyo and Osaka are displacing single-gene testing with integrated NGS platforms.
India
CDSCO's tightened IVD import regulations filter substandard assay kits and elevate demand for validated alternatives. Local adverse event reporting mandates reshape distributor selection and post-market surveillance investment. Diagnostic procurement concentrates in Maharashtra and Karnataka, where hospital chains are consolidating laboratory networks under centralized supply contracts.
South Korea
Mid-sized hospital laboratories adopt modular sample preparation automation to offset technician shortages. MFDS alignment with international quality standards streamlines regulatory pathways for validated assay kits. Seoul's metropolitan hospital networks anchor demand for integrated PCR and NGS platforms.
Australia
TGA's convergence with EU MDR pathways creates dual-compliance efficiencies for European suppliers holding CE-IVD certifications. Decentralized healthcare geography generates field service engineer scarcity that shapes instrument vendor selection. Tertiary oncology centers in Sydney and Melbourne lead NGS adoption for comprehensive mutation profiling.
Asia-Pacific Molecular Diagnostics Market Competitive Landscape
Swiss and German producers anchor one tier; American specialists hold integrated platform positions. The vendor base spans multinational conglomerates with diversified life science portfolios and focused molecular diagnostic pure-plays. Three archetypes dominate: centralized manufacturing operators with regional distribution hubs, automated workflow specialists competing on technical service proximity, and sequencing platform vendors capturing oncology companion diagnostic pull-through. Competitive moves concentrate on regulatory compliance infrastructure investment and localized service network expansion.
Among Swiss-based conglomerates, F. Hoffmann-La Roche Ltd occupies a position exemplifying centralized manufacturing scale. Danaher represents the diversified life science operator archetype through its Beckman Coulter service infrastructure. Qiagen NV sits within the sample preparation automation specialist tier where technical support proximity outweighs kit pricing alone. These three anchors illustrate how compliance cost absorption, service network density, and workflow integration capability separate sustainable competitive positions from commodity exposure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| bioMerieux SA |
| Abbott Laboratories |
| Danaher |
| Illumina Inc |
| Agilent Technologies Inc |
| Qiagen NV |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc |
| Others |
Pricing and Supply Chain Analysis
Multinational conglomerates with centralized manufacturing footprints in Singapore and diversified life science portfolios anchor supply-side discipline, translating regional procurement consolidation into bundled pricing power across ASEAN tender markets while compressing margins for pure-play assay suppliers lacking integrated service networks.
Pricing Analysis
Premium positioning for rapid lead-time fulfillment dominates municipal procurement frameworks, with Beijing and Shanghai health bureaus paying contract premiums for guaranteed reagent supply security while spot-market assay kits face downward pressure from domestic manufacturers with localized trial networks. Three-tier pricing structure across premium companion diagnostics, standard infectious disease panels, and economy-grade research-use-only reagents reflects CE-IVD certification tier and technical support bundling. Cost compression in standardized PCR panels is intensifying because China's NMPA registration timeline extensions freeze non-domestic competitors from volume tenders. Hospital laboratories in tier-two provincial capitals exhibit highest price sensitivity, while tertiary oncology centers in Tokyo and Sydney absorb premium NGS platform costs through reimbursement-protected companion diagnostic protocols.
Supply Chain Analysis
Single-source vulnerability sits with specialized enzyme and fluorescent probe suppliers concentrated in Germany, Switzerland, and the United States, exposing assay manufacturers to input volatility when pharmaceutical-grade chemical production faces capacity constraints. Automated nucleic acid extraction robotics and thermal cycler components draw from precision manufacturing clusters in Japan, South Korea, and Germany, with logistics chokepoints through Singapore's regional distribution hub creating tender fulfillment risk. Distribution runs through municipal health bureau consolidated procurement offices in China's tier-one cities, hospital GPO contracts in Australia, and distributor-led field service networks in India's Maharashtra and Karnataka laboratory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific molecular diagnostics sector sits in a platform-transition phase, with next-generation sequencing displacing single-gene PCR testing in tertiary oncology centers and automated sample preparation modularizing laboratory workflows.
For Market Incumbents: Hedge against CRISPR-based diagnostic substitution by deepening backward integration into critical enzyme supply chains and accelerating regulatory affairs infrastructure investment for PMDA quality management system compliance. Anchor installed base retention through localized field service engineer density in Australia's decentralized healthcare geography, where technical support proximity outweighs kit pricing in vendor selection.
For New Entrants and Emerging Players: Australia's TGA-EU MDR convergence opens a window for European CE-IVD holders to bypass duplicative compliance costs and penetrate hospital procurement with validated assay kits. Target India's CDSCO-quality-elevated import channel by establishing pharmacovilance-capable distributor partnerships in Maharashtra and Karnataka, where hospital chain laboratory consolidation creates standardized panel demand.
For Investors and Strategic Acquirers: Distressed-cycle entries favor sample preparation automation specialists with technical service networks in South Korea and Australia, where technician scarcity accelerates robotic nucleic acid extraction adoption. Watch for inflection when China's provincial health bureaus extend municipal procurement consolidation beyond Jiangsu and Zhejiang into tier-three cities, signaling volume aggregation sufficient to support platform switching economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Convergence Pathway | TGA-EU MDR alignment reduces compliance duplication for European IVD suppliers holding CE-IVD certifications. |
| Sample Preparation Automation | Robotic nucleic acid extraction systems address technician shortages in South Korean mid-sized hospital laboratories. |
| Companion Diagnostic Partnership | NGS panel integration with targeted oncology protocols secures reimbursement-protected revenue in Japan and South Korea. |
| Localized Manufacturing Footprint | Singapore-based production sustains margin stability across ASEAN tender markets for multinational assay suppliers. |
| Post-Market Surveillance Infrastructure | CDSCO-mandated adverse event reporting capability filters distributor partnerships and elevates validated kit demand in India. |
Research Methodology
Company regulatory filings, hospital procurement databases, and GPO contract records formed the secondary backbone, cross-referenced against primary interviews with hospital laboratory directors, biomedical engineers, IVD regulatory affairs leads, and municipal health bureau procurement officers. Bottom-up instrument installation tracking and top-down reagent consumption modeling were triangulated against NMPA, PMDA, CDSCO, and TGA registration databases to validate market sizing assumptions.
Bottom-up modeling segmented demand across PCR, NGS, microarray, and Sanger sequencing technologies, further disaggregated by oncology, infectious disease, genetic testing, and autoimmune disorder applications, with pricing tiers reflecting CE-IVD certification level and technical support bundling. CAGRs were derived from installed base replacement cycles, municipal procurement volume commitments, and companion diagnostic protocol expansion trajectories across the analysis window.
Caveats apply where NMPA registration timeline volatility, CRISPR platform technical substitution, or sovereign health spending austerity could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
China in Vitro Diagnostics Market