
 Lipase Testing Reagents Market | 2026-2036
Lipase Testing Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Lipase Testing Reagents Market Foresight
Hospital procurement consortia is rewriting how lipase reagents reach end users in concentrated purchasing networks. Abbott leverages its installed base of automated chemistry analyzers to sustain recurring reagent revenue across North American health systems. DiaSys Diagnostic Systems GmbH anchors European distribution through ISO-certified manufacturing in Germany. Sunson Industry Group Co., Ltd. competes on recombinant enzyme cost structures from Chinese production facilities.
Lipase testing reagents comprise substrate-buffer systems, chromogenic or chemiluminescent indicators, and stabilizing cofactors designed to quantify pancreatic lipase activity in serum or plasma samples, typically operating within pH 7.5–8.5 and 37°C reaction conditions to ensure enzymatic specificity. Assay kits dominate hospital purchasing due to workflow integration with open-channel analyzers, while chemiluminescent reagents capture margin pools in high-throughput reference laboratories seeking lower detection limits. Home healthcare represents the fastest-growing application segment as point-of-care devices migrate enzyme quantification beyond centralized labs.
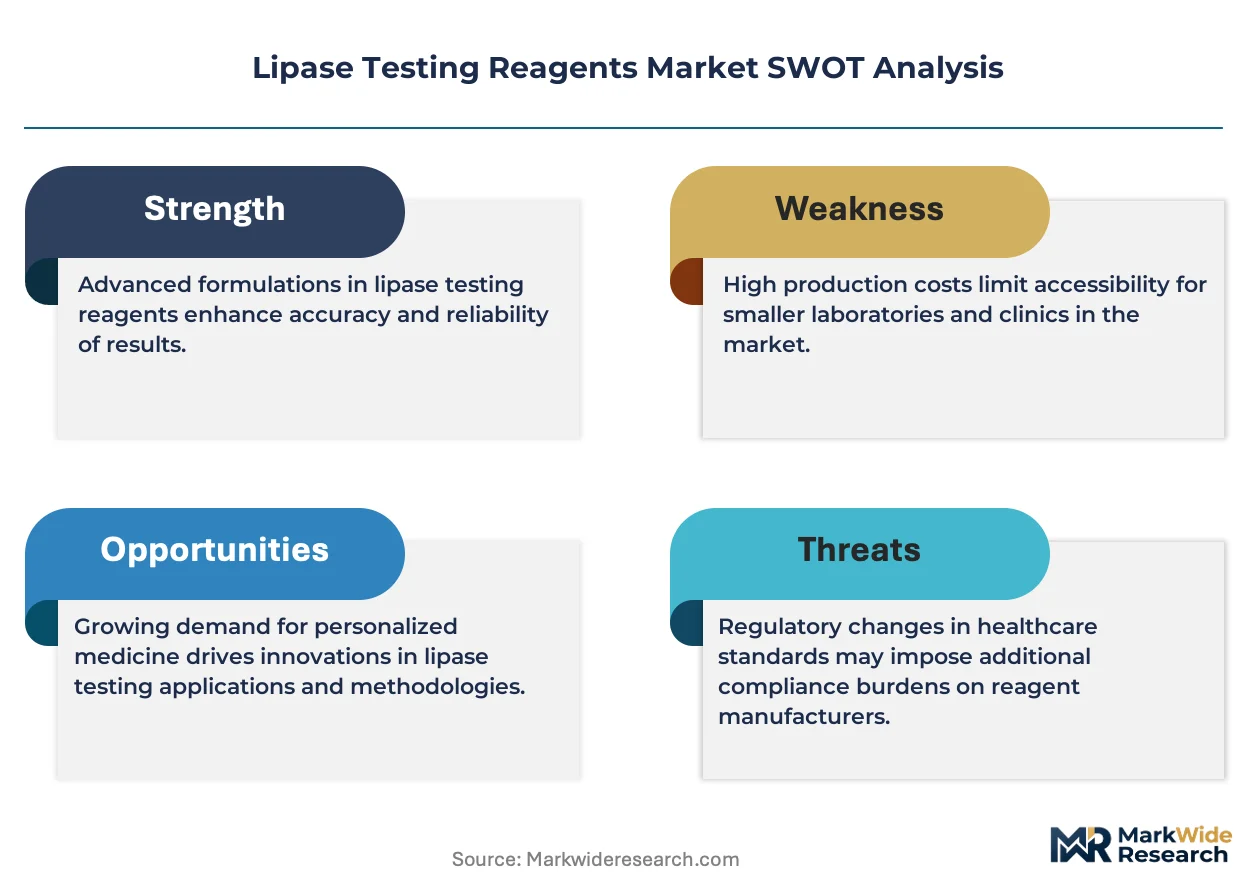
FDA clearance pathways for in vitro diagnostic reagents shape product development timelines and clinical claim substantiation in the United States, while EMA's In Vitro Diagnostic Regulation compels European manufacturers to renew technical documentation and performance data under stricter notified body oversight. India's CDSCO enforces import licensing and local quality testing for foreign-sourced diagnostic enzymes, creating compliance thresholds for multinational suppliers. Stakeholders must monitor evolving harmonization between FDA and EMA post-market surveillance requirements to anticipate dual-territory registration costs.
Market Dynamics
Hospital procurement consortia are consolidating purchasing power across integrated delivery networks, forcing reagent suppliers to restructure pricing and service models around multi-year sole-source contracts rather than transactional spot sales.
Growth Catalysts
- Point-of-care migration:Home healthcare devices for enzyme quantification are expanding addressable demand beyond centralized laboratories into ambulatory and residential settings.
- EMA MDR compliance cycles:European laboratories face mandatory revalidation of diagnostic assays under stricter notified body oversight, creating replacement demand for certified reagent kits.
- Recombinant enzyme production:Bioprocess advances in microbial expression systems are lowering unit production costs for high-purity lipase substrates.
Market Restraints
- Raw material concentration:Chromogenic indicator synthesis depends on specialty chemical suppliers concentrated in Germany and Switzerland, exposing reagent manufacturers to input bottlenecks.
- Technical specificity limits:Lipase assays require precise pH buffering between 7.5–8.5, constraining formulation flexibility and cross-platform compatibility.
- Substitution pressure from amylase testing:Some pancreatic function assessments now prioritize amylase quantification over lipase, particularly in pediatric diagnostics.
Strategic Opportunities
- Indian diagnostic expansion:CDSCO-mandated quality testing for imported enzymes creates openings for local manufacturing partnerships and technical service capabilities.
- Chemiluminescence-chemiluminescence convergence:Integration of high-sensitivity detection with automated immunoassay platforms enables multiplexed pancreatic panels in reference laboratories.
- Direct-to-laboratory distribution:Bypassing traditional distributor markups through manufacturer-managed e-procurement portals captures margin in price-sensitive segments.
Industry Challenges
- ISO 13485 certification timelines:In vitro diagnostic reagent manufacturers face 12–18 month approval cycles for quality management system updates, delaying product launches.
- Legacy analyzer integration:Open-channel chemistry systems require customized calibration protocols, fragmenting technical support resources across heterogeneous installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipase Testing Reagents Market |
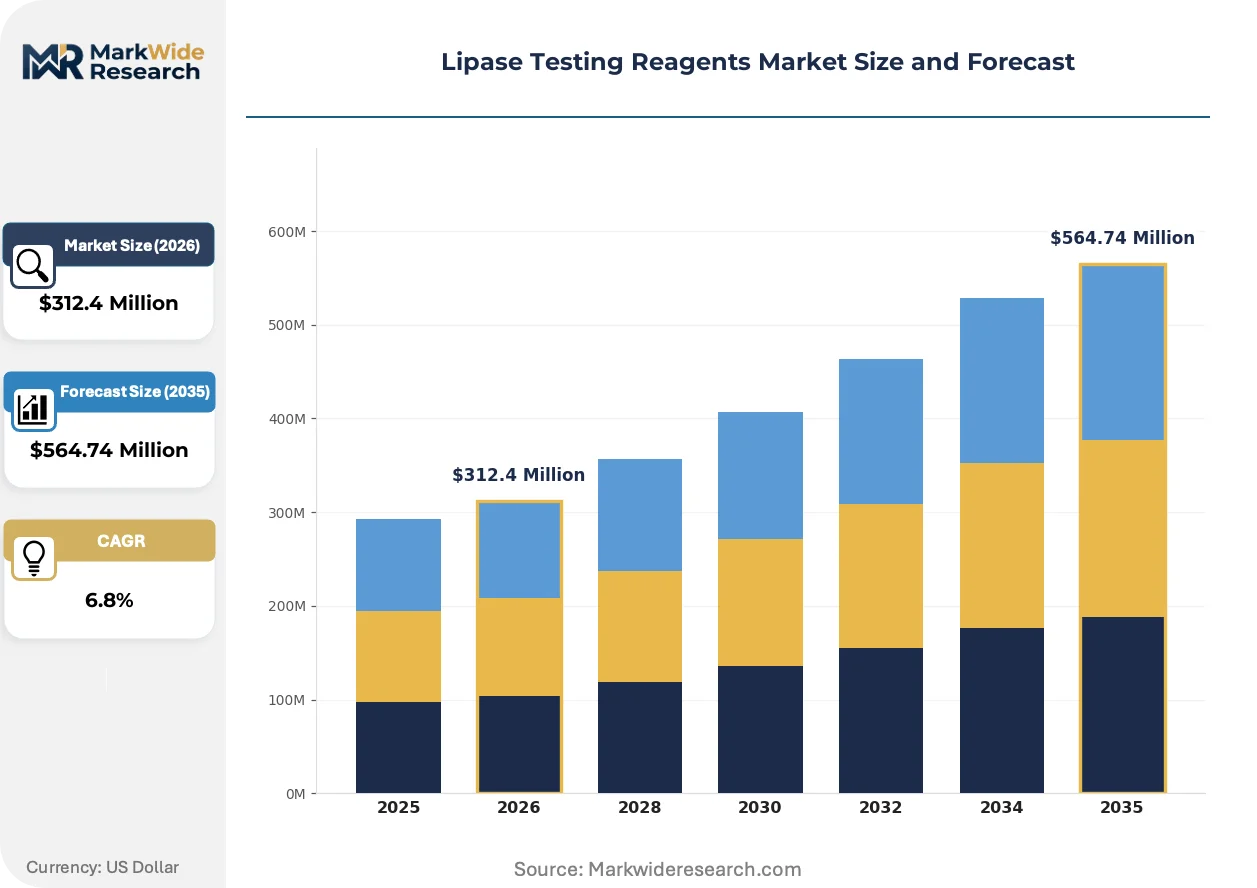
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Enzymes, Monoclonal Antibodies, Assay Kits, Chemiluminescent Reagents Application: Clinical Diagnostics, Research Laboratories, Blood Testing, Home Healthcare End User: Hospitals, Diagnostic Centers, Academic Institutions, Contract Research Organizations Delivery Mode: Liquid Reagents, Lyophilized Reagents, Kit-Based Solutions, Diagnostic Strips |
| Companies Covered | Abbott, Merck KGaA, DiaSys Diagnostic Systems GmbH, Biosystems S.A., Sunson Industry Group Co., Ltd., DIALAB GmbH, Beckman Coulter, Inc., Sisco Research Laboratories Pvt. Ltd., Randox Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipase Testing Reagents Market Shifts & Advancements
Reagent chemistry is converging with automation engineering and digital workflow management, compressing turnaround times while raising analytical sensitivity thresholds for pancreatic diagnostics.
Chemiluminescent substrate formulations are collapsing detection limits for low-concentration lipase samples. High-throughput reference laboratories in Germany and Japan are adopting these systems for STAT testing protocols. The technology is collapsing competitive differentiation previously held by specialized immunochemistry platforms, forcing chromogenic reagent suppliers into price-based positioning.
EMA's In Vitro Diagnostic Regulation is mandating renewed clinical performance documentation for all CE-marked reagents. Manufacturers must regenerate technical files under notified body supervision, extending product lifecycle management costs. European distributors are responding by consolidating supplier portfolios to reduce compliance administrative burden.
Consolidated purchasing through group purchasing organizations is replacing fragmented hospital buying. Integrated delivery networks in the United States now negotiate system-wide reagent contracts with penalty clauses for non-exclusive sourcing. This concentration is most visible in North American health systems where procurement departments report directly to chief financial officers rather than laboratory directors.
Lipase Testing Reagents Market Segmentation
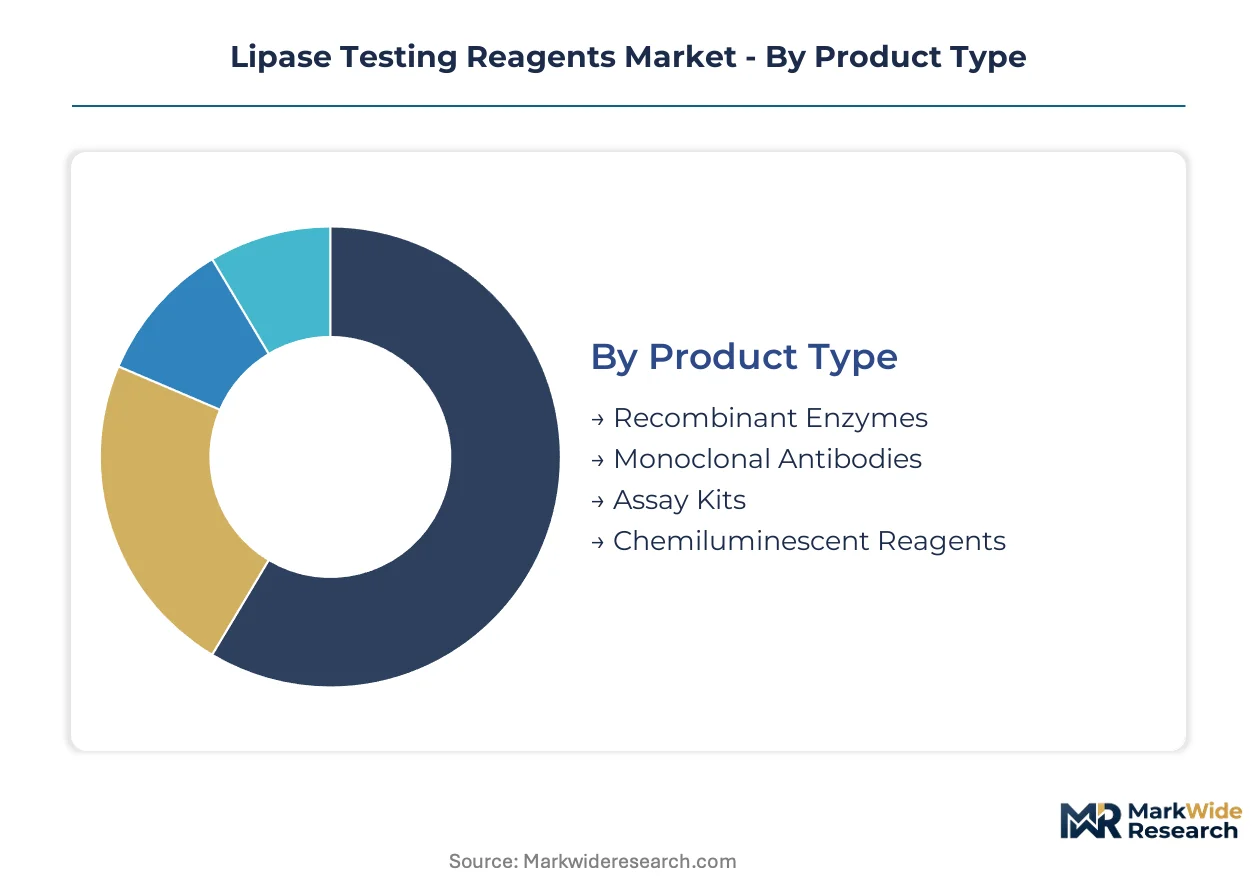
Segmentation in the lipase testing reagents market reveals distinct procurement rhythms and margin structures across product formats and use settings. Each category carries different inventory velocity, technical validation requirements, and customer concentration patterns that shape supplier strategy.
Product Type:
Cycle times vary dramatically: chemiluminescent reagents turn over fastest in high-throughput reference labs, while recombinant enzymes move slowest due to bulk purchasing and extended stability profiles.
- Recombinant Enzymes:Microbial expression systems produce high-purity lipase substrates with batch-to-batch consistency. Demand concentrates in kit manufacturers seeking backward integration into enzyme supply, driven by CDSCO-mandated quality documentation for Indian diagnostic production.
- Assay Kits:Pre-formulated substrate-buffer-indicator systems integrate with open-channel chemistry analyzers. Hospital procurement consortia in the United States favor these for workflow standardization, though EMA MDR compliance cycles are forcing revalidation of legacy kit configurations.
- Monoclonal Antibodies:Highly specific immunoreagents for lipase isoform detection in specialized pancreatic panels.
- Chemiluminescent Reagents:High-sensitivity detection chemistry for STAT testing protocols in German and Japanese reference laboratories.
Assay kits anchor the volume base while chemiluminescent reagents gain share at the steepest rate.
Application:
Margin concentration follows test urgency: emergency pancreatitis diagnostics command premium pricing, while research applications tolerate longer lead times and price sensitivity.
- Clinical Diagnostics:Serum and plasma lipase quantification for acute pancreatitis detection operates under FDA 510(k) and EMA IVDR pathways. Hospital laboratories in Germany drive demand for harmonized assay standardization aligned with EMA clinical chemistry guidelines.
- Home Healthcare:Point-of-care enzyme quantification devices bypass centralized laboratory infrastructure. Indian diagnostic expansion under CDSCO quality mandates is accelerating portable device registration, creating demand for stabilized reagent cartridges.
- Research Laboratories:Investigational applications in pancreatic disease modeling and drug metabolism studies.
- Blood Testing:Donor screening and transfusion-related enzyme monitoring in blood bank networks.
Clinical diagnostics anchors the volume base while home healthcare gains share at the steepest rate.
End User:
Customer scale determines contract structure: integrated hospital networks negotiate multi-year sole-source agreements, while academic buyers purchase through fragmented grant-funded procurement.
- Hospitals:Acute care settings require 24-hour STAT testing capability with analyzer-integrated reagent supplies. United States integrated delivery networks now centralize purchasing through CFO-directed procurement departments, consolidating vendor relationships.
- Diagnostic Centers:Independent laboratories and imaging chains in India are expanding enzyme-based testing capacity under CDSCO quality mandates, creating demand for ISO-certified reagent sourcing with local technical support.
- Academic Institutions:University medical centers and research hospitals with mixed clinical-investigational workflows.
- Contract Research Organizations:Externalized drug development and clinical trial services with specialized bioanalytical requirements.
Hospitals anchor the volume base while diagnostic centers gain share at the steepest rate.
Delivery Mode:
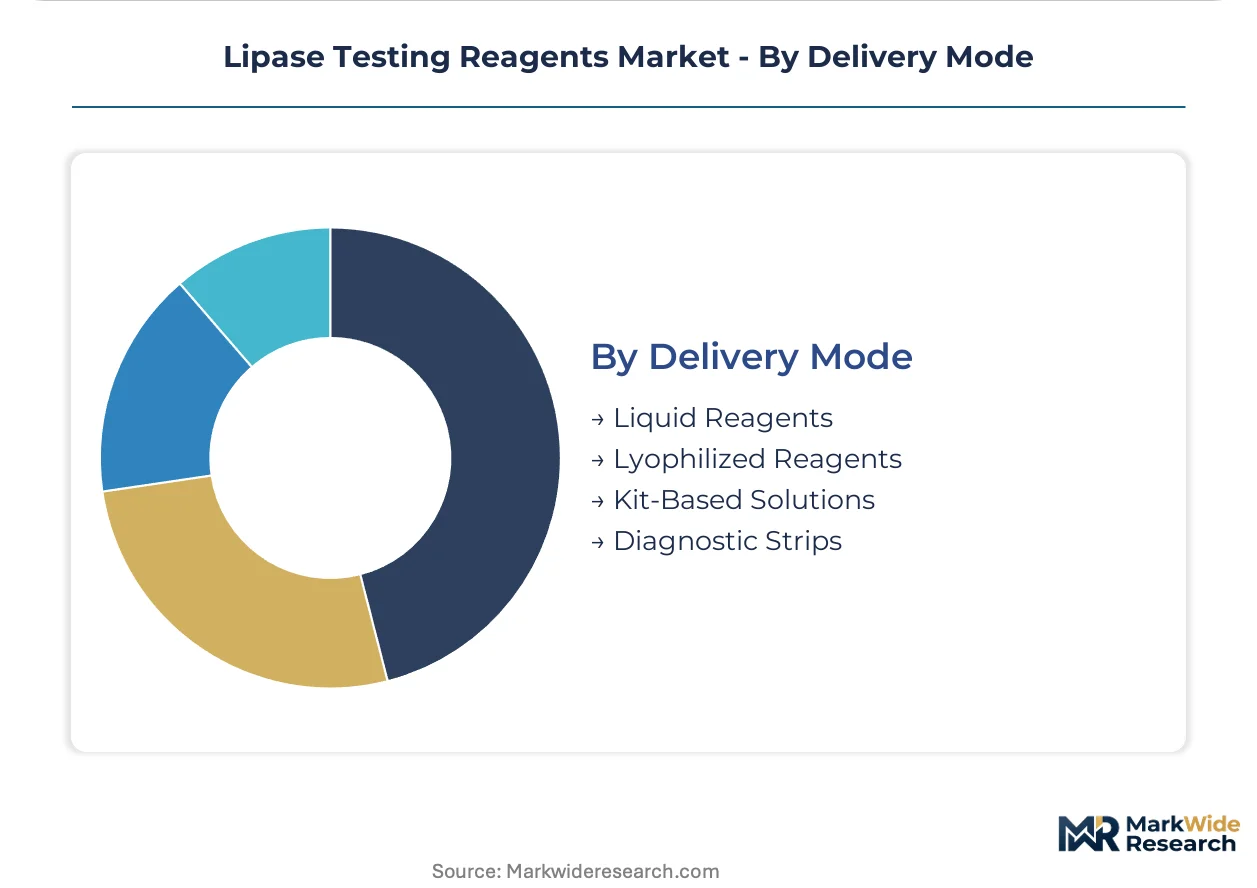
Supply chain configuration shapes geographic reach: liquid formulations require cold-chain logistics, while lyophilized formats enable ambient distribution to price-sensitive markets.
- Liquid Reagents:Ready-to-use formulations with precise pH buffering between 7.5–8.5 for immediate analyzer loading. German reference laboratories favor these for high-throughput chemiluminescent platforms where reagent stability and lot-to-lot consistency are critical.
- Kit-Based Solutions:Complete assay systems with calibrators, controls, and substrate cocktails in standardized packaging. Demand concentrates in diagnostic centers seeking workflow simplification with minimal validation overhead.
- Lyophilized Reagents:Freeze-dried enzyme preparations with extended shelf stability for ambient distribution.
- Diagnostic Strips:Solid-phase enzyme detection for portable point-of-care devices in home healthcare settings.
Kit-based solutions anchor the volume base while liquid reagents gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways and EMA's In Vitro Diagnostic Regulation are reshaping where manufacturers prioritize registration investments. CDSCO import licensing in India and Japan's PMDA quality benchmarks add further complexity to geographic expansion decisions.
United States
Hospital procurement consortia across integrated delivery networks now centralize reagent purchasing through CFO-directed departments. FDA 510(k) pathways govern clinical claim substantiation for pancreatic enzyme assays, extending product development timelines. The Boston-Cambridge diagnostic cluster anchors automated chemistry analyzer manufacturing, with reference laboratories in New York and California driving STAT testing demand.
Germany
EMA-aligned clinical chemistry standards drive precision diagnostics adoption in high-throughput reference laboratories. The In Vitro Diagnostic Regulation mandates renewed technical documentation under notified body oversight, creating replacement demand for certified reagent kits. The Munich-Stuttgart industrial corridor concentrates chemiluminescent substrate production, with Frankfurt-area distributors consolidating supplier portfolios to reduce compliance burden.
India
Diagnostic centers in Maharashtra and Karnataka are expanding enzyme-based testing capacity under CDSCO quality mandates. Import licensing and local quality testing for foreign-sourced diagnostic enzymes create compliance thresholds for multinational suppliers. The Hyderabad-Bengaluru med-tech corridor is emerging as a hub for ISO-certified reagent manufacturing partnerships.
Japan
PMDA quality benchmarks and METI industrial standards shape reagent validation requirements for pancreatic diagnostics. Reference laboratories in Tokyo and Osaka are adopting chemiluminescent systems for STAT testing protocols. The Kansai region's precision manufacturing base supports high-sensitivity detection chemistry production.
China
NMPA registration pathways and GB standards for in vitro diagnostic reagents govern market access for pancreatic enzyme assays. Recombinant enzyme production facilities in Jiangsu and Zhejiang provinces leverage microbial expression systems for cost-optimized substrate manufacturing. The Shanghai-Suzhou biotech cluster is integrating automated immunoassay platforms for multiplexed diagnostic panels.
Lipase Testing Reagents Market Competitive Landscape
On the supply side, the industry is consolidating around multi-year sole-source contracts rather than transactional spot sales. Hospital procurement consortia and group purchasing organizations are compressing vendor margins while favoring suppliers with analyzer-integrated workflow solutions. Three strategic archetypes dominate: multinational diagnostics conglomerates with automated platform installed bases, European ISO-certified manufacturers with EMA compliance expertise, and Asian recombinant enzyme specialists with cost-optimized production structures. Competitive moves center on backward integration into enzyme supply and direct-to-laboratory e-procurement portals that bypass traditional distributor markups.
Among Germany-based manufacturers, DiaSys Diagnostic Systems GmbH and DIALAB GmbH exemplify the European quality-certification archetype, anchoring distribution networks through notified body-aligned technical documentation. Abbott represents the multinational platform-integrated tier, leveraging recurring reagent revenue across North American health systems. Sunson Industry Group Co., Ltd. occupies the Asian production-optimization position, with Chinese manufacturing facilities serving cost-sensitive segments.
| Leading Market Players |
|---|
| Abbott |
| Merck KGaA |
| DiaSys Diagnostic Systems GmbH |
| Biosystems S.A. |
| Sunson Industry Group Co., Ltd. |
| DIALAB GmbH |
| Beckman Coulter, Inc. |
| Sisco Research Laboratories Pvt. Ltd. |
| Randox Laboratories Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese recombinant enzyme production is compressing spot pricing for bulk lipase substrates while simultaneously pressuring European manufacturers to defend margin through certification-tier differentiation. German chemiluminescent reagent facilities are responding by locking in multi-year offtake agreements with reference laboratories, converting variable demand into contracted revenue streams that insulate against Asian price erosion.
Pricing Analysis
Volume-discount tiering structures separate premium chemiluminescent reagents for STAT testing from standard chromogenic kits and economy-grade bulk enzymes for research applications. Price differentiation rests on ISO 13485 certification status and EMA IVDR technical documentation completeness, with notified body-aligned suppliers commanding 15-20 point spreads over uncertified competitors. Pricing pressure stems from hospital procurement consortia consolidating vendor panels under CFO-directed purchasing departments. Academic research laboratories exhibit highest price sensitivity, while German reference laboratories prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for reagent manufacturers with cross-border enzyme sourcing. Production concentrates in China for recombinant substrates, Germany for chemiluminescent indicators, and Switzerland for specialty chromogenic chemicals. Raw material dependencies include microbial expression media, synthetic substrate precursors, and stabilizing cofactor compounds. Single-source vulnerability concentrates in German-Swiss specialty chemical suppliers for indicator synthesis. Distribution runs through manufacturer-managed e-procurement portals direct to hospital systems, bypassing traditional distributor markups in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as point-of-care enzyme quantification migrates beyond centralized laboratories into ambulatory and residential settings, creating new addressable demand from home healthcare device manufacturers.
For Market Incumbents: Build installed-base moats through analyzer-integrated reagent contracts that embed workflow switching costs. Abbott and Beckman Coulter should extend calibration protocol standardization across open-channel chemistry systems to fragment competitor technical support resources. Defensive moves include backward integration into recombinant enzyme supply through partnerships with Jiangsu bioprocess facilities, and pre-emptive EMA IVDR technical file regeneration to capture replacement demand from non-compliant suppliers. The threat of amylase substitution in pediatric diagnostics demands R&D investment in multiplexed pancreatic panels that preserve lipase testing relevance. For New Entrants and Emerging Players: Indian diagnostic center expansion under CDSCO quality mandates offers the most penetrable geographic entry point, with Maharashtra and Karnataka laboratories seeking ISO-certified reagent sourcing with local technical support. White-space targets include stabilized reagent cartridges for portable point-of-care devices, and direct-to-laboratory distribution bypassing fragmented distributor networks. A go-to-market angle anchored in CDSCO import licensing compliance services bundled with reagent supply addresses unmet demand from multinational suppliers lacking local quality testing infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across recombinant enzyme production as microbial expression system yields improve, reducing barriers to backward integration. Long-term viability over a 5-10 year window favors platform-integrated diagnostics conglomerates with recurring reagent revenue streams over standalone reagent manufacturers exposed to procurement consortia price compression. Acquisition targets should profile as European ISO-certified manufacturers with EMA compliance expertise and established notified body relationships. The signal to watch is CDSCO mandating local manufacturing partnerships for import licensing, which would revalue Indian production assets.| Strategic Initiative | Industry Significance |
|---|---|
| EMA IVDR Technical File Regeneration | Notified body-aligned documentation captures replacement demand from non-compliant European suppliers. |
| CDSCO Local Manufacturing Partnership | Hyderabad-Bengaluru production assets satisfy import licensing mandates for Indian diagnostic expansion. |
| Chemiluminescence Platform Integration | High-sensitivity detection chemistry collapses competitive differentiation held by specialized immunochemistry platforms. |
| Direct-to-Laboratory E-Procurement Portal | Manufacturer-managed distribution bypasses traditional markups in price-sensitive North American health systems. |
| Recombinant Enzyme Backward Integration | Microbial expression system control secures batch-to-lot consistency for kit manufacturers under quality mandates. |
Research Methodology
The analysis maps recombinant enzyme supply, assay kit manufacturing, and chemiluminescent reagent production, each validated through procurement directors at integrated delivery networks, regulatory affairs leads at IVD manufacturers, and laboratory managers at German reference facilities. Primary interviews with hospital purchasing committees, GPO contracts managers, and CDSCO compliance officers combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation databases, and Indian import licensing records. Bottom-up demand modeling across end-user segments triangulated against top-down capacity assessments at Chinese bioprocess facilities.
Assumptions held fixed include EMA IVDR enforcement timelines, CDSCO quality mandate implementation, and chemiluminescence adoption curves in reference laboratories. Variables included hospital procurement consortia consolidation rates, recombinant enzyme yield improvements, and point-of-care device regulatory clearance pathways. Segmentation dimensions modeled encompass product type, application setting, end-user scale, and delivery mode logistics. CAGRs derived from installed base expansion, replacement demand cycles, and penetration rate trajectories across clinical diagnostics and home healthcare segments.
Practitioners should monitor EMA IVDR compliance deadlines, CDSCO local manufacturing mandates, and chemiluminescence platform conversion rates for early signals of forecast revision. Forecasts reflect assumptions about regulatory enforcement consistency, procurement consolidation trajectories, and technology substitution thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Blood Pressure Test Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Allergy Tester Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Global Sterility Testing Market