
 Paper Based Diagnostic Test Kits Market | 2026-2036
Paper Based Diagnostic Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Based Diagnostic Test Kits Market Analytics
ISO 13485 certification timelines for paper-based IVD manufacturing is collapsing from twenty-four months to under fourteen months in several jurisdictions. Siemens Healthineers leverages its captive supply of cellulose substrates to control quality from pulp to finished strip. Abbott anchors its competitive position through R&D intensity in fluorescent detection chemistry for cardiac biomarker panels.
Paper based diagnostic test kits are cellulose-fiber devices, typically manufactured by wax printing or photolithography on Whatman-grade substrates, designed to transport aqueous samples via capillary action to reaction zones for visual or instrument-read qualitative and semi-quantitative assays. Lateral flow assays occupy the largest installed base due to their simplicity, yet microfluidic devices represent the fastest-growing product category as multiplexing demands intensify in infectious disease panels. Home care settings extract disproportionate margin pools because reimbursement pathways for self-testing glucose and cardiac markers reward shelf-stable formats with minimal cold-chain requirements.
FDA 510(k) clearance pathways and WHO prequalification frameworks govern market access for paper-based diagnostics, with the former demanding clinical sensitivity benchmarks above ninety-five percent for HIV and malaria rapid tests. EMA's In Vitro Diagnostic Regulation extends conformity assessment burdens to lateral flow manufacturers seeking European market entry, particularly for cancer screening applications. Stakeholders must monitor evolving harmonization between FDA and WHO performance standards, as divergence in analytical specificity thresholds could fragment product development roadmaps and force parallel validation investments.
Market Dynamics
Capillary-driven cellulose substrates face mounting pressure from polymer microfluidic alternatives as WHO prequalification timelines compress and point-of-care networks in rural India and Southeast Asia demand multiplexed infectious disease panels.
Growth Catalysts
- WHO prequalification acceleration:Streamlined assessment pathways for HIV and malaria rapid diagnostics expand product eligibility across low-resource health systems in Kenya and Nigeria.
- Cellulose substrate innovations:Wax-printed Whatman-grade materials enable shelf-stable glucose and cardiac biomarker assays without cold-chain infrastructure.
- Home care reimbursement expansion:Self-testing formats for chronic disease monitoring attract favorable coverage decisions from payers prioritizing decentralized care models.
Market Restraints
- Photolithography equipment concentration:Precision patterning tools for microfluidic channel fabrication depend on German and Japanese capital equipment suppliers with extended lead times.
- Fluorescent detection chemistry costs:Rare-earth luminophores and conjugate stabilization reagents inflate per-test manufacturing economics beyond visual-read alternatives.
- EMA MDR conformity burdens:Extended technical documentation requirements for cancer screening lateral flows delay European market entry by twelve to eighteen months.
Strategic Opportunities
- Indonesia's archipelago logistics:Island health post networks create demand for heat-stable diagnostic formats bypassing refrigerated distribution.
- Multiplexing convergence with smartphone readers:Colorimetric-fluorescent hybrid detection couples paper substrates with CMOS imaging for quantitative home use.
- India PLI scheme for medical devices:Production-linked incentives offset capital costs for domestic IVD manufacturing facilities serving Southeast Asian export markets.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies for paper-based IVD quality management systems face backlogs extending implementation timelines.
- Cross-platform biomarker validation:Clinical correlation studies between lateral flow and laboratory reference methods require multisite trials with divergent regulatory acceptance criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Based Diagnostic Test Kits Market |
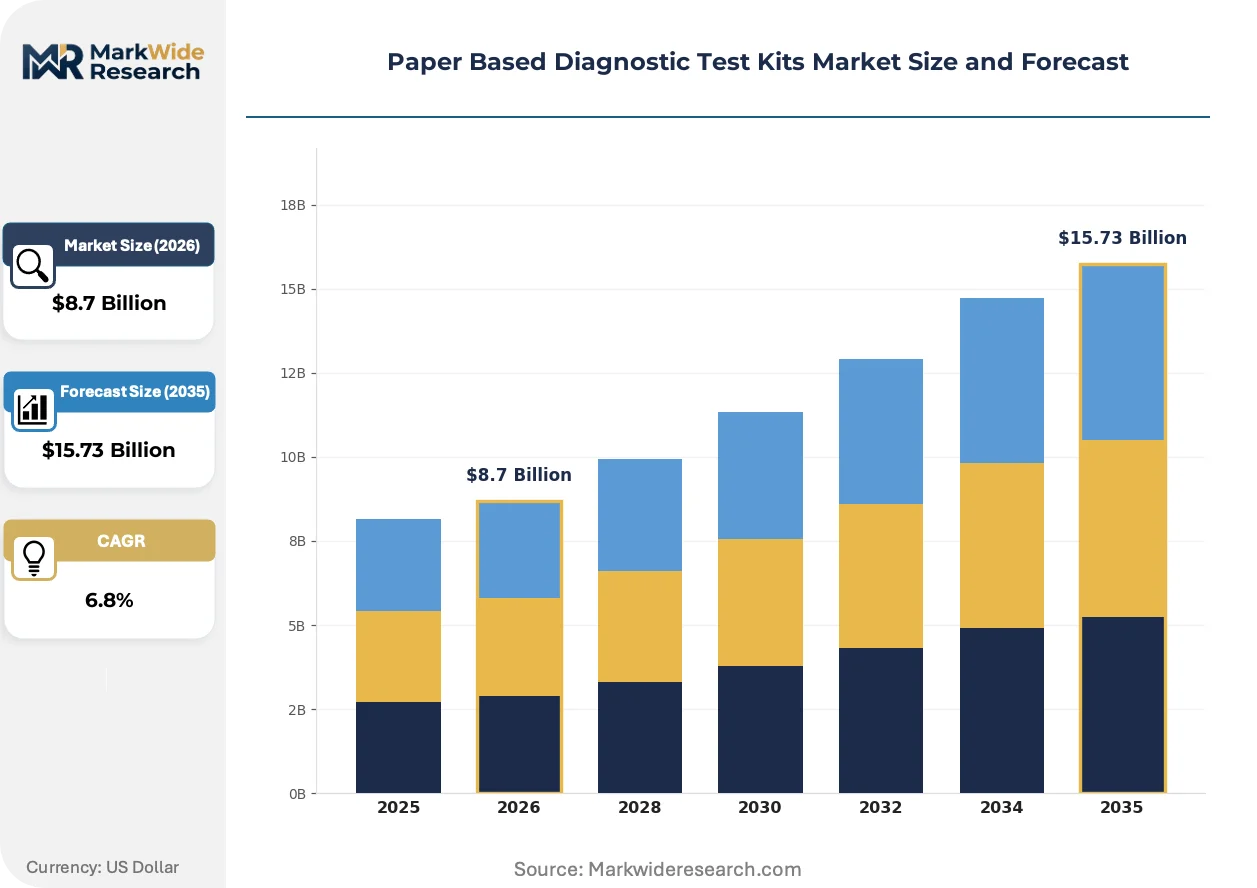
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, Lateral Flow Assays, Microfluidic Devices, Enzyme-Linked Immunosorbent Assays End User: Hospitals, Clinical Laboratories, Home Care, Research Institutes Application: Infectious Diseases, Diabetes Management, Cancer Screening, Cardiac Biomarkers Technology: Colloidal Gold, Paper Microfluidics, Immunochemistry, Fluorescent Detection |
| Companies Covered | Siemens Healthineers, ACON Laboratories, Abbott, Diagnostics For All, Chembio Diagnostic Systems, Roche, Bio-Rad Laboratories, Abingdon Health, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Based Diagnostic Test Kits Market Evolving Landscape
Detection chemistry architectures and manufacturing processes are diverging as quantitative demands intensify in infectious disease surveillance while visual-read formats retain cost advantages in screening programs.
Wax-printed microfluidic channel geometries on cellulose substrates is bifurcating the installed base between high-sensitivity instrument-read platforms and bare-eye qualitative screening tools. Reference laboratories in Thailand and Vietnam adopt smartphone-coupled fluorescence readers for dengue and Zika panels. This technology divergence compresses pricing power for mid-tier semi-quantitative formats lacking clear performance or cost positioning.
EMA's In Vitro Diagnostic Regulation extends post-market surveillance obligations to lateral flow manufacturers, mandating periodic safety reporting and clinical evidence updates for cancer screening applications. Manufacturers must maintain technical files with performance data spanning the product lifecycle. European notified bodies prioritize cardiovascular and oncology biomarker panels for enhanced scrutiny, forcing resource reallocation from infectious disease portfolios.
Hospital procurement consortia in Maharashtra and Tamil Nadu consolidate purchasing authority for rapid diagnostic tests, displacing fragmented distributor networks with direct manufacturer contracting. Volume commitments and performance-based payment terms replace traditional fee-for-product arrangements. This concentration is most visible in tertiary care networks standardizing on prequalified HIV and tuberculosis test formats across affiliated rural clinics.
Paper Based Diagnostic Test Kits Market Segmentation
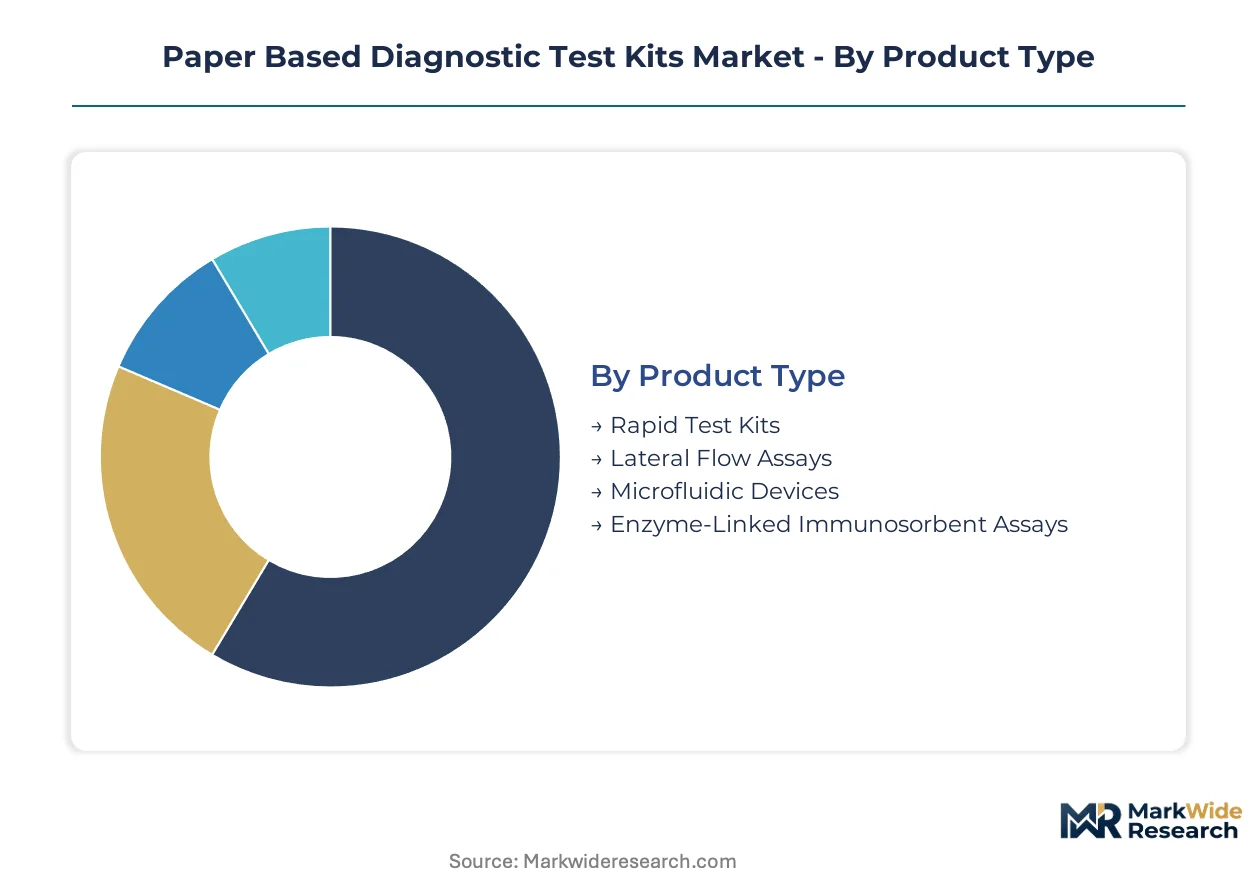
Paper-based diagnostics fragment across multiple technical and commercial axes. Manufacturers configure product portfolios around substrate chemistry, readout modality, and care setting economics. Segment boundaries blur as multiplexing demands reshape platform architectures.
Product Type:
Domestic production concentrates on lateral flow formats for local health systems. Export-led manufacturing targets instrument-read microfluidic platforms for regulated markets in Europe and North America.
- Lateral Flow Assays:Wax-printed cellulose strips transport samples via capillary action to reaction zones for visual or instrument-read detection. Demand clusters in rural Indian clinics and Southeast Asian island health posts where cold-chain infrastructure remains limited. WHO prequalification pathways favor these formats for HIV and malaria screening.
- Microfluidic Devices:Photolithography-patterned Whatman-grade substrates enable multiplexed detection of dengue, Zika, and chikungunya from single samples. Thailand and Vietnam reference laboratories drive adoption through smartphone-coupled fluorescence readers. Shelf stability without refrigeration supports archipelago logistics in Indonesia.
- Rapid Test Kits:Single-analyte visual-read formats dominate procurement tenders in Kenya and Nigeria.
- Enzyme-Linked Immunosorbent Assays:Laboratory-based quantitative platforms serve research institutes and clinical reference sites.
Lateral flow assays command the established base. The steepest expansion runs through microfluidic devices.
End User:
Margin structures diverge sharply across care settings. Home care formats extract premium economics through favorable reimbursement. Hospital procurement consolidates purchasing authority.
- Home Care:Self-testing glucose and cardiac biomarker panels leverage shelf-stable cellulose substrates with minimal cold-chain requirements. Payers in regulated markets reward decentralized chronic disease monitoring with coverage decisions that protect manufacturer margins. Abbott and Siemens Healthineers anchor competitive positions through R&D intensity in fluorescent detection chemistry.
- Hospitals:Tertiary care networks in Maharashtra and Tamil Nadu consolidate rapid diagnostic purchasing through direct manufacturer contracting. Volume commitments and performance-based payment terms displace fragmented distributor networks. Standardization on prequalified HIV and tuberculosis formats extends across affiliated rural clinics.
- Clinical Laboratories:Quantitative instrument-read platforms support diagnostic confirmation workflows.
- Research Institutes:Custom assay development drives demand for flexible substrate formats and novel detection chemistries.
Hospitals command the established base. Home care formats are climbing the fastest.
Application:
Infectious disease panels concentrate manufacturing volumes. Chronic disease monitoring commands pricing power through reimbursement attachment.
- Infectious Diseases:Multiplexed HIV, malaria, tuberculosis, and dengue panels dominate procurement in WHO prequalification pathways. Streamlined assessment timelines expand product eligibility across low-resource health systems. Kenyan and Nigerian national programs anchor demand volumes.
- Diabetes Management:Self-testing glucose strips operate in saturated markets with intense cost competition. Visual-read formats retain share in price-sensitive segments while fluorescent detection chemistries target premium instrument-coupled systems.
- Cancer Screening:EMA MDR conformity burdens extend technical documentation requirements for lateral flow manufacturers. European notified bodies prioritize cardiovascular and oncology biomarker panels for enhanced scrutiny.
- Cardiac Biomarkers:Point-of-care troponin and BNP assays serve emergency department triage workflows.
Infectious diseases command the established base. Cardiac biomarkers are gaining share fastest.
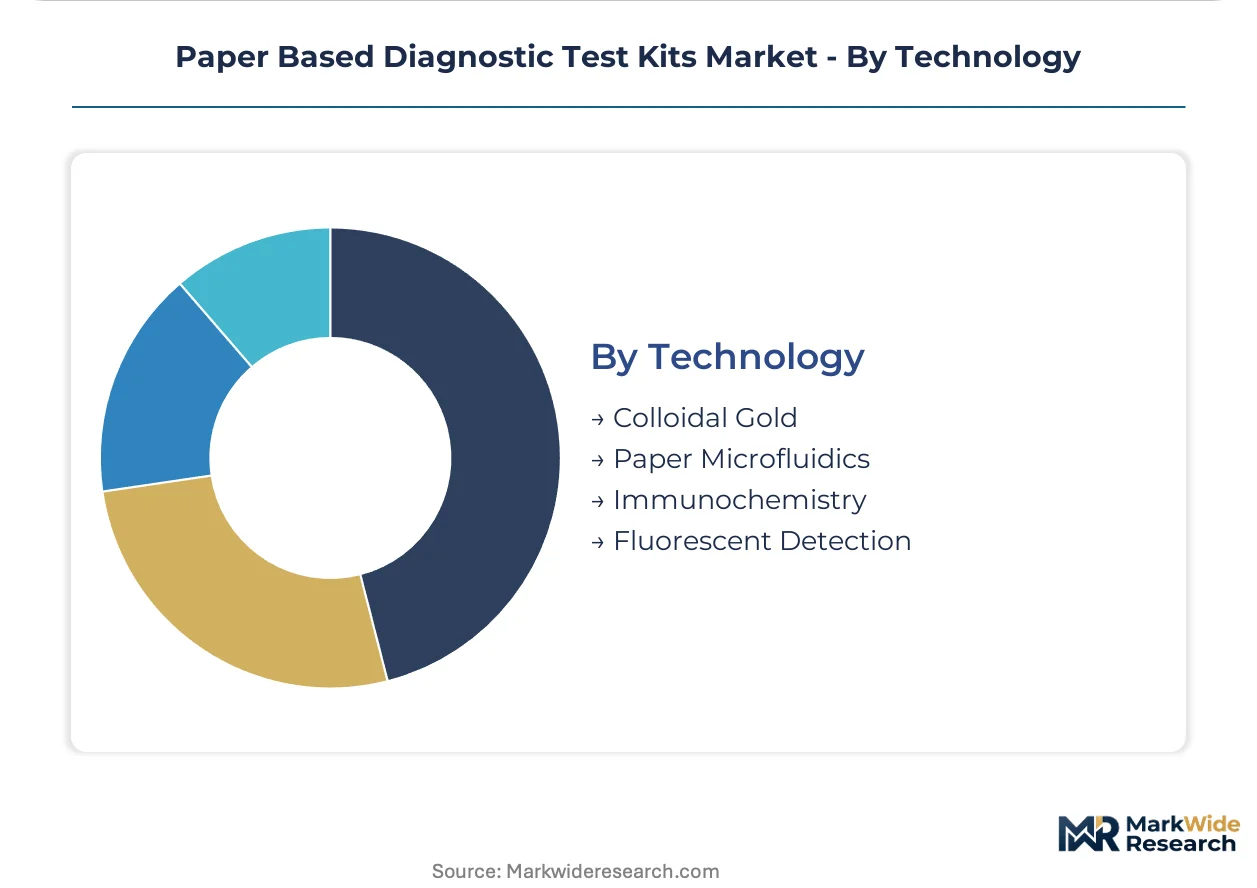
Technology:
Detection chemistry architectures bifurcate between cost-driven visual formats and sensitivity-driven instrument platforms. Manufacturing process selection locks in performance ceilings.
- Colloidal Gold:Visual-read qualitative detection dominates screening programs where bare-eye interpretation suffices. Cost economics favor high-volume production of single-analyte strips for resource-limited settings. Wax-printing equipment concentration among German and Japanese suppliers constrains capacity expansion timelines.
- Fluorescent Detection:Rare-earth luminophores and conjugate stabilization reagents enable quantitative sensitivity for cardiac and infectious disease panels. Per-test manufacturing economics exceed visual-read alternatives but attract favorable reimbursement in home care and hospital settings. Siemens Healthineers leverages captive cellulose substrate supply to control quality from pulp to finished strip.
- Paper Microfluidics:Capillary-driven channel geometries support multiplexed assay architectures.
- Immunochemistry:Antibody-antigen binding formats underpin specificity across detection modalities.
Colloidal gold commands the established base. Fluorescent detection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives in India compress ISO 13485 certification timelines and redirect manufacturing investment toward cellulose substrate facilities serving Southeast Asian export corridors.
India
Hospital procurement consortia in Maharashtra and Tamil Nadu consolidate rapid diagnostic purchasing through direct manufacturer contracting with volume commitments. CDSCO regulatory pathways align with WHO prequalification standards for HIV and malaria test formats. Domestic manufacturing clusters in Gujarat and Karnataka leverage PLI scheme offsets to expand lateral flow production capacity.
United States
FDA 510(k) clearance pathways demand clinical sensitivity benchmarks above ninety-five percent for HIV rapid tests, shaping product development priorities. Home care reimbursement expansion for self-testing glucose and cardiac biomarker panels rewards shelf-stable formats. Siemens Healthineers anchors its competitive position through R&D intensity in fluorescent detection chemistry.
Germany
EMA MDR conformity assessment burdens extend technical documentation requirements for cancer screening lateral flows, delaying market entry. Photolithography equipment concentration among German capital equipment suppliers constrains microfluidic channel fabrication capacity. Bavaria-based precision tooling manufacturers face extended lead times for wax-printing systems destined for Indian export markets.
Indonesia
Archipelago logistics networks create structural demand for heat-stable diagnostic formats bypassing refrigerated distribution to island health posts. Ministry of Health procurement standardizes on prequalified tuberculosis test formats across the eastern provinces. Java-based distributors consolidate supply chains for multiplexed infectious disease panels serving the outer islands.
Kenya
National HIV and malaria screening programs anchor demand volumes for single-analyte visual-read rapid test kits through WHO prequalification pathways. The country's national pharmaceutical regulator harmonizes import requirements with East African Community standards. Nairobi-based logistics hubs coordinate last-mile distribution to rural clinics in the Rift Valley and Western Province.
Paper Based Diagnostic Test Kits Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive substrate supply chains and specialized IVD manufacturers focused on lateral flow formats. Market structure concentrates around three strategic archetypes: integrated conglomerates controlling cellulose production from pulp to finished strip, mid-scale specialists in fluorescent detection chemistry, and regional contract manufacturers serving prequalified infectious disease panels. Dominant competitive moves include backward integration into cellulose substrate production and strategic partnerships with smartphone reader developers for quantitative home testing platforms.
Among diversified health technology conglomerates, Siemens Healthineers and Abbott exemplify the integrated archetype through upstream control over quality-critical material inputs. ACON Laboratories occupies a position within the specialist tier focused on high-volume production of visual-read formats for resource-limited settings. These three anchors illustrate the bifurcation between sensitivity-driven instrument platforms and cost-optimized screening tools.
| Leading Market Players |
|---|
| Siemens Healthineers |
| ACON Laboratories |
| Abbott |
| Diagnostics For All |
| Chembio Diagnostic Systems |
| Roche |
| Bio-Rad Laboratories |
| Abingdon Health |
| Danaher |
| Others |
Value Network & Pricing Analysis
Wax-printed cellulose substrates displacing photolithography-patterned alternatives simultaneously concentrate manufacturing in Gujarat and Karnataka while compressing price premiums for instrument-read formats. This substitution dynamic redirects procurement power toward domestic Indian suppliers serving Southeast Asian export corridors, eroding margins for German and Japanese equipment-dependent tiers.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium instrument-read microfluidic platforms and economy visual-read lateral flows. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, cellulose substrate purity grades, and fluorescent detection chemistry inclusion. Cost compression in economy tiers is intensifying because Kenyan and Nigerian national programs consolidate volume tenders. Hospital procurement consortia in Maharashtra and Tamil Nadu exhibit least price sensitivity due to performance-based contracting, while island health posts in Indonesia remain most cost-constrained.
Supply Chain Analysis
Photolithography equipment concentration among Bavaria-based precision tooling manufacturers constrains microfluidic channel fabrication capacity for multiplexed infectious disease panels. Raw material flows draw from Whatman-grade cellulose pulp suppliers in North America, rare-earth luminophore processors in China, and conjugate stabilization reagent specialists in Japan. Single-source vulnerability persists for wax-printing equipment with extended lead times from German and Japanese capital equipment suppliers. Distribution runs through Java-based distributors consolidating supply chains for Indonesia's archipelago logistics and Nairobi-based hubs coordinating last-mile delivery to Kenya's Rift Valley clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification acceleration represents a regulatory inflection compressing market entry timelines from twenty-four months to under fourteen months, enabling high-growth disruption for cellulose substrate innovators. This streamlining simultaneously expands addressable health systems and intensifies competitive velocity.
For Market Incumbents: Shield market position through backward integration into captive cellulose substrate production and accelerated ISO 13485 certification investments. Polymer microfluidic alternatives threaten instrument-read platform margins. Siemens Healthineers exemplifies defensive positioning through pulp-to-finished-strip quality control. For New Entrants and Emerging Players: Anchor in Indonesia's archipelago logistics gap for heat-stable diagnostic formats bypassing refrigerated distribution. Smartphone-coupled fluorescence readers for quantitative home use represent the most penetrable white-space. Partner with CMOS imaging developers for hybrid colorimetric-fluorescent detection platforms. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists in fluorescent detection chemistry with established WHO prequalification pathways. Long-term viability over a five-to-ten-year window rests on multiplexing convergence with decentralized care reimbursement expansion. Monitor EMA MDR conformity burden evolution as the critical inflection signal for European market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Streamlined assessment expands product eligibility across Kenyan and Nigerian health systems. |
| Cellulose Substrate Backward Integration | Captive pulp-to-finished-strip control protects quality margins against supply volatility. |
| Smartphone Reader Partnership | CMOS imaging integration enables quantitative home testing for cardiac biomarker panels. |
| India PLI Scheme Utilization | Production-linked incentives offset capital costs for Southeast Asian export manufacturing. |
| EMA MDR Conformity Investment | Enhanced technical documentation capabilities accelerate cancer screening lateral flow entry. |
Research Methodology
The analysis maps lateral flow assays, microfluidic devices, rapid test kits, and enzyme-linked immunosorbent assays, each validated through quality management directors, regulatory affairs leads at IVD manufacturers, hospital procurement committee members, and GPO contracts managers. Primary interview insights triangulate against FDA 510(k) filings, WHO prequalification databases, CDSCO regulatory circulars, and EMA MDR technical documentation requirements. Bottom-up volume modeling and top-down value reconciliation ensure consistency across substrate chemistry, readout modality, and care setting dimensions.
Forecasts were validated against external benchmarks including hospital procurement consortium tender awards, national HIV program volume disclosures, and cellulose substrate trade flow data. The analytical framework segments by product type, end user, application, and detection technology across the projection horizon. CAGRs derive from installed base evolution, replacement cycle analysis, and reimbursement pathway expansion rates. Industry-specific inputs include WHO prequalification timeline compression rates and EMA notified body capacity constraints.
Material uncertainties — ISO 13485 auditor scarcity extending implementation timelines, divergence between FDA and WHO analytical specificity thresholds, and photolithography equipment lead time volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding harmonization trajectory and cellulose substrate innovation cadence. Revision becomes warranted when regulatory divergence or supply chain chokepoint severity crosses thresholds affecting manufacturer entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
US Influenza Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market