
 Infectious Disease Point-Of-Care (POC) Diagnostics Market | 2026-2036
Infectious Disease Point-Of-Care (POC) Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Disease Point-Of-Care (POC) Diagnostics Market Analysis
The FDA's Emergency Use Authorization framework is repositioning the cost-of-entry calculus for infectious disease POC diagnostics, forcing smaller developers to front-load clinical validation spending before commercialization. Abbott leverages its vertically integrated manufacturing footprint to sustain margin control across lateral flow and molecular cartridge production. Siemens Healthineers anchors its competitive position through installed-base density in hospital emergency departments, while bioMérieux SA specializes in syndromic multiplex panels that differentiate its menu from commodity rapid tests.
Infectious disease point-of-care diagnostics encompass portable analytical systems designed to detect pathogenic agents directly at or near the patient site, typically delivering results within five to sixty minutes through sample-to-answer workflows that integrate nucleic acid amplification, immunochromatographic detection, or electrochemical sensing on miniaturized disposable cartridges. These devices serve primarily to compress diagnostic turnaround time, enabling clinicians to initiate targeted antimicrobial therapy during a single patient encounter rather than awaiting centralized laboratory confirmation. Molecular diagnostics platforms command premium positioning due to their analytical sensitivity and multiplexing capacity, while lateral flow technology occupies high-volume, low-cost screening applications in clinics and home care settings. Isothermal amplification methods are gaining structural traction in resource-limited deployment contexts where thermocycler infrastructure proves impractical.
FDA clearance pathways, European CE marking under the In Vitro Diagnostic Regulation, and WHO prequalification standards collectively shape product development roadmaps and market access sequencing for manufacturers targeting multiple geographies. The EPA maintains jurisdiction over waste disposal protocols for contaminated test consumables, adding compliance layers to product design specifications. Stakeholders must monitor evolving reimbursement codes for home-based testing and anticipate how decentralized regulatory harmonization between the FDA and notified bodies will reshape competitive positioning.
Market Dynamics
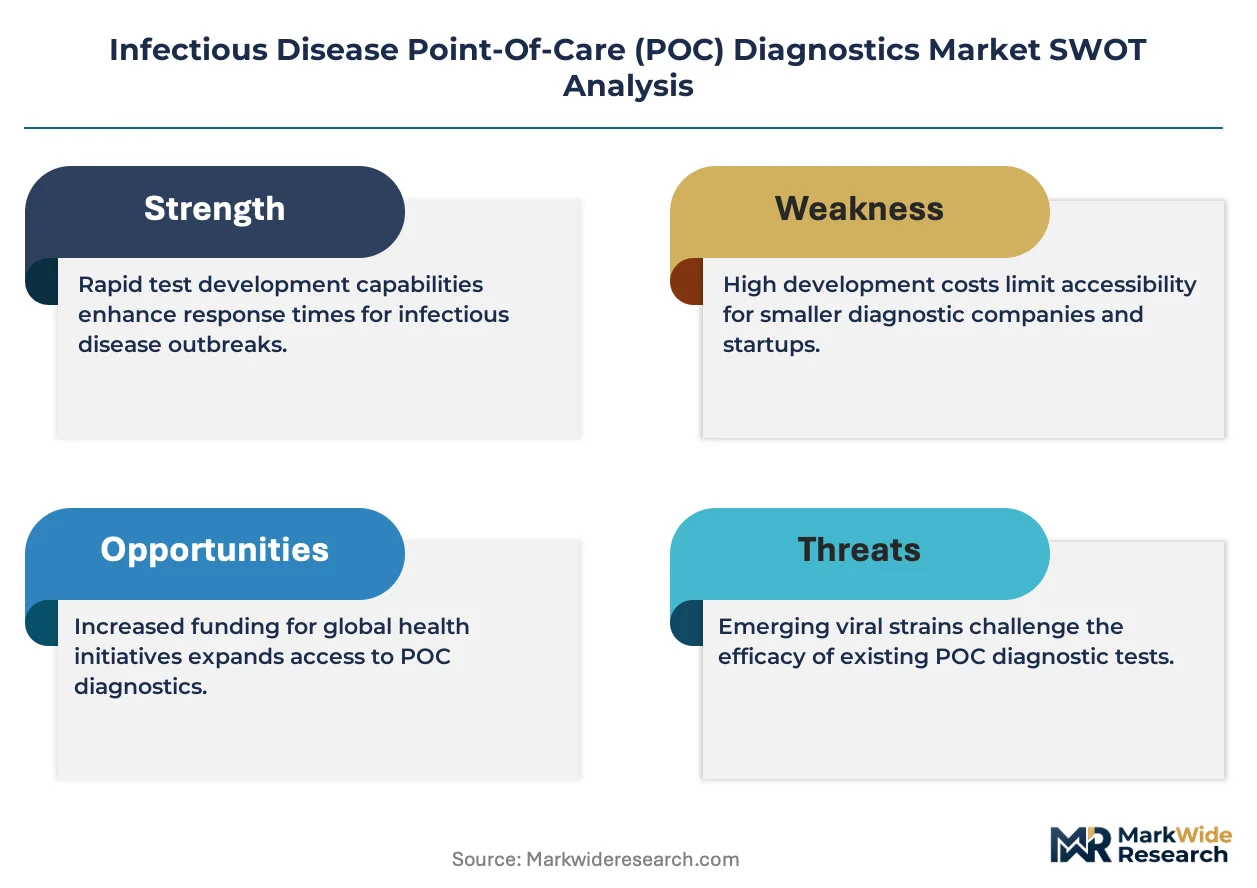
Decentralized testing infrastructure is compressing diagnostic workflows into retail pharmacy and home settings, forcing manufacturers to re-engineer devices for untrained users while maintaining clinical-grade analytical performance.
Growth Catalysts
- CLIA Waivers:The FDA's Clinical Laboratory Improvement Amendments waiver pathway is expanding the addressable site base for moderate-complexity molecular tests into physician offices and urgent care clinics.
- Isothermal Amplification:Loop-mediated isothermal amplification (LAMP) and recombinase polymerase amplification (RPA) methods are eliminating thermocycler dependencies, opening deployment in resource-limited field settings.
- Medicare Reimbursement:United States reimbursement codes for home-based infectious disease testing are accelerating patient self-testing adoption through pharmacy retail channels.
Market Restraints
- Raw Material Concentration:Nitrocellulose membrane and conjugate pad supply chains concentrate among Southeast Asian specialty chemical manufacturers, creating single-source vulnerabilities.
- Validation Cost Burden:The FDA's evolving Emergency Use Authorization framework is front-loading clinical validation spending, elevating capital requirements before commercialization.
- Centralized Laboratory Substitution:High-throughput automated analyzers in hospital core labs retain cost advantages for high-volume screening, limiting POC penetration in health system accounts.
Strategic Opportunities
- Multiplex Syndromic Panels:Respiratory and gastrointestinal pathogen combinations are capturing premium positioning in emergency departments by replacing sequential single-target testing.
- At-Home Subscription Models:Direct-to-consumer recurring test kits for sexually transmitted infections are building predictable revenue streams outside traditional clinical procurement.
- Indian Manufacturing Incentives:The country's Production Linked Incentive scheme for medical devices is attracting contract manufacturing investment for export-oriented cartridge production.
Industry Challenges
- Quality Control Talent Scarcity:Manufacturing engineers with combined expertise in microfluidics, biochemistry, and regulatory compliance command premium compensation, constraining scale-up velocity.
- Legacy LIS Integration:Hospital information system connectivity requirements vary across Epic, Cerner, and MEDITECH deployments, fragmenting software development roadmaps.
- Waste Disposal Compliance:EPA jurisdiction over contaminated test consumables is adding operational complexity to product take-back programs and reverse logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Disease Point-Of-Care (POC) Diagnostics Market |
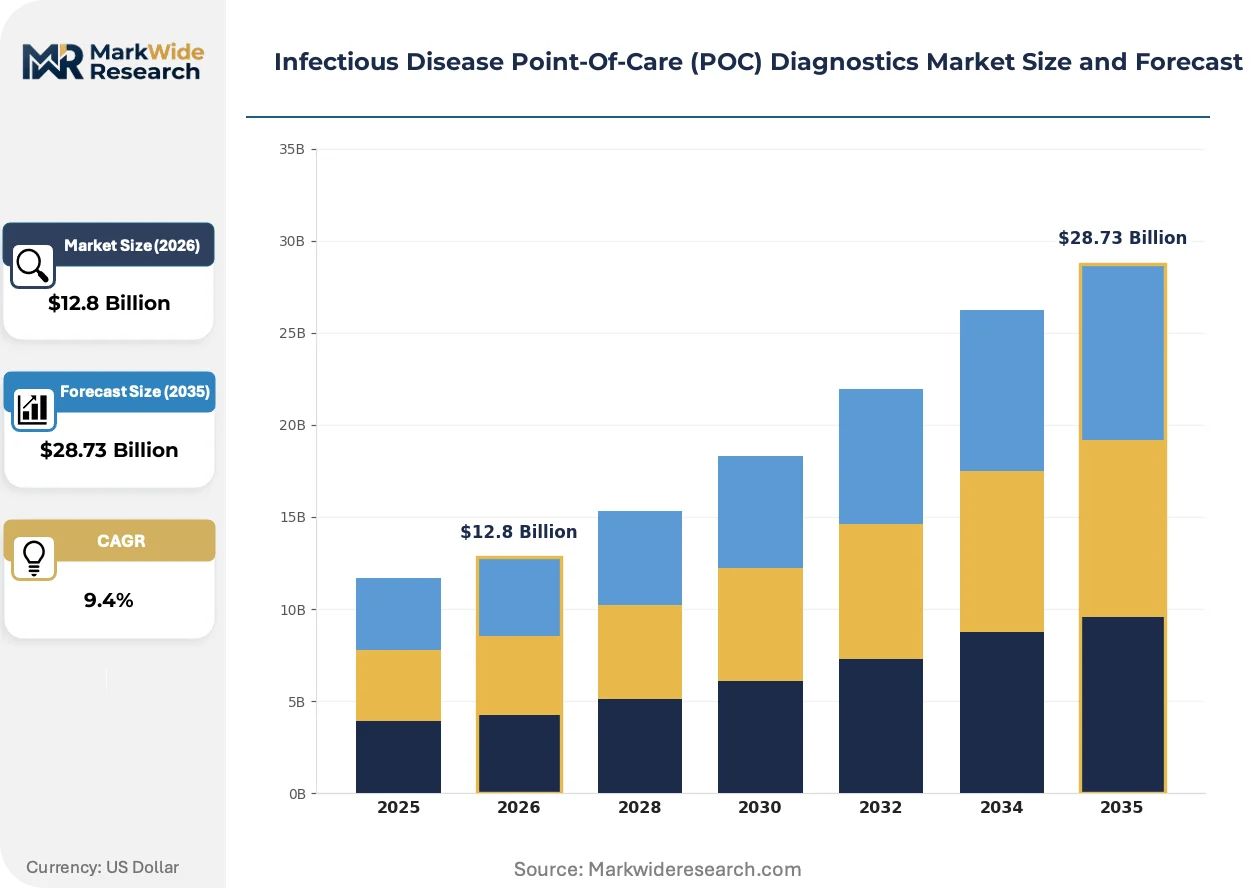
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Antigen Tests, Molecular Diagnostics, Serology Tests Technology: PCR, Lateral Flow, Microfluidics, Isothermal Amplification End User: Clinics, Hospitals, Research Laboratories, Home Care Delivery Mode: Disposable Devices, Reusable Devices, Cartridge-Based, Integrated Systems |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Thermo Fisher Scientific Inc, Danaher Corporation, bioMérieux SA, Becton, Dickinson & Company, Quest Diagnostics Incorporated, Bio-Rad Laboratories Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Disease Point-Of-Care (POC) Diagnostics Market Emerging Trajectories
Microfluidic integration and artificial intelligence-assisted result interpretation are compressing the skill gap required for accurate pathogen detection at the point of care.
Digital microfluidics is automating sample preparation, nucleic acid extraction, and amplification within single-use cartridges, reducing operator steps from fifteen to three. Community health centers and retail clinics are adopting these platforms to extend molecular diagnostic capability without laboratory technician staffing. The technology is automating error-prone manual pipetting, improving reproducibility across variable user skill levels.
The European Union's In Vitro Diagnostic Regulation (IVDR) is elevating clinical evidence requirements for Class C and D devices, extending conformity assessment timelines by twelve to eighteen months. Manufacturers are restructuring quality management systems and post-market surveillance protocols to satisfy notified body expectations. High-risk infectious disease assays face the steepest compliance burden, consolidating development resources toward larger portfolio holders.
Hospital procurement committees are unbundling instrument placement from reagent contracts, shifting toward competitive bidding for consumables across installed bases. Group purchasing organizations are consolidating negotiating leverage for high-volume accounts, pressuring manufacturers to disclose cartridge cost structures. This behavioral shift is most pronounced in United States integrated delivery networks managing multi-site standardization mandates.
Infectious Disease Point-Of-Care (POC) Diagnostics Market Segmentation
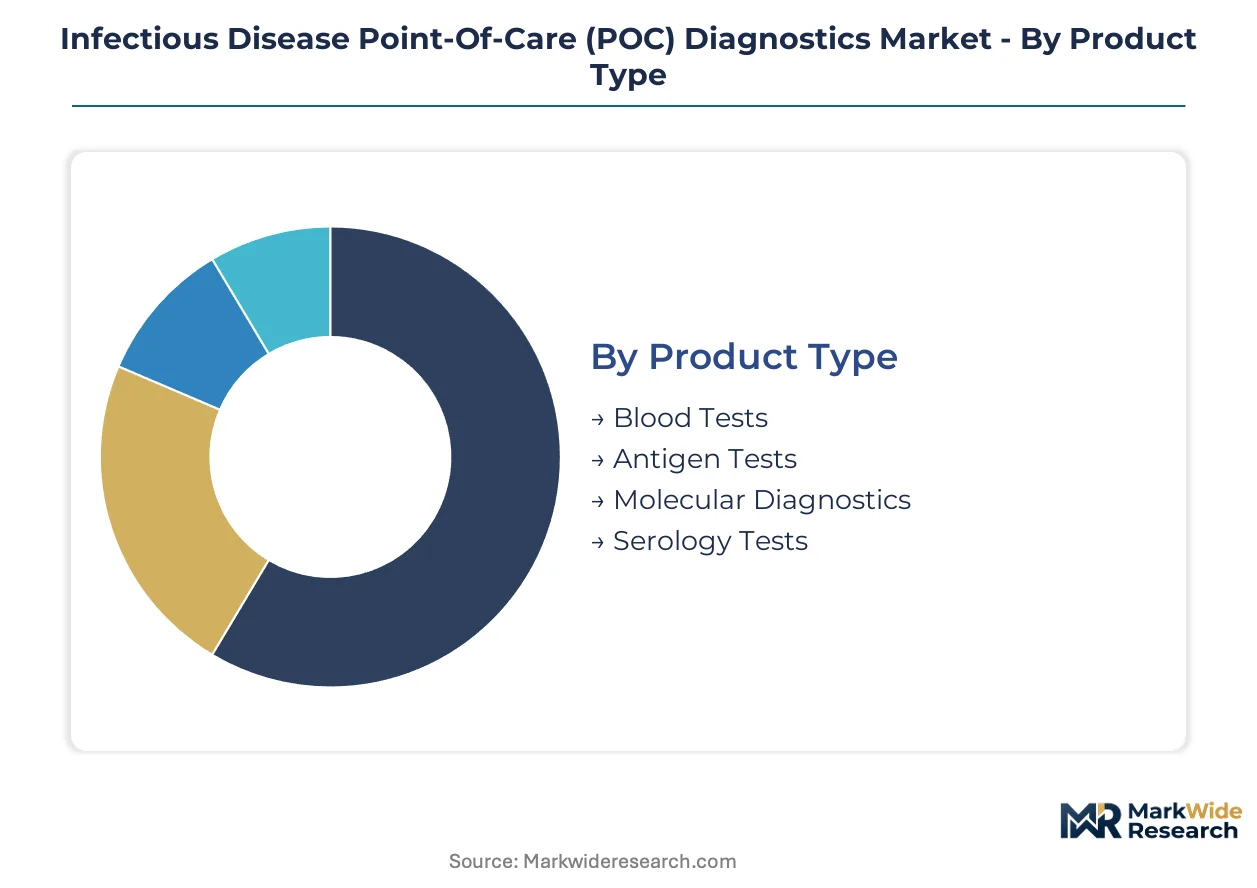
Segmentation in infectious disease POC diagnostics reveals how technology choices, clinical setting requirements, and regulatory pathways fragment manufacturing priorities. Product architecture decisions cascade through reimbursement eligibility, supply chain design, and competitive differentiation.
Product Type:
Customization intensity spans from commodity rapid strips to engineered molecular cartridges, with standardization deepest in high-volume screening formats.
- Molecular Diagnostics:Nucleic acid amplification platforms deliver sample-to-answer workflows with analytical sensitivity rivaling centralized laboratories. Demand concentrates in United States hospital emergency departments where syndromic panels replace sequential testing, driven by CLIA waiver expansion enabling placement in non-laboratory settings.
- Antigen Tests:Lateral flow immunochromatographic strips detect pathogen surface proteins through visual line formation without instrumentation. Pharmacy retail channels in the United States are absorbing volume through Medicare-reimbursed home testing programs, constrained by cold-chain requirements for conjugate stability.
- Blood Tests:Whole-blood analyzers integrate hematology and infectious marker detection on finger-stick samples.
- Serology Tests:Antibody detection assays identify past infection or immune response through capillary blood or serum.
Most installed capacity flows through Antigen Tests. Expansion is steepest in Molecular Diagnostics.
Technology:
Cost tier stratification separates capital-intensive thermocycler-dependent platforms from deployable field methods.
- PCR:Polymerase chain reaction thermocycling achieves gold-standard analytical specificity through temperature-cycled denaturation and extension. United States urgent care clinics are adopting cartridge-based PCR systems where CLIA waivers permit operation without certified laboratory personnel, limited by instrument footprint and power requirements.
- Isothermal Amplification:Loop-mediated isothermal amplification and recombinase polymerase amplification operate at constant temperature, eliminating thermocycler hardware. Community health centers in India are deploying these platforms under Production Linked Incentive scheme subsidies, constrained by primer design complexity for multiplex targets.
- Lateral Flow:Immunochromatographic capillary action drives reagent migration through nitrocellulose membranes.
- Microfluidics:Digital droplet manipulation automates sample preparation and detection within disposable cartridges.
Most installed capacity flows through PCR. Isothermal Amplification is gaining share fastest in resource-limited deployment contexts.
End User:
Customer type determines regulatory pathway complexity and reimbursement code availability.
- Hospitals:Emergency departments and intensive care units demand rapid turnaround for sepsis and respiratory pathogen identification. United States integrated delivery networks are unbundling instrument placement from reagent contracts, pressuring manufacturers toward competitive consumable bidding.
- Home Care:Patient self-testing bypasses clinical encounter infrastructure entirely. Direct-to-consumer subscription models for sexually transmitted infection screening are building recurring revenue outside traditional procurement, constrained by FDA validation requirements for untrained user performance.
- Clinics:Physician offices and urgent care centers bridge primary care and emergency settings.
- Research Laboratories:Academic and pharmaceutical development sites utilize investigational platforms.
Most installed capacity flows through Hospitals. Home Care is climbing the fastest as pharmacy retail channel integration accelerates.
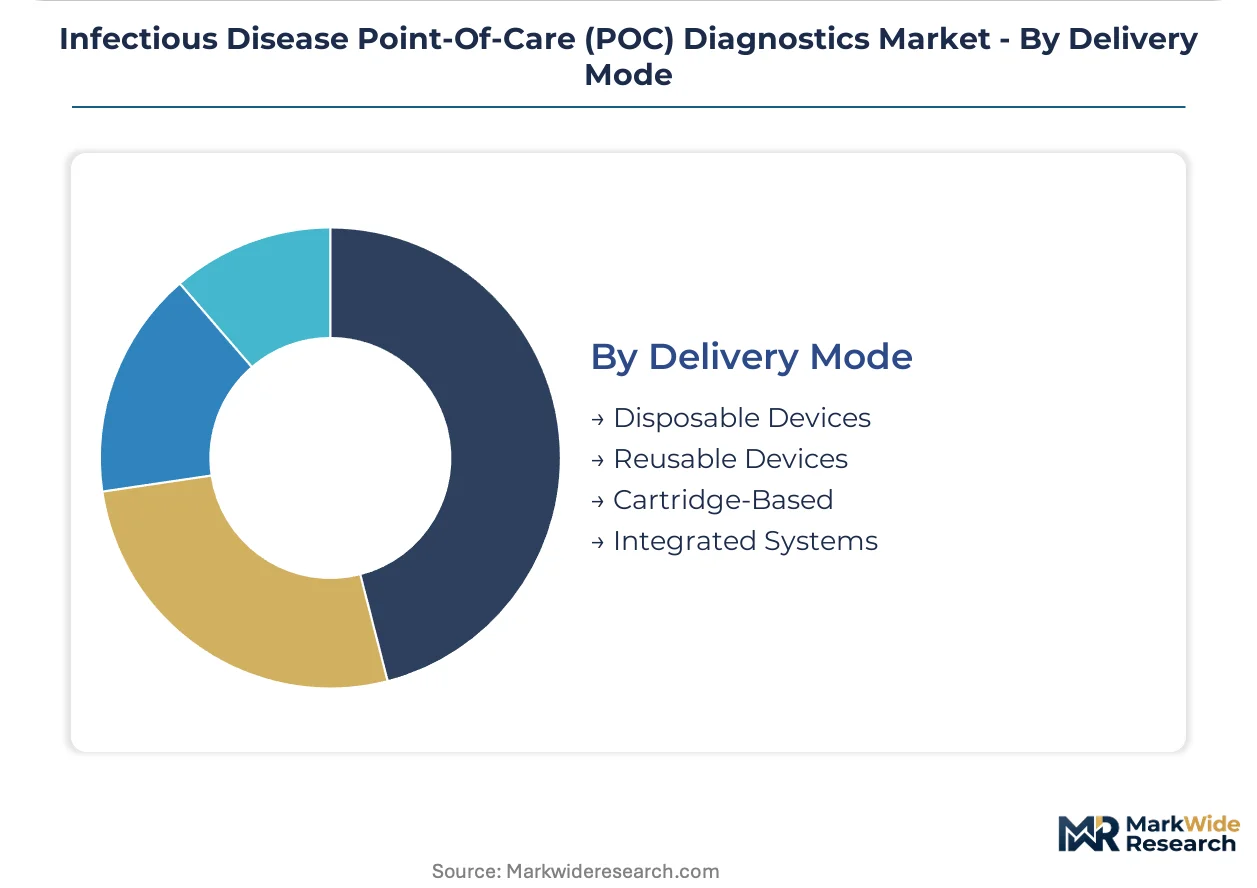
Delivery Mode:
Supply concentration varies from single-use disposables to capital-intensive integrated platforms.
- Cartridge-Based:Self-contained reagent vessels integrate sample processing, amplification, and detection in sealed formats. Manufacturing engineering talent scarcity constrains scale-up velocity for microfluidic cartridge production, particularly for combined biochemistry and regulatory compliance expertise.
- Integrated Systems:Benchtop analyzers combine instrument, software, and consumable in closed ecosystems. Hospital information system connectivity requirements across Epic, Cerner, and MEDITECH deployments fragment software development roadmaps for result transmission integration.
- Disposable Devices:Single-use lateral flow cassettes and dipsticks require no instrumentation.
- Reusable Devices:Durable instruments with replaceable reagent modules reduce per-test consumable cost.
Most installed capacity flows through Cartridge-Based formats. Integrated Systems are expanding most quickly in health system standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in the United States, Germany, and India are anchoring regional production and R&D investment for infectious disease POC diagnostics. Regulatory pathway complexity and reimbursement structures vary sharply across these geographies, fragmenting market entry sequencing for multinational manufacturers.
United States
Urgent care clinic expansion and Medicare reimbursement codes for home-based testing are accelerating patient self-testing adoption. The FDA's CLIA waiver pathway is repositioning moderate-complexity molecular tests into physician offices and retail pharmacy settings. The Boston-Cambridge corridor concentrates venture-backed diagnostic startups developing multiplex syndromic panels for emergency department deployment.
Germany
Hospital procurement committees in integrated delivery networks are unbundling instrument placement from reagent contracts, shifting toward competitive consumable bidding. The EU In Vitro Diagnostic Regulation (IVDR) is extending conformity assessment timelines for Class C and D infectious disease assays by twelve to eighteen months. The Rhine-Main region hosts notified bodies and quality management consultants serving manufacturers navigating CE marking transitions.
India
Community health centers are deploying isothermal amplification platforms under Production Linked Incentive scheme subsidies for resource-limited field settings. CDSCO regulatory harmonization with WHO prequalification standards is streamlining export-oriented manufacturing approvals. The Bangalore-Hyderabad corridor is attracting contract manufacturing investment for microfluidic cartridge production serving European and African markets.
China
Domestic manufacturers are scaling lateral flow production for respiratory pathogen screening in primary care clinics. NMPA priority review pathways for innovative diagnostic devices are compressing registration timelines for molecular platforms with domestic clinical trial data. The Yangtze River Delta concentrates nitrocellulose membrane and conjugate pad suppliers serving both domestic consumption and export demand.
United Kingdom
NHS England procurement frameworks are consolidating negotiating leverage for high-volume infectious disease testing contracts across hospital trusts. The Medicines and Healthcare products Regulatory Agency (MHRA) is operating transitional recognition arrangements for EU-authorized devices post-Brexit. The Oxford-Cambridge arc anchors academic-industry partnerships developing digital microfluidic sample-to-answer systems.
Infectious Disease Point-Of-Care (POC) Diagnostics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in infectious disease POC diagnostics. The vendor base stratifies between integrated life science conglomerates with vertically controlled supply chains and specialized diagnostic developers with concentrated assay menus. Three archetypes dominate: full-service conglomerates spanning instrument, reagent, and service ecosystems; molecular diagnostic specialists with multiplex syndromic panel differentiation; and rapid test commodity producers competing on manufacturing scale and distribution reach. Consolidation through strategic acquisitions and technology licensing partnerships represents the dominant competitive vector, alongside geographic expansion into emerging reimbursement markets.
Among diversified conglomerates, Abbott and Danaher Corporation occupy positions spanning lateral flow commodity production through premium molecular cartridge systems. Siemens Healthineers anchors the hospital emergency department installed base segment, while bioMérieux SA exemplifies the syndromic multiplex panel specialist archetype with differentiated respiratory and gastrointestinal pathogen combinations. These three companies represent contrasting strategic postures: full-stack vertical control, acute care workflow integration, and assay menu specialization respectively.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Thermo Fisher Scientific Inc |
| Danaher Corporation |
| bioMérieux SA |
| Becton, Dickinson & Company |
| Quest Diagnostics Incorporated |
| Bio-Rad Laboratories Inc |
| Others |
Supply Flow & Price Mechanics
EPA waste disposal mandates for contaminated test consumables gate qualified supply and premium-tier pricing access, forcing manufacturers to absorb compliance costs or forfeit high-margin hospital contracts. Cartridge-based molecular diagnostics command price premiums contingent on validated reverse logistics, while lateral flow producers compete on stripped-down cost structures.
Pricing Analysis
Bundled instrument-reagent contracts are unbundling into competitive consumable bidding, particularly in United States integrated delivery networks. Three-tier pricing structure across premium molecular cartridges, standard antigen cassettes, and economy dipsticks differentiates by analytical sensitivity and CLIA waiver status. Pricing pressure stems from group purchasing organization consolidation pressuring cartridge cost disclosure. Urgent care clinics exhibit highest price sensitivity; hospital emergency departments prioritize turnaround time over per-test cost.
Supply Chain Analysis
Nitrocellulose membrane supply rests on Southeast Asian specialty chemical producers in Thailand, Malaysia, and Indonesia, with conjugate pad fabrication concentrated in Chinese coastal provinces. Raw material dependencies span nitrocellulose, gold nanoparticle conjugates, and PCR-grade polymerases. Single-source vulnerability in membrane substrates creates disruption exposure from regional environmental enforcement actions. Distribution runs through pharmaceutical wholesale networks and direct hospital procurement channels, with retail pharmacy chains absorbing growing home-test volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infectious disease POC diagnostics market reads as a late-cycle quality story, with demand shifting toward multiplex syndromic panels that replace sequential single-target testing in emergency departments.
For Market Incumbents: Deploy CLIA waiver expansion as the priority lever to reposition moderate-complexity molecular platforms into physician offices and urgent care clinics. Incumbents should secure backward integration into nitrocellulose membrane production to defend against Southeast Asian supply disruptions, while investing in digital microfluidic automation to differentiate from emerging isothermal amplification entrants. Hospital procurement committee unbundling of reagent contracts represents the central margin threat requiring competitive consumable bidding capabilities. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable white-space for sexually transmitted infection screening kits outside traditional clinical procurement. New entrants should target Indian contract manufacturing under Production Linked Incentive scheme subsidies to achieve cost parity for export-oriented cartridge production. Isothermal amplification platforms for resource-limited field settings present the fastest vector for differentiation from entrenched PCR incumbents. For Investors and Strategic Acquirers: Roll-up economics work for syndromic multiplex panel specialists because hospital emergency departments are consolidating testing menus toward comprehensive pathogen coverage. Investors should frame five-to-ten year viability around regulatory clearance moats rather than manufacturing scale alone. The signal to watch is FDA Emergency Use Authorization pathway evolution for at-home molecular tests, which would trigger step-change valuation repricing for validated platform holders.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA Waiver Pathway | Expands addressable site base for molecular tests into non-laboratory clinical settings. |
| CE Marking Under IVDR | Extends conformity assessment timelines for Class C and D infectious disease assays. |
| Hospital System Partnership | Secures installed base density in emergency departments against competitive consumable bidding. |
| Software Companion Development | Resolves fragmented LIS integration across Epic, Cerner, and MEDITECH deployments. |
| Reimbursement Strategy | Captures Medicare codes for home-based testing through pharmacy retail channel integration. |
Methodological Framework
Multiple input streams — regulatory filing analysis, hospital procurement database extraction, and manufacturing cost modeling — were reconciled through bottom-up and top-down triangulation. Primary interviews with biomedical engineers, GPO contracts managers, FDA regulatory consultants, and urgent care clinic administrators were validated against secondary sources including FDA 510(k) and EUA filings, CMS Medicare reimbursement code databases, and CDSCO export approval records. Cross-referencing manufacturer capacity disclosures with customs trade data enabled supply-side calibration.
Historical volume trajectories were cross-referenced against panel input from procurement executives to anchor the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user setting, and delivery mode complexity. CAGRs were derived from regression analysis of installed base expansion rates and consumable pull-through per instrument. Forecast inputs incorporated CLIA waiver expansion timelines and IVDR transition compliance costs.
The model assumes a particular technology adoption path; alternative pathways for isothermal amplification would alter the outlook if primer design complexity yields to automated multiplex optimization. Forecasts reflect assumptions regarding regulatory harmonization between FDA and notified bodies, reimbursement code stability for home testing, and nitrocellulose supply chain resilience. A small set of named triggers — EPA enforcement escalation, GPO consolidation acceleration, and WHO prequalification pathway expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Fungal Antigens Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Antigen Kit Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Home Diagnostics Market