
 Clostridium Diagnostics Market | 2026-2036
Clostridium Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Clostridium Diagnostics Market Analysis
CLIA certification for high-complexity molecular diagnostics is rotating market access toward vendors with validated laboratory workflows. Abbott Laboratories leverages its integrated Alinity platform to sustain throughput advantages in hospital core labs. bioMérieux S.A. anchors its competitive position through specialized anaerobic culture media and complementary mass spectrometry identification systems.
Clostridium diagnostics encompasses laboratory methods for detecting toxigenic Clostridioides difficile and related anaerobic pathogens, primarily through nucleic acid amplification of toxin B genes or glutamate dehydrogenase antigen screening with reflex confirmation, operating at sensitivity thresholds below one picogram of toxin per milliliter of stool specimen. PCR technology dominates current revenue pools due to superior sensitivity over enzyme immunoassay alone, while rapid testing segments capture expanding point-of-care deployment in emergency departments seeking sub-hour turnaround. Reagents and kits constitute the consumable backbone of recurring revenue, though software segments for laboratory information system integration are gaining margin traction as health networks consolidate testing protocols.
FDA oversight of 510(k) premarket notifications and CLIA complexity classifications shapes which assay formats reach clinical laboratories, while the EU In Vitro Diagnostic Regulation enforces stricter performance validation and post-market surveillance for CE-marked products distributed in European member states. Stakeholders must monitor evolving antimicrobial stewardship mandates that tie diagnostic testing frequency to hospital reimbursement formulas.
Market Dynamics
Automated molecular platforms are compressing turnaround times for C. difficile detection while CLIA complexity classifications filter market access toward vendors with validated high-throughput workflows.
Growth Catalysts
- Medicare reimbursement incentives:Hospital-acquired infection testing policies in the United States create direct procurement pull for integrated health systems adopting multiplex PCR panels.
- Antimicrobial stewardship mandates:Tighter diagnostic testing frequency requirements tied to reimbursement formulas accelerate adoption of rapid toxin detection protocols in acute care settings.
- Mass spectrometry integration:MALDI-TOF platforms for anaerobic species identification are expanding reference laboratory capacity for clostridial speciation beyond C. difficile.
Market Restraints
- Reagent supply concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and the United States create vulnerability to single-source disruptions for NAAT kit production.
- Technical specificity limitations:Glutamate dehydrogenase antigen screening yields false-positive rates requiring reflex confirmation, extending workflow complexity and consumable costs.
- FDA 510(k) validation friction:Stricter in vitro diagnostic premarket notification requirements for modified molecular assays lengthen product development timelines by 12-18 months.
Strategic Opportunities
- Point-of-care emergency deployment:Sub-hour turnaround requirements in United States hospital emergency departments create white space for cartridge-based molecular systems outside core laboratories.
- EU MDR performance validation:Stricter post-market surveillance obligations for CE-marked devices favor established manufacturers with robust clinical evidence portfolios.
- AI-assisted susceptibility prediction:Machine learning integration with MALDI-TOF spectra is enabling preemptive resistance profiling for recurrent C. difficile management.
Industry Challenges
- Cross-training anaerobic microbiology expertise:Declining specialized technologist pipelines in clinical laboratories strain capacity for complex culture interpretation and mass spectrometry validation.
- Laboratory information system interoperability:Disparate data formats between automated identification platforms and hospital electronic health records impede real-time stewardship alert integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clostridium Diagnostics Market |
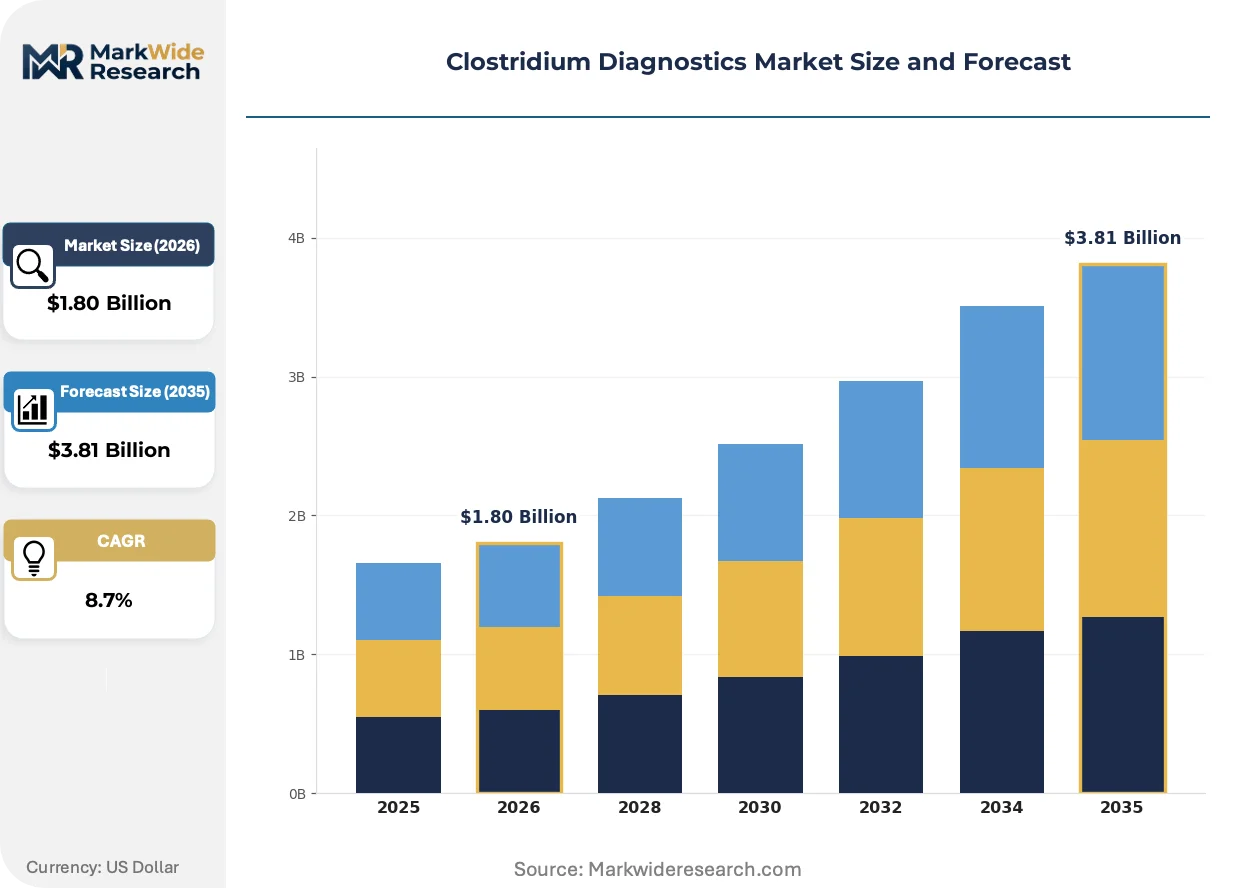
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PCR, ELISA, Culture, Rapid Testing Product Type: Reagents, Kits, Software, Accessories End User: Hospitals, Laboratories, Research Institutions, Diagnostic Centers Application: Infection Detection, Antibiotic Susceptibility Testing, Epidemiological Studies, Research |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Becton, Dickinson and Company, Siemens Healthineers AG, Beckman Coulter Inc., bioMérieux S.A., Thermo Fisher Scientific Inc., Danaher Corporation, QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clostridium Diagnostics Market Emerging Trajectories
Convergence of rapid nucleic acid detection with artificial intelligence interpretation is redefining diagnostic workflows while regulatory frameworks tighten performance validation requirements across major markets.
Loop-mediated isothermal amplification (LAMP) technology is miniaturizing clostridial detection into cartridge formats operable outside centralized laboratories. Community hospitals and urgent care networks in the United States are piloting these platforms for same-shift treatment decisions. The technology is compressing the traditional send-out model for toxin testing by embedding molecular sensitivity at the point of specimen collection.
The EU In Vitro Diagnostic Regulation enforces expanded clinical evidence requirements for CE-marked molecular assays, including post-market performance surveillance. Manufacturers must maintain updated technical documentation and periodic safety reporting to notified bodies. Small-to-mid kit vendors face disproportionate compliance burdens relative to integrated platform suppliers with dedicated regulatory affairs infrastructure.
Health system consolidation is consolidating purchasing authority into centralized laboratory networks with standardized testing menus. Independent reference laboratories face exclusion from preferred vendor agreements as integrated delivery networks negotiate exclusive supply contracts. This concentration is most visible in United States metropolitan markets where three-to-five health systems control regional inpatient capacity.
Clostridium Diagnostics Market Segmentation
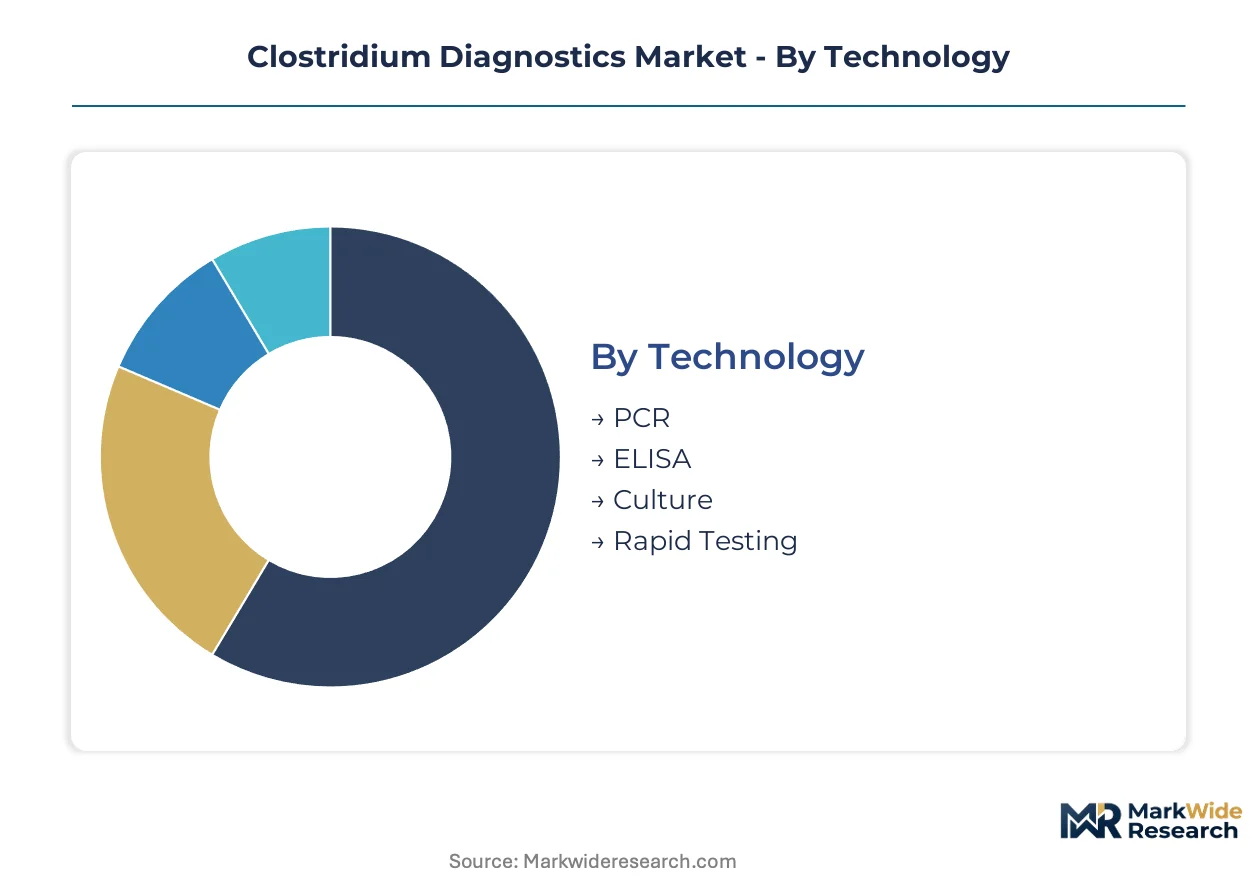
Diagnostic workflows for Clostridioides difficile span multiple technology platforms and procurement channels, each with distinct margin profiles and regulatory pathways. Understanding segment boundaries clarifies where capital deployment yields the highest returns for assay manufacturers and laboratory service providers.
Technology:
Margin pools concentrate in molecular amplification platforms where reagent recurring revenue and instrument placement cycles create durable income streams.
- PCR:Nucleic acid amplification of toxin B genes operates at sub-picogram sensitivity thresholds, making it the reference standard for hospital core laboratories. United States health systems with Medicare reimbursement incentives favor multiplex PCR panels for hospital-acquired infection surveillance, driving platform consolidation around automated high-throughput systems.
- Rapid Testing:Cartridge-based molecular and immunochromatographic formats compress turnaround to under one hour for emergency department deployment. Point-of-care adoption in United States community hospitals is accelerating as same-shift treatment decisions replace traditional send-out workflows.
- ELISA:Enzyme immunoassay for glutamate dehydrogenase antigen screening requires reflex confirmation due to false-positive rates, constraining its role to triage rather than definitive diagnosis.
- Culture:Anaerobic isolation and toxigenic culture remains essential for epidemiological typing and antimicrobial susceptibility profiling, though turnaround times of 48-72 hours limit clinical utility.
The dominant share belongs to PCR, while rapid testing is closing the gap fastest.
Product Type:
Recurring consumable revenue outpaces capital equipment sales, with software integration emerging as a margin expansion layer for consolidated laboratory networks.
- Reagents:Polymerases, fluorescent probes, and master mixes constitute the consumable backbone with 60-90 day replenishment cycles. Manufacturing concentration in Germany and the United States creates supply vulnerability that favors vendors with dual-source raw material strategies.
- Kits:Complete assay systems with pre-formulated reagents and validated protocols command premium pricing in CLIA high-complexity laboratories. FDA 510(k) clearance and EU MDR CE marking requirements filter market access toward established manufacturers with regulatory affairs infrastructure.
- Software:Laboratory information system integration modules for automated result reporting and stewardship alert generation are gaining traction as health networks consolidate testing protocols across multiple sites.
- Accessories:Pipette tips, collection containers, and transport media represent commoditized revenue with price pressure from group purchasing organizations.
Reagents capture the largest revenue base, though software is expanding most quickly as interoperability mandates tighten.
End User:
Procurement authority is concentrating into integrated delivery networks with standardized testing menus and exclusive vendor agreements.
- Hospitals:Inpatient facilities with antimicrobial stewardship programs drive the highest testing frequency, particularly for recurrent C. difficile management and infection control surveillance. United States metropolitan markets where three-to-five health systems control regional capacity are seeing preferred supplier consolidation.
- Laboratories:Reference and hospital core laboratories with automated platforms process the highest specimen volumes, with CLIA complexity classifications filtering access toward vendors with validated high-throughput workflows.
- Diagnostic Centers:Outpatient and urgent care networks are piloting point-of-care molecular platforms for same-shift results, though reimbursement parity with hospital-based testing remains uneven.
- Research Institutions:Academic medical centers with epidemiological studies and strain typing programs sustain demand for specialized culture media and mass spectrometry identification systems.
Hospitals retain the dominant procurement volume, while diagnostic centers are gaining share fastest through point-of-care expansion.
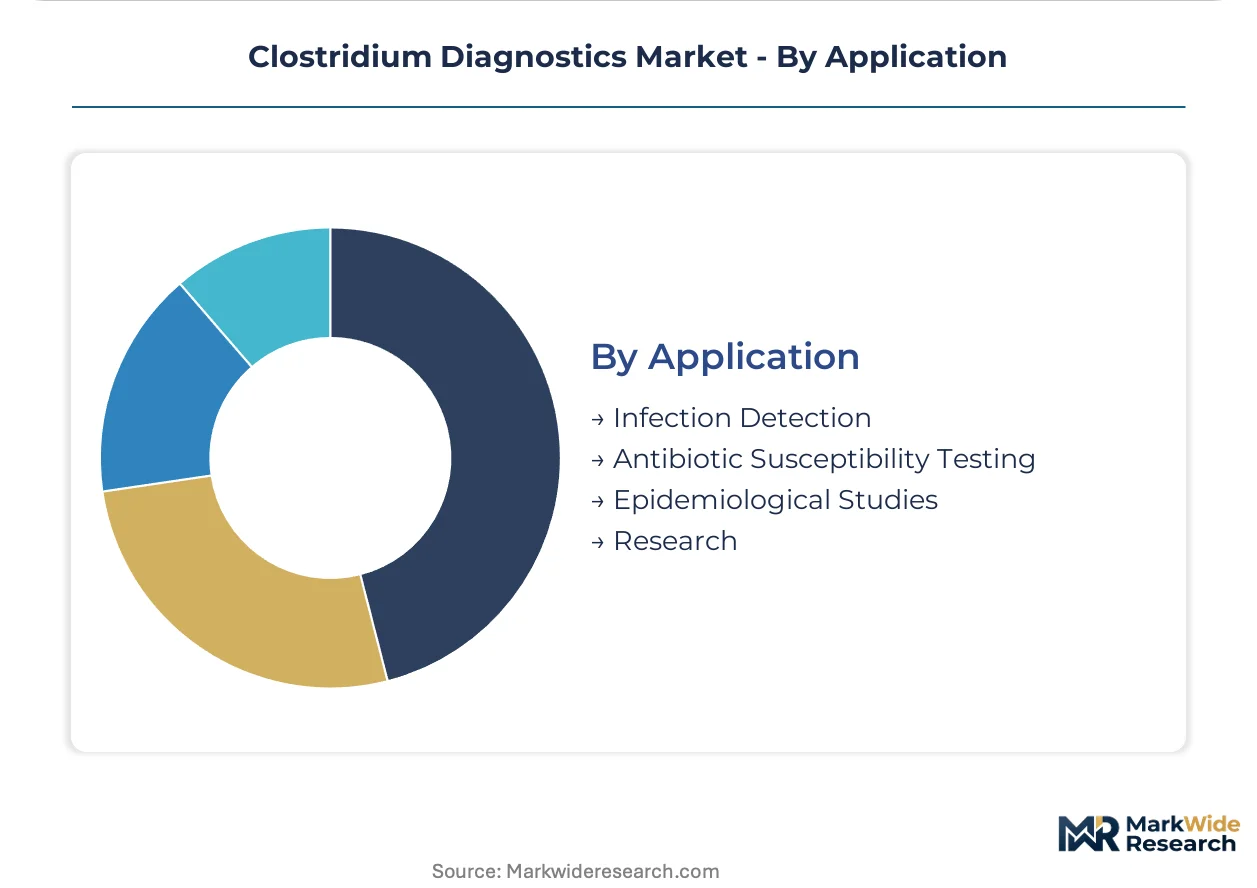
Application:
Clinical diagnostic utility commands premium pricing over research applications, with stewardship-linked reimbursement creating direct demand pull for infection detection protocols.
- Infection Detection:Toxigenic C. difficile identification in symptomatic patients represents the core revenue pool, with Medicare hospital-acquired infection policies creating direct procurement incentives for integrated United States health systems.
- Antibiotic Susceptibility Testing:MALDI-TOF mass spectrometry integration enables preemptive resistance profiling for recurrent infection management, expanding reference laboratory capacity beyond primary diagnosis.
- Epidemiological Studies:Strain typing and outbreak investigation through whole genome sequencing and ribotyping supports public health surveillance but operates on grant-funded rather than reimbursed revenue models.
- Research:Preclinical and translational studies on clostridial pathogenesis and novel therapeutics sustain niche demand for specialized reagents and culture systems.
Infection detection holds the dominant share, while antibiotic susceptibility testing is climbing the fastest as resistance profiling integrates into recurrent disease protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies for hospital-acquired infection testing in the United States create direct procurement incentives that cascade through integrated health systems. FDA enforcement of stricter 510(k) validation protocols is reshaping product development timelines across North America and Europe. Germany and the United States host concentrated polymerase manufacturing clusters that supply NAAT kit production globally.
United States
Hospital-acquired infection surveillance mandates and antimicrobial stewardship programs drive testing frequency in acute care settings. FDA 510(k) premarket notification requirements filter market access toward established IVD manufacturers with regulatory affairs infrastructure. The Boston-Cambridge corridor anchors reference laboratory capacity for specialized anaerobic identification and mass spectrometry validation.
Germany
Polymerase and fluorescent probe manufacturing clusters supply critical raw materials for molecular assay production across Europe. EU MDR post-market surveillance obligations enforce expanded clinical evidence requirements for CE-marked devices. The Rhine-Main region concentrates diagnostic reagent manufacturing with dual-source strategies mitigating supply vulnerability.
United Kingdom
NHS antimicrobial resistance strategies accelerate adoption of rapid toxin detection protocols in hospital core laboratories. MHRA alignment with EU MDR performance standards maintains regulatory continuity for IVD distribution. London's integrated delivery networks are consolidating purchasing authority through standardized testing menus and exclusive vendor agreements.
Japan
PMDA oversight of in vitro diagnostics ensures rigorous performance validation for molecular assay clearance in hospital laboratories. METI industrial policy supports domestic manufacturing of automated identification platforms. The Kanto region around Tokyo concentrates diagnostic instrument deployment with health system consolidation driving preferred supplier relationships.
France
ANSM regulation of high-complexity molecular diagnostics reinforces CLIA-equivalent certification requirements for clinical laboratories. National hospital-acquired infection surveillance programs create institutional demand for multiplex PCR panels. The Paris-Saclay cluster anchors reference laboratory networks with specialized anaerobic culture interpretation capacity.
Clostridium Diagnostics Market Vendor Landscape
Player mix skews toward diversified life science conglomerates with integrated diagnostic platforms and specialized IVD manufacturers with regulatory depth. Market structure concentrates around automated molecular systems vendors and anaerobic identification specialists. Three archetypes dominate: platform-integrated multinationals with hospital core lab presence, reagent-focused specialists with CLIA workflow validation, and rapid testing innovators targeting point-of-care deployment. Competitive moves center on exclusive supply contracting with consolidated health systems and M&A to secure complementary mass spectrometry or software capabilities.
Among platform-integrated multinationals, Abbott Laboratories and bioMérieux S.A. exemplify divergent strategic positioning. Abbott represents the automated high-throughput archetype with integrated Alinity infrastructure sustaining hospital core lab relationships. bioMérieux occupies the specialized anaerobic identification position through complementary culture media and mass spectrometry systems. Thermo Fisher Scientific Inc. sits within the diversified life science conglomerate tier with broad reagent manufacturing and instrument placement capabilities spanning reference and hospital laboratory segments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Becton, Dickinson and Company |
| Siemens Healthineers AG |
| Beckman Coulter Inc. |
| bioMérieux S.A. |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| QIAGEN N.V. |
| Others |
Supply Flow & Price Mechanics
Take-or-pay reagent supply agreements lock United States hospital laboratories into multi-year contracts with Abbott and bioMérieux, guaranteeing polymerase access while capping annual price escalations at fixed percentages. This structure concentrates procurement leverage with integrated health systems and shields them from spot-market volatility in German-manufactured fluorescent probes.
Pricing Analysis
Certification level (FDA 510(k) clearance vs. EU MDR CE marking vs. CLIA-waived status) creates the primary spread between premium automated platforms and economy rapid-test cartridges. Per-unit transactional pricing dominates consumables, while instrument placements run on subscription-like reagent rental models with minimum volume commitments. Cost compression in the economy rapid-test tier is intensifying because urgent care networks negotiate group purchasing discounts for point-of-care deployment. Diagnostic centers exhibit the highest price sensitivity due to reimbursement gaps with hospital-based testing, whereas integrated delivery networks prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs from Rhine-Main manufacturing clusters to United States distribution hubs have risen with container availability constraints on trans-Atlantic lanes. Polymerase and fluorescent probe production concentrates in Germany and the United States, with master-mix formulation drawing from specialty chemical suppliers in Switzerland and Japan. Single-source vulnerability in thermostable enzyme manufacturing creates exposure to regulatory inspection delays at FDA-registered facilities. Distribution runs through regional laboratory distributors with cold-chain capabilities, consolidating last-mile delivery to hospital core laboratories and reference networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Clostridium diagnostics market is entering a cyclical recovery phase as hospital capital expenditure budgets rebound from post-pandemic austerity and antimicrobial stewardship mandates renew testing frequency requirements.
For Market Incumbents: Secure exclusive supply contracts with consolidating United States integrated delivery networks before preferred vendor windows close. Defend against point-of-care disintermediation by embedding AI-assisted result interpretation into core laboratory platforms, and deepen backward integration into polymerase manufacturing to mitigate German supply concentration risk. For New Entrants and Emerging Players: Anchor in the diagnostic center segment where reimbursement parity gaps have slowed incumbent penetration and same-shift turnaround requirements outstrip current rapid-test performance. Target community hospital emergency departments with cartridge-based LAMP systems, and pursue CLIA waiver pathways to bypass high-complexity laboratory certification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale reagent specialists with validated EU MDR technical documentation and established notified body relationships, as compliance burdens disproportionately strain smaller kit vendors. The long-term viability window favors platform-agnostic software modules for laboratory information system integration. Watch FDA 510(k) clearance timelines for modified molecular assays as the signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Pathway Pursuit | Unlocks point-of-care deployment in United States urgent care networks seeking sub-hour turnaround. |
| EU MDR Technical Documentation Investment | Preserves CE-marked market access as notified bodies enforce expanded clinical evidence requirements. |
| Hospital System Partnership | Secures preferred supplier status within consolidating integrated delivery networks with standardized menus. |
| Software Companion Development | Enables stewardship alert integration with hospital electronic health records for antimicrobial programs. |
| Reimbursement Strategy Formulation | Aligns test menu design with Medicare hospital-acquired infection surveillance incentive structures. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, CLIA compliance officers, antimicrobial stewardship program leads, and diagnostic reagent procurement managers at group purchasing organizations. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up testing volume estimates were triangulated against top-down health system expenditure data.
Across the analysis window, the forecasting framework modeled technology platform adoption curves, product type replenishment cycles, end-user procurement concentration patterns, and application-specific reimbursement linkages. CAGRs were derived from segment-level volume projections and pricing trajectory assumptions, incorporating antimicrobial stewardship mandate implementation timelines and health system consolidation patterns as structural drivers.
Decision-makers should treat outputs as directional under base assumptions of sustained Medicare reimbursement incentives and stable CLIA regulatory frameworks; material deviation would warrant model refresh. Specific risk factors include FDA enforcement discretion shifts, EU MDR notified body capacity constraints, and polymerase supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Population Screening Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market