
 Antigen Kit Market | 2026-2036
Antigen Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Antigen Kit Market Outlook
EU IVDR compliance is broadening the cost-of-entry calculus for manufacturers seeking CE marking on self-test antigen products. Abbott Laboratories leverages its vertically integrated immunoassay manufacturing footprint to sustain price competitiveness across European tenders. Roche Diagnostics anchors its position through proprietary digital reader ecosystems that differentiate workflow efficiency in hospital laboratories. SD Biosensor competes aggressively on volume scale in emerging procurement markets across Southeast Asia and Latin America.
An antigen kit is a diagnostic consumable containing monoclonal or polyclonal antibodies immobilized on a nitrocellulose membrane or polystyrene microplate, designed to detect specific pathogen-associated proteins through antibody-antigen binding reactions with visual or fluorometric readout. Rapid Test Kits and Lateral Flow Devices dominate current procurement volumes due to their minimal equipment requirements and suitability for decentralized settings, though Multiplex Assays are capturing margin pools as health systems prioritize panel-based respiratory screening. ELISA Kits retain stable demand in research laboratories and blood bank screening protocols where quantitative sensitivity thresholds remain non-negotiable.
FDA Emergency Use Authorization pathways and EU IVDR notified body oversight collectively determine market access timelines and post-market surveillance obligations for antigen kit manufacturers. ISO 13485 quality management certification functions as a baseline procurement filter across OECD health systems, with WHO prequalification extending addressable demand into low-income country tenders. Stakeholders must monitor evolving WHO Essential Diagnostics List revisions and national self-test reimbursement decisions as these frameworks will determine which product formats achieve sustainable volume scale.
Market Dynamics
EU IVDR's expanded technical documentation requirements are compressing margins for mid-tier manufacturers while accelerating consolidation among notified body capacity. The shift from directive-based to regulation-based conformity assessment has extended approval timelines and concentrated certification power among a shrinking pool of designated bodies.
Growth Catalysts
- WHO Essential Diagnostics List expansion:Inclusion of SARS-CoV-2 and influenza rapid tests in the 2023 EDL revision unlocks multilateral procurement channels for lateral flow manufacturers. Gavi and Global Fund tenders now prioritize prequalified antigen products.
- Decentralized testing infrastructure:China's municipal health bureaus in tier-two cities are deploying 15-minute testing circles using self-administered kits. Local government procurement budgets for respiratory screening doubled in fiscal 2024.
- Over-the-counter regulatory pathways:FDA's streamlined Emergency Use Authorization for home-use diagnostics eliminates prescription barriers. Retail pharmacy chains now stock multiplex respiratory panels alongside seasonal flu kits.
Market Restraints
- Nitrocellulose membrane supply concentration:Three Asian suppliers control 70% of high-purity membrane substrate for lateral flow devices. Geopolitical friction or export restrictions would cascade through manufacturing schedules.
- IVDR notified body bottleneck:Only 12 designated bodies exist for the full scope of self-test device certification. Queue times now exceed 18 months for new product submissions.
- PCR sensitivity threshold substitution:Hospital laboratories retain quantitative PCR as the gold standard for low-titer detection. Antigen kits face displacement risk in settings where analytical sensitivity remains paramount.
Strategic Opportunities
- Multiplex respiratory panel adoption:Simultaneous SARS-CoV-2, influenza A/B, and RSV detection on single devices commands 40% price premiums over single-analyte formats. European hospital procurement is shifting toward panel-based screening protocols.
- Digital reader ecosystem integration:Smartphone-connected lateral flow readers with automated result interpretation address home-user error rates. Bluetooth-enabled devices qualify for remote patient monitoring reimbursement codes in Germany.
- India's PLI scheme for diagnostics:Production-linked incentives cover 5% of eligible capital expenditure for domestic antigen kit manufacturing. State-level medical device parks in Gujarat and Telangana offer additional land and tax concessions.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system auditors command premium consulting rates. Small manufacturers face 12-18 month delays in certification renewal cycles.
- Lateral flow reader firmware validation:Software-as-medical-device classification under EU IVDR requires cybersecurity documentation and post-market surveillance. Development timelines extend by 8-10 months for connected diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antigen Kit Market |
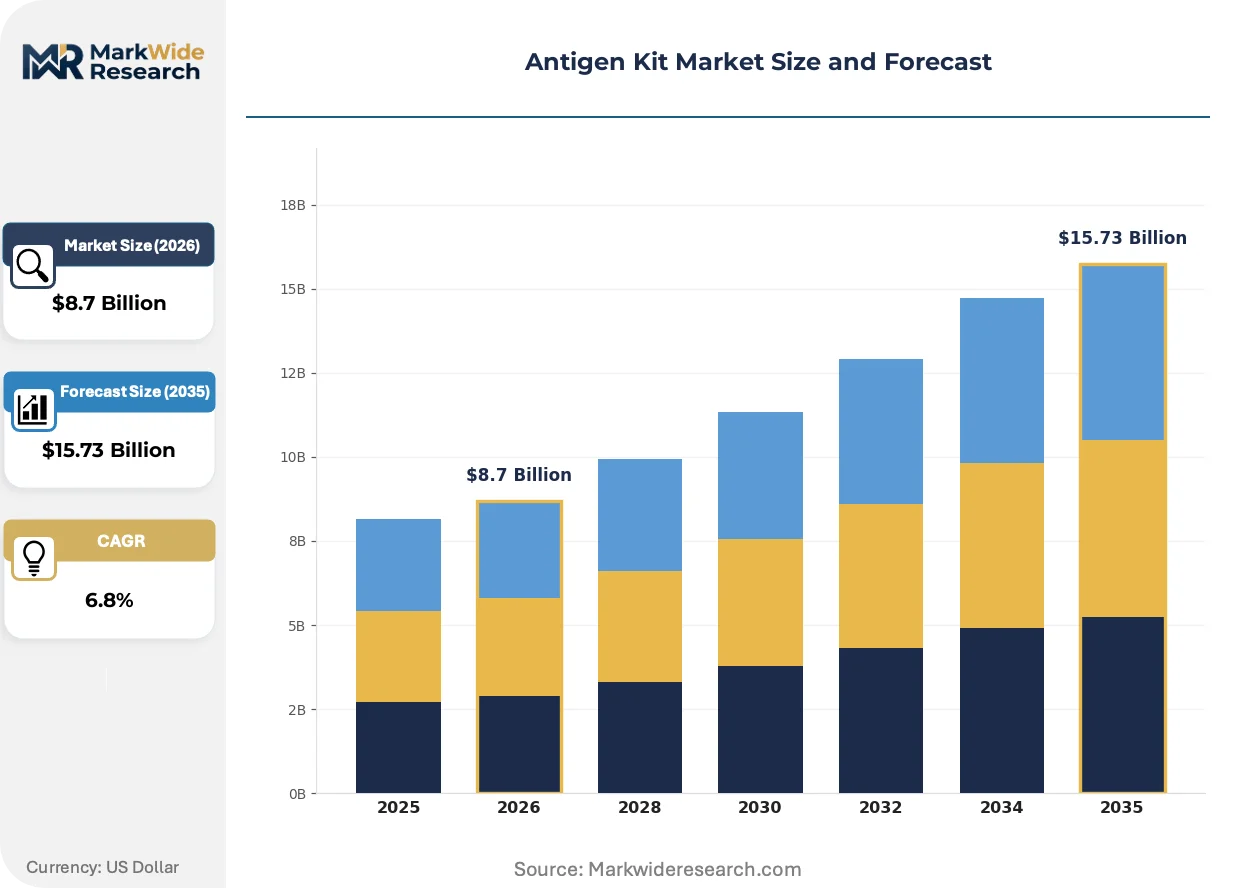
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, ELISA Kits, Lateral Flow Devices, Multiplex Assays Application: Infectious Diseases, Autoimmune Disorders, Cancer Diagnosis, Allergy Testing End User: Hospitals, Clinics, Research Laboratories, Home Care Technology: Immunoassay, Microfluidics, Molecular Diagnostics, Biosensors |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Becton, Dickinson and Company, Quidel Corporation, SD Biosensor, Thermo Fisher Scientific, Mylab Discovery Solutions, PerkinElmer, GenBody, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antigen Kit Market Strategic Shifts
Fluorescent nanoparticle reporters and machine-vision readout systems are displacing colloidal gold visual interpretation in premium diagnostic segments. The convergence of materials science and consumer electronics is redefining performance benchmarks for point-of-care testing.
Quantum dot nanocrystal technology delivers 10-100x signal intensity versus conventional gold conjugates. Reference laboratories in Japan and South Korea are validating fluorometric lateral flow for quantitative troponin and D-dimer applications. This enhanced sensitivity is converging with smartphone camera-based quantification to enable laboratory-grade precision in decentralized settings.
EU IVDR's post-market surveillance requirements now mandate annual safety reporting and periodic safety update reports for self-test devices. Manufacturers must maintain vigilance systems with dedicated qualified persons for regulatory compliance. Smaller kit producers without European legal entities are outsourcing pharmacovigilance to specialized contract organizations, adding 8-12% to regulatory operating costs.
Hospital procurement committees are unbundling rapid test supply from analyzer service contracts, creating direct-to-manufacturer purchasing channels. Group purchasing organizations in France and Italy now run competitive tenders for respiratory antigen panels separate from automated platform agreements. This disintermediation is most pronounced in academic medical centers with dedicated point-of-care testing committees and independent quality validation capabilities.
Antigen Kit Market Segmentation
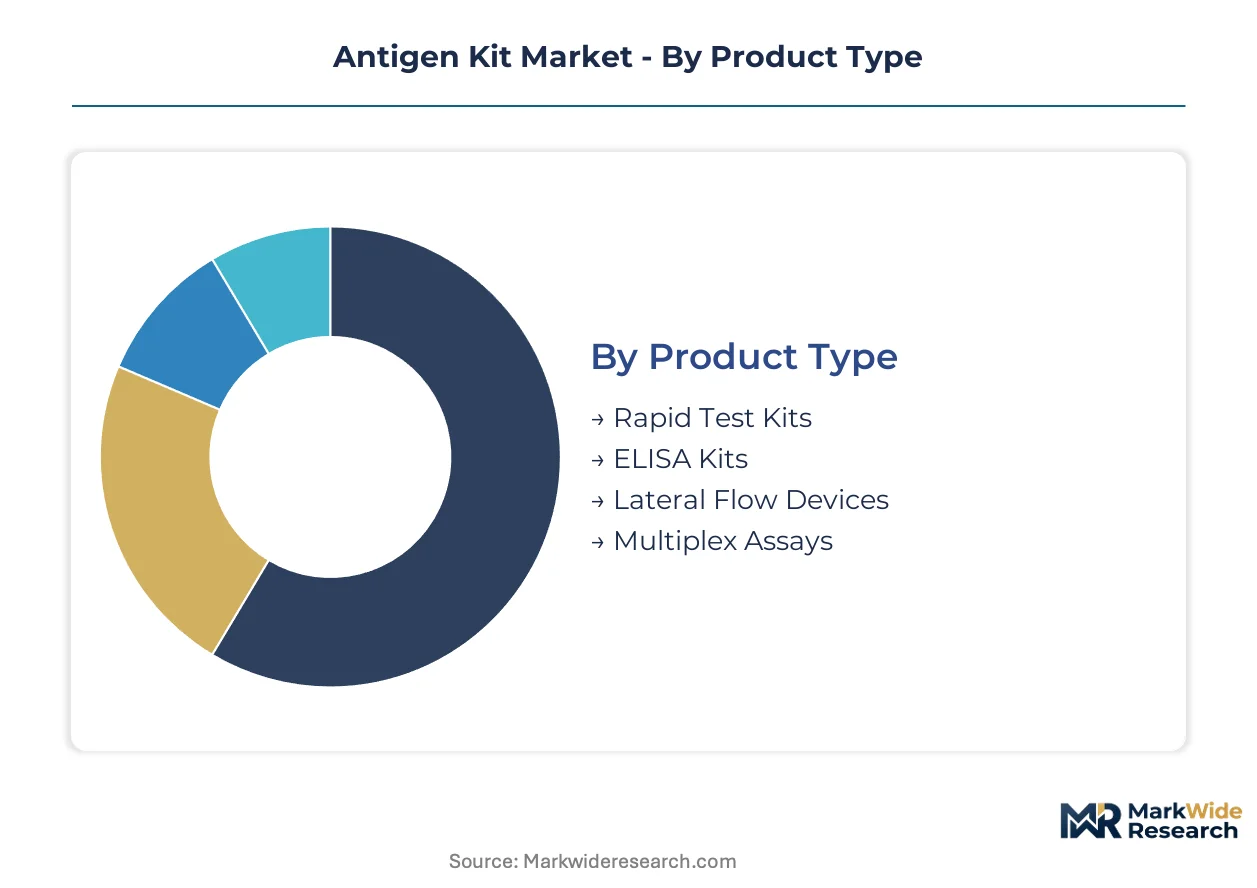
Antigen kit procurement patterns diverge sharply across use environments, with hospital laboratories prioritizing quantitative sensitivity while decentralized settings trade analytical performance for speed and minimal equipment requirements. Manufacturers must configure product portfolios across four distinct segmentation axes to capture volume in divergent channel economics.
Product Type:
Replacement cycles accelerate where digital readout integration and multiplex panel expansion create upgrade pressure against installed base of single-analyte visual formats.
- Rapid Test Kits:Colloidal gold or latex bead conjugates on nitrocellulose strips deliver results within 15 minutes without auxiliary equipment. India's tier-two municipal health bureaus are scaling procurement for respiratory screening at sub-center level, though batch-to-batch variability constrains WHO prequalification rates.
- Lateral Flow Devices:Capillary-driven fluidics on porous membranes support smartphone-connected quantification through fluorometric or colorimetric signal amplification. China's 15-minute testing circle infrastructure in Chengdu, Wuhan, and Xi'an anchors regional demand concentration for self-administered formats with Bluetooth result transmission.
- ELISA Kits:Microplate-based enzyme-linked immunosorbent assays with spectrophotometric readout maintain dominance in blood bank screening and research protocols requiring picogram-level sensitivity thresholds.
- Multiplex Assays:Simultaneous detection of SARS-CoV-2, influenza A/B, and RSV on single cartridges commands procurement premiums in European hospital tender frameworks prioritizing panel-based respiratory triage.
Lateral Flow Devices sit at the top of the volume ranking, with Multiplex Assays climbing the fastest.
Application:
Cost tier stratification separates premium quantitative formats in reference laboratories from economy visual strips in community screening programs.
- Infectious Diseases:Respiratory pathogen panels and sexually transmitted infection screening dominate procurement volumes, with Gavi and Global Fund tenders channeling prequalified products into low-income country distribution networks. FDA Emergency Use Authorization pathways for over-the-counter SARS-CoV-2 diagnostics eliminated prescription barriers in US retail pharmacy channels.
- Autoimmune Disorders:Anti-nuclear antibody and rheumatoid factor detection kits serve rheumatology clinics and reference laboratories with moderate throughput requirements, though ELISA retention in this segment resists lateral flow displacement due to titer quantification needs.
- Cancer Diagnosis:Tumor-associated antigen detection for AFP, CEA, and PSA monitoring occupies niche procurement in oncology centers with integrated immunoassay analyzers.
- Allergy Testing:Specific IgE detection panels for food and environmental allergen screening concentrate in pediatric allergy clinics and occupational health programs in Germany and France.
Infectious Diseases commands the dominant procurement share, while Cancer Diagnosis shows the steepest expansion trajectory in companion diagnostic protocols.
End User:
Customer type determines pricing tolerance and regulatory documentation burden, with hospital procurement committees unbundling rapid test supply from analyzer service contracts.
- Hospitals:Acute care settings demand quantitative sensitivity and LIS connectivity, driving preference for analyzer-based immunoassays over visual lateral flow in laboratory medicine departments. Academic medical centers in France and Italy operate independent point-of-care testing committees with direct-to-manufacturer purchasing authority.
- Clinics:Primary care and urgent care settings prioritize 10-15 minute turnaround for respiratory triage, with India's Ayushman Bharat health and wellness centers scaling lateral flow procurement for tuberculosis and malaria screening.
- Research Laboratories:Investigational use and biomarker validation studies sustain stable ELISA and multiplex bead array demand with stringent lot-to-lot consistency requirements.
- Home Care:Self-administered kits with simplified specimen collection and automated result interpretation are gaining reimbursement traction under Germany's digital health application framework for remote patient monitoring.
Hospitals retain the largest procurement volume, with Home Care gaining share fastest as over-the-counter regulatory pathways mature.
Technology:
Supply concentration in membrane substrates and conjugate manufacturing shapes competitive positioning across technology platforms.
- Immunoassay:Antibody-antigen binding reactions with enzymatic, fluorescent, or particle-based signal generation constitute the foundational technology layer, with monoclonal antibody specificity determining commercial differentiation.
- Microfluidics:Laminated plastic cartridges with precision-molded channels enable sample preparation integration and reagent on-board storage, reducing operator skill requirements in decentralized settings.
- Molecular Diagnostics:Isothermal amplification with antigen detection readout hybrids are emerging in tuberculosis and COVID-19 screening programs requiring sensitivity bridging between PCR and conventional lateral flow.
- Biosensors:Electrochemical and optical transducers with surface plasmon resonance or field-effect transistor architectures enable label-free detection with real-time kinetic monitoring in research and reference applications.
Immunoassay dominates installed base and procurement volume, while Microfluidics is expanding most quickly through cartridge-based platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized immunoassay manufacturing talent clusters in Germany, the United States, China, India, and Japan anchor regional production capabilities and shape procurement patterns across diagnostic value chains.
United States
Hospital procurement committees at academic medical centers in Boston and the Research Triangle unbundle rapid test supply from analyzer service contracts. FDA Emergency Use Authorization pathways for over-the-counter diagnostics compress approval timelines for home-use respiratory panels. The San Francisco Bay Area and San Diego corridor host venture-backed startups developing smartphone-connected lateral flow readers.
Germany
Bluetooth-enabled lateral flow devices qualify for remote patient monitoring reimbursement codes under the digital health application framework. BfArM and PEI oversight maintains stringent post-market surveillance requirements for self-test devices. The Munich and Frankfurt Rhine-Main clusters concentrate notified body capacity and contract research organizations serving IVDR compliance needs.
China
Municipal health bureaus in Chengdu, Wuhan, and Xi'an deploy 15-minute testing circles using self-administered kits with Bluetooth result transmission. NMPA regulatory harmonization with international standards accelerates import substitution in high-purity nitrocellulose membrane manufacturing. The Yangtze River Delta anchors precision molding capabilities for microfluidic cartridge production.
India
Ayushman Bharat health and wellness centers scale lateral flow procurement for tuberculosis and malaria screening at sub-center level. The PLI scheme for diagnostics covers five percent of eligible capital expenditure for domestic antigen kit manufacturing. State-level medical device parks in Gujarat and Telangana offer land and tax concessions to anchor contract manufacturers.
Japan
Reference laboratories in Tokyo and Osaka validate fluorometric lateral flow for quantitative troponin and D-dimer applications bridging to PCR sensitivity thresholds. PMDA quality management system requirements align with MHLW reimbursement decisions for point-of-care testing. The Kansai region maintains specialized conjugate manufacturing capabilities for nanoparticle reporter production.
Antigen Kit Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three strategic archetypes: vertically integrated multinationals with captive antibody production, regional scale specialists serving tender markets, and technology licensors monetizing assay patents. Consolidation pressure intensifies as IVDR compliance costs and notified body queue times favor balance sheet depth. Dominant competitive moves include backward integration into membrane substrate manufacturing and geographic expansion through distributor acquisitions in Southeast Asia and Latin America.
Among diversified healthcare conglomerates, Abbott Laboratories and Roche Diagnostics exemplify archetypes of manufacturing scale and digital ecosystem integration respectively. SD Biosensor occupies a position representing regional volume specialists competing aggressively on procurement tenders. Thermo Fisher Scientific anchors the research and reference laboratory tier through consumable and platform bundling strategies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Becton, Dickinson and Company |
| Quidel Corporation |
| SD Biosensor |
| Thermo Fisher Scientific |
| Mylab Discovery Solutions |
| PerkinElmer |
| GenBody |
| Others |
Value Chain & Pricing Dynamics
Specialized immunoassay manufacturing talent clusters in Germany and the United States anchor labor-cost differentials that widen pricing-tier spreads between premium digital-reader ecosystems and economy visual-strip formats. IVDR compliance investments and notified body queue premiums concentrate in European production bases, compressing margins for mid-tier manufacturers while Asian contract manufacturers capture volume procurement in emerging tenders.
Pricing Analysis
Hospital procurement committees increasingly unbundle rapid test supply from analyzer service contracts, fragmenting historical pricing power held by integrated platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-connected multiplex panels from single-analyte visual strips and bulk tender commodities. Cost compression in economy tiers intensifies because nitrocellulose membrane supply concentrates among three Asian suppliers. Municipal health bureaus in China's tier-two cities exhibit highest price sensitivity, while European academic medical centers with independent validation capabilities tolerate premium positioning for quantitative sensitivity.
Supply Chain Analysis
Reverse-logistics flows for expired or defective lateral flow devices remain underdeveloped across emerging procurement markets, creating compliance liabilities for distributors without temperature-controlled recall infrastructure. High-purity nitrocellulose membrane manufacturing concentrates in China, Japan, and South Korea, with precision molding for microfluidic cartridges anchored in the Yangtze River Delta. Raw material dependencies span antibody conjugates, fluorometric nanoparticles, and polystyrene microplates. Single-source vulnerability in membrane substrate exposes manufacturing schedules to export restriction cascades. Distribution runs through group purchasing organizations in France and Italy, direct-to-manufacturer channels at academic medical centers, and state-level tenders in India's Ayushman Bharat network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme covers five percent of eligible capital expenditure for domestic manufacturing, while EU IVDR compliance costs and eighteen-month notified body queues erect barriers against European entrants. The cost differential between Indian production-linked incentives and European regulatory overhead creates manufacturing relocation pressure.
For Market Incumbents: Anticipate displacement risk from PCR sensitivity thresholds in hospital laboratory settings by deepening fluorometric lateral flow capabilities that bridge to quantitative troponin and D-dimer applications. Backward integration into nitrocellulose membrane substrate manufacturing defends margin position against supply concentration among three Asian suppliers. Prioritize WHO prequalification investment to capture Gavi and Global Fund tender volumes in low-income country distribution networks. For New Entrants and Emerging Players: Distributor partnerships in Southeast Asia and Latin America offer the most penetrable white-space targets, as SD Biosensor and regional volume specialists have not fully captured municipal health bureau procurement in tier-two cities. India's state-level medical device parks in Gujarat and Telangana present manufacturing footprint opportunities under PLI scheme coverage. Target home care segments with smartphone-connected lateral flow readers qualifying for Germany's remote patient monitoring reimbursement codes. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with captive antibody production are the most active acquirer in this space, seeking notified body relationships and IVDR technical documentation capabilities. The long-term viability window favors targets with established WHO prequalification and emerging market tender track records. Monitor FDA Emergency Use Authorization pathway expansions for over-the-counter respiratory panels as inflection indicators for home care segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR notified body relationships compress eighteen-month queue times for self-test device certification. |
| Backward Integration | In-house nitrocellulose membrane production insulates manufacturing schedules from Asian supplier export restrictions. |
| Hospital System Partnership | Academic medical centers in France and Italy unbundle rapid test supply from analyzer service contracts. |
| Software Companion Development | Bluetooth-enabled lateral flow readers qualify for Germany's digital health application reimbursement framework. |
| Reimbursement Strategy | WHO prequalification unlocks Gavi and Global Fund procurement channels in low-income country tenders. |
Study Parameters
Bottom-up hospital and home care procurement modeling reconciled against top-down antibody conjugate and membrane substrate manufacturing tracking forms the analytical core. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies combined with secondary validation from FDA Emergency Use Authorization filings, EU IVDR technical documentation databases, WHO prequalification records, and hospital procurement databases. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Historical trendline analysis of lateral flow device procurement volumes and multiplex panel adoption rates informs projection trajectories across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology platform, with regional regulatory cluster and reimbursement framework status as cross-cutting variables. CAGRs derive from growth rate convergence between bottom-up channel build and top-down manufacturing capacity expansion. Forecast inputs incorporate PLI scheme utilization rates and IVDR notified body capacity constraints.
Revisions become necessary when FDA Emergency Use Authorization pathways expand or contract, WHO Essential Diagnostics List revisions alter prequalification priorities, or nitrocellulose membrane export restrictions materialize. Forecasts reflect assumptions about regulatory harmonization timelines and municipal health bureau budget allocations. Practitioners should monitor FDA over-the-counter diagnostic pathway announcements, WHO EDL revision cycles, and Indian PLI scheme disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market