
 Viral Disease Diagnosis Market | 2026-2036
Viral Disease Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Disease Diagnosis Market Analytics
Diagnostic laboratories is bifurcating demand from hospital core labs as outpatient testing volumes surge. Abbott Laboratories leverages its installed base of rapid molecular platforms to sustain channel control in decentralized settings. Thermo Fisher Scientific anchors high-throughput sequencing workflows for epidemiological surveillance programs. F. Hoffmann-La Roche Ltd competes on automated sample-to-answer systems that reduce operator dependency in mid-volume sites.
Viral disease diagnosis encompasses the detection and characterization of pathogenic viruses through biochemical, molecular, or immunological methods, typically requiring nucleic acid amplification with sensitivity thresholds below 100 copies per milliliter or antigen binding with defined specificity cutoffs. Its primary purpose is to enable clinical treatment decisions, public health containment, and blood safety verification. Molecular tests command premium pricing due to multiplexing capabilities that simultaneously identify respiratory and bloodstream pathogens. Rapid diagnostics occupy the fastest-expanding margin pool as point-of-care settings prioritize turnaround time over comprehensive pathogen profiling. NGS technology leads investment intensity among instrument manufacturers despite slower clinical adoption curves.
FDA emergency use authorization pathways shape product development timelines and commercial access for novel assays, while the Clinical Laboratory Improvement Amendments govern test complexity classifications that determine where technologies deploy. The EU In Vitro Diagnostic Regulation imposes stricter performance documentation requirements that filter market entrants across European member states. Stakeholders must monitor evolving reimbursement codes for multiplex respiratory panels as payors recalibrate coverage toward outcomes-based criteria.
Market Dynamics
Molecular multiplexing is compressing turnaround times below 90 minutes while FDA emergency use authorization pathways compress assay validation cycles from years to months, fundamentally restructuring competitive positioning between centralized laboratories and point-of-care sites.
Growth Catalysts
- CLIA Complexity Waivers:The Clinical Laboratory Improvement Amendments permit moderately complex testing in physician office laboratories, expanding molecular platform placement beyond hospital core labs into ambulatory settings.
- Respiratory Panel Reimbursement:Medicare coverage determinations for multiplex respiratory pathogen detection create predictable revenue streams that justify capital expenditure on automated sample-to-answer systems.
- Epidemiological Surveillance Mandates:WHO International Health Regulations compel national health agencies to maintain sequencing capacity for novel pathogen identification, sustaining demand for high-throughput NGS infrastructure.
Market Restraints
- Reagent Supply Concentration:Polymerase and reverse transcriptase enzyme production concentrates among three contract manufacturers, creating vulnerability to single-source disruption.
- EU IVDR Documentation Burden:The In Vitro Diagnostic Regulation requires clinical evidence packages that extend time-to-market by 18-24 months for novel assay developers without notified body relationships.
- Lateral Flow Substitution:Antigen-based rapid diagnostics capture outpatient volume for influenza and SARS-CoV-2, constraining molecular test pricing power in low-acuity settings.
Strategic Opportunities
- At-Home Molecular Testing:Prescription-authorized self-collection kits for sexually transmitted infections open direct-to-patient channels bypassing traditional laboratory intermediaries.
- AI-Assisted Variant Calling:Machine learning algorithms trained on genomic databases are converging with cloud-based bioinformatics pipelines to automate phylogenetic classification without specialist intervention.
- India PLI Scheme:The Production Linked Incentive scheme for medical devices subsidizes domestic manufacturing of diagnostic reagents, reducing import dependency for Southeast Asian distributors.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories struggle to recruit computational biologists capable of validating variant interpretation pipelines under CAP accreditation standards.
- Interoperability Friction:Proprietary data formats from instrument manufacturers impede integration with hospital electronic health record systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Disease Diagnosis Market |
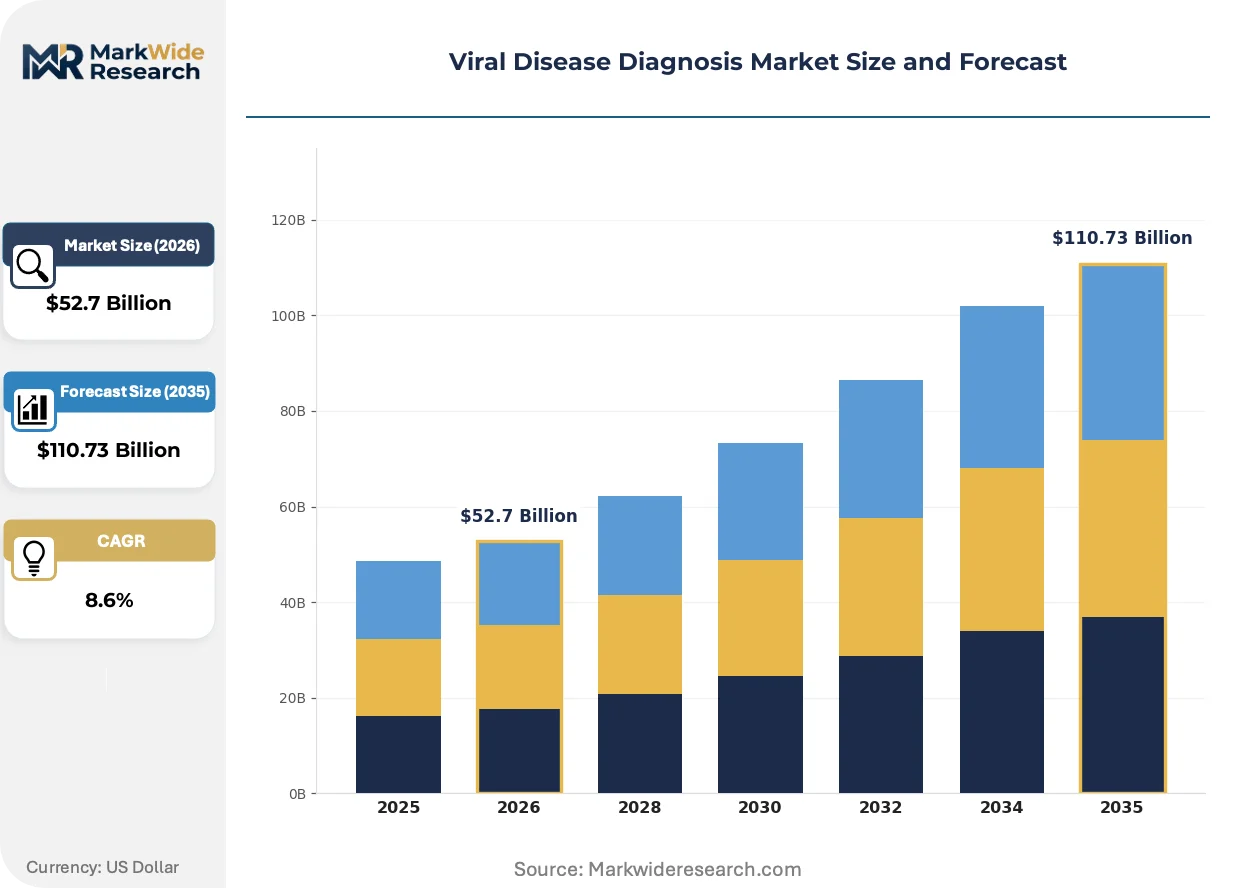
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serological Tests, Molecular Tests, Antigen Tests, Rapid Diagnostics End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Technology: PCR, ELISA, Immunoassays, NGS Application: Infectious Disease Screening, Blood Screening, Epidemic Surveillance, Travel Health |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, BioMérieux SA, Becton, Dickinson and Company, Danaher Corporation, QIAGEN N.V., Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Disease Diagnosis Market Evolving Landscape
Digital PCR platforms are compressing limit-of-detection thresholds while regulatory frameworks accelerate decentralized authorization, creating divergence between high-complexity reference laboratories and distributed testing networks.
CRISPR-based diagnostics is displacing conventional nucleic acid amplification in outbreak response scenarios. Field epidemiology teams in sub-Saharan Africa deploy SHERLOCK and DETECTR assays without cold-chain logistics. The technology is displacing quantitative PCR for resource-limited settings where thermocycler infrastructure remains unavailable.
The EU Medical Device Regulation imposes post-market surveillance obligations that require manufacturers to submit periodic safety reports for all class C and D IVDs. European notified bodies have reduced active certificates by 40% since 2021, filtering market entrants toward established quality management systems. Mid-volume laboratories in Germany and France delay platform procurement decisions pending MDR transition completion.
Hospital procurement committees now unbundle instrument placement from reagent supply agreements, demanding competitive bidding on consumables independent of capital equipment vendors. Group purchasing organizations negotiate multi-year sole-source contracts that lock out secondary suppliers. This pattern concentrates in the United States where health system consolidation has reduced independent laboratory purchasing autonomy.
Viral Disease Diagnosis Market Segmentation
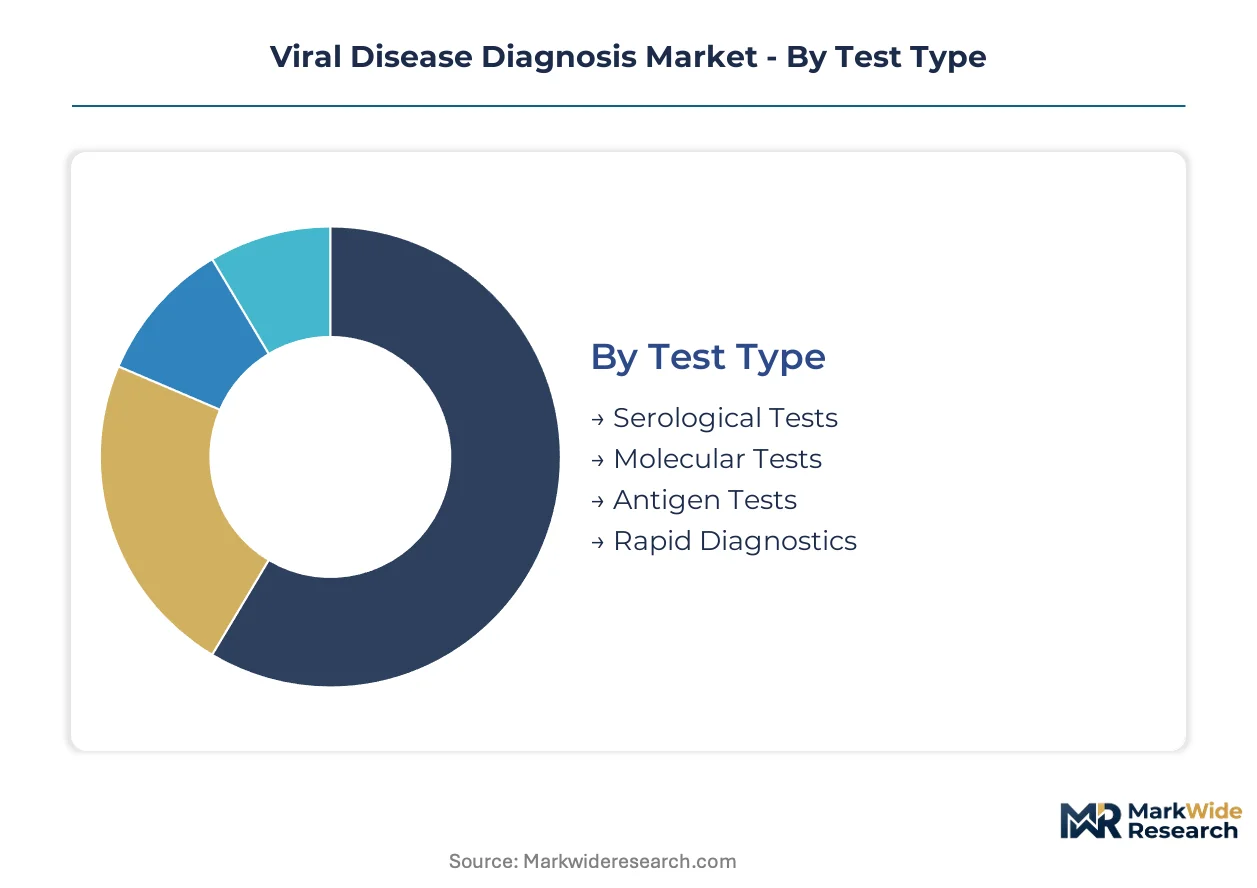
Segmentation in viral disease diagnosis reveals how margin pools migrate between centralized high-complexity laboratories and distributed point-of-care networks. Technology choices determine reimbursement pathways, while end-user concentration shapes procurement leverage and platform loyalty.
Test Type:
Margin pools concentrate in molecular multiplexing capabilities that command premium pricing for simultaneous pathogen identification.
- Molecular Tests:Nucleic acid amplification platforms achieve sensitivity below 100 copies per milliliter through quantitative PCR or isothermal methods. Demand concentrates in hospital core laboratories and large reference networks where CLIA high-complexity certification enables comprehensive respiratory and bloodstream pathogen panels under favorable Medicare reimbursement.
- Rapid Diagnostics:Lateral flow and cartridge-based systems deliver results within 30 minutes at point-of-care sites. Physician office laboratories and urgent care chains in the United States drive volume as CLIA-waived complexity classifications expand placement beyond traditional laboratory infrastructure.
- Serological Tests:Antibody detection assays identify past immune response through ELISA or chemiluminescence platforms.
- Antigen Tests:Direct pathogen protein detection offers intermediate sensitivity with minimal equipment requirements.
Molecular Tests hold installed capacity. Rapid Diagnostics is rotating up the share rankings.
End User:
Procurement concentration determines pricing power, with consolidated health systems extracting volume discounts unavailable to fragmented purchasers.
- Diagnostic Laboratories:Centralized reference networks process high-throughput sample volumes using automated sample-to-answer systems. National laboratory chains in the United States leverage multi-year sole-source contracts with group purchasing organizations to lock in reagent pricing and exclude secondary suppliers.
- Hospitals:Acute care facilities maintain STAT laboratories for emergency department turnaround requirements. Core laboratory consolidation following health system mergers has reduced independent purchasing autonomy and shifted procurement decisions to centralized supply chain committees.
- Home Care:Prescription-authorized self-collection kits for sexually transmitted infections bypass traditional laboratory intermediaries.
- Research Institutes:Academic medical centers and public health agencies sustain sequencing capacity for novel pathogen identification under WHO International Health Regulations mandates.
Hospitals anchor procurement volume. Home Care is climbing the fastest as direct-to-patient channels mature.
Technology:
Investment intensity diverges between established amplification methods and next-generation sequencing infrastructure requiring specialized bioinformatics support.
- PCR:Quantitative and digital PCR platforms remain the clinical standard for viral load quantification and qualitative detection. Mid-volume sites in Germany and France delay platform procurement decisions pending EU Medical Device Regulation transition completion, while United States laboratories accelerate placement under FDA emergency use authorization pathways.
- NGS:High-throughput sequencing enables phylogenetic classification and variant surveillance without prior pathogen knowledge. National health agencies sustain demand through epidemiological surveillance mandates, though clinical adoption curves remain slower due to bioinformatics talent scarcity and CAP accreditation requirements for variant interpretation pipelines.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective antibody quantification for blood bank screening.
- Immunoassays:Chemiluminescence and electrochemiluminescence platforms automate antigen and antibody detection with high throughput.
PCR dominates installed base. NGS is gaining share fastest in surveillance applications.
Application:
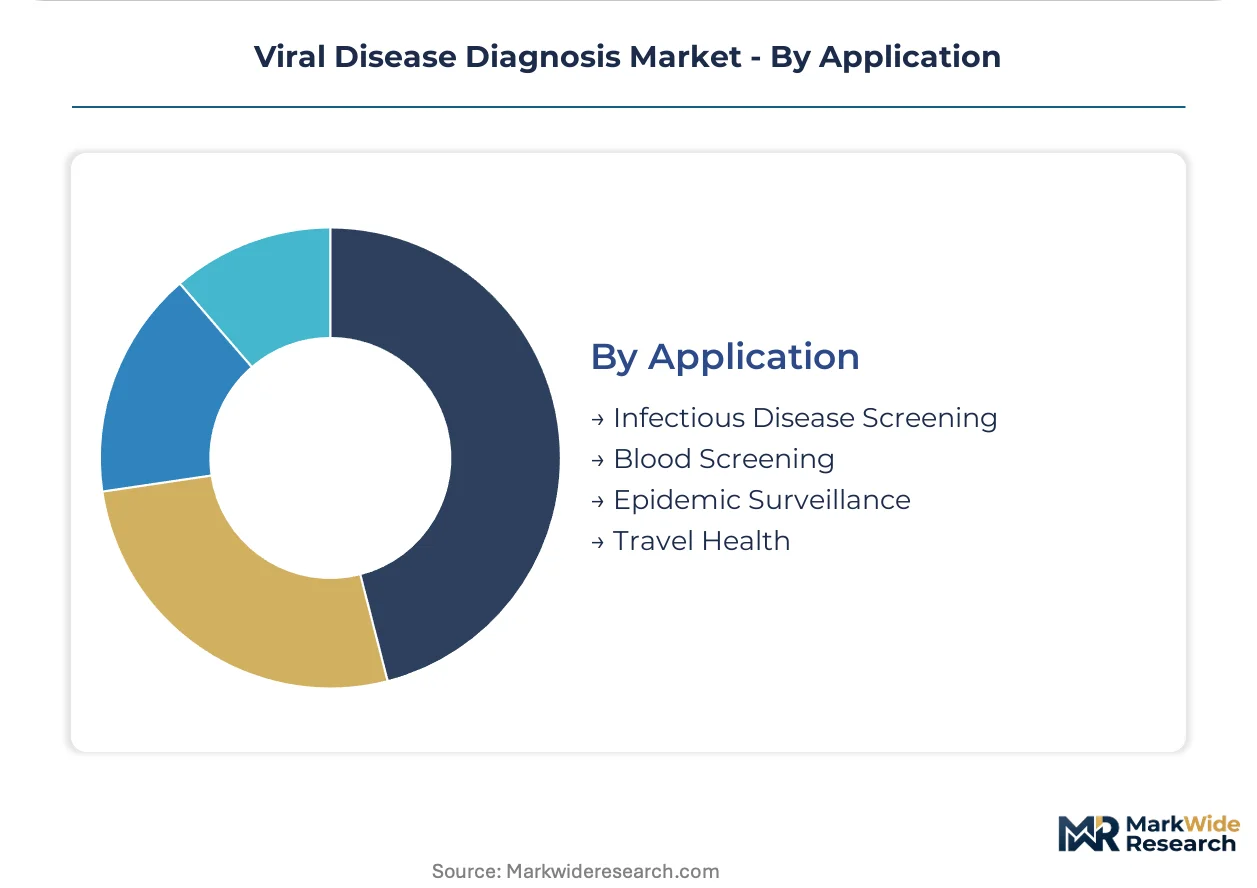
Reimbursement stability varies by use case, with screening programs offering predictable revenue streams compared to discretionary travel health spending.
- Infectious Disease Screening:Respiratory panels and sexually transmitted infection assays generate recurring volume through symptomatic patient presentation and asymptomatic screening protocols. Medicare coverage determinations for multiplex respiratory pathogen detection create predictable revenue streams justifying capital expenditure on automated systems.
- Blood Screening:Donor testing for HIV, hepatitis, and emerging pathogens maintains zero-defect quality requirements. Blood bank networks in the United States enforce stringent sensitivity thresholds that sustain demand for nucleic acid amplification technology despite higher per-test costs.
- Epidemic Surveillance:Field deployable assays and sequencing capacity support outbreak response.
- Travel Health:Pre-departure testing for yellow fever and other region-specific pathogens serves discretionary demand.
Infectious Disease Screening holds procedure volume. Blood Screening maintains pricing stability through regulatory requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution of temperature-sensitive molecular reagents, while the Dubai-Al Ain road corridor enables Gulf-wide redistribution of rapid diagnostic kits.
United States
Hospital consolidation into mega-systems like HCA Healthcare and Kaiser Permanente concentrates procurement decisions at centralized supply chain committees. FDA emergency use authorization pathways compress assay validation timelines, accelerating platform placement. The Research Triangle Park in North Carolina anchors high-complexity reference laboratory networks serving the Southeast.
Germany
Mid-volume laboratories in Bavaria and Baden-Württemberg delay platform procurement pending EU Medical Device Regulation transition completion. The EU In Vitro Diagnostic Regulation imposes clinical evidence documentation extending time-to-market for novel assays. Berlin-Brandenburg clusters academic medical centers maintaining sequencing capacity under WHO International Health Regulations mandates.
China
Domestic manufacturers exploit NMPA fast-track pathways for infectious disease assays to displace imported platforms in provincial hospital networks. The dual carbon goals pressure energy-intensive reagent production facilities toward process efficiency investments. The Yangtze River Delta concentration of biotech parks in Shanghai and Suzhou drives molecular platform innovation.
India
The Production Linked Incentive scheme for medical devices subsidizes domestic manufacturing of diagnostic reagents, reducing import dependency for Southeast Asian distributors. CDSCO streamlined approval pathways accelerate assay registration for tuberculosis and dengue diagnostics. Hyderabad and Bengaluru clusters specialize in contract manufacturing of polymerase enzymes for global supply chains.
Japan
PMDA's Sakigake designation system accelerates approval for novel viral detection technologies addressing unmet infectious disease needs. METI funding programs sustain domestic sequencing infrastructure for pandemic preparedness. The Kansai region's Osaka-Kobe medical device corridor specializes in automated sample-to-answer systems for mid-volume sites.
Viral Disease Diagnosis Market Competitive Landscape
Listed leaders compete with private specialists across instrument placement and reagent supply contracting. The vendor base concentrates among ten to fifteen firms with established regulatory quality management systems, while mid-tier assay developers face notified body capacity constraints. Three archetypes dominate: diversified life science conglomerates with installed base leverage, pure-play molecular diagnostic specialists, and contract manufacturers supplying private-label reagents. Competitive moves center on unbundling instrument placement from consumable supply agreements and securing multi-year sole-source contracts with group purchasing organizations.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Abbott Laboratories exemplify platform-anchored reagent strategies. F. Hoffmann-La Roche Ltd occupies a position emphasizing automated systems that reduce operator dependency. These three firms represent contrasting approaches to channel control—Thermo Fisher Scientific through high-throughput sequencing workflows, Abbott Laboratories through rapid molecular platform ubiquity, and Roche through sample-to-answer automation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| BioMérieux SA |
| Becton, Dickinson and Company |
| Danaher Corporation |
| QIAGEN N.V. |
| Hologic Inc. |
| Others |
Value Network & Pricing Analysis
FDA emergency use authorization pathways gate both supply qualification and price differentiation simultaneously, as manufacturers with validated quality management systems command premium positioning while assay developers without notified body relationships face 18-24 month delays that compress their pricing power upon market entry.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with group purchasing organizations extracting multi-year sole-source contracts that lock in reagent pricing independent of capital equipment vendors. Three-tier pricing stratifies across automated sample-to-answer systems, rapid molecular platforms, and lateral flow alternatives, with FDA tier and CLIA complexity classification serving as primary differentiation drivers. Cost compression in rapid diagnostics intensifies as antigen-based substitutes capture outpatient volume, while blood screening segments maintain pricing stability through zero-defect regulatory requirements. Consolidated health systems demonstrate lowest price sensitivity; independent physician office laboratories exhibit highest.
Supply Chain Analysis
Inventory lead times for polymerase and reverse transcriptase enzymes extend when single-source contract manufacturers in the United States, Germany, and India face capacity constraints. Production draws from temperature-sensitive reagent facilities concentrated near Rotterdam's cold-chain logistics hub and the Dubai-Al Ain corridor for Gulf redistribution. Single-source vulnerability in enzyme supply creates structural risk, as three contract manufacturers anchor global capacity. Distribution runs through diagnostic laboratory networks and hospital supply chain committees, with regional clusters in Hyderabad and Bengaluru feeding Southeast Asian demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral disease diagnosis represents a service-attach opportunity as reagent supply agreements and bioinformatics support contracts expand faster than instrument hardware placement, creating recurring revenue streams that justify upfront platform discounts.
For Market Incumbents: Fortify installed base leverage by unbundling instrument placement from consumable supply agreements before hospital procurement committees mandate competitive bidding. Deepen backward integration into polymerase enzyme production to offset single-source supply vulnerability. Channel control through rapid molecular platform ubiquity defends against CRISPR-based diagnostic substitutes displacing quantitative PCR in resource-limited settings.
For New Entrants and Emerging Players: Differentiate on AI-assisted variant calling capabilities that automate phylogenetic classification without specialist intervention, addressing bioinformatics talent scarcity in clinical laboratories. Target at-home molecular testing channels for sexually transmitted infections, where prescription-authorized self-collection kits bypass traditional laboratory intermediaries. Pursue CDSCO streamlined approval pathways for tuberculosis and dengue diagnostics to establish beachhead in India before scaling to Southeast Asian distributors.
For Investors and Strategic Acquirers: EU IVDR transition completion reshapes the acquisition landscape by filtering market entrants toward established quality management systems with notified body relationships. Five-to-ten year viability favors assay developers with clinical evidence packages already submitted, as European notified bodies have reduced active certificates by 40% since 2021. Target acquisition archetype: mid-tier molecular diagnostic specialists with automated sample-to-answer systems and existing GPO contracts. Signal to watch: MDR transition completion in Germany and France triggering delayed platform procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emergency Use Authorization Pathway | Accelerates assay validation timelines from years to months for novel viral detection technologies. |
| CLIA Complexity Waiver Expansion | Enables molecular platform placement in physician office laboratories beyond hospital core labs. |
| Hospital System Partnership | Secures multi-year sole-source contracts with consolidated mega-systems like HCA Healthcare. |
| Software Companion Development | Cloud-based bioinformatics pipelines address variant interpretation pipeline validation requirements. |
| Reimbursement Strategy | Medicare coverage determinations for multiplex respiratory panels create predictable revenue streams. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from FDA emergency use authorization filings, CMS Medicare reimbursement databases, hospital procurement records, and WHO International Health Regulations compliance documentation. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down epidemiological surveillance mandate funding allocations.
Sensitivity analysis tested forecast robustness across alternative CLIA waiver expansion scenarios and EU IVDR transition timelines. Segmentation dimensions modeled include test type complexity tier, end-user procurement concentration, technology amplification method, and application reimbursement stability. CAGRs derived from installed base growth rates and consumable attach rates projected across the analysis window. Industry-specific inputs incorporated polymerase enzyme supply capacity constraints and digital PCR platform adoption curves in mid-volume sites.
The analysis sits within stated boundaries; outcomes outside sustained FDA emergency use authorization pathway velocity or notified body capacity expansion would require recalibration. Forecasts reflect assumptions regarding hospital consolidation trajectories and respiratory panel reimbursement stability. Revision becomes warranted when lateral flow substitution rates in outpatient settings cross thresholds that fundamentally compress molecular test pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Immunoassay Market
Diagnostics
Antibody Testing Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
IVD Antibody Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Global Chlamydia Infection Diagnostics Market