
 Infectious Disease Molecular Diagnostics Market | 2026-2036
Infectious Disease Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Disease Molecular Diagnostics Market Intelligence
The distribution model for diagnostic assays and systems is reconfiguring as testing decentralizes from large reference centers. This shift creates new opportunities for suppliers with robust logistics. F. Hoffmann-La Roche Ltd leverages its extensive installed base of instruments to secure long-term reagent contracts. Abbott Laboratories competes effectively with its rapid, point-of-care platforms designed for smaller clinical settings.
Infectious disease molecular diagnostics involves the detection and identification of pathogen-specific nucleic acid sequences, such as DNA or RNA. These techniques provide highly sensitive and specific results, often identifying the exact strain of a virus or bacterium. Polymerase Chain Reaction (PCR) technology remains the workhorse for routine testing, while Next-Generation Sequencing is gaining traction for complex cases. The viral detection application segment holds a dominant position, driven by surveillance of respiratory and bloodborne pathogens.
Regulatory frameworks dictate market access and product design. The US FDA's approval pathways, Europe's CE marking under the IVDR, and China's NMPA regulations set high bars for clinical validation and manufacturing quality. These bodies ensure the accuracy and reliability of tests used for public health decisions. Choosing between rapid, targeted assays and comprehensive, sequencing-based panels represents a central strategic consideration for end users.
Market Dynamics
The central structural force shaping the market is the decentralization of testing, moving from high-volume reference laboratories to smaller clinical and point-of-care settings. This shift is driven by clinical demand for faster turnaround times to guide patient treatment.
Growth Catalysts
- Public Health Investment:China's significant national investment in its public health infrastructure and disease control centers accelerates the adoption of advanced molecular diagnostic platforms for nationwide surveillance programs.
- NGS Proliferation:The expanding use of Next-Generation Sequencing technology in clinical laboratories enables more comprehensive pathogen identification and antimicrobial resistance profiling from a single patient sample, improving diagnostic yield.
- Syndromic Testing Demand:Clinical need for rapid differentiation of pathogens with similar symptoms, particularly for respiratory infections, drives uptake of multiplex PCR panels that test for numerous targets simultaneously.
Market Restraints
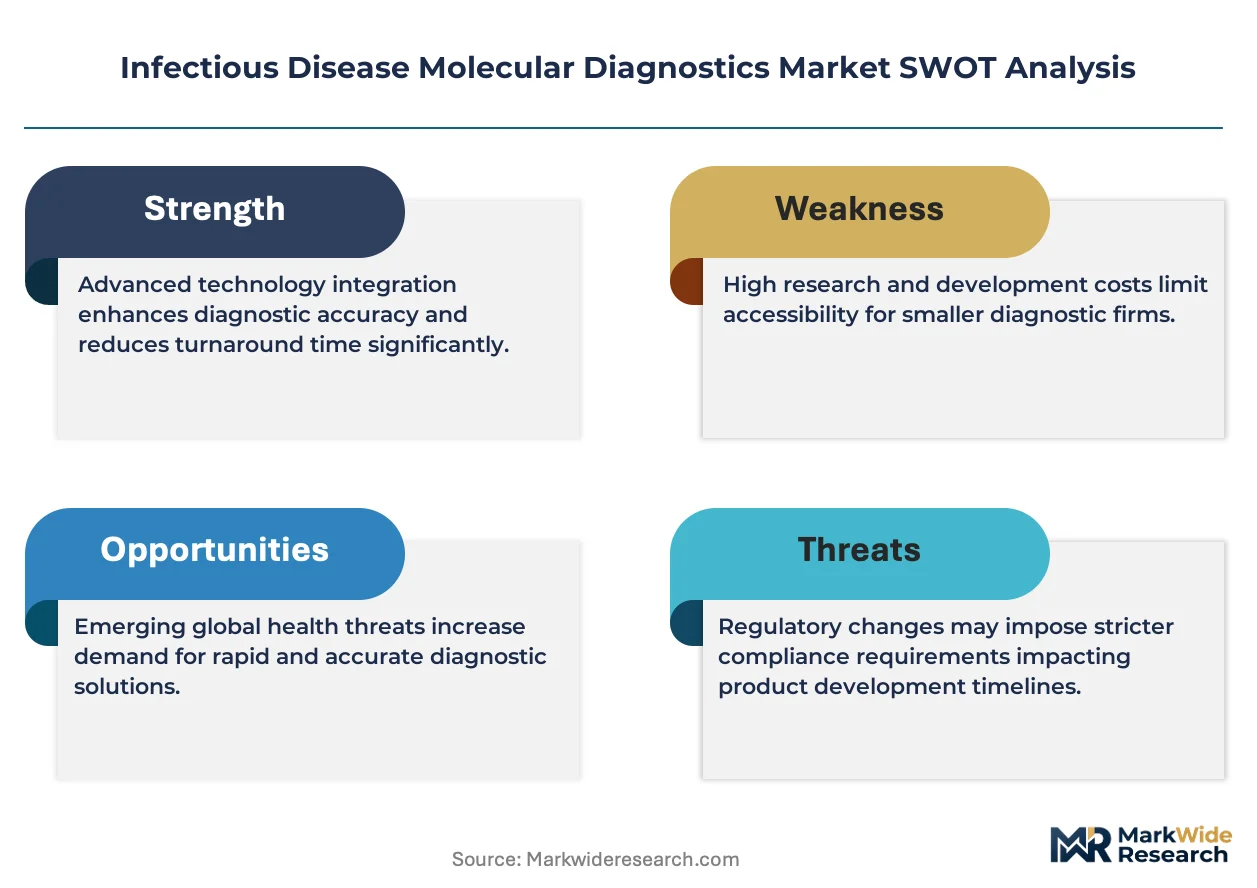
- High Instrument Costs:The substantial capital expenditure required to acquire and maintain high-throughput PCR and NGS systems presents a significant barrier for smaller laboratories and healthcare facilities in resource-limited settings.
- Regulatory Hurdles:Europe's stringent In Vitro Diagnostic Regulation (IVDR) imposes extensive clinical evidence and post-market surveillance requirements, increasing the time and cost for manufacturers to achieve CE marking.
- Bioinformatics Bottleneck:The analysis and clinical interpretation of large datasets generated by NGS platforms require specialized bioinformatics expertise, a skill set that remains scarce within many clinical laboratory teams.
Strategic Opportunities
- Emerging Market Expansion:Building out diagnostic infrastructure and distribution networks in Latin American and Southeast Asian countries offers access to large, underpenetrated populations with growing healthcare expenditures.
- Wastewater Surveillance:Developing and validating molecular assays for wastewater-based epidemiology presents a new application for public health agencies to monitor infectious disease trends at a community level.
- Assay Automation:Integrating sample-to-result automation into molecular diagnostic workflows can reduce hands-on time, minimize human error, and improve laboratory efficiency, creating value for high-volume end users.
Industry Challenges
- Skilled Labor Shortage:A persistent deficit of medical technologists and laboratory scientists trained to operate complex molecular instruments and perform nuanced data interpretation constrains testing capacity.
- System Interoperability:Integrating new diagnostic instruments with legacy Laboratory Information Systems (LIS) and Electronic Health Records (EHR) often requires custom development, creating implementation delays and additional costs for hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Disease Molecular Diagnostics Market |
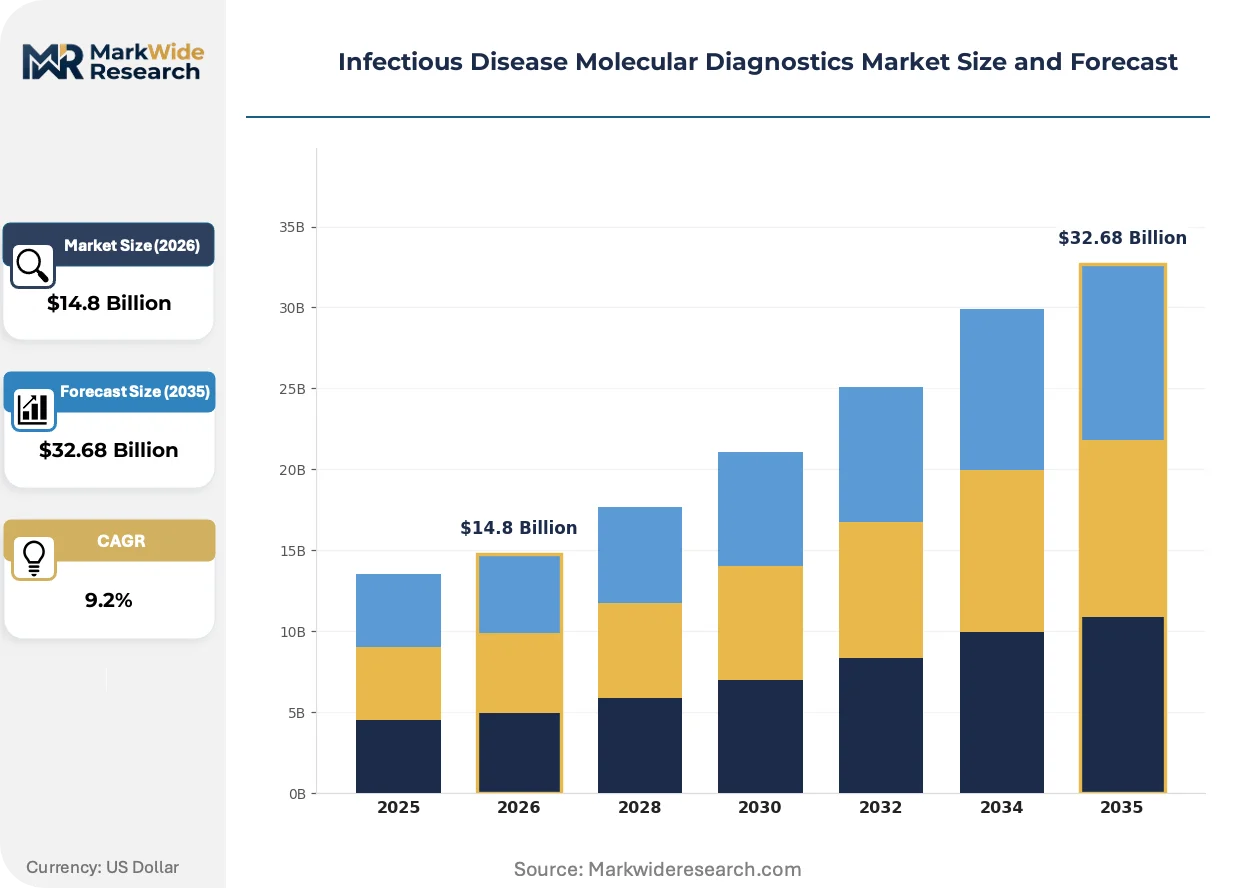
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time PCR Systems, Nucleic Acid Amplification Kits, DNA Sequencers, Gene Chips Application: Viral Detection, Bacterial Identification, Fungal Testing, Parasitic Diagnostics End User: Clinical Laboratories, Reference Centers, Research Institutes, Public Health Laboratories Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Microarray Analysis, Isothermal Amplification |
| Companies Covered | Thermo Fisher Scientific, QIAGEN N.V., Abbott Laboratories, Siemens Healthineers AG, Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd, bioMérieux SA, Hologic Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Disease Molecular Diagnostics Market Strategic Shifts & Innovations
Diagnostic workflows are evolving to prioritize speed and accessibility, pushing technological innovation toward automation and platform consolidation. This movement reflects a fundamental change in how clinicians and public health officials utilize molecular data for immediate decision-making, impacting instrument design and reagent sales models.
Multiplex PCR technology enables the simultaneous detection of multiple viral and bacterial targets from one sample. Clinical laboratories are rapidly adopting these syndromic panels to diagnose complex respiratory or gastrointestinal infections more efficiently. The diagnostic approach is migrating from a series of single-target tests to a comprehensive, panel-based first-line screen, compressing the time to a definitive result.
Europe's In Vitro Diagnostic Regulation (IVDR) has fundamentally altered the compliance landscape for assay manufacturers. The regulation mandates more rigorous clinical performance studies and continuous post-market surveillance, raising the bar for market entry. The laboratory-developed test (LDT) segment is most affected, as many previously exempt tests now require formal CE marking and supporting technical documentation.
Contractual agreements are changing how laboratories acquire diagnostic capabilities. End users are increasingly favoring reagent rental or cost-per-test models over outright capital purchases of large instruments, especially in North America and Western Europe. This shifts the financial burden from a large upfront investment to a predictable operational expense, lowering the adoption barrier for advanced technologies like NGS.
Infectious Disease Molecular Diagnostics Market Segmentation
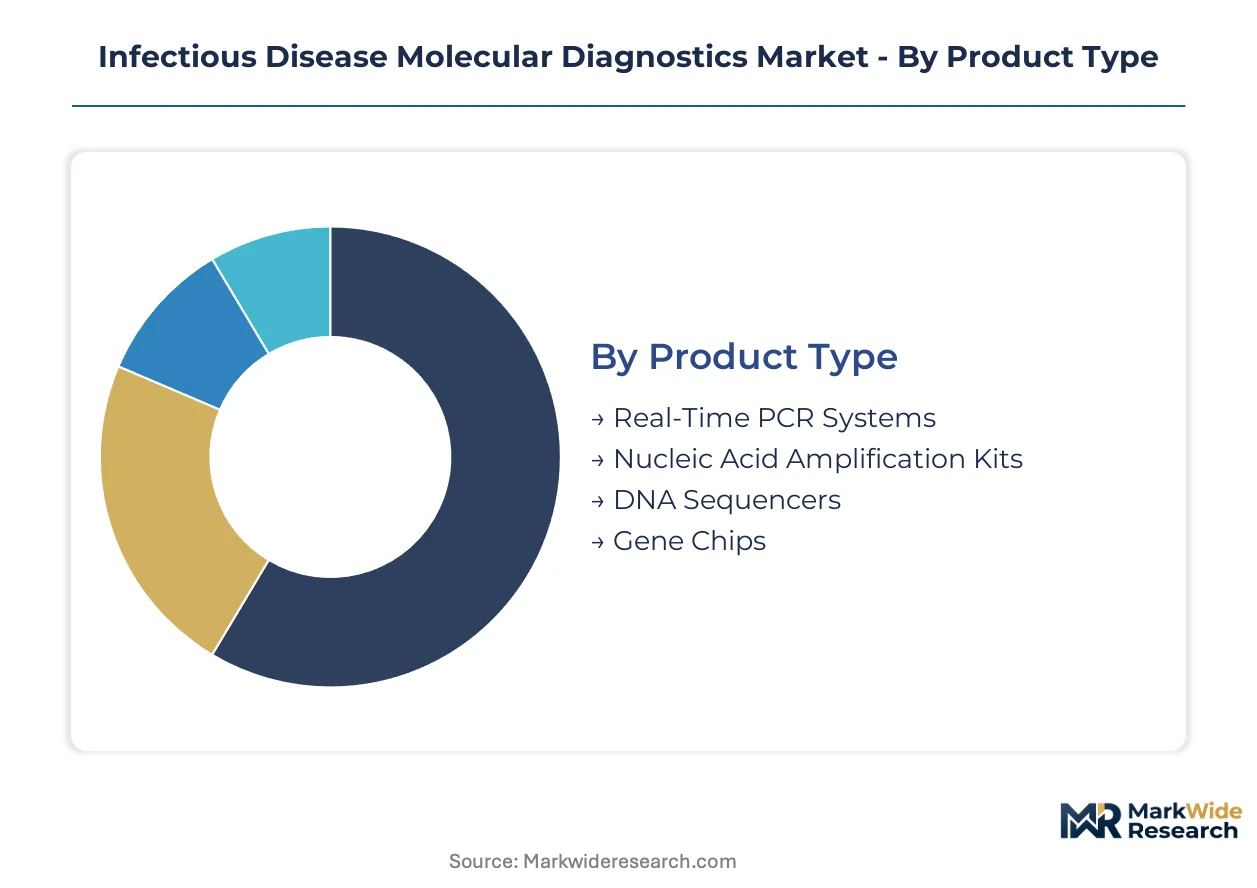
The infectious disease molecular diagnostics market segments across product type, application, end user, and technology, each reflecting distinct operational requirements and commercial dynamics. Understanding these divisions is crucial for manufacturers to align product development and distribution strategies with specific market needs.
Product Type:
The product type segment is heavily influenced by the intensity of after-sales service and ongoing consumable supply required for instrument operation.
- Real-Time PCR Systems:These systems enable rapid, quantitative detection of nucleic acids, offering high sensitivity and specificity for infectious agents. Demand is concentrated in clinical laboratories and public health settings requiring fast turnaround times for patient management and outbreak surveillance.
- Nucleic Acid Amplification Kits:These kits contain reagents for amplifying target DNA or RNA sequences, forming the consumable core for most molecular diagnostic tests. Their demand is driven by the increasing volume of routine testing in decentralized clinical settings and reference laboratories.
- DNA Sequencers:These instruments determine the precise order of nucleotides within DNA molecules, essential for comprehensive pathogen identification and antimicrobial resistance profiling.
- Gene Chips:Microarray-based platforms allow for the simultaneous detection of hundreds or thousands of genetic targets, providing broad pathogen screening capabilities.
Nucleic Acid Amplification Kits hold the largest share; momentum sits with Real-Time PCR Systems.
Application:
Application segments delineate the specific pathogens or disease categories targeted by molecular diagnostic assays, reflecting varying clinical priorities and public health burdens.
- Viral Detection:This application focuses on identifying viral nucleic acids, critical for diagnosing respiratory infections, hepatitis, HIV, and emerging viral threats. Surveillance programs and patient management in hospitals drive significant demand for these tests.
- Bacterial Identification:This segment involves detecting bacterial DNA or RNA, essential for diagnosing bacterial infections, guiding antibiotic therapy, and identifying antibiotic resistance markers. Clinical laboratories prioritize rapid and accurate bacterial identification to improve patient outcomes.
- Fungal Testing:Molecular assays in this area identify fungal pathogens, particularly important for immunocompromised patients where fungal infections can be severe.
- Parasitic Diagnostics:This application targets parasitic organisms, providing sensitive detection for diseases like malaria and toxoplasmosis, especially relevant in endemic regions.
Viral Detection applications dominate the market; bacterial identification is expanding quickly.
End User:
The end-user segmentation highlights the diverse operational environments where molecular diagnostics are deployed, each with unique infrastructure, budget, and regulatory considerations.
- Clinical Laboratories:These facilities perform a broad range of diagnostic tests for patient care, driven by the need for rapid and accurate pathogen identification to inform treatment decisions. Decentralization of testing is increasing the volume handled by smaller clinical labs.
- Reference Centers:Large, centralized laboratories that handle high volumes of complex or specialized molecular diagnostic tests, often serving multiple smaller healthcare providers. These centers benefit from high-throughput automated systems.
- Research Institutes:Academic and commercial research organizations utilize molecular diagnostics for pathogen discovery, epidemiology studies, and developing new diagnostic methods. Their focus is on advanced sequencing and novel assay development.
- Public Health Laboratories:Government-funded laboratories responsible for disease surveillance, outbreak investigation, and monitoring population health trends. These labs are critical for national disease control programs.
Clinical Laboratories represent the primary end-user segment, while Public Health Laboratories show significant growth.
Technology:
The technology segment groups diagnostic methods by their underlying scientific principles, influencing assay performance characteristics such as speed, sensitivity, and multiplexing capabilities.
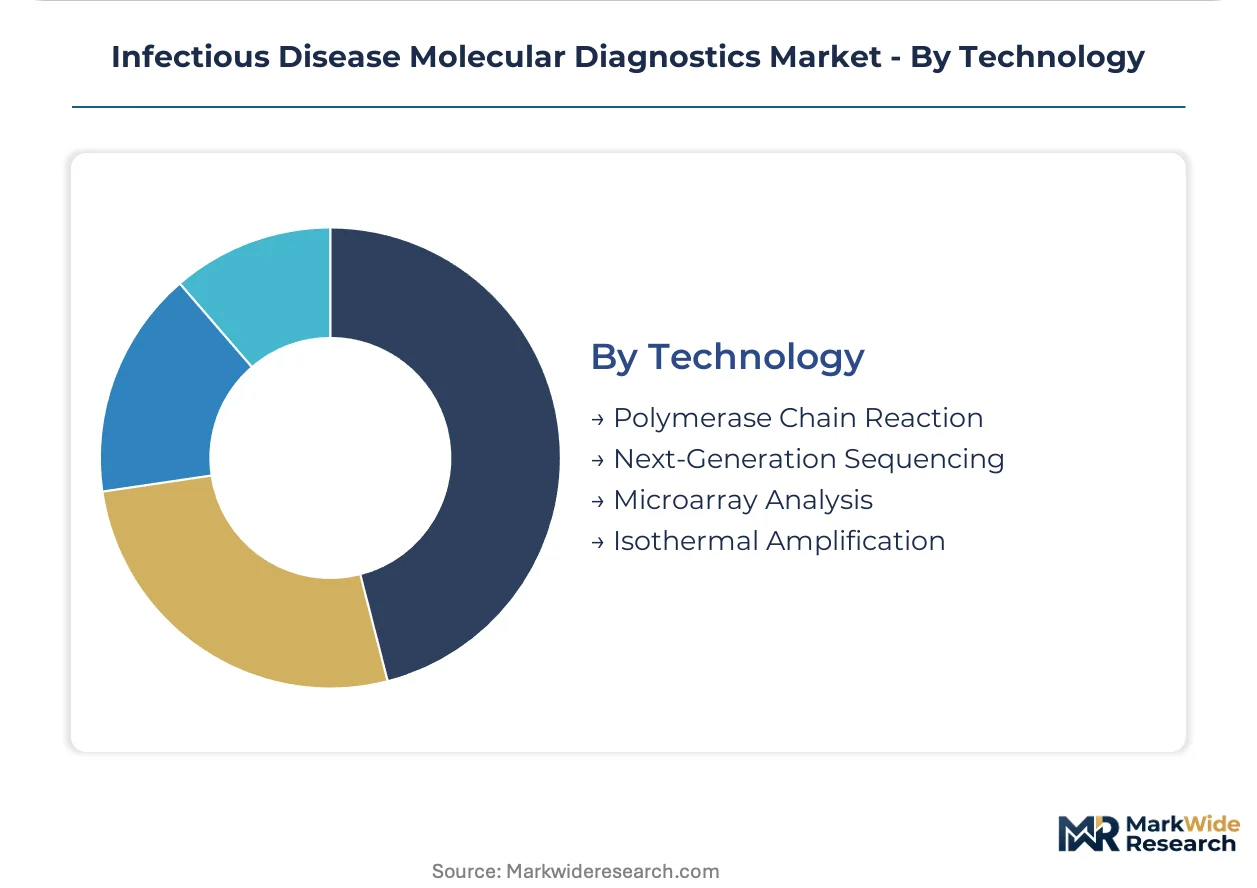
- Polymerase Chain Reaction:PCR technology amplifies specific DNA or RNA sequences, remaining the cornerstone for routine molecular diagnostic testing due to its high sensitivity and specificity. Clinical laboratories widely adopt PCR for its reliability and established protocols.
- Next-Generation Sequencing:NGS platforms sequence millions of DNA fragments simultaneously, providing comprehensive genetic information for pathogen identification, strain typing, and antimicrobial resistance profiling. Research institutes and specialized reference centers increasingly use NGS for complex cases.
- Microarray Analysis:This technology uses a solid surface with an array of probes to detect multiple nucleic acid targets simultaneously, offering high-throughput screening capabilities.
- Isothermal Amplification:These methods amplify nucleic acids at a constant temperature, simplifying instrumentation and enabling point-of-care applications due to reduced equipment requirements.
Polymerase Chain Reaction remains the foundational technology, and Next-Generation Sequencing is experiencing rapid uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's significant national investment in its public health infrastructure drives the adoption of advanced molecular diagnostic platforms. This commitment to nationwide surveillance programs shapes regional market dynamics. Public health initiatives across multiple countries influence demand for rapid pathogen identification.
United States
United States demand for infectious disease molecular diagnostics stems from its advanced healthcare infrastructure and high disease burden. The US FDA's stringent approval pathways ensure test reliability and market access for manufacturers. Major biotech clusters like Boston and San Diego focus on developing novel sequencing technologies and diagnostic assays.
China
China's public health investment continues to stimulate demand for infectious disease molecular diagnostics across its vast population. The NMPA regulations govern product design and market entry for diagnostic assays, setting high quality standards. Beijing and Shanghai serve as hubs for domestic manufacturers and research institutes developing advanced diagnostic solutions.
Germany
Germany shows strong demand for infectious disease molecular diagnostics due to its robust healthcare system and extensive research capabilities. Europe's IVDR mandates rigorous clinical evidence for market access, impacting product design and development costs. Munich and Heidelberg are centers for advanced molecular biology research and diagnostic development, attracting significant investment.
India
India's expanding healthcare infrastructure and rising infectious disease burden create significant molecular diagnostics demand, particularly in urban centers. The CDSCO regulates medical devices and diagnostics, influencing market entry and product specifications. Bengaluru and Hyderabad emerge as key locations for R&D and manufacturing activities within the diagnostic sector.
Brazil
Brazil's public health initiatives and increasing access to advanced medical technologies generate demand for infectious disease molecular diagnostics. ANVISA oversees regulatory approval processes for diagnostic products within the country, ensuring product safety and efficacy. São Paulo and Rio de Janeiro host significant clinical laboratory networks and distribution centers for diagnostic equipment.
Infectious Disease Molecular Diagnostics Market Key Industry Players
On the supply side, the industry is characterized by a mix of established multinational corporations and agile specialized firms. These players often fall into archetypes of broad-portfolio providers, rapid-test innovators, or high-throughput system specialists, each targeting different end-user needs. Dominant competitive moves include strategic partnerships to expand market reach and continuous portfolio diversification through targeted research and development efforts.
Within the broad-portfolio provider archetype, F. Hoffmann-La Roche Ltd exemplifies a company leveraging an extensive installed instrument base to secure long-term reagent contracts across diverse clinical settings. Abbott Laboratories, known for its rapid, point-of-care platforms, represents the agile innovator archetype, competing effectively with solutions designed for smaller clinical environments. Thermo Fisher Scientific, a global supplier of scientific instruments, reagents, and consumables, anchors the high-throughput system specialist segment, catering to large reference laboratories and research institutes.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN N.V. |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| bioMérieux SA |
| Hologic Inc. |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly Europe's IVDR, determine both pricing tier spreads for compliant assays and shape the supply chain by demanding specialized manufacturing and clinical validation capabilities. This regulatory intensity influences market access and the cost of bringing new diagnostic solutions to market.
Pricing Analysis
Certification level (US FDA, Europe's CE marking, China's NMPA) creates the primary spread in infectious disease molecular diagnostics pricing. A hybrid model of reagent rental and capital purchase dominates, with differentiation driven by instrument sophistication, assay multiplexing capabilities, and bundled after-sales support. Pricing softness reflects increasing competition in routine PCR testing, particularly for high-volume consumables. Smaller clinical laboratories demonstrate higher price sensitivity compared to large reference centers or research institutes.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often underpin the procurement of high-value molecular diagnostic instruments and reagents. Supply concentrates in advanced manufacturing hubs like Germany, the United States, and China for complex instrumentation and critical reagents. Raw material dependencies include specialized enzymes for amplification and proprietary microfluidic components. Single-source vulnerability for certain highly specialized reagents presents a structural risk. Distribution runs through a mix of direct sales forces for large systems and specialized third-party logistics providers for consumable kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infectious disease molecular diagnostics market is experiencing high-growth disruption, driven by the proliferation of Next-Generation Sequencing technology. This technological inflection enables more comprehensive pathogen identification and antimicrobial resistance profiling.
For Market Incumbents: Harden existing customer relationships by leveraging extensive installed instrument bases to secure long-term reagent contracts. Invest in sample-to-result automation to counter the skilled labor shortage and improve laboratory efficiency, particularly against the threat of agile point-of-care platforms. Strategic acquisitions of specialized bioinformatics companies can mitigate the analysis bottleneck. Focus R&D on next-generation multiplexing to maintain a competitive edge.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated emerging markets, particularly Latin America and Southeast Asia, by building out localized diagnostic infrastructure. Target smaller clinical laboratories with rapid, user-friendly point-of-care platforms that offer simplified workflows. Developing and validating molecular assays for wastewater-based epidemiology provides a novel application for public health agencies. Adopt cost-per-test models to lower adoption barriers.
For Investors and Strategic Acquirers: The market sits at a high-growth phase that favors specialized technology providers and platform consolidators. Long-term viability remains strong for the next decade, driven by continuous public health investment and ongoing innovation in sequencing technologies. Identify acquisition targets with proprietary bioinformatics solutions, advanced automation capabilities, or novel isothermal amplification platforms. The signal to watch is the increasing adoption of syndromic testing panels in routine clinical practice.
| Strategic Initiative | Industry Significance |
|---|---|
| Assay Automation Integration | Reduces hands-on time and minimizes human error in high-volume laboratories, improving efficiency. |
| Next-Generation Sequencing (NGS) Platform Development | Enables comprehensive pathogen identification and antimicrobial resistance profiling from a single sample. |
| Point-of-Care (POC) Diagnostic System Launch | Expands testing accessibility to smaller clinical settings and decentralized environments, improving turnaround. |
| Emerging Market Distribution Network Expansion | Accesses large, underpenetrated populations with growing healthcare expenditures, driving market reach. |
| Multiplex PCR Panel Commercialization | Addresses clinical demand for rapid differentiation of pathogens with similar symptoms, compressing diagnostic time. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Primary data involved conversations with clinical lab directors, R&D scientists, regulatory affairs specialists, and public health officials across key geographies. Secondary sources included regulatory body publications, scientific journals, company annual reports, and industry association data. This approach facilitated bottom-up and top-down triangulation for market sizing and forecasting.
Forecast inputs considered historical market performance, current industry dynamics, and projected growth catalysts across the analysis window. The quantitative model segmented the market by product type, application, end user, technology, and regional public health investment. Compound annual growth rates were derived by analyzing historical trends and projecting future adoption rates of advanced diagnostics. Key industry-specific inputs included pathogen prevalence data and national public health infrastructure spending.
Stress conditions across public health policy shifts, major technological breakthroughs, and global pandemic responses were modeled; outcomes outside those bands fall beyond the analytical envelope. The forecasts reflect documented assumptions regarding market access and technology adoption. Unforeseen regulatory changes or rapid shifts in pathogen epidemiology could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Bronchitis Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
IVD Infectious Disease Market