
 Europe Hospital Acquired Disease Testing Market | 2026-2036
Europe Hospital Acquired Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hospital Acquired Disease Testing Market Intelligence
MDR is repositioning the cost-of-entry calculus for hospital acquired disease testing platforms across European member states. bioMérieux SA leverages its French manufacturing base to sustain PCR-based instrument placements in tertiary hospitals. F. Hoffmann-La Roche Ltd anchors centralized laboratory workflows with high-throughput molecular systems. Abbott Laboratories differentiates through point-of-care connectivity that competes with traditional laboratory turnaround benchmarks.
Hospital acquired disease testing encompasses diagnostic methodologies that detect pathogens transmitted during healthcare delivery, including PCR amplification cycles, antigen-antibody binding assays, and culture-based phenotypic identification with 24-72 hour incubation requirements. Molecular diagnostics commands the dominant revenue position due to superior sensitivity for bloodstream and respiratory tract infections. Serological tests occupy a narrowing but defended role in outbreak surveillance where seroprevalence tracking supports epidemiological mapping. Rapid tests are gaining structural traction in emergency departments where clinical decision-making demands results within sixty minutes.
EMA and notified bodies under MDR enforce clinical performance documentation for Class C and D in vitro diagnostics, while GDPR constrains how patient-derived genomic data flows across hospital information systems. The EU Green Deal indirectly shapes reagent procurement through sustainability criteria embedded in public tender specifications. Stakeholders must monitor how the EU AI Act classifies algorithm-enhanced pathogen identification software, as this determination will reshape regulatory pathways for next-generation sequencing platforms integrated with diagnostic workflows.
Market Dynamics
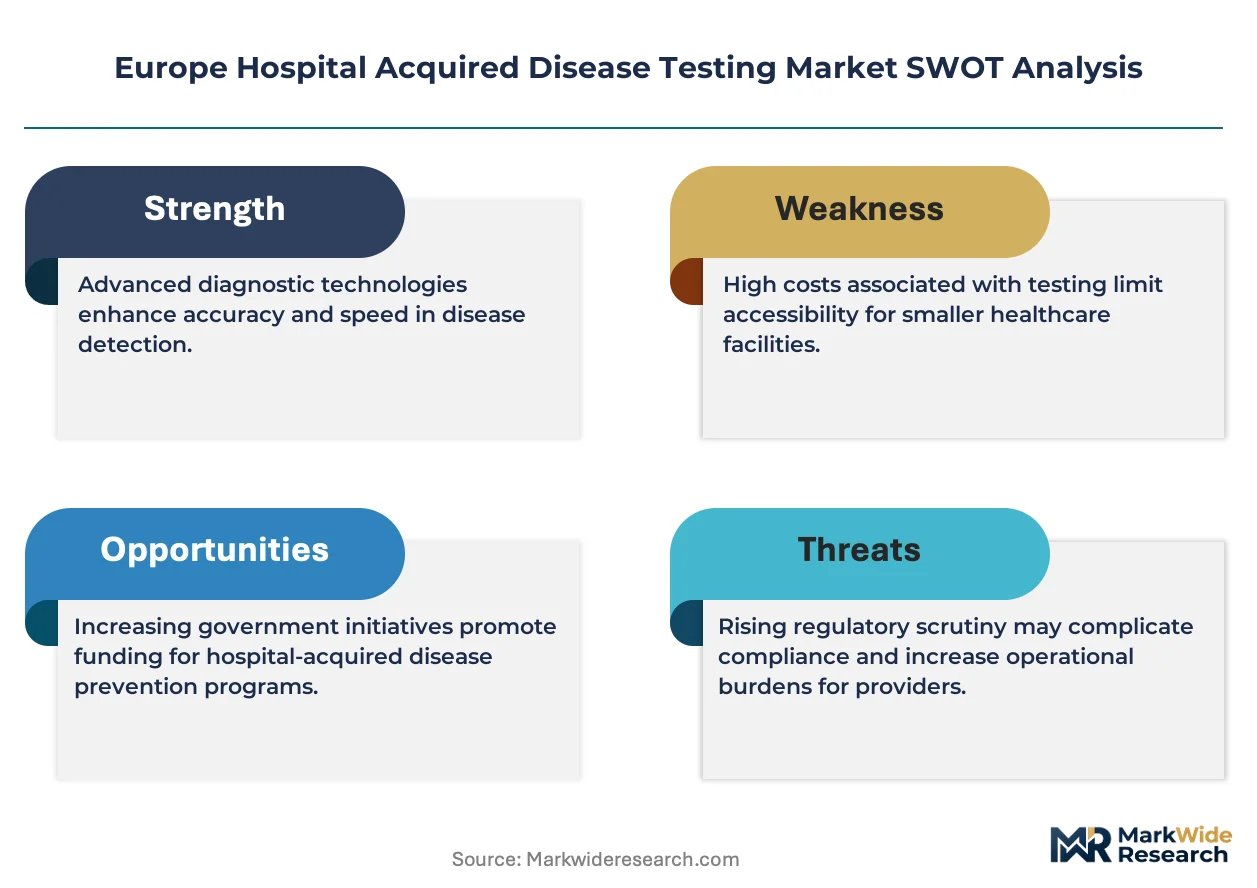
The EU Medical Device Regulation is compressing conformity timelines for Class C and D in vitro diagnostics while intensifying notified body scrutiny over clinical performance dossiers. This regulatory density is forcing manufacturers to restructure quality management systems and accelerate post-market surveillance investments.
Growth Catalysts
- ICU Expansion:Tertiary hospitals in Germany, France, and Italy are extending molecular screening protocols for bloodstream and respiratory pathogens. This infrastructure buildout creates instrument placement opportunities.
- GDPR-Compliant Data Flows:Standardized genomic data architectures are enabling cross-border hospital information system integration. Pathogen surveillance networks now operate with reduced legal friction.
- Point-of-Care Connectivity:Emergency departments are adopting networked rapid testing platforms that transmit results directly to isolation protocols. This workflow compression reduces transmission windows.
Market Restraints
- MDR Transition Costs:Notified body capacity constraints are extending conformity assessment timelines to 18-24 months. Small and mid-sized diagnostic manufacturers face working capital pressure.
- Reagent Supply Concentration:Polymerase and nucleotide supply chains concentrate in German and Dutch chemical manufacturing clusters. Geopolitical disruptions threaten PCR workflow continuity.
- Culture-Based Substitution Resistance:Phenotypic identification retains reimbursement preference for certain antibiotic susceptibility testing. Molecular sensitivity advantages do not fully displace established workflows.
Strategic Opportunities
- Central and Eastern Europe:Hospital infrastructure modernization in Poland, Romania, and Czechia is outpacing domestic diagnostic manufacturing capacity. Import substitution creates vendor entry points.
- EU AI Act Classification:Algorithm-enhanced pathogen identification software may qualify as high-risk AI systems. Early compliance positioning secures regulatory pathway advantages for next-generation sequencing platforms.
- EU Green Deal Procurement:Sustainability criteria embedded in public tender specifications favor reagent suppliers with reduced cold-chain footprints. Biodegradable consumable formats attract scoring premiums.
Industry Challenges
- Notified Body Queue Compression:MDR transition deadlines have created application backlogs exceeding 12 months for Class C IVDs. Manufacturers face portfolio freeze risks.
- Legacy LIS Integration:Hospital information systems running 1990s-era architectures require middleware development for molecular diagnostic connectivity. Custom integration consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hospital Acquired Disease Testing Market |
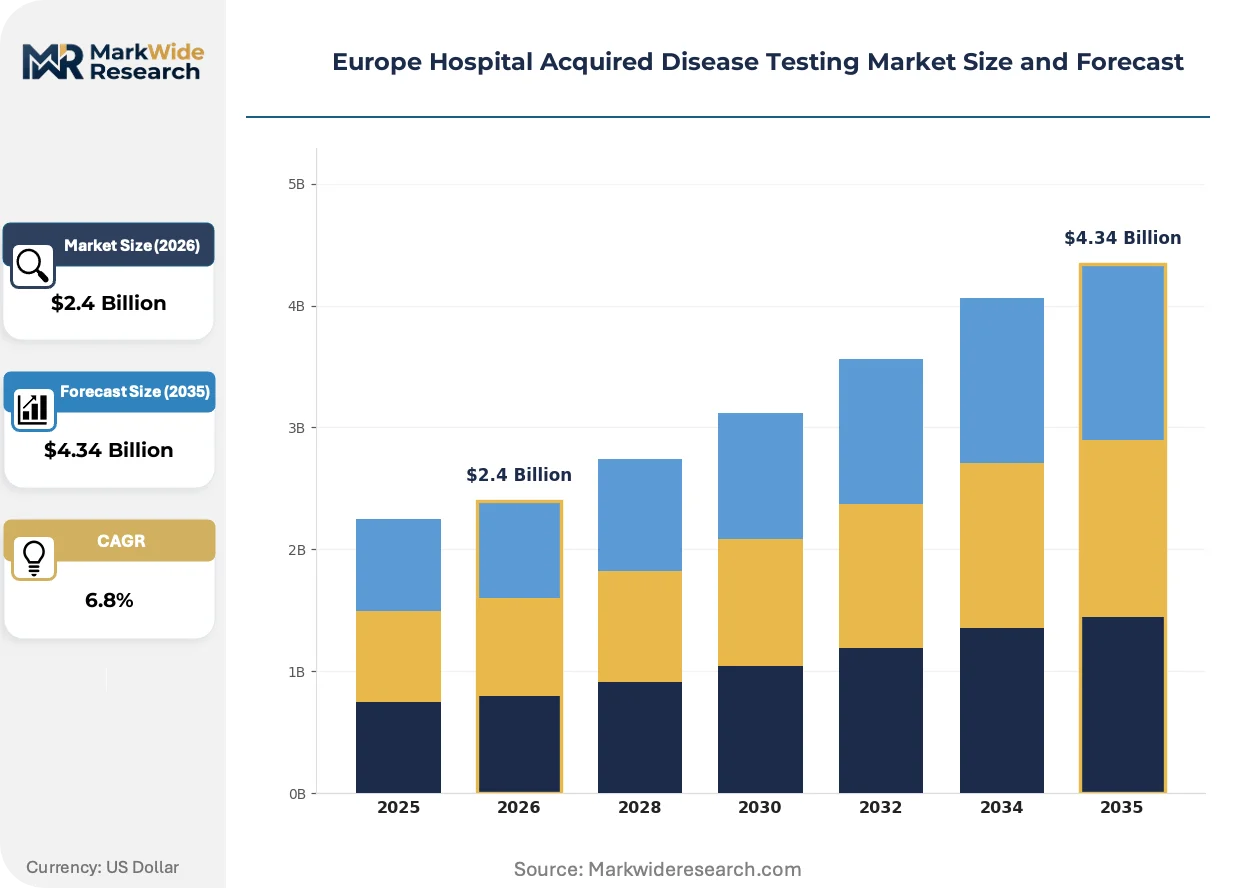
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molecular Diagnostics, Serological Tests, Culture Tests, Rapid Tests End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Technology: PCR, ELISA, NGS, Microarrays Application: Bacterial Infections, Viral Infections, Fungal Infections, Parasitic Infections |
| Companies Covered | bioMérieux SA, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Becton Dickinson and Company, Thermo Fisher Scientific, Hologic, Inc., QIAGEN, Danaher Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hospital Acquired Disease Testing Market Strategic Shifts & Innovations
Next-generation sequencing workflows are penetrating hospital laboratories previously dominated by PCR-based platforms. This technology transition is compressing pathogen identification timelines while expanding resistance gene profiling capabilities.
Multiplex PCR panels are converging with antimicrobial stewardship software to enable real-time treatment guidance. Tertiary hospital microbiology laboratories in France and Germany are adopting these integrated workflows. The convergence is compressing the gap between pathogen detection and therapeutic decision-making.
EMA guidance on clinical performance studies for infectious disease IVDs is elevating evidence requirements for novel platform introductions. Manufacturers must now demonstrate diagnostic accuracy across diverse hospital populations. Smaller diagnostic developers face disproportionate clinical trial cost burdens relative to established multinational instrument suppliers.
Hospital procurement consortia in Italy and Spain are consolidating reagent purchasing through multi-year framework agreements. Independent distributors are losing access to high-volume tertiary accounts. This concentration is visible in regional tender awards that specify single-source molecular platform commitments spanning five-year horizons.
Europe Hospital Acquired Disease Testing Market Segmentation
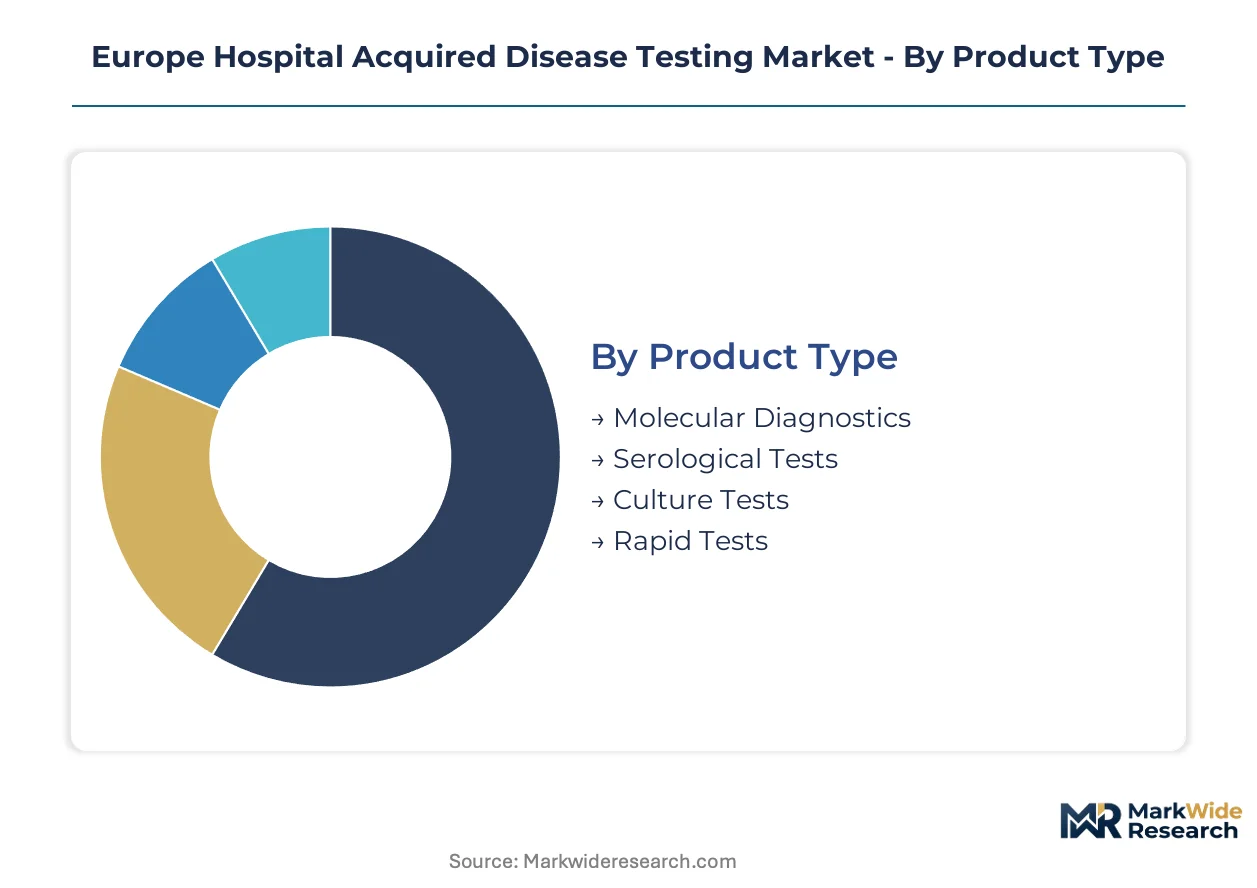
Segmentation in hospital acquired disease testing reveals how diagnostic workflows fragment across care settings and pathogen types. Procurement decisions in German and French tertiary hospitals diverge sharply from outpatient clinic requirements in Spain and Poland.
Product Type:
Molecular diagnostics platforms operate as standalone capital investments requiring dedicated laboratory infrastructure, while rapid tests embed directly into emergency department workflows with minimal integration overhead.
- Molecular Diagnostics:PCR and nucleic acid amplification systems detect bloodstream and respiratory pathogens with sensitivity exceeding culture methods. Demand concentrates in German and Italian ICU expansion projects where turnaround time drives isolation protocol efficiency. MDR conformity timelines extend procurement cycles for new instrument placements.
- Rapid Tests:Lateral flow and immunochromatographic assays deliver results within sixty minutes at point-of-care. Emergency departments in France and Spain adopt these for immediate triage decisions where laboratory connectivity remains limited.
- Serological Tests:Antibody detection supports outbreak surveillance and seroprevalence mapping across EU hospital networks.
- Culture Tests:Phenotypic identification retains reimbursement preference for antibiotic susceptibility profiling in centralized microbiology laboratories.
Volume placements concentrate in molecular diagnostics; the faster expansion belongs to rapid tests.
End User:
Customer type determines integration complexity and regulatory exposure, with hospitals bearing full MDR compliance burdens while outpatient clinics operate under lighter oversight frameworks.
- Hospitals:Tertiary and secondary acute care facilities operate molecular diagnostic laboratories with trained microbiology staff. German university hospitals and French CHU networks anchor instrument demand through multi-year reagent framework agreements.
- Diagnostic Laboratories:Centralized reference labs in the Netherlands and Belgium process high-throughput screening for hospital networks. These facilities optimize batch economics across regional catchment areas.
- Research Institutions:Academic medical centers in the UK and Sweden validate novel resistance gene detection methods before clinical translation.
- Outpatient Clinics:Ambulatory surgical centers and day clinics in Spain and Poland adopt rapid testing for pre-admission screening with minimal infrastructure investment.
Revenue concentration sits with hospitals; outpatient clinics are expanding most quickly as same-day surgery volumes rise.
Technology:
Technology selection tracks the tension between established workflow familiarity and emerging platform capabilities, with PCR dominating current placements while NGS builds evidence for clinical adoption.
- PCR:Polymerase chain reaction remains the backbone of hospital molecular diagnostics, with thermal cycler placements concentrated in German and French tertiary facilities. Reagent supply chains from Dutch chemical manufacturers sustain workflow continuity.
- NGS:Next-generation sequencing platforms penetrate reference laboratories in the UK and Sweden for resistance gene profiling and outbreak investigation. EMA guidance on clinical performance studies elevates evidence requirements for broader hospital adoption.
- ELISA:Enzyme-linked immunosorbent assays serve serological surveillance networks with established automation compatibility.
- Microarrays:Multiplex probe arrays detect predefined pathogen panels in centralized laboratories with standardized reporting protocols.
PCR claims the largest installed base; NGS holds the steepest expansion trajectory as resistance profiling demands intensify.
Application:
Application segmentation aligns with infection site prevalence and antimicrobial stewardship priorities, with bloodstream and respiratory pathogens commanding disproportionate screening investment.
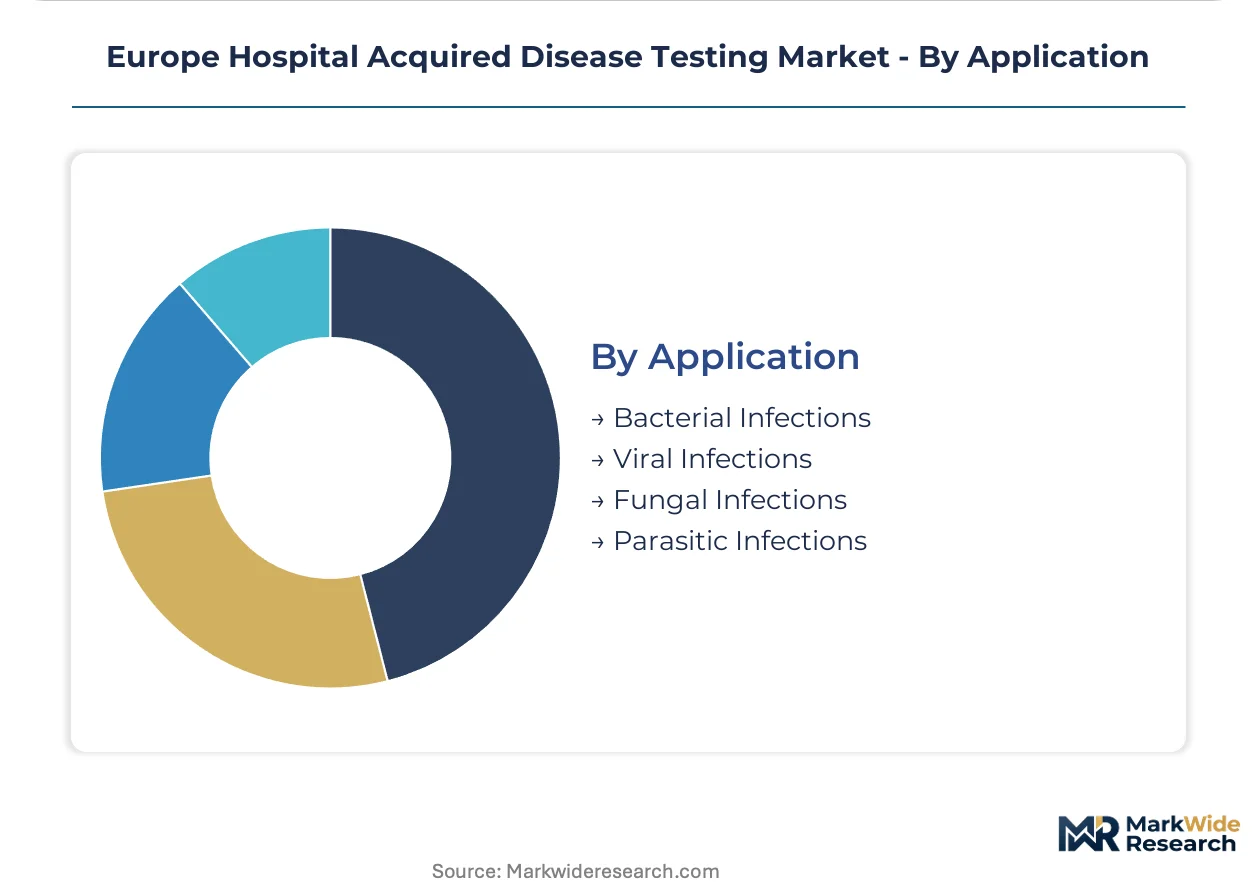
- Bacterial Infections:Methicillin-resistant Staphylococcus aureus and Clostridioides difficile drive molecular screening volumes in German and Italian ICUs. These pathogens trigger mandatory isolation protocols that compress acceptable turnaround windows.
- Viral Infections:Cytomegalovirus and respiratory virus panels support transplant and immunocompromised patient management in French and UK tertiary centers.
- Fungal Infections:Candida species detection concentrates in hematology and oncology units with prolonged neutropenia exposure.
- Parasitic Infections:Limited screening volumes focus on imported cases and immunocompromised populations in Mediterranean port cities.
Bacterial infection testing dominates procedure volumes; viral panels are gaining share fastest through expanded immunocompromised patient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region concentrates diagnostic manufacturing through tax-advantaged industrial zones. German chemical clusters supply polymerase reagents to hospital laboratories across Western Europe. French medical technology parks near Lyon anchor instrument assembly operations serving tertiary care networks.
Germany
University hospitals in Berlin and Munich drive molecular diagnostic placements through ICU expansion programs. The Federal Institute for Drugs and Medical Devices enforces MDR transition timelines that compress notified body assessment windows. The Rhine-Ruhr chemical manufacturing belt sustains PCR reagent production for domestic consumption and export to Benelux markets.
France
CHU networks in Paris and Lyon anchor high-throughput screening volumes for bloodstream pathogen detection. ANSM coordinates with notified bodies to streamline Class C IVD conformity assessments for domestic manufacturers. The Lyon biotech corridor houses assembly operations for multiplex PCR platforms deployed across Mediterranean hospital systems.
United Kingdom
Academic medical centers in London and Cambridge validate next-generation sequencing workflows for resistance gene profiling. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit IVD regulations with retained EU MDR principles. The Cambridge-Oxford arc concentrates research institutions pioneering algorithm-enhanced pathogen identification methods.
Italy
Lombardy hospital consortia consolidate reagent purchasing through multi-year framework agreements covering molecular diagnostics. The Italian Medicines Agency enforces clinical performance documentation requirements for novel platform introductions. The Milan metropolitan area anchors procurement decisions that specify single-source instrument commitments spanning five-year horizons.
Netherlands
Centralized reference laboratories in Rotterdam and Utrecht optimize batch economics for regional hospital network screening. The Healthcare and Youth Care Inspectorate monitors GDPR compliance in cross-border genomic data flows. The Dutch chemical manufacturing cluster supplies nucleotide reagents sustaining PCR workflow continuity across Northern European markets.
Europe Hospital Acquired Disease Testing Market Key Industry Players
French and German producers anchor one tier; Swiss and American specialists hold differentiated positions in molecular diagnostics. The vendor base concentrates around multinational instrument suppliers with established notified body relationships and quality management systems. Three archetypes dominate: integrated diagnostics conglomerates with broad assay menus, point-of-care connectivity specialists, and reagent-focused chemical suppliers. Competitive moves center on MDR compliance positioning and strategic partnerships with hospital procurement consortia.
Within the integrated diagnostics tier, bioMérieux SA and F. Hoffmann-La Roche Ltd exemplify archetypes leveraging domestic manufacturing bases to sustain instrument placements in tertiary hospitals. Abbott Laboratories occupies a position in point-of-care connectivity that challenges traditional laboratory turnaround benchmarks. These three entities represent the competitive spectrum from centralized high-throughput systems to distributed rapid testing platforms.
| Leading Market Players |
|---|
| bioMérieux SA |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Hologic, Inc. |
| QIAGEN |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
EU Green Deal sustainability criteria embedded in public tender specifications gate qualified supply access and premium-tier pricing power for hospital acquired disease testing reagents. Manufacturers demonstrating reduced cold-chain footprints and biodegradable consumable formats secure scoring premiums that translate into margin protection, while non-compliant suppliers face exclusion from high-volume procurement frameworks.
Pricing Analysis
Premium pricing for instruments with sub-24-hour lead times contrasts with spot-inventory discounts for standardized PCR reagents nearing expiry. The dominant structure is contract-based long-term offtake through multi-year framework agreements, with price differentiation driven by MDR certification tier and volume scale commitments. Cost compression in rapid test consumables is intensifying because outpatient clinic procurement consortia are consolidating purchasing power. Diagnostic laboratories exhibit the highest price sensitivity due to batch-optimization pressures, while tertiary ICU expansion projects show lowest sensitivity given isolation protocol efficiency imperatives.
Supply Chain Analysis
MDR conformity assessment certification gates supply chain participation, with notified body approvals required for polymerase and nucleotide reagent suppliers. Manufacturing concentrates in Germany, the Netherlands, and France, with raw material dependencies on specialty enzymes, fluorescent probes, and sterile plastics. Single-source vulnerability runs through Dutch chemical clusters supplying thermal-stable polymerases. Distribution runs through hospital procurement consortia and centralized reference laboratory networks rather than independent distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where MDR transition timelines create a barrier-to-entry moat for manufacturers with established notified body relationships and quality management systems.
For Market Incumbents: Lock in reagent supply agreements with Rhine-Ruhr chemical manufacturers to defend against polymerase supply concentration risks. Prioritize post-market surveillance infrastructure investments to satisfy intensified EMA scrutiny over clinical performance dossiers, securing portfolio continuity as smaller competitors face working capital pressure from extended conformity timelines.
For New Entrants and Emerging Players: The gap between premium-tier molecular diagnostics and economy rapid test pricing creates entry space for mid-tier multiplex platforms with antimicrobial stewardship software integration. Central and Eastern European hospital infrastructure modernization in Poland and Czechia offers the most penetrable geography, with import substitution demand outpacing domestic manufacturing capacity. A go-to-market angle through diagnostic laboratory partnerships bypasses direct competition with established tertiary hospital instrument placements.
For Investors and Strategic Acquirers: EU AI Act classification determinations for algorithm-enhanced pathogen identification software are the leading indicator that next-generation sequencing platform valuations will separate from conventional PCR instrument multiples. The 5-10 year viability window favors acquisition targets with early compliance positioning in high-risk AI system pathways and established hospital information system middleware capabilities. The specific signal to watch is EMA guidance publication on clinical performance studies for infectious disease IVDs incorporating machine learning components.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Acceleration | Notified body queue compression in Germany and France threatens portfolio freeze for non-compliant manufacturers. |
| Antimicrobial Stewardship Software Integration | French CHU networks are adopting multiplex PCR panels with real-time treatment guidance compression. |
| Central and Eastern European Distribution Partnerships | Polish and Romanian hospital modernization creates vendor entry points through import substitution demand. |
| EU AI Act Early Compliance Positioning | Algorithm-enhanced NGS platforms require high-risk AI system pathway navigation for regulatory clearance. |
| Sustainable Reagent Format Development | EU Green Deal procurement criteria favor reduced cold-chain footprints in Italian and Spanish tender awards. |
Research Approach
Document review covered EMA guidance publications, MDR technical documentation requirements, and hospital procurement tender databases, complemented by interviews with hospital laboratory directors, IVD regulatory affairs specialists, biomedical engineers, and GPO contracts managers. Secondary validation drew from notified body capacity reports, EU medical device trade data, and CMS Medicare laboratory fee schedule references. Bottom-up instrument placement modeling and top-down market sizing triangulated volume estimates across molecular diagnostics, rapid tests, and serological surveillance segments.
Cross-referencing historical placement data against expert panel input on ICU expansion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user facility tier, technology platform, and application pathogen category, with regional regulatory cluster differentiation for MDR transition maturity. CAGRs were derived from weighted average of epidemiological trend trajectories and capital expenditure pipeline visibility, incorporating antimicrobial resistance surveillance data and hospital infrastructure investment announcements as industry-specific forecast inputs.
Inputs from notified body capacity trackers and hospital procurement consortium award databases were available through the study window; gaps in real-time reagent pricing transparency and private tender negotiation outcomes introduce uncertainty bands around competitive share assumptions. Forecasts reflect documented assumptions regarding MDR transition timeline adherence and geopolitical stability in German-Dutch chemical manufacturing corridors. A model refresh is warranted upon material change in EU AI Act implementing regulation publication or notified body accreditation suspension events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Measles Market
Infectious Disease
Hepatitis C Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market