
 Global Herpes Zoster Infection Treatment Market | 2026-2036
Global Herpes Zoster Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Herpes Zoster Infection Treatment Market Foresight
Biologics manufacturing capacity in Ireland is decoupling from traditional small-molecule production networks, creating dedicated supply corridors for antiviral therapies. GlaxoSmithKline leverages its vaccine infrastructure across European and North American sites to secure bulk recombinant zoster antigen supply. Merck & Co. anchors its position through long-standing relationships with specialty distributors serving immunology clinics. Pfizer competes via integrated sterile fill-finish capacity that reduces third-party dependency for injectable formulations.
Herpes zoster infection treatment encompasses pharmaceutical and biologic interventions targeting varicella-zoster virus reactivation, including nucleoside analog antivirals such as acyclovir, valacyclovir, and famciclovir formulated for oral or intravenous administration with specific bioavailability profiles and dosing regimens designed to reduce viral shedding duration and prevent postherpetic neuralgia complications. Vaccines command the highest margin pool within product type segments due to recombinant adjuvanted manufacturing complexity and limited supplier field, while pain relievers occupy commoditized positions with generic saturation. Among therapy areas, postherpetic neuralgia generates disproportionate revenue per treated patient because chronic pain management requires multidrug regimens and repeat clinical encounters.
FDA's Division of Antiviral Products and EMA's Committee for Medicinal Products for Human Use enforce divergent efficacy endpoints for zoster vaccine licensure, shaping trial design costs and approval timelines for developers seeking transatlantic market access. WHO prequalification standards influence procurement eligibility across Gavi-supported national immunization programs, particularly in lower-middle-income countries expanding adult vaccination schedules. Stakeholders must monitor evolving CDC Advisory Committee on Immunization Practices recommendations for age-based and indication-based vaccine prioritization, as these determinations redirect public and private payer budgets across competing preventive therapy categories.
Market Dynamics
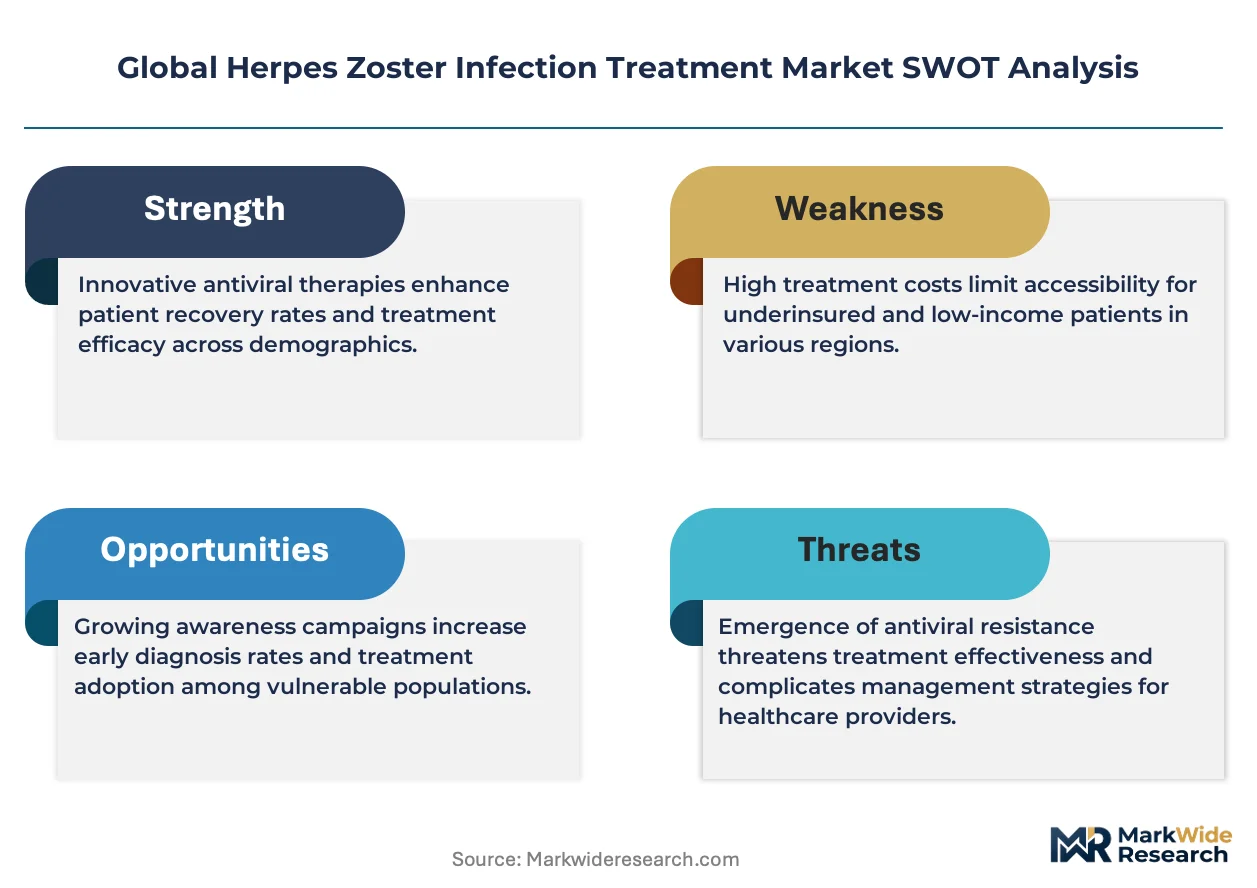
Recombinant adjuvanted vaccine manufacturing is absorbing capital and technical talent at rates that reshape competitive entry barriers, concentrating supply among facilities capable of sterile bulk antigen production and cold-chain distribution at scale.
Growth Catalysts
- Immunization schedule expansion:CDC Advisory Committee on Immunization Practices recommendations for broader age-based eligibility are redirecting public health budgets toward adult zoster vaccination programs.
- EMA accelerated assessment pathways:The Committee for Medicinal Products for Human Use offers priority review for novel antiviral formulations targeting immunocompromised populations, compressing development timelines.
- Postherpetic neuralgia burden:Chronic pain management requirements in tertiary care settings drive multidrug regimen adoption and repeat clinical encounters.
Market Restraints
- Recombinant protein supply concentration:Bulk antigen production clusters in Ireland and Belgium, creating single-source dependency for adjuvanted vaccine fill-finish.
- FDA-EMA endpoint divergence:Differing efficacy thresholds for zoster vaccine licensure force duplicate clinical trial designs, inflating regulatory compliance costs.
- Generic nucleoside analog saturation:Acyclovir and valacyclovir commoditization erodes pricing power in oral antiviral segments.
Strategic Opportunities
- Japan's aging demographic:METI-supported biomanufacturing investments align with expanding eligible treatment pools for adults over 65.
- WHO prequalification procurement:Gavi-supported national immunization programs in lower-middle-income countries create volume opportunities for vaccine suppliers meeting prequalification standards.
- Integrated sterile fill-finish:Captive injectable production capacity reduces third-party dependency and accelerates batch release timelines.
Industry Challenges
- Biologics talent scarcity:Recombinant antigen process development and analytical method validation expertise concentrates in established manufacturing hubs.
- Cold-chain infrastructure capex:Ultra-low temperature storage and distribution networks require substantial capital deployment for regional market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Herpes Zoster Infection Treatment Market |
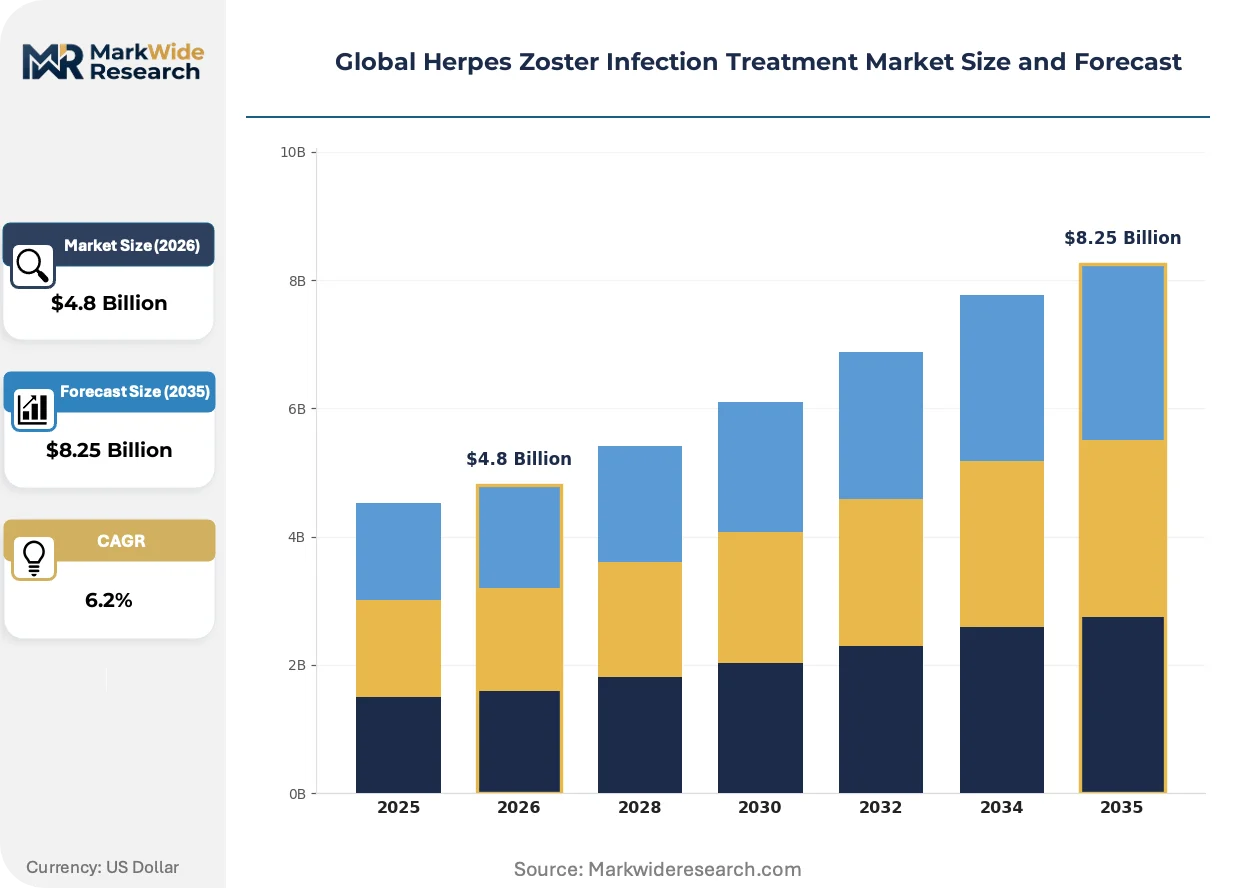
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Agents, Pain Relievers, Corticosteroids, Vaccines Therapy Area: Postherpetic Neuralgia, Acute Rash, Immunocompromised Patients, Elderly Care End User: Hospitals, Specialty Clinics, Outpatient Centers, Home Healthcare Delivery Mode: Oral, Topical, Injectable, Transdermal Patches |
| Companies Covered | GlaxoSmithKline, Merck & Co., Pfizer, Viatris, Novartis, Sanofi, Apotex, Teva Pharmaceutical Industries, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Herpes Zoster Infection Treatment Market Shifts & Advancements
Novel delivery technologies and regulatory pathway refinements are compressing development cycles while procurement centralization reshapes commercial access models across institutional buyers.
Recombinant adjuvanted subunit vaccines are absorbing technical investment from live-attenuated platforms, with healthcare systems in Germany and Japan prioritizing non-live formulations for immunocompromised patient access. Hospital pharmacy committees are consolidating formularies around these products. The shift is absorbing market share from legacy alternatives while expanding addressable populations previously excluded from vaccination.
REACH and RoHS compliance requirements in Europe are forcing reformulation of excipients and packaging materials used in antiviral drug products, with EMA's quality guidelines tightening impurity thresholds for nucleoside analogs. Manufacturers serving EU markets are responding by qualifying alternative suppliers and resubmitting chemistry-manufacturing-controls dossiers.
Integrated delivery networks in the United States are consolidating vaccine procurement through specialty distributors serving immunology clinics, displacing fragmented physician-office purchasing. Hospital systems are absorbing these volumes into centralized pharmacy operations. This concentration is most visible in Medicare Advantage plan structures where risk-bearing entities negotiate direct purchasing agreements.
Global Herpes Zoster Infection Treatment Market Segmentation
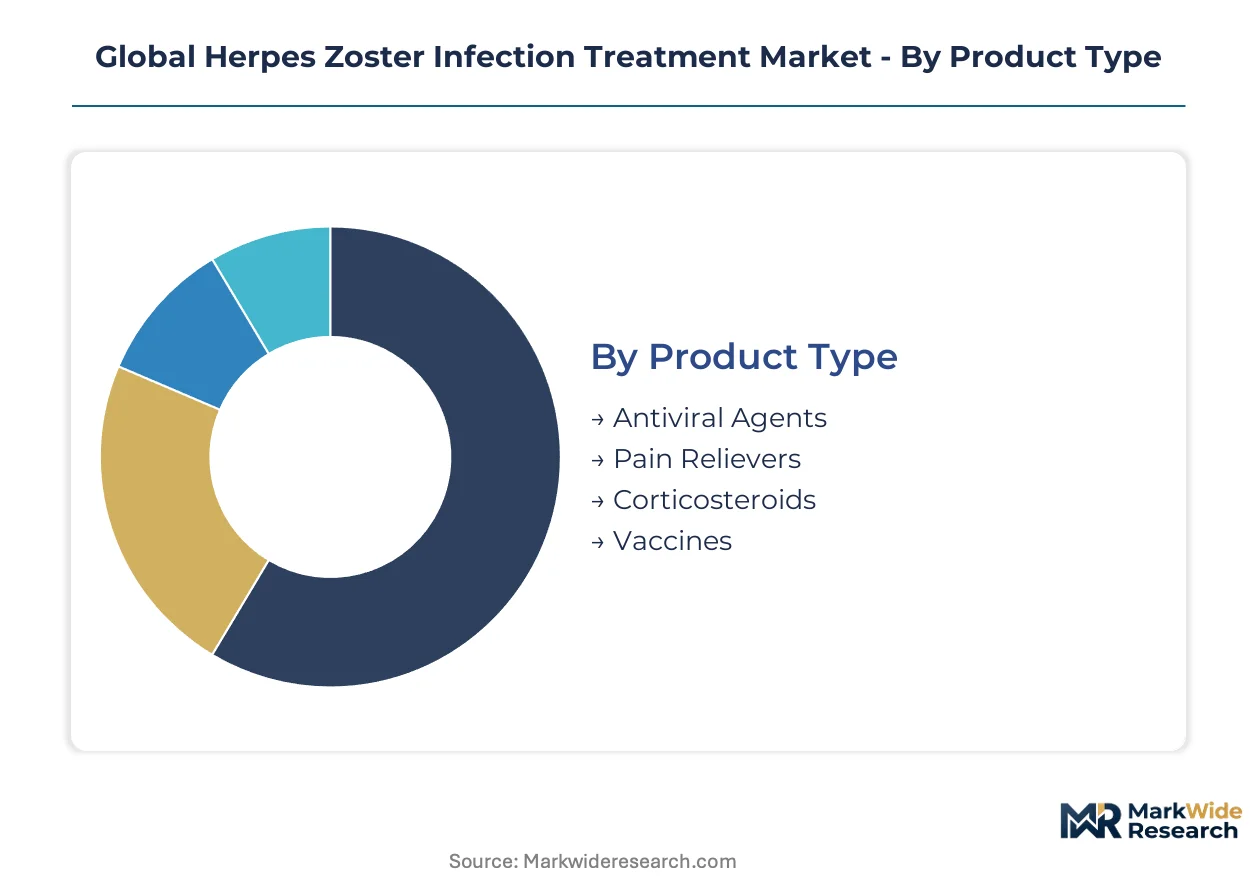
Treatment modality selection in herpes zoster care hinges on disease stage, patient immunocompetence, and care setting infrastructure. Segmentation reveals how vaccines capture preventive budgets while antivirals and pain management fragment across acute and chronic therapeutic contexts.
Product Type:
Standalone therapeutic categories operate independently of combination regimens, with each addressing distinct points in the disease continuum from prophylaxis through complication management.
- Antiviral Agents:Nucleoside analog formulations including acyclovir, valacyclovir, and famciclovir inhibit viral DNA polymerase to reduce lesion duration and viral shedding. Demand clusters in hospital emergency departments and urgent care settings across the United States and Japan, where rapid initiation within 72 hours of rash onset drives protocol adherence. Generic saturation has compressed margins, though IV formulations retain pricing power in inpatient settings.
- Vaccines:Recombinant adjuvanted subunit products stimulate cell-mediated immunity against varicella-zoster virus reactivation. Germany and Japan have prioritized these non-live formulations for immunocompromised populations, with specialty distributors capturing procurement volumes through integrated delivery networks. Manufacturing complexity and cold-chain requirements limit supplier field to facilities with sterile bulk antigen capability.
- Pain Relievers:NSAIDs, acetaminophen, and neuropathic agents address acute discomfort and postherpetic neuralgia symptoms.
- Corticosteroids:Systemic and localized anti-inflammatory therapy reduces edema and neural inflammation in select patient populations.
Vaccines lead volumes today; antiviral agents are gaining share fastest in emerging markets expanding access to acute care.
Therapy Area:
Cost tier stratification separates high-complexity chronic management from commodity acute interventions, with reimbursement intensity varying by complication severity and treatment duration.
- Postherpetic Neuralgia:Chronic neuropathic pain persisting beyond 90 days after rash resolution requires multidrug regimens combining gabapentinoids, tricyclics, and topical lidocaine. Tertiary pain clinics in the United States generate disproportionate revenue per patient through repeat encounters and device-based interventions. The condition's refractory nature sustains prolonged therapeutic relationships.
- Immunocompromised Patients:Prophylaxis and treatment in transplant recipients, oncology patients, and HIV-positive individuals demand higher-dose or extended antiviral courses with intensive monitoring. Hospital-based infectious disease services in Germany and Japan coordinate these complex cases through multidisciplinary protocols.
- Acute Rash:Initial vesicular eruption management focuses on lesion care and symptom control during the active viral phase.
- Elderly Care:Age-specific protocols address polypharmacy considerations and functional status in patients over 65.
Postherpetic neuralgia commands premium pricing today; immunocompromised patient protocols are expanding most quickly as transplant volumes rise.
End User:
Customer type differentiation tracks care acuity and reimbursement mechanism, with institutional buyers consolidating procurement leverage against fragmented outpatient purchasing.
- Hospitals:Inpatient and emergency settings manage severe disseminated zoster, ophthalmic involvement, and neurologic complications requiring IV antivirals and specialist consultation. Medicare Advantage risk-bearing entities in the United States negotiate direct purchasing agreements for vaccine and antiviral formularies.
- Specialty Clinics:Immunology and pain management practices deliver targeted prophylaxis and chronic neuropathy care.
- Outpatient Centers:Urgent care and primary care sites handle uncomplicated acute presentations with oral antiviral dispensing.
- Home Healthcare:Post-acute administration of oral regimens and patient education for homebound elderly.
Hospitals dominate value capture today; specialty clinics are ascending fastest as vaccination and pain management concentrate in dedicated settings.
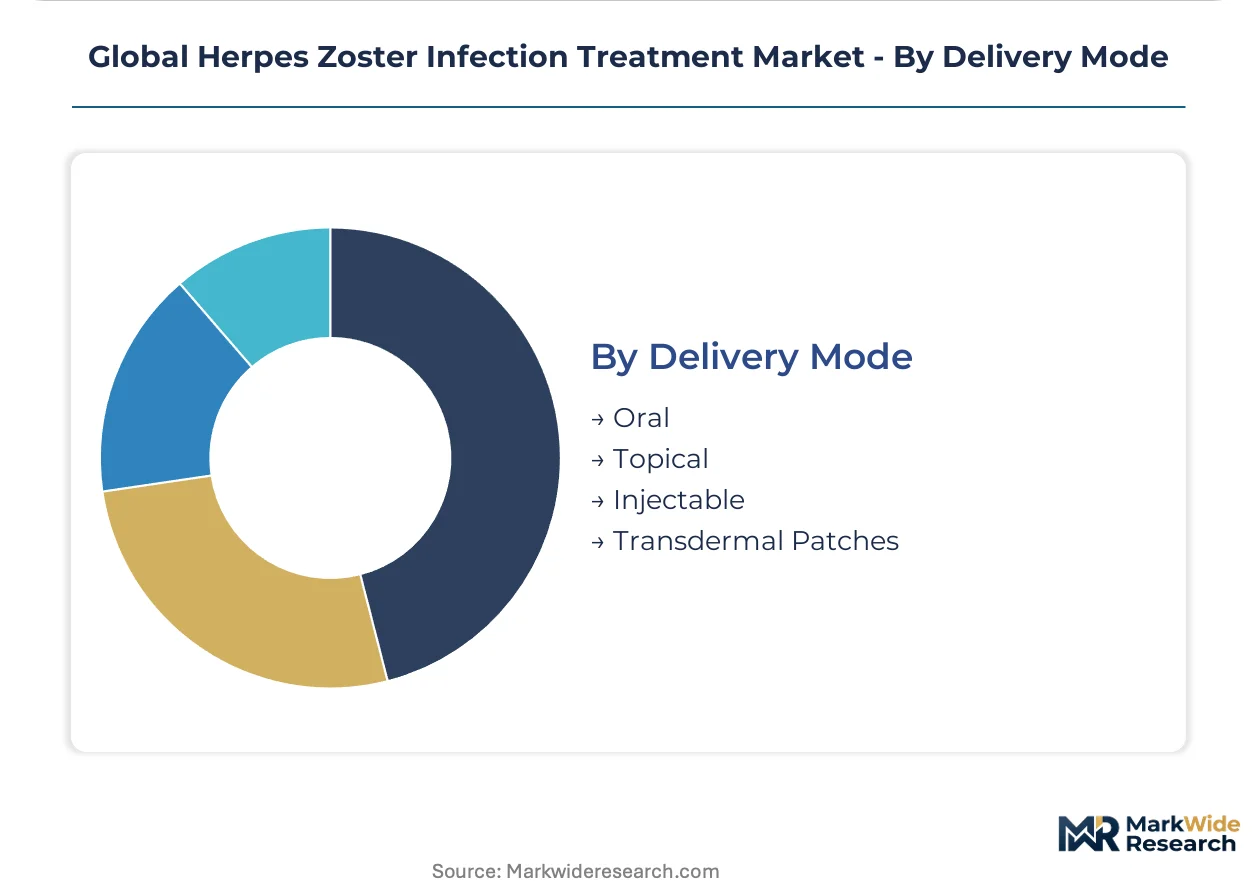
Delivery Mode:
Supply concentration varies by manufacturing complexity, with sterile injectable capacity constraining availability relative to commodified oral and topical formats.
- Injectable:Intravenous acyclovir and subcutaneous vaccine delivery require sterile fill-finish infrastructure with cold-chain integrity. Pfizer's integrated manufacturing network and GlaxoSmithKline's European bulk antigen facilities anchor supply for these high-value formats.
- Oral:Tablet and capsule formulations of nucleoside analogs and analgesics offer convenience and cost efficiency for outpatient compliance.
- Topical:Cream, gel, and ointment preparations provide localized antiviral or anesthetic effect with minimal systemic exposure.
- Transdermal Patches:Sustained-release lidocaine and capsaicin formulations deliver prolonged neuropathic pain modulation.
Oral delivery leads prescription volumes today; injectable formats are climbing fastest as recombinant vaccine adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting recombinant vaccine bulk production toward Ireland and Belgium, where EMA quality guidelines align with streamlined chemistry-manufacturing-controls dossier pathways. Developers exploit this arbitrage to compress approval timelines while maintaining FDA-equivalent standards for transatlantic market access.
United States
Medicare Advantage risk-bearing entities negotiate direct purchasing agreements for zoster vaccine formularies, consolidating procurement through specialty distributors. FDA's Division of Antiviral Products enforces divergent efficacy endpoints from EMA counterparts, forcing duplicate clinical trial designs. Boston and Research Triangle Park anchor infectious disease research clusters where hospital systems coordinate multidisciplinary protocols for immunocompromised patient management.
Germany
Hospital-based infectious disease services coordinate complex cases through multidisciplinary protocols for transplant recipients and oncology patients. EMA's Committee for Medicinal Products for Human Use offers priority review for novel antiviral formulations, accelerating development timelines. The Rhine-Ruhr and Bavarian biomanufacturing corridors concentrate sterile fill-finish capacity for injectable antiviral supply across European markets.
Japan
METI-supported biomanufacturing investments align with expanding eligible treatment pools for adults over 65, the fastest-aging demographic among developed economies. PMDA standards for recombinant adjuvanted vaccines prioritize non-live formulations for immunocompromised access. The Kanto and Kansai regions host pharmaceutical manufacturing clusters where cold-chain infrastructure supports regional distribution networks.
Ireland
Biologics manufacturing capacity is decoupling from traditional small-molecule production networks, creating dedicated supply corridors for antiviral therapies. EMA regulatory alignment and REACH compliance frameworks attract bulk antigen production investment. Cork and Dublin facilities anchor sterile bulk recombinant zoster antigen supply for European and North American markets.
India
CDSCO regulatory pathways for generic nucleoside analogs sustain commoditized oral antiviral production for domestic and export markets. BIS quality standards and PLI scheme incentives attract formulation manufacturing investment. Hyderabad and Ahmedabad clusters concentrate active pharmaceutical ingredient synthesis and oral dosage form production for acyclovir and valacyclovir supply.
Global Herpes Zoster Infection Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated delivery technologies and regional procurement eligibility. The vendor base stratifies across three maturity levels: integrated pharmaceutical conglomerates with captive biologics infrastructure, mid-scale generic manufacturers with formulation expertise, and specialty biotech developers targeting novel antiviral mechanisms. Dominant competitive moves include backward integration into sterile fill-finish capacity and strategic partnerships with specialty distributors serving immunology clinics.
Within the integrated pharmaceutical tier, GlaxoSmithKline and Pfizer exemplify archetypes of biologics manufacturing scale, with the former representing European bulk antigen production networks and the latter anchoring North American sterile injectable capacity. Merck & Co. occupies a position between these models, reflecting long-standing distributor relationships in institutional channels. These three entities collectively represent the concentration of recombinant adjuvanted vaccine supply and nucleoside analog antiviral distribution infrastructure across the United States, Germany, and Japan.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Merck & Co. |
| Pfizer |
| Viatris |
| Novartis |
| Sanofi |
| Apotex |
| Teva Pharmaceutical Industries |
| Takeda Pharmaceutical Company |
| Others |
Supply & Pricing Matrix
REACH and RoHS compliance requirements in Europe gate both qualified supply and premium-tier pricing access for herpes zoster treatments, forcing manufacturers to qualify alternative excipient suppliers and resubmit chemistry-manufacturing-controls dossiers before capturing margin-rich adjuvanted vaccine positions.
Pricing Analysis
Distributor margins in specialty immunology channels absorb significant value from recombinant adjuvanted vaccines, with three-tier pricing structure across premium, standard, and economy levels separating sterile injectable formulations from oral nucleoside analogs and commoditized pain relievers. Price differentiation hinges on cold-chain certification grade and manufacturing complexity tier. Cost compression in oral antiviral segments is intensifying because generic acyclovir and valacyclovir saturation erodes pricing power. Hospital procurement committees exhibit lowest price sensitivity due to protocol-driven formulary adherence, while outpatient urgent care settings demonstrate highest sensitivity to per-dose costs.
Supply Chain Analysis
Biologics process development talent scarcity in Ireland and Belgium concentrates sterile bulk antigen production among facilities with validated analytical method expertise. Supply draws from recombinant protein feedstocks, adjuvant components, and specialized cold-chain packaging materials. Single-source vulnerability persists for adjuvanted vaccine fill-finish operations clustered in Cork and Dublin facilities. Distribution runs through specialty distributors serving immunology clinics and hospital pharmacy committees, displacing fragmented physician-office purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herpes zoster infection treatment market functions as a stable compounder, with aging demographic expansion across developed economies providing predictable demand visibility for preventive and therapeutic portfolios.
For Market Incumbents: Acquire sterile fill-finish capacity in North American and European corridors to reduce third-party dependency for injectable formulations. Secure long-term relationships with specialty distributors serving immunology clinics to defend against integrated delivery network consolidation. Invest in EMA priority review pathway preparation to compress development timelines for novel antiviral formulations targeting immunocompromised populations.
For New Entrants and Emerging Players: Underserved home healthcare providers for elderly patients over 65 represent the most penetrable entry point, with oral antiviral regimens and patient education services offering lower capital barriers than biologics manufacturing. Target lower-middle-income countries expanding adult vaccination schedules through WHO prequalification procurement channels. Pursue partnership-based go-to-market models with established cold-chain distributors rather than captive infrastructure buildout.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale generic manufacturers with nucleoside analog formulation expertise because commoditized oral antiviral production generates steady cash flows while adjuvanted vaccine manufacturing faces capacity constraints. Monitor CDC Advisory Committee on Immunization Practices recommendation shifts as inflection indicators redirecting public and private payer budgets across competing preventive therapy categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive sterile fill-finish capacity reduces third-party dependency for Pfizer and GlaxoSmithKline injectable networks. |
| Regulatory Approval Pathway | EMA accelerated assessment compresses timelines for novel antiviral formulations targeting immunocompromised hospital populations. |
| Long-term Supply Agreement | Direct purchasing contracts between Medicare Advantage risk-bearing entities and specialty distributors consolidate vaccine procurement. |
| Clinical Trial Advancement | Divergent FDA-EMA efficacy endpoints force duplicate trial designs, inflating development costs for transatlantic market access. |
| Geographic Expansion | METI-supported biomanufacturing investments in Japan align with expanding eligible treatment pools for adults over 65. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down epidemiological projections were triangulated to anchor market size estimates.
Historical reference periods spanning the pre-pandemic baseline through recent immunization schedule expansions anchored the forecast window across the analysis window. Segmentation dimensions modeled include treatment modality, dosage form, patient immunocompetence status, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation, pricing trajectory analysis, and therapy area penetration curves, with inputs from hospital admission data for disseminated zoster cases and transplant volume projections for immunocompromised protocols.
Underlying measurement precision varies by segment; recombinant adjuvanted vaccines carry tighter precision than commoditized oral antivirals due to concentrated supplier field and visible procurement volumes. Forecasts reflect assumptions about CDC recommendation stability, EMA-FDA regulatory alignment, and cold-chain infrastructure deployment rates. Material deviation in immunization schedule prioritization or bulk antigen production capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market