
 Direct-Acting Antiviral Medicines Market | 2026-2036
Direct-Acting Antiviral Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-Acting Antiviral Medicines Market Outlook
Specialty pharmacy distribution is reshaping how direct-acting antiviral therapies reach hepatitis C and HIV patients. Gilead Sciences leverages its nucleotide polymerase inhibitor portfolio to sustain dominance in curative HCV regimens. AbbVie anchors its position through protease inhibitor combinations, while Merck competes with differentiated NS5A inhibitor offerings in price-sensitive markets.
Direct-acting antiviral medicines are small-molecule agents engineered to interrupt specific viral replication enzymes—NS5A, RNA-dependent RNA polymerase, or NS3/4A protease—typically formulated as once-daily oral fixed-dose combinations achieving sustained virologic response in over 95% of hepatitis C cases. The therapy area dimension shows hepatitis C as the mature revenue base with contracting patient pools, while COVID-19 antivirals represent the fastest-growing segment as health systems stockpile oral outpatient options. Oral delivery mode commands the deepest margin pools due to manufacturing scale and patient compliance advantages over injectable alternatives.
The FDA's Breakthrough Therapy designation and the EMA's PRIME scheme compress development timelines for novel antiviral combinations, while the WHO prequalification program shapes access in low-income markets. India's CDSCO and the PLI scheme for active pharmaceutical ingredients are altering where polymerase inhibitor synthesis occurs. Stakeholders must monitor how payer formularies reweight curative versus chronic therapy economics as patient volumes shift from hepatitis C toward emerging respiratory virus indications.
Market Dynamics
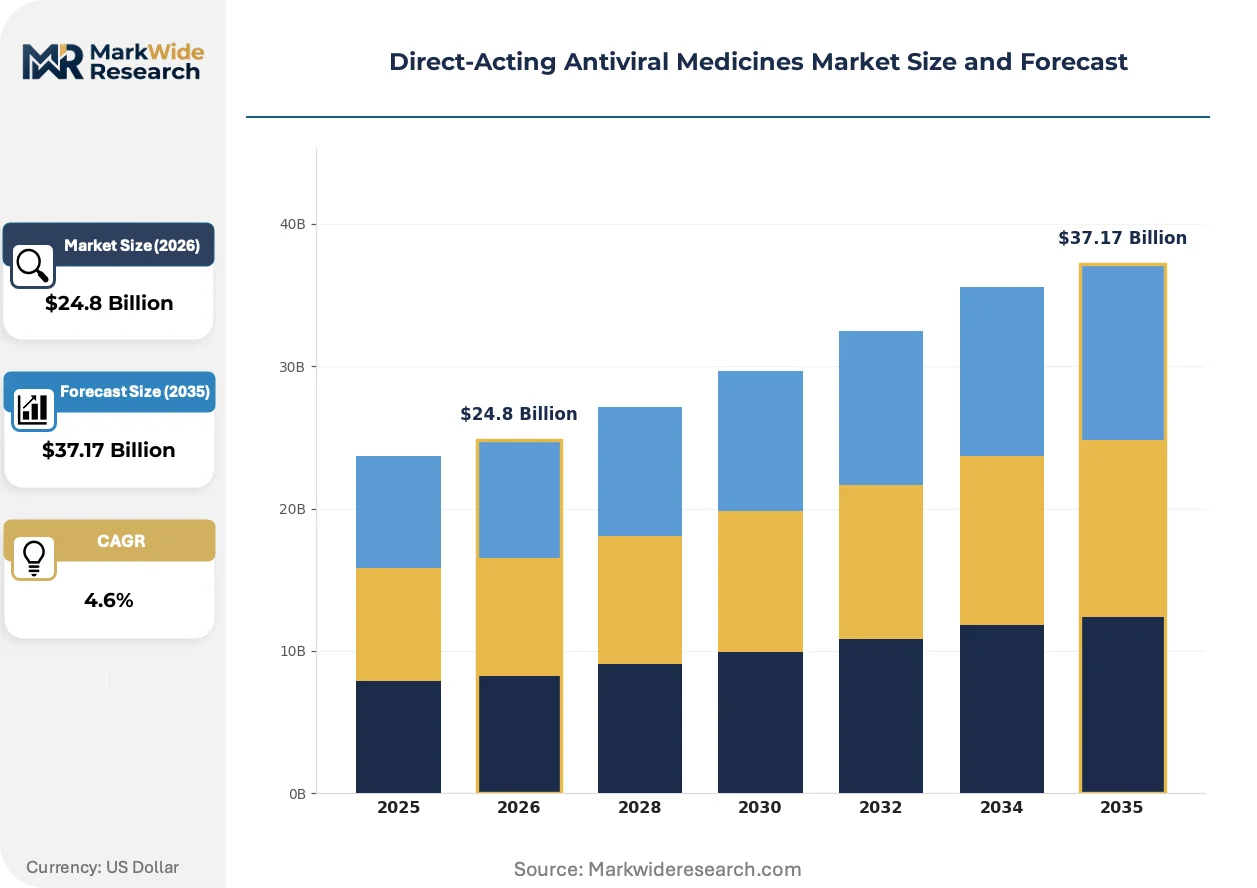
The Direct-Acting Antiviral Medicines Market pivots on the tension between curative therapy economics and contracting hepatitis C patient pools, forcing manufacturers to redirect polymerase inhibitor capacity toward respiratory virus indications while Medicare reimbursement policies accelerate hospital procurement of oral regimens.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's Breakthrough Therapy designation and EMA's PRIME scheme compress development timelines for novel antiviral combinations, enabling faster market entry for fixed-dose oral regimens.
- Medicare Reimbursement Realignment:US payer formularies now favor curative treatment models over chronic management, driving hospital procurement of complete hepatitis C therapy courses rather than episodic care.
- Polymerase Inhibitor Manufacturing Scale:India's PLI scheme for active pharmaceutical ingredients is expanding nucleotide analog synthesis capacity, reducing production bottlenecks for oral antiviral combinations.
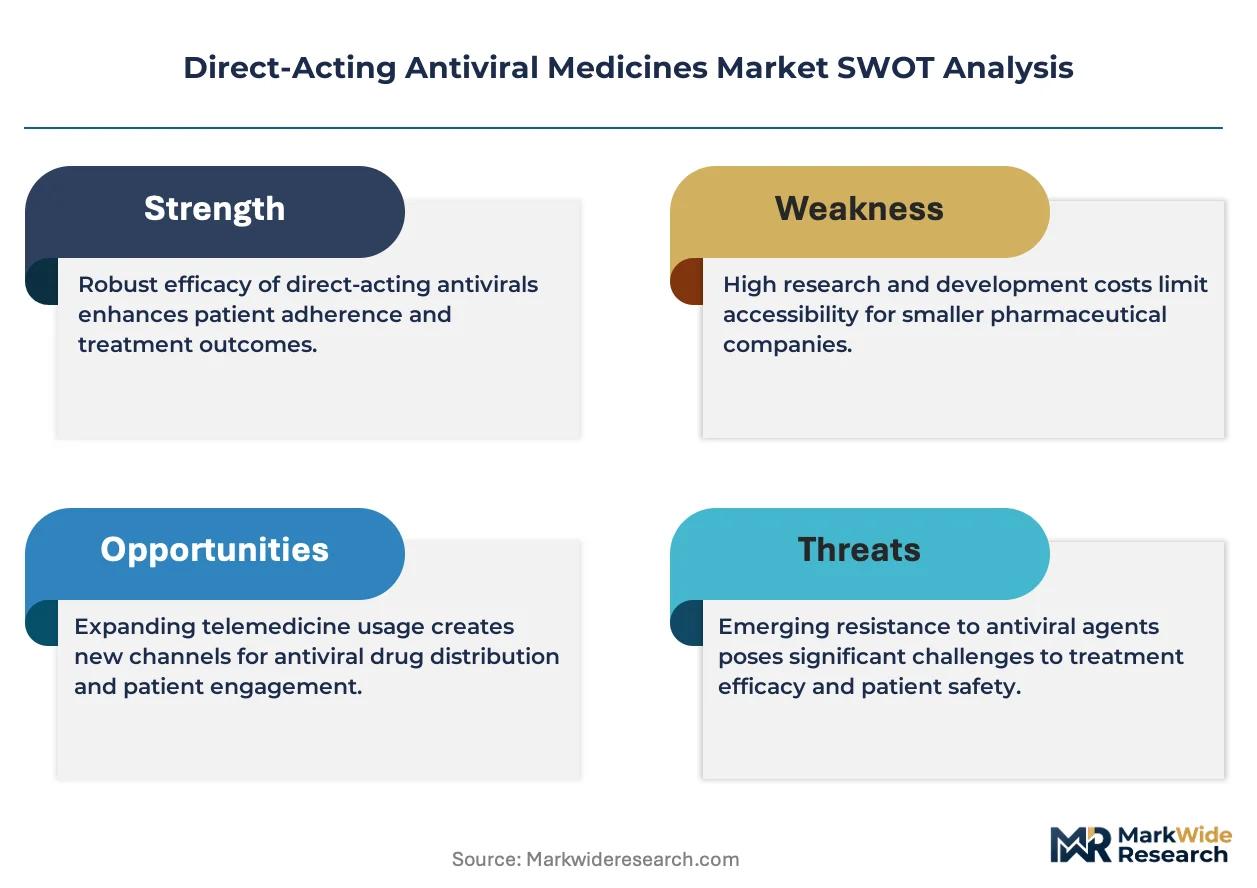
Market Restraints
- Hepatitis C Patient Pool Contraction:Sustained virologic response rates exceeding 95% are progressively eliminating the addressable population for HCV therapies in mature markets.
- NS5A Inhibitor Supply Concentration:Active pharmaceutical ingredient synthesis for NS5A complex inhibitors concentrates among a limited supplier base in South and East Asia, creating vulnerability to geographic disruption.
- Price Sensitivity in Emerging Markets:WHO prequalification requirements and compulsory licensing frameworks in low-income countries compress margins for originator antiviral products.
Strategic Opportunities
- Respiratory Virus Indication Expansion:RNA-dependent RNA polymerase inhibitors validated in hepatitis C are being repurposed for influenza and emerging coronavirus variants, opening outpatient antiviral stockpiling contracts.
- Specialty Pharmacy Channel Development:Direct-to-patient distribution models bypass traditional hospital pharmacy procurement, capturing margin through medication therapy management services.
- CDSCO Streamlined Registration:India's central drug regulator is harmonizing bioequivalence requirements for fixed-dose combinations, accelerating market access for oral antiviral generics.
Industry Challenges
- Antiviral Resistance Surveillance Infrastructure:Health systems lack systematic sequencing capacity to detect NS5A or NS3/4A mutations, complicating therapy selection and retreatment protocols.
- Fixed-Dose Combination Formulation Complexity:Achieving bioequivalence across multiple polymerase inhibitor classes with differing metabolic profiles requires specialized pharmaceutical development expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-Acting Antiviral Medicines Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NS5A Inhibitors, Polymerase Inhibitors, Protease Inhibitors, Others End User: Hospitals, Clinics, Pharmacies, Homecare Delivery Mode: Oral, Injectable, Transdermal, Others Therapy Area: Hepatitis C, COVID-19, HIV, Influenza |
| Companies Covered | Gilead Sciences, AbbVie, Merck, F. Hoffmann-La Roche, Bristol-Myers Squibb, Johnson & Johnson, GSK, Cipla, Aurobindo Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-Acting Antiviral Medicines Market Strategic Shifts
Antiviral development is pivoting from single-pathogen targets toward platform technologies applicable across RNA virus families, while regulatory frameworks and procurement models co-evolve to accommodate curative rather than chronic therapy paradigms.
Artificial intelligence-driven molecular design is digitizing the lead optimization process for RNA polymerase inhibitors. Large pharmaceutical developers deploy machine learning algorithms to predict resistance mutation profiles before clinical trials begin. Hospital formularies are digitizing their prior authorization workflows to match the compressed treatment timelines these predictive models enable.
The EMA's PRIME scheme is expanding eligibility criteria to include antiviral combinations addressing antimicrobial resistance threats. European health technology assessment bodies now evaluate curative therapies on lifetime cost-offset models rather than annualized treatment costs. Manufacturers targeting EU markets are restructuring clinical trial endpoints to demonstrate sustained virologic response durability.
Hospital procurement departments are consolidating antiviral purchasing through specialty pharmacy networks rather than traditional wholesale distributors. This channel shift concentrates buying power among three national pharmacy benefit managers in the United States. The model is compressing manufacturer margins while capturing patient adherence data that informs formulary positioning.
Direct-Acting Antiviral Medicines Market Segmentation
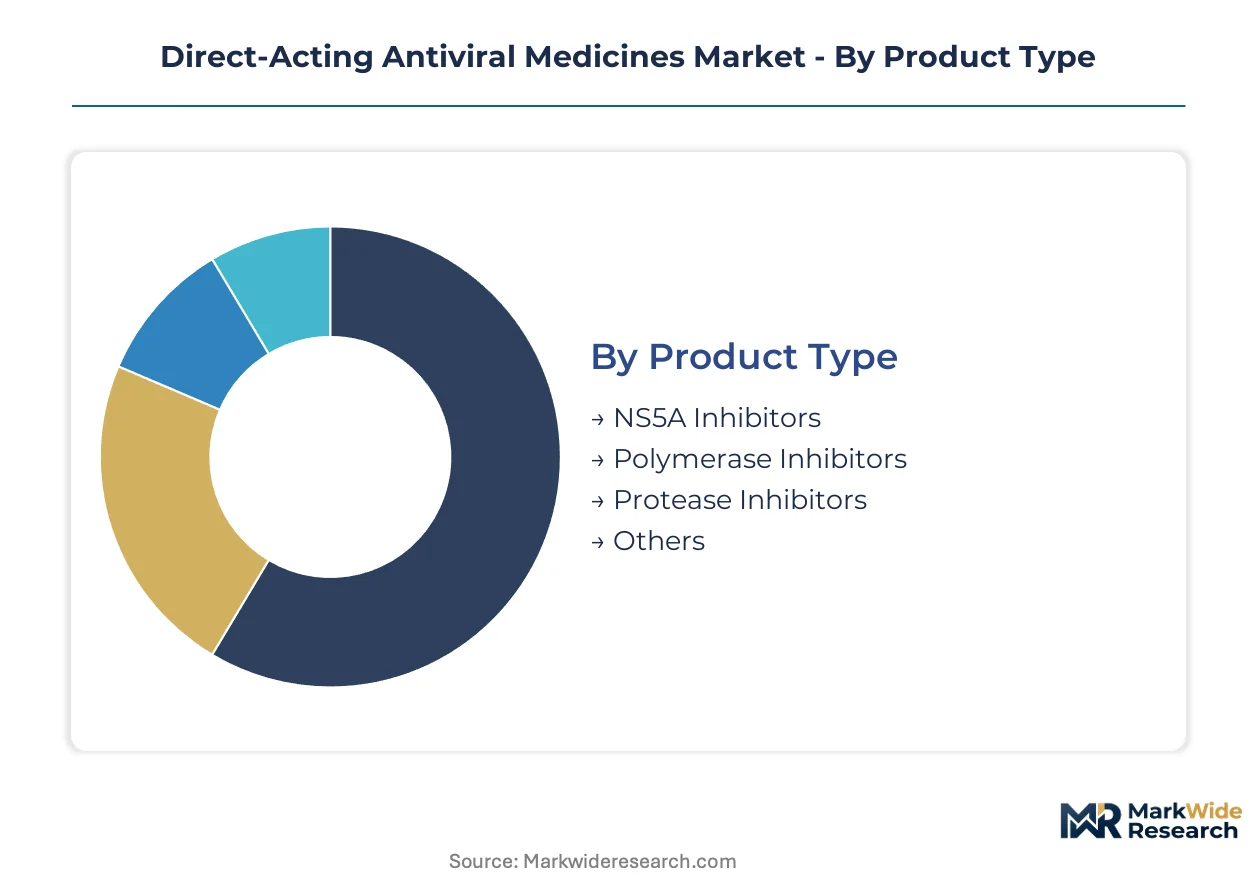
Segmentation of direct-acting antiviral medicines reveals how formulation chemistry, care setting economics, and disease-specific procurement patterns fragment commercial opportunity. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning across therapeutic categories.
Product Type:
Cost tier stratification across inhibitor classes determines manufacturing complexity and pricing power in procurement negotiations.
- NS5A Inhibitors:These agents block viral replication through domain I of the NS5A protein, requiring complex asymmetric synthesis routes. Hospital formularies in the United States prioritize these combinations for genotype 1a hepatitis C cases where resistance barriers matter most.
- Polymerase Inhibitors:Nucleotide and non-nucleotide analogs terminate RNA chain elongation by competing with natural substrates. India's PLI scheme is expanding active pharmaceutical ingredient capacity for these compounds as health systems stockpile oral regimens against respiratory RNA viruses.
- Protease Inhibitors:NS3/4A serine protease blockers prevent viral polyprotein cleavage. These retain relevance in retreatment protocols and HIV combination therapy.
- Others:Emerging host-targeting agents and entry inhibitors occupy niche positioning in antiviral development pipelines.
Polymerase inhibitors hold installed capacity. NS5A inhibitors are rotating up the share rankings.
End User:
Customer type determines reimbursement mechanics and adherence monitoring requirements across the care continuum.
- Hospitals:Inpatient and outpatient departments manage complex hepatitis C cases with cirrhosis complications. Medicare reimbursement policies in the United States now favor complete curative courses over episodic management, accelerating procurement of oral fixed-dose combinations through 340B programs.
- Clinics:Federally qualified health centers and infectious disease specialty practices handle high-volume hepatitis C screening and treatment initiation. These settings drive demand for simplified 8-12 week regimens with minimal monitoring requirements.
- Pharmacies:Specialty pharmacy networks capture medication therapy management revenue through direct-to-patient distribution models that bypass traditional hospital procurement.
- Homecare:Self-administered oral antiviral regimens enable treatment completion without facility visits, particularly relevant for COVID-19 outpatient therapy and stable HIV patients.
Hospitals anchor procurement volume. Specialty pharmacies are expanding fastest as distribution channels consolidate.
Delivery Mode:
Application format shapes bioavailability engineering, patient compliance economics, and manufacturing scale advantages.
- Oral:Once-daily fixed-dose tablets dominate hepatitis C and HIV therapy due to high barrier-to-resistance formulations and patient preference. Oral delivery commands the deepest margin pools through polymerase inhibitor manufacturing scale and compliance advantages over alternatives.
- Injectable:Long-acting formulations address adherence challenges in HIV pre-exposure prophylaxis and treatment-experienced populations. These require cold chain infrastructure and clinical administration that limits addressable settings.
- Transdermal:Patch-based delivery remains experimental for antiviral agents due to molecular weight constraints and skin permeability challenges.
- Others:Inhalation and intranasal routes are under investigation for respiratory virus prophylaxis and early treatment.
Oral formulations hold manufacturing scale. Injectable long-acting products are gaining share in HIV maintenance therapy.
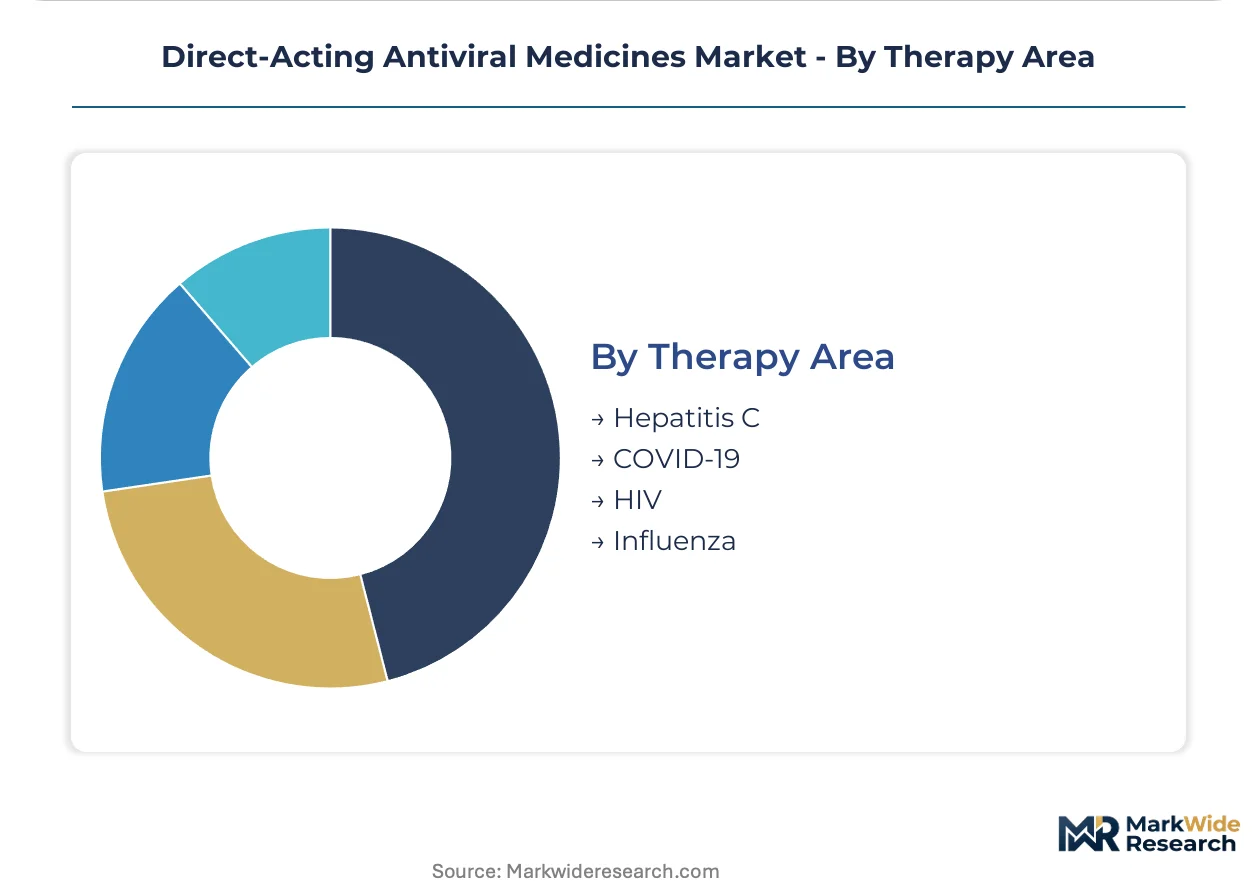
Therapy Area:
Maturity and growth trajectories diverge sharply across viral indications, with curative hepatitis C economics contrasting chronic disease management models.
- Hepatitis C:Sustained virologic response exceeding 95% has transformed this into a curative therapy market with contracting patient pools in mature markets. The FDA's Breakthrough Therapy designation compressed development timelines for fixed-dose combinations now facing pricing pressure from generic entry.
- COVID-19:RNA polymerase inhibitors validated in hepatitis C are being repurposed for SARS-CoV-2, driving the steepest expansion trajectory as governments stockpile oral outpatient options against variant emergence.
- HIV:Chronic suppressive therapy requires lifelong adherence, supporting premium pricing for integrase and protease inhibitor combinations with high resistance barriers.
- Influenza:Neuraminidase and polymerase inhibitors compete with vaccines for seasonal prophylaxis and treatment, with pandemic stockpiling contracts providing revenue visibility.
Hepatitis C holds installed manufacturing capacity. COVID-19 antivirals are rotating up the share rankings fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution for polymerase inhibitor active pharmaceutical ingredients. India's Jawaharlal Nehru Port Trust handles the bulk of generic antiviral API exports to WHO prequalification markets. The Shanghai Yangshan Deep Water Port underwrites China's role in NS5A inhibitor intermediate synthesis.
United States
Medicare reimbursement policies now favor complete curative hepatitis C courses over episodic management, accelerating hospital procurement through 340B programs. The FDA's Breakthrough Therapy designation compresses development timelines for novel fixed-dose combinations. The Boston-Cambridge biotech corridor concentrates RNA polymerase inhibitor discovery operations.
Germany
EMA's PRIME scheme enables accelerated assessment for antiviral combinations addressing antimicrobial resistance threats. German health technology assessment bodies evaluate curative therapies on lifetime cost-offset models rather than annualized treatment costs. The Rhine-Main pharmaceutical cluster around Frankfurt hosts nucleotide analog manufacturing facilities.
India
The CDSCO's streamlined bioequivalence requirements for fixed-dose combinations accelerate market access for oral antiviral generics. India's PLI scheme for active pharmaceutical ingredients expands polymerase inhibitor synthesis capacity. The Hyderabad-Visakhapatnam corridor concentrates NS5A inhibitor API manufacturing for export markets.
Switzerland
Swissmedic's alignment with EMA centralized procedures facilitates parallel market access for combination antiviral therapies. The country's bilateral free trade agreements with emerging markets enable preferential tariff treatment for originator products. The Basel pharmaceutical cluster anchors protease inhibitor formulation expertise.
Japan
PMDA's Sakigake designation system provides priority review for innovative antiviral regimens with superior resistance profiles. Japan's National Health Insurance price listing favors once-daily oral fixed-dose combinations with demonstrated sustained virologic response durability. The Kansai region around Osaka hosts specialized pharmaceutical manufacturing for HIV combination therapies.
Direct-Acting Antiviral Medicines Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the API and intermediate supply chain. The market structure concentrates around vertically integrated pharmaceutical developers with nucleotide polymerase inhibitor portfolios and generic manufacturers with cost-optimized synthesis capabilities. Two strategic archetypes dominate: originator developers leveraging regulatory exclusivity for premium-priced curative regimens, and high-volume generic producers capturing WHO prequalification and compulsory licensing markets. Competitive moves center on respiratory virus indication expansion and specialty pharmacy channel consolidation.
Among originator developers, Gilead Sciences and AbbVie occupy positions reflecting sustained investment in hepatitis C combination therapy platforms. Merck sits within the competitive set through differentiated NS5A inhibitor positioning. Cipla and Aurobindo Pharma represent the high-volume generic manufacturing archetype, with Indian corporate structures enabling cost-competitive supply to price-sensitive emerging markets. F. Hoffmann-La Roche, Bristol-Myers Squibb, Johnson & Johnson, and GSK each exemplify diversified pharmaceutical developers with antiviral assets integrated within broader infectious disease portfolios.
| Leading Market Players |
|---|
| Gilead Sciences |
| AbbVie |
| Merck |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| GSK |
| Cipla |
| Aurobindo Pharma |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's pharmaceutical cold chain corridors carry nucleotide polymerase inhibitor active pharmaceutical ingredients from Indian synthesis facilities to European formulation plants, with freight cost volatility amplifying margin pressure on originator products while enabling price differentiation between 340B-eligible hospital procurement and specialty pharmacy direct distribution.
Pricing Analysis
Three-tier pricing structure across premium originator, authorized generic, and compulsory-licensed economy levels dominates hepatitis C therapy procurement, with price differentiation driven by FDA Breakthrough Therapy certification status and volume scale through Medicare Part D formularies. Pricing pressure stems from WHO prequalification requirements in low-income markets compressing originator margins. Hospital procurement departments exhibit lowest price sensitivity due to 340B program protections, while emerging market ministries of health demonstrate highest sensitivity to per-treatment-course costs.
Supply Chain Analysis
Supplier-financing facilities extended by Indian API manufacturers to generic formulation partners in sub-Saharan Africa are reshaping working capital structures across the value chain. Geographic supply concentration centers on India, China, and Switzerland for nucleotide analog synthesis, with raw material dependencies on pyrimidine bases, phosphoramidite reagents, and specialized chiral intermediates. Single-source vulnerability concentrates in NS5A inhibitor asymmetric synthesis routes. Distribution runs through specialty pharmacy networks consolidating buying power among three national pharmacy benefit managers in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic imperatives as biosimilar interferon alternatives and emerging host-targeting antivirals threaten established polymerase inhibitor franchises. Incumbents must navigate curative therapy economics that progressively eliminate addressable hepatitis C populations.
For Market Incumbents: Entrench polymerase inhibitor manufacturing scale through backward integration into Indian API synthesis capacity under the PLI scheme, while securing specialty pharmacy channel control to capture medication therapy management revenue. Defend against NS5A inhibitor supply concentration risk by diversifying intermediate sourcing across the Hyderabad-Visakhapatnam corridor and Basel formulation clusters.
For New Entrants and Emerging Players: Southeast Asian markets with nascent hepatitis C screening infrastructure present the most penetrable white-space opportunity, particularly Vietnam and Indonesia where WHO prequalification pathways remain underutilized. Target respiratory virus indication expansion as governments stockpile oral antivirals against variant emergence. Pursue CDSCO streamlined registration for fixed-dose combination generics as the fastest go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underperforming antiviral assets stranded between hepatitis C market contraction and respiratory virus pivot requirements. Long-term viability hinges on platform technologies applicable across RNA virus families rather than single-pathogen dependence. Watch FDA Breakthrough Therapy designation velocity for emerging coronavirus polymerase inhibitors as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Respiratory Virus Indication Expansion | RNA polymerase inhibitors validated in hepatitis C access pandemic stockpiling contracts through FDA emergency use pathways. |
| Specialty Pharmacy Channel Consolidation | Direct-to-patient distribution models bypass hospital procurement and capture adherence data that informs formulary positioning. |
| Backward Integration into API Synthesis | India's PLI scheme enables captive supply of nucleotide analogs, reducing exposure to NS5A inhibitor supply concentration. |
| Regulatory Exclusivity Extension | EMA PRIME scheme and FDA Breakthrough Therapy designation compress development timelines for novel combination regimens. |
| Generics Portfolio Diversification | WHO prequalification and compulsory licensing frameworks in low-income markets create volume anchors against originator margin erosion. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base for this study. Primary interview findings combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation ensured cross-verified segmentation outputs.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning inhibitor class, therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from installed base erosion curves for hepatitis C and stockpiling contract visibility for respiratory virus indications. Forecast inputs incorporated Medicare reimbursement policy trajectories and CDSCO registration velocity for fixed-dose combination generics.
Practitioners should monitor FDA Breakthrough Therapy designation rates, EMA PRIME scheme eligibility expansion, and WHO prequalification queue depth for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding curative therapy durability and respiratory virus variant emergence patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Q Fever Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Virology Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Japanese Encephalitis Market