
 Global Herpes Simplex Virus Treatment Market | 2026-2036
Global Herpes Simplex Virus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Herpes Simplex Virus Treatment Market Foresight
Aftermarket service revenue from patient adherence programs and telehealth follow-up is tilting toward integrated care platforms. GlaxoSmithKline plc leverages its established antiviral manufacturing infrastructure to sustain bulk supply contracts across North America and Europe. Teva Pharmaceutical Industries Ltd. anchors its position through aggressive generic penetration of oral antiviral formulations. Pfizer Inc. differentiates via targeted R&D investment in next-generation nucleoside analogs with improved bioavailability profiles.
Herpes simplex virus treatment encompasses pharmaceutical and biologic interventions designed to suppress viral replication, reduce lesion severity, and limit transmission risk through inhibition of viral DNA polymerase. Oral antivirals such as acyclovir, valacyclovir, and famciclovir constitute the standard of care, typically administered in 400-1000 mg doses depending on indication and immune status. Among product type segments, oral antivirals command the dominant share due to established efficacy and payer familiarity, while suppressive therapy represents the fastest-expanding category as patients and providers prioritize outbreak prevention over reactive management. Within therapy areas, genital infection treatments generate the largest revenue pool, though mucocutaneous applications in immunocompromised populations are gaining clinical attention for specialized formulation development.
FDA bioequivalence standards and EMA quality guidelines for generic antivirals shape product entry timelines and manufacturing compliance costs across developed markets. India's CDSCO and China's NMPA maintain distinct bioavailability testing requirements that influence regional filing strategies for multinational sponsors. Stakeholders must monitor evolving pharmacovigilance mandates from WHO prequalification programs and national regulators as novel delivery mechanisms advance through clinical pipelines.
Market Dynamics
Hospital procurement of suppressive therapy regimens is tilting competitive dynamics toward long-term supply contracts and integrated care platforms, compressing margins for episodic treatment providers.
Growth Catalysts
- FDA Streamlined Pathways:Accelerated bioequivalence reviews for generic antivirals are shortening product entry timelines and expanding therapeutic access across managed care networks.
- Immunocompromised Patient Populations:Rising transplant volumes and oncology caseloads are creating specialized demand for mucocutaneous HSV prophylaxis with enhanced formulation stability.
- Telehealth Infrastructure:Remote consultation platforms are reducing diagnostic friction and sustaining prescription continuity for suppressive therapy patients in rural and underserved areas.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bulk acyclovir and valacyclovir production clusters in specific Asian manufacturing zones, creating single-source vulnerability for finished dose formulators.
- EMA Quality Compliance Costs:Stringent bioavailability documentation requirements for generic antivirals are elevating filing expenses and discouraging mid-tier sponsor participation.
- Topical Formulation Limitations:Poor dermal penetration of nucleoside analogs restricts efficacy for cutaneous lesions, ceding share to systemic oral alternatives despite patient preference for localized therapy.
Strategic Opportunities
- Indian CDSCO Registration:Distinct bioavailability testing protocols create first-mover positioning for sponsors establishing local manufacturing partnerships ahead of multinational generic entry.
- Long-Acting Injectable Convergence:Depot formulation technology combined with polymer-based sustained-release matrices offers monthly dosing alternatives to daily oral regimens.
- WHO Prequalification Alignment:Pharmacovigilance harmonization for novel delivery mechanisms opens procurement channels for public health programs in low-income country markets.
Industry Challenges
- Virology Specialist Scarcity:Limited pipeline of infectious disease clinicians trained in HSV resistance pattern recognition constrains optimal suppressive therapy titration.
- Cross-Border Serialization:Divergent track-and-trace mandates between FDA DSCSA and EU FMD are complicating packaging line configurations for multi-market antiviral shipments.
- Patent Thicket Navigation:Prodrug modification claims surrounding valacyclovir derivatives are generating licensing disputes that delay next-generation nucleoside analog development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Herpes Simplex Virus Treatment Market |
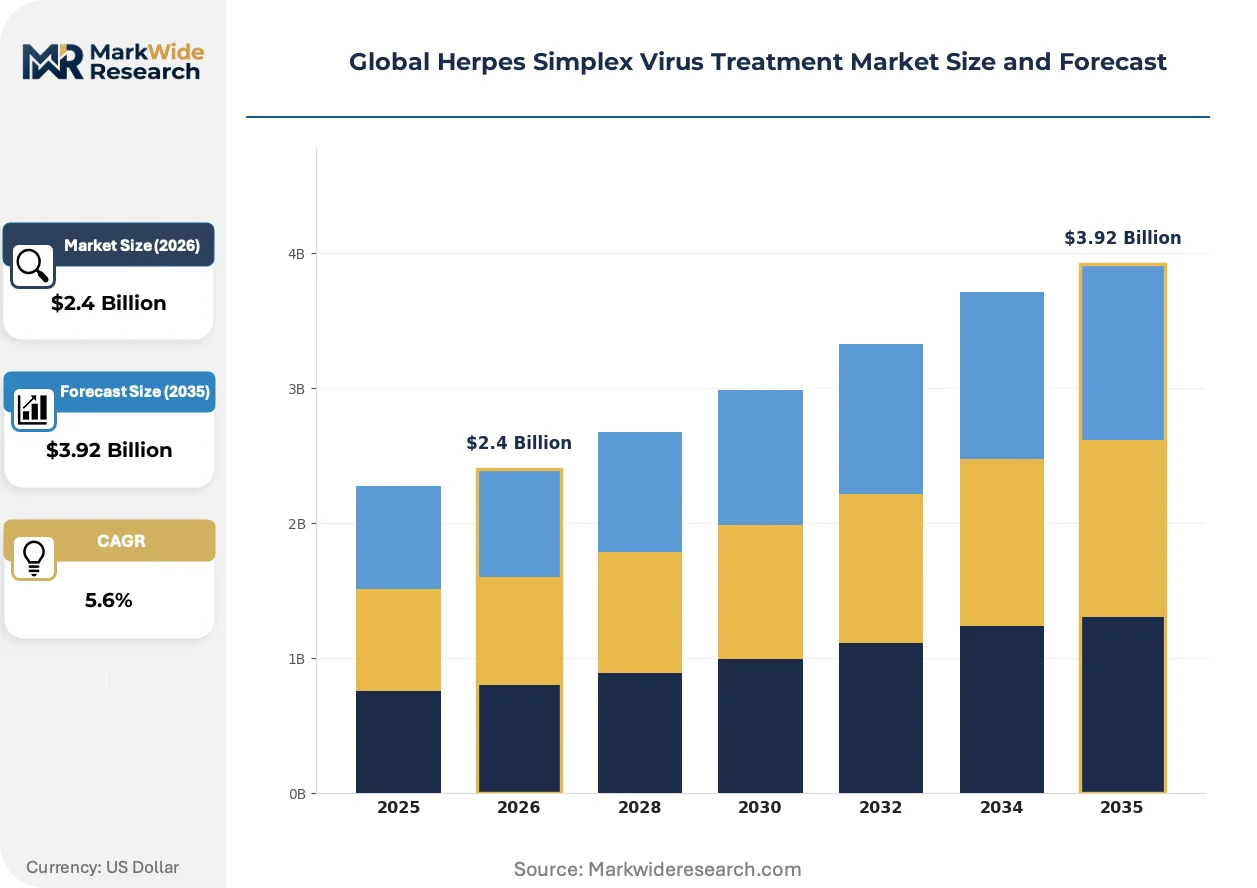
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Creams, Oral Antivirals, Topical Ointments, Injectable Medications, Suppressive Therapy Therapy Area: Genital Infection, Oral Infection, Neonatal Infection, Ocular Infection, Mucocutaneous Infection End User: Hospitals, Specialized Clinics, Diagnostic Laboratories, Home Healthcare Providers, Sexual Health Centers Distribution Channel: Pharmacies, Online Retailers, Hospital Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Viatris Inc., Novartis AG, Pfizer Inc., Fresenius Kabi AG, Glenmark Pharmaceuticals Inc., Emcure Pharmaceuticals Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Herpes Simplex Virus Treatment Market Shifts & Advancements
Delivery mechanism innovation and regulatory pathway evolution are compressing development cycles while fragmenting competitive positioning across branded and generic antiviral portfolios.
Lipid nanoparticle encapsulation of nucleoside analogs is hybridizing oral and topical administration routes, enabling lymphatic-targeted drug delivery with reduced systemic exposure. Dermatology clinics and transplant centers are piloting these formulations for mucocutaneous prophylaxis. The technology is hybridizing competitive dynamics by creating specialty formulation niches distinct from commodity oral tablets.
EMA's revised bioequivalence guidelines for highly variable drugs are tightening statistical criteria for generic antiviral approvals, extending study duration and sample size requirements. Sponsors face elevated clinical trial costs and compressed filing windows as the agency implements centralized assessment procedures. Oral antiviral manufacturers with established European manufacturing footprints are responding by consolidating quality control operations to reduce batch-to-batch variability documentation burdens.
Integrated pharmacy benefit managers are unbundling adherence monitoring from prescription fulfillment, creating standalone service contracts for telehealth-enabled suppressive therapy management. This disintermediation pressures traditional retail pharmacy margins while opening revenue pools for digital health platforms. The United States exhibits the most pronounced shift, where large payers are directly contracting with remote patient monitoring vendors to reduce emergency department visits for breakthrough outbreaks.
Global Herpes Simplex Virus Treatment Market Segmentation
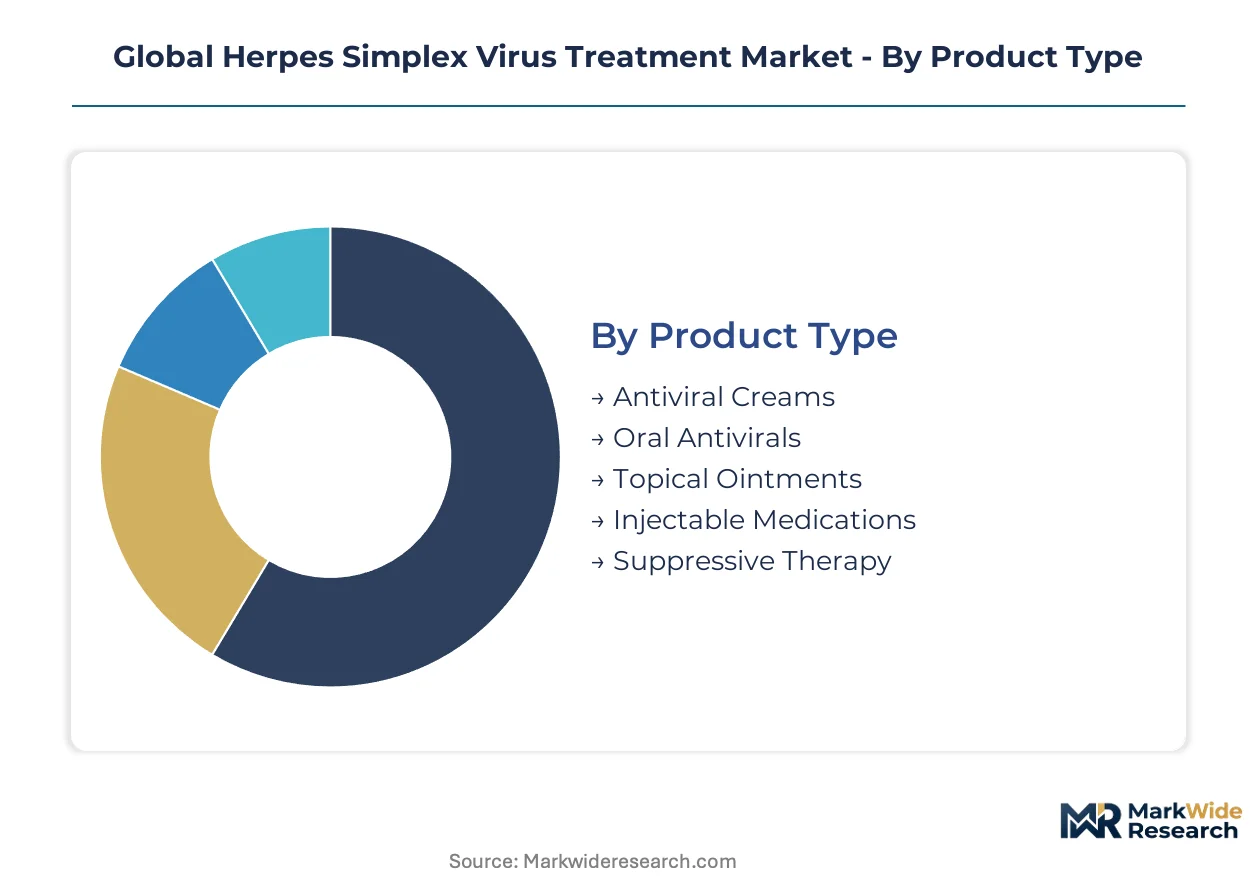
Segmentation in the herpes simplex virus treatment market reveals divergent procurement rhythms across product categories, with oral formulations commanding predictable replenishment cycles while injectable and suppressive modalities stretch inventory turnover. Therapy area fragmentation creates distinct clinical gatekeepers, from sexual health centers managing genital infections to ophthalmology specialists handling ocular presentations. Understanding these segment dynamics enables manufacturers to align supply chain investments with actual consumption velocity rather than aggregate demand signals.
Product Type:
Oral antivirals rotate through pharmacy shelves fastest due to standardized dosing protocols and broad prescriber familiarity, while injectable medications sit longest in cold-chain inventory awaiting specialized administration settings.
- Oral Antivirals:Systemic nucleoside analogs including acyclovir, valacyclovir, and famciclovir delivered in 400-1000 mg tablet or capsule forms. Demand concentrates in United States retail pharmacy networks where high diagnosis rates and reimbursement coverage sustain prescription continuity for both episodic and suppressive indications.
- Suppressive Therapy:Long-term daily regimens designed to reduce outbreak frequency and asymptomatic shedding. Adoption is accelerating fastest among managed care populations in Germany and the United Kingdom where clinicians favor proactive viral suppression over reactive lesion management.
- Antiviral Creams:Topical formulations for cutaneous lesion application with limited dermal penetration. United Kingdom dermatology clinics represent a concentrated demand node for combination therapy protocols.
- Topical Ointments:Petroleum-based vehicles delivering nucleoside analogs to mucocutaneous surfaces. Patient preference for localized therapy drives steady demand in France and Italy despite efficacy gaps versus systemic alternatives.
- Injectable Medications:Intravenous formulations reserved for severe disseminated infections or central nervous system involvement. United States hospital systems maintain strategic stockpiles for immunocompromised patient populations.
Oral antivirals anchor the volume base while suppressive therapy gains share at the steepest rate.
Therapy Area:
Genital infection treatments generate the largest revenue pool due to stigma-driven treatment-seeking behavior and sexual health screening expansion, whereas neonatal applications command premium pricing despite restricted volume.
- Genital Infection:Pharmaceutical interventions targeting HSV-2 replication in anogenital mucosa with transmission risk reduction endpoints. United States sexual health centers and telehealth platforms drive concentrated demand as remote consultation reduces diagnostic friction for stigmatized presentations.
- Mucocutaneous Infection:Specialized prophylaxis and treatment for immunocompromised patients including transplant recipients and oncology cohorts. Germany's transplant center network generates outsized demand for enhanced formulation stability in prophylactic protocols.
- Oral Infection:Labialis and gingivostomatitis management spanning pediatric and adult populations. Over-the-counter availability in Japan and Australia segments demand between prescription and self-directed care pathways.
- Ocular Infection:Keratitis and blepharitis interventions requiring ophthalmology specialist gatekeeping. France maintains dedicated HSV ocular treatment protocols through its hospital-based ophthalmology referral network.
- Neonatal Infection:High-acuity interventions for perinatally acquired HSV with mortality reduction endpoints. United States maternal-fetal medicine specialists drive protocol-driven demand concentrated in academic medical centers.
Genital infection treatments sustain the revenue foundation while mucocutaneous applications expand most quickly on transplant volume growth.
End User:
Hospitals and specialized clinics operate on formal tender cycles with 12-24 month contract horizons, whereas home healthcare providers and sexual health centers replenish on rolling monthly schedules.
- Hospitals:Inpatient and emergency department settings managing severe or disseminated HSV presentations. United States health systems are consolidating antiviral procurement through centralized pharmacy and therapeutics committees.
- Sexual Health Centers:Dedicated clinics providing confidential screening, diagnosis, and treatment for genital HSV. United Kingdom's integrated sexual health services generate concentrated demand for suppressive therapy initiation.
- Specialized Clinics:Dermatology, infectious disease, and ophthalmology practices managing complex or recurrent cases. Germany's ambulatory specialist sector maintains preference for branded formulations with established bioavailability documentation.
- Home Healthcare Providers:Services delivering long-term suppressive therapy to mobility-limited or rural populations. Telehealth-integrated platforms in Australia are expanding this channel's reach beyond metropolitan centers.
- Diagnostic Laboratories:PCR and serology facilities confirming HSV infection to guide treatment selection. France's centralized laboratory network influences downstream prescribing patterns through rapid turnaround protocols.
Hospitals anchor the institutional procurement base while sexual health centers capture the steepest volume expansion trajectory on screening program scaling.
Distribution Channel:
Pharmacies and hospital pharmacies dominate volume throughput with established cold-chain and controlled-substance handling capabilities, while online retailers and direct sales compress delivery timelines for specific patient segments.
- Pharmacies:Community and retail outlets dispensing oral antivirals and topical formulations. United States independent and chain pharmacies maintain the deepest inventory positions for episodic treatment regimens.
- Hospital Pharmacies:Captive dispensaries serving inpatient units and affiliated outpatient clinics. Germany's hospital pharmacy federation enforces stringent sourcing standards that favor established European manufacturers.
- Online Retailers:Digital platforms enabling discreet procurement of recurring suppressive prescriptions. United Kingdom pharmacy-led online services are capturing share from traditional retail through subscription-based adherence programs.
- Wholesalers:Regional distributors managing bulk inventory and logistics for multi-site pharmacy networks. McKesson and Alliance Healthcare maintain dominant positions in North American and European distribution respectively.
- Direct Sales:Manufacturer-to-provider arrangements for specialized or high-value formulations. Japan's hospital purchasing cooperatives leverage direct contracts to secure favorable pricing on novel delivery mechanisms.
Pharmacies sustain the volume foundation while online retailers climb the fastest on telehealth integration and patient preference for discreet fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients favor daily suppressive regimens over episodic treatment, while German clinicians emphasize prophylactic protocols for immunocompromised cohorts. Japanese consumers split demand between prescription oral antivirals and over-the-counter topical alternatives. India's market concentrates on generic acyclovir penetration through domestic manufacturing clusters.
United States
Telehealth platforms and sexual health screening expansion drive suppressive therapy adoption. FDA streamlined bioequivalence reviews accelerate generic antiviral entry timelines. Massachusetts and California biotech corridors host nucleoside analog R&D facilities advancing polymer-based sustained-release formulations.
Germany
Transplant center networks generate specialized demand for mucocutaneous HSV prophylaxis with enhanced stability. EMA quality compliance mandates elevate bioavailability documentation standards for generic sponsors. Baden-Württemberg pharmaceutical manufacturing clusters consolidate quality control operations to reduce batch variability burdens.
Japan
Over-the-counter topical availability segments demand between prescription and self-directed care pathways. PMDA maintains distinct pharmacovigilance requirements for novel delivery mechanisms. Tokyo and Osaka metropolitan areas concentrate dermatology clinic networks piloting lipid nanoparticle encapsulation technologies.
India
Domestic generic manufacturing anchors oral antiviral supply for export markets. CDSCO bioavailability testing protocols create first-mover positioning for local manufacturing partnerships. Hyderabad and Mumbai pharmaceutical clusters expand bulk acyclovir production capacity serving multinational formulation sponsors.
United Kingdom
Integrated sexual health services drive concentrated suppressive therapy initiation through confidential screening programs. NHS procurement frameworks favor long-term supply contracts over episodic treatment purchasing. London and Manchester telehealth-integrated pharmacy platforms capture share through subscription-based adherence programs.
Global Herpes Simplex Virus Treatment Market Competitive Landscape
Capability concentration sits with established antiviral manufacturers possessing integrated manufacturing infrastructure; scale advantage sits with generic specialists leveraging high-volume production economics. The competitive structure stratifies across three tiers: multinational innovators with proprietary nucleoside platforms, mid-tier generic houses with regional distribution depth, and emerging market manufacturers competing on API cost position. Dominant competitive moves include vertical integration into active pharmaceutical ingredient supply and strategic partnerships with telehealth platforms for patient adherence program delivery.
Within the multinational innovator tier, GlaxoSmithKline plc and Pfizer Inc. exemplify established antiviral manufacturing infrastructure. Among generic penetration specialists, Teva Pharmaceutical Industries Ltd. occupies a position representing aggressive oral formulation commoditization. These three anchors illustrate divergent strategic postures: proprietary platform development versus high-volume generic manufacturing versus integrated care ecosystem participation.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Novartis AG |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Glenmark Pharmaceuticals Inc. |
| Emcure Pharmaceuticals Ltd. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian bulk acyclovir manufacturing zones is compressing API spot prices and forcing formulation sponsors toward long-term offtake contracts to secure supply continuity. This utilization dynamic tilts supplier behavior toward volume guarantees while enabling buyers to extract pricing concessions through committed purchase obligations.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational sponsors and Asian API manufacturers, displacing spot-market purchasing for nucleoside analog inputs. Price differentiation rests on bioavailability certification tier and geographic delivery cost, with FDA-inspected facilities commanding premiums over CDSCO-registered alternatives. Cost compression in generic oral tablet segments is intensifying because Teva and Viatris are expanding high-volume production economics. Sexual health centers and telehealth platforms exhibit the highest price sensitivity, while transplant centers and academic medical centers prioritize formulation stability over unit cost.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk planning for finished dose formulators dependent on cross-border API shipments. Bulk acyclovir and valacyclovir production concentrates in India, China, and South Korea, with formulation finishing distributed across North America and Europe. Raw material dependencies include nucleoside base chemicals, polymer excipients for sustained-release matrices, and specialized cold-chain packaging. Single-source vulnerability persists for high-purity API grades serving immunocompromised patient formulations. Distribution runs through McKesson and Alliance Healthcare wholesaler networks in developed markets, with direct manufacturer-to-hospital contracts gaining share in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The suppressive therapy shift and FDA's accelerated bioequivalence reviews are disrupting competitive positioning, creating openings for sponsors with novel delivery mechanisms and integrated adherence platforms.
For Market Incumbents: Insulate market position by securing captive supply of nucleoside base chemicals through backward integration into Indian API manufacturing partnerships. Invest in polymer-based sustained-release R&D to differentiate from commodity oral tablets as generic penetration intensifies. Threats from lipid nanoparticle encapsulation technologies and telehealth-integrated adherence platforms demand preemptive response through licensing or acquisition. For New Entrants and Emerging Players: Establish a beachhead in mucocutaneous prophylaxis for transplant and oncology populations, where formulation stability requirements create barriers to generic commoditization. Target Germany's transplant center network and United States academic medical centers with enhanced stability claims and specialist education programs. A go-to-market angle through infectious disease specialist societies and hospital pharmacy committees bypasses saturated retail pharmacy channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated care platforms combining suppressive therapy dispensing with telehealth follow-up and adherence monitoring. Long-term viability across the analysis window favors sponsors with WHO prequalification alignment and low-income country procurement access. Acquisition targets should exhibit depot formulation technology capabilities or established CDSCO manufacturing partnerships. The signal to watch is EMA bioequivalence guideline tightening, which will elevate clinical trial costs and accelerate consolidation among mid-tier generic sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Development | Depot formulations reduce daily dosing burden and improve adherence in suppressive therapy populations. |
| CDSCO Manufacturing Partnership | Local production access accelerates bioavailability testing and first-mover positioning in Indian generic markets. |
| Telehealth Platform Integration | Remote consultation infrastructure reduces diagnostic friction and sustains prescription continuity for suppressive patients. |
| WHO Prequalification Alignment | Harmonized pharmacovigilance standards open procurement channels for public health programs in low-income countries. |
| Polymer Excipient Supply Agreement | Sustained-release matrix materials anchor next-generation nucleoside analog differentiation against commodity tablets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and infectious disease specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates across product type and therapy area segments.
Forecast inputs span treatment line, dosage form, patient immune status, and regional regulatory cluster variations. Growth trajectories were derived from segment-level volume projections and pricing dynamics across the projection horizon. Industry-specific inputs include transplant volume growth, sexual health screening expansion rates, and telehealth platform penetration by geography.
Sensitivities concentrate around EMA bioequivalence guideline implementation timelines, API manufacturing zone regulatory inspections, and suppressive therapy reimbursement policy shifts. Forecasts reflect documented assumptions regarding patient adherence rates and generic entry sequencing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Valley Fever Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Efavirenz Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Measles Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market