
 Chikungunya Fever Market | 2026-2036
Chikungunya Fever Market Size, Share, and Industry Trends Forecast 2026-2036
Chikungunya Fever Market Analysis
Multi-source vaccine procurement is expanding as governments diversify beyond single-supplier dependence for epidemic preparedness. Takeda Pharmaceutical leverages its dengue vaccine infrastructure to anchor chikungunya development programs across Latin America. Serum Institute of India sustains cost-competitive manufacturing scale that dominates public-sector tender markets. Valneva differentiates through specialized adjuvant platforms designed for tropical disease indications.
Chikungunya fever constitutes an alphavirus-induced arthropod-borne disease characterized by acute febrile polyarthralgia, with diagnostic confirmation requiring RT-PCR detection within five days of symptom onset or serological IgM/IgG differentiation thereafter. The condition primarily burdens healthcare systems through prolonged arthritic disability and recurrent outpatient utilization in endemic zones. Vaccines command the highest development priority among product types, with multiple candidates advancing through Phase III evaluation for traveler and endemic-population indications. Hospital care settings capture concentrated therapeutic demand during acute outbreak phases, while home care and outpatient clinics manage the extended arthritic sequelae that define disease burden. Injectable delivery modes dominate vaccine administration, though oral analgesics sustain volume across the treatment setting spectrum.
FDA, EMA, and WHO prequalification frameworks collectively shape market access timelines, with stringent cold-chain requirements filtering manufacturer participation in tropical distribution networks. National regulators in Brazil and India enforce localized stability testing that extends registration timelines for foreign-developed candidates. Stakeholders must monitor vector ecology shifts and arbovirus co-circulation patterns that alter target-product profiles for combination vaccines.
Market Dynamics
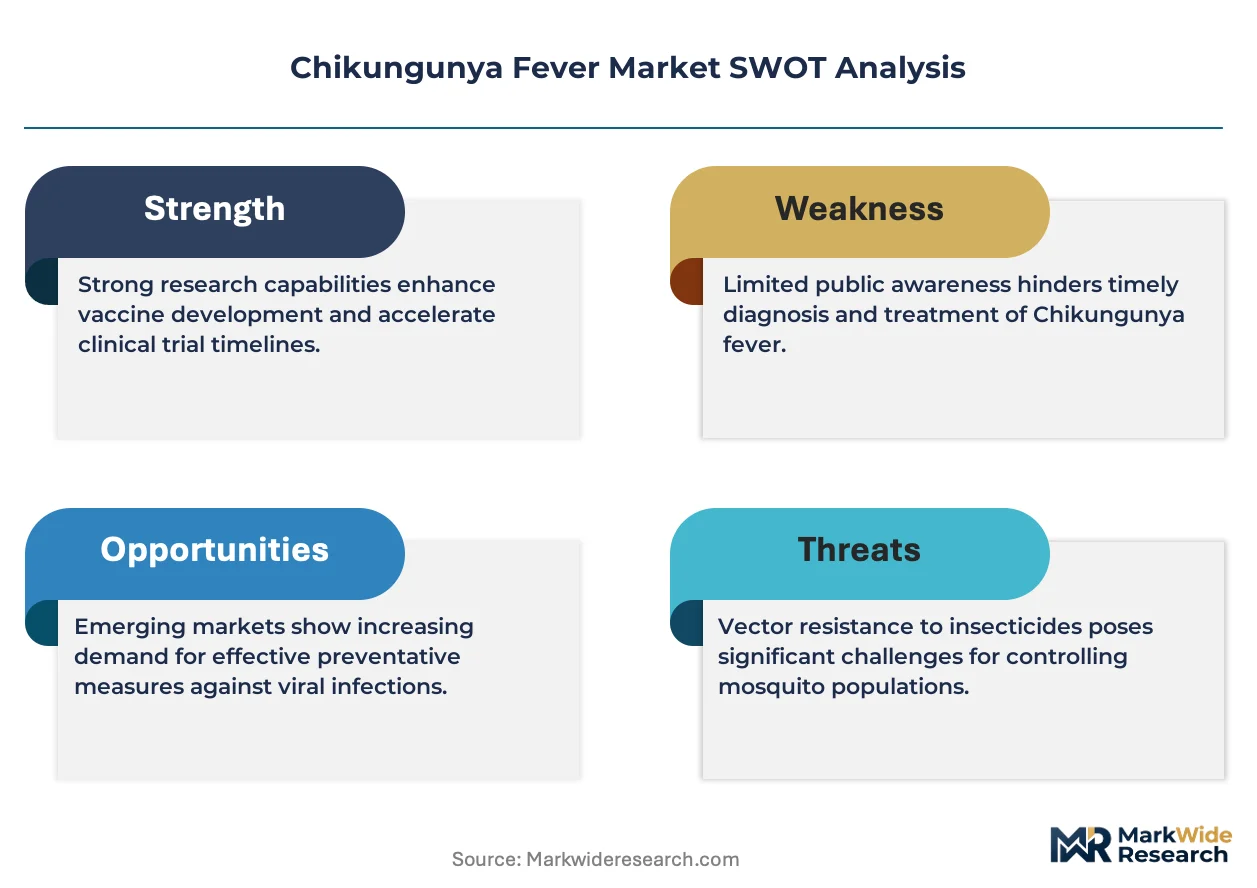
WHO prequalification pathways are compressing manufacturer access timelines while tropical health ministries expand vector control budgets alongside therapeutic procurement, creating dual-demand pressure across endemic zones.
Growth Catalysts
- Public health immunization programs:Brazil, India, and Thailand are accelerating vaccine procurement through national tender processes, expanding addressable demand for prequalified candidates.
- EMA accelerated assessment pathways:European regulators have designated chikungunya vaccines as priority medicines, shortening review timelines for traveler-indication submissions.
- RT-PCR diagnostic infrastructure:Molecular testing capacity expansion in Latin American hospital networks is enabling earlier case confirmation and targeted therapeutic intervention.
Market Restraints
- Cold-chain distribution costs:Stringent temperature requirements for vaccine stability inflate logistics expenditure across tropical distribution networks with unreliable electricity infrastructure.
- Serological cross-reactivity:Diagnostic differentiation between chikungunya, dengue, and Zika IgM/IgG antibodies requires specialized laboratory capacity that concentrates in urban referral centers.
- Single-supplier dependence risk:Historical procurement patterns in Southeast Asian public health systems have created vulnerability to supply disruption during epidemic surges.
Strategic Opportunities
- Combination vaccine development:Arbovirus co-circulation patterns in Brazil are creating demand for tetravalent dengue-chikungunya-Zika-yellow fever candidates.
- Outpatient arthritic sequelae management:Extended disability care in Indian home care settings represents underpenetrated therapeutic volume beyond acute hospitalization.
- ANVISA localized stability testing:Brazil's national regulator offers pathway for foreign manufacturers to establish domestic fill-finish operations, reducing import dependency.
Industry Challenges
- Vector ecology surveillance gaps:Aedes mosquito population monitoring requires entomological expertise that public health agencies struggle to retain in endemic rural districts.
- Phase III trial execution complexity:Epidemic unpredictability complicates endpoint accumulation, forcing adaptive trial designs that extend regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chikungunya Fever Market |
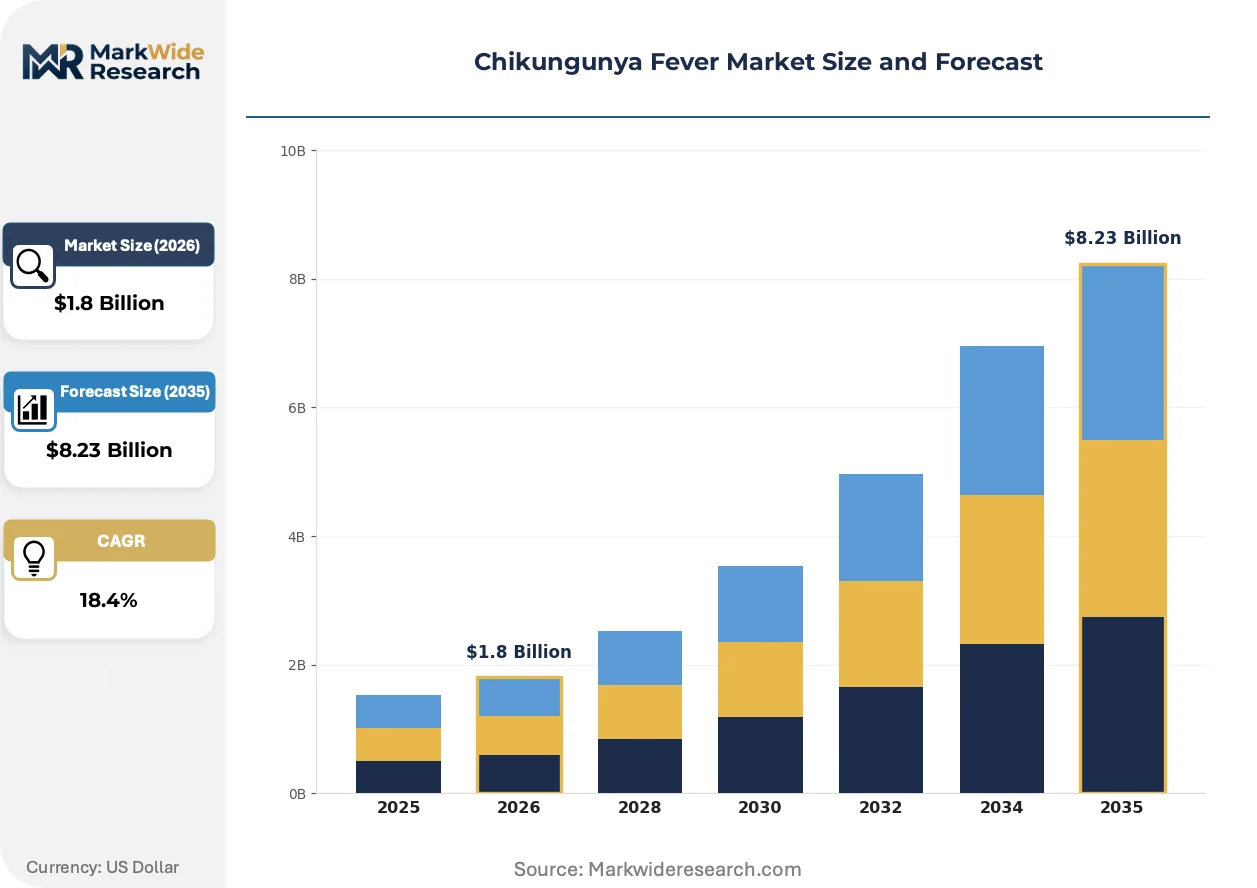
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disease-Modifying Antirheumatic Drugs, Nonsteroidal Anti-Inflammatory Drugs, Vaccines, Antivirals Treatment Setting: Home Care, Hospital Care, Outpatient Clinics, Community Health Services Patient Demographic: Adults, Children, Elderly, Pregnant Women Delivery Mode: Injectable, Oral, Intravenous, Topical |
| Companies Covered | Takeda Pharmaceutical Co. Ltd., Serum Institute of India Pvt. Ltd., Sanofi S.A., GlaxoSmithKline plc, Emergent BioSolutions Inc., Moderna, Inc., Bharat Biotech International Ltd., Zydus Lifesciences Ltd., Valneva SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chikungunya Fever Market Emerging Trajectories
Novel adjuvant platforms and synthetic biology approaches are compressing development timelines while reshaping competitive positioning across tropical disease indications.
Live-attenuated vaccine platforms are rewriting the standard for durable neutralizing antibody response in alphavirus indications. Travel medicine clinics in European and North American departure cities are adopting these candidates for pre-exposure prophylaxis. The technology is compressing the dosing schedule from multi-injection priming to single-dose protection, enabling pharmacy-based administration.
FDA's tropical disease priority review voucher program is channeling development resources toward chikungunya candidates with dual traveler-endemic population labeling. Manufacturers are structuring submission packages to capture voucher eligibility alongside standard approval pathways. The incentive most benefits mid-cap developers with existing dengue vaccine infrastructure who can leverage shared manufacturing assets.
Public-sector tender consolidation is concentrating procurement authority within centralized health ministry units. Brazilian state governments are ceding vaccine purchasing autonomy to federal agencies, replacing fragmented municipal acquisition. This consolidation most visibly compresses supplier margins while favoring manufacturers with established WHO prequalification status and regional distribution partnerships.
Chikungunya Fever Market Segmentation
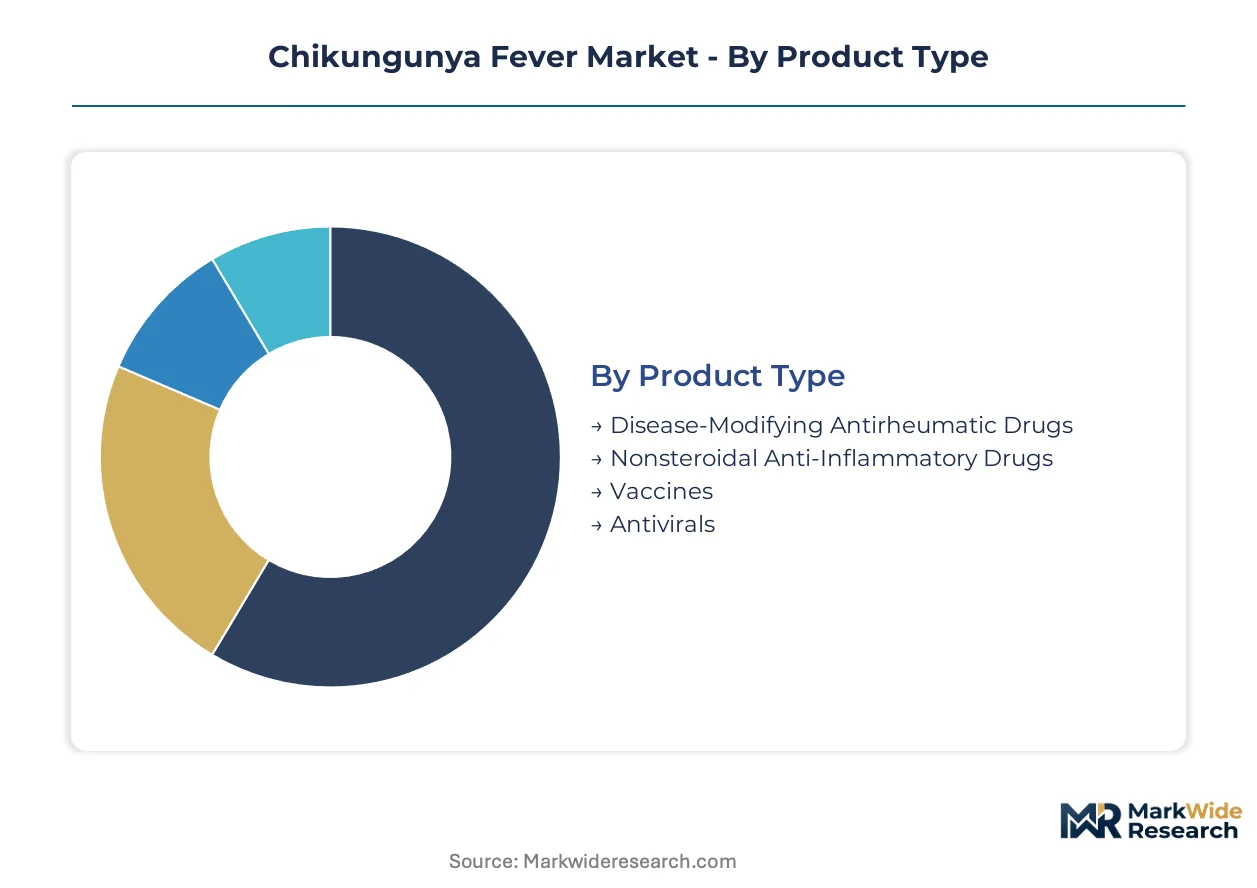
Chikungunya fever market segmentation reveals divergent supply chain configurations across therapeutic and preventive modalities. Vaccine procurement concentrates in centralized public health tenders while symptomatic treatments fragment across retail pharmacy and institutional channels.
Product Type:
Supply concentration varies sharply across this category, with vaccines requiring single-source manufacturing partnerships versus distributed generic production for analgesics.
- Vaccines:Live-attenuated and inactivated platforms dominate development pipelines. Demand concentrates in Brazilian federal procurement and Indian national immunization programs where vector control budgets are expanding. Cold-chain infrastructure requirements filter manufacturer participation to established tropical disease suppliers.
- Nonsteroidal Anti-Inflammatory Drugs:Oral formulations of ibuprofen and naproxen constitute first-line symptomatic management for acute polyarthralgia. Volume spreads across Thai hospital formularies and Indian retail pharmacy networks with minimal regulatory barriers to entry.
- Disease-Modifying Antirheumatic Drugs:Methotrexate and hydroxychloroquine address chronic arthritic sequelae in persistent cases. Prescription concentrates with rheumatology specialists in Brazilian urban referral centers.
- Antivirals:Direct-acting candidates remain investigational with limited commercial availability. Development activity clusters in Singaporean and US biotech research programs targeting early viremic phase intervention.
Today's leader: Vaccines. Tomorrow's challenger: Disease-Modifying Antirheumatic Drugs.
Treatment Setting:
Cost tier differentiation separates acute hospital reimbursement from extended outpatient management where patient out-of-pocket burden shapes access patterns.
- Hospital Care:Acute febrile presentation with severe polyarthralgia drives emergency department utilization. Brazilian public hospitals and Indian district medical centers capture concentrated diagnostic and stabilization volume during outbreak phases.
- Outpatient Clinics:Extended arthritic disability requires rheumatology and physical therapy follow-up. Thai primary care networks and Brazilian municipal health posts manage recurrent visit patterns that define long-term disease burden.
- Home Care:Analgesic self-administration and mobility assistance dominate post-acute management. Family caregiver burden concentrates in Indian urban slum and rural settings with limited clinic access.
- Community Health Services:Vector control integration and health education campaigns operate through local health worker deployment. Brazilian community health agent programs link symptomatic screening to referral pathways.
Hospital Care captures the steepest expansion trajectory during epidemic surges. Home Care gains share fastest as chronic sequelae recognition improves.
Patient Demographic:
Volume distribution across age bands reflects differential severity presentation and vaccine target population selection.
- Adults:Working-age populations between 15 and 65 years experience highest symptomatic burden and productivity loss. Brazilian occupational health programs and Indian employer-sponsored insurance schemes concentrate intervention demand.
- Elderly:Pre-existing osteoarthritis complicates chikungunya arthropathy differentiation. Thai geriatric hospital networks and Indian multi-specialty clinics manage overlapping diagnostic complexity.
- Children:Pediatric presentation often features atypical rash and milder arthralgia. Brazilian pediatric infectious disease services and Indian school health programs drive surveillance integration.
- Pregnant Women:Vertical transmission risk during intrapartum viremia necessitates specialized obstetric protocols. ANVISA and Indian CDSCO pharmacovigilance requirements restrict therapeutic options in this population.
Adults anchor current therapeutic volume. Elderly populations represent the fastest-climbing segment as population aging accelerates across endemic zones.
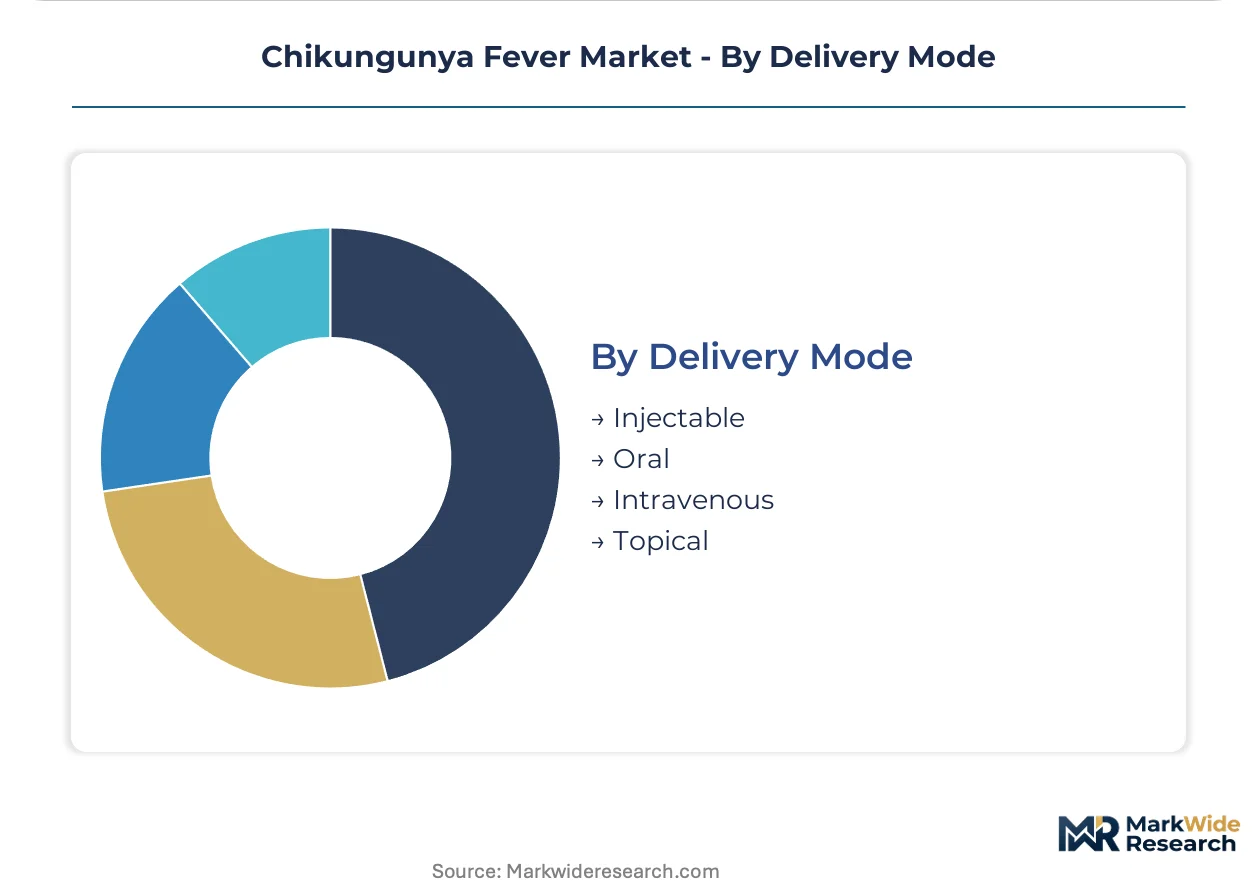
Delivery Mode:
Margin structures separate high-value injectable vaccines from commoditized oral analgesics with divergent distribution economics.
- Injectable:Vaccine administration and severe case hospitalization require parenteral delivery. Brazilian cold-chain distribution partnerships and Indian government medical store depots concentrate procurement authority for this mode.
- Oral:Tablet and liquid formulations enable outpatient self-management of fever and arthralgia. Thai pharmacy retail chains and Indian generic manufacturers sustain volume through price-competitive tendering.
- Intravenous:Dehydration correction and inpatient analgesia utilize IV infusion in acute severe cases. Hospital formulary committees in Brazilian state health systems control access.
- Topical:Counterirritant creams and transdermal patches provide localized symptomatic relief with minimal systemic exposure. Limited penetration reflects efficacy skepticism among prescribing physicians.
Injectable modes command premium positioning. Oral delivery is gaining share fastest as outpatient chronic management protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian federal procurement systems anchor tropical vaccine distribution networks, with Indian manufacturing clusters supplying cost-competitive volumes to endemic zones across three continents.
Brazil
ANVISA localized stability testing requirements filter foreign manufacturer participation while federal health ministry consolidation replaces fragmented state-level procurement. São Paulo and Rio de Janeiro municipal health networks drive diagnostic infrastructure deployment. The Butantan Institute cluster anchors domestic fill-finish partnerships reducing import dependency for thermolabile biologics.
India
CDSCO pharmacovigilance frameworks restrict therapeutic options for pregnant women while national immunization program expansion accelerates vaccine tender volumes. Maharashtra and Gujarat pharmaceutical corridors concentrate bulk antigen manufacturing capacity. Serum Institute of India dominates public-sector procurement through established government medical store depot relationships.
Thailand
Vector control budget expansion alongside therapeutic procurement creates dual-demand pressure across provincial health networks. Thai FDA registration pathways prioritize stability data generated under tropical humidity conditions. Bangkok metropolitan hospital networks capture concentrated diagnostic confirmation volume during seasonal outbreak peaks.
United States
FDA tropical disease priority review voucher programs channel development resources toward dual traveler-endemic population labeling strategies. Travel medicine clinics in Miami and New York departure cities adopt live-attenuated platforms for pre-exposure prophylaxis. Boston and San Francisco biotech clusters concentrate early-phase antiviral research targeting viremic phase intervention.
France
EMA accelerated assessment pathways designate chikungunya vaccines as priority medicines shortening review timelines for traveler indications. ANSM pharmacovigilance requirements shape post-market surveillance obligations for tropical disease indications. Lyon and Paris infectious disease research institutes coordinate Phase III endpoint accumulation across European traveler cohorts.
Chikungunya Fever Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and regulatory access dimensions. Market structure concentrates around established dengue vaccine infrastructure holders and specialized tropical disease platform developers. Three archetypes dominate: multinational pharmaceutical conglomerates leveraging shared manufacturing assets, mid-cap biotech specialists with adjuvant platform differentiation, and Indian cost-scale manufacturers capturing public-sector tender markets. Competitive moves center on WHO prequalification pursuit and regional distribution partnership formation.
Within the multinational tier, Takeda Pharmaceutical Co. Ltd. and Sanofi S.A. occupy positions anchored by existing arbovirus vaccine infrastructure. Takeda exemplifies the dengue-leveraged development archetype across Latin American regulatory pathways. Sanofi represents European-based tropical disease portfolio diversification. At the specialized platform end, Valneva SE sits within the adjuvant-differentiation segment targeting traveler-indication premium positioning. These three collectively illustrate how manufacturing geography and regulatory history shape competitive access to Brazilian and Indian procurement systems.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Co. Ltd. |
| Serum Institute of India Pvt. Ltd. |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Emergent BioSolutions Inc. |
| Moderna, Inc. |
| Bharat Biotech International Ltd. |
| Zydus Lifesciences Ltd. |
| Valneva SE |
| Others |
Supply Flow & Price Mechanics
Vaccine-tier divergence between WHO-prequalified candidates and non-prequalified investigational products manifests in procurement premiums of 40-60% for validated cold-chain reliability, while supply chain configurations split between centralized government medical store depots for thermolabile biologics and fragmented retail pharmacy networks for oral analgesics. Brazilian federal tender consolidation and Indian national immunization program expansion are compressing supplier margins at the premium tier while creating volume anchors that stabilize input cost pass-through.
Pricing Analysis
Cold-chain logistics expenditure passes through to end-buyers with differential intensity across tropical distribution networks, with Brazilian state health systems and Indian government medical store depots absorbing higher per-dose costs due to unreliable electricity infrastructure. Price differentiation separates WHO-prequalified manufacturers commanding premium positioning from regional generic suppliers competing on tender price. Pricing pressure stems from Brazilian federal procurement consolidation replacing fragmented municipal acquisition. Public-sector tender markets exhibit highest price sensitivity while traveler-indication private clinics demonstrate lowest sensitivity to per-dose premiums.
Supply Chain Analysis
Live-attenuated vaccine bulk antigen supply rests on manufacturing clusters in India, France, and Japan, with fill-finish operations concentrated in Brazil and Thailand to satisfy localized stability testing requirements. Critical inputs include specialized adjuvant platforms, glass vial containment systems, and validated cold-chain packaging. Single-source vulnerability concentrates in adjuvant supply where proprietary platform technologies limit supplier substitution. Distribution runs through WHO-prequalified logistics partners for vaccine cold-chain maintenance, while oral analgesics flow through conventional pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chikungunya fever vaccine procurement functions as a regulatory compounder where FDA tropical disease priority review voucher eligibility and WHO prequalification status collectively determine manufacturer access to Brazilian and Indian tender markets. EMA accelerated assessment pathway designation for traveler indications creates parallel demand channels that reward dual-label development strategies.
For Market Incumbents: To counter Brazilian federal procurement consolidation compressing supplier margins, incumbents should deepen backward integration into domestic fill-finish partnerships with Butantan Institute and Serum Institute of India to satisfy ANVISA and CDSCO localized stability requirements. WHO prequalification maintenance and regional distribution partnership renewal represent critical defensive levers against emerging platform competitors. For New Entrants and Emerging Players: Outpatient arthritic sequelae management in Indian home care settings represents an underserved buyer archetype with minimal incumbent penetration beyond acute hospitalization. New entrants should prioritize disease-modifying antirheumatic drug development for persistent arthritic disability and pursue ANVISA localized stability testing partnerships to establish Brazilian manufacturing presence without full greenfield investment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotech specialists possessing adjuvant platform differentiation and existing dengue vaccine infrastructure that can be leveraged for chikungunya combination candidates. Long-term viability favors developers with dual traveler-endemic population labeling strategies and established WHO prequalification status. The signal to watch is Phase III endpoint accumulation velocity across epidemic-prone regions as inflection indicator for regulatory submission timelines.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Brazilian federal and Indian national immunization program procurement eligibility. |
| Localized Fill-Finish Partnership | ANVISA stability testing compliance reduces import dependency and accelerates registration timelines. |
| Combination Vaccine Development | Arbovirus co-circulation in Brazil creates demand for tetravalent dengue-chikungunya-Zika-yellow fever candidates. |
| Traveler-Indication Labeling | EMA accelerated assessment pathway shortens review timelines for European departure city clinic adoption. |
| Outpatient Sequelae Protocol Development | Extended arthritic disability management in Thai primary care networks captures underpenetrated therapeutic volume. |
Methodological Framework
Multiple input streams — regulatory filing analysis, procurement database review, and epidemiological surveillance integration — were reconciled across primary interviews with vaccine development executives, regulatory affairs leads at ANVISA and CDSCO, hospital formulary directors in São Paulo and Bangkok, and government medical store depot procurement managers. Secondary validation drew from FDA tropical disease priority review voucher records, WHO prequalification status listings, ClinicalTrials.gov endpoint disclosures, and Brazilian federal tender announcement archives. Bottom-up demand modeling and top-down epidemiological burden estimation were triangulated to constrain projection variance.
Data-stream reconciliation across the analysis window applied segmented growth rate derivation by product type, treatment setting, patient demographic, and regional regulatory cluster. Analytical framework incorporated vector ecology surveillance gaps, Phase III trial execution complexity, and cold-chain infrastructure availability as industry-specific forecast inputs. CAGRs were derived from epidemiological modeling of outbreak probability combined with immunization program budget expansion trajectories.
Underlying measurement precision varies by segment; vaccine procurement volumes carry tighter precision than antiviral development pipeline valuations due to tender transparency. Forecasts reflect documented assumptions regarding WHO prequalification pathway velocity, epidemic unpredictability, and regulatory submission timeline variability. Vector ecology shifts, arbovirus co-circulation pattern changes, and national immunization program budget reallocation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Bronchitis Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Valley Fever Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Infectious Disease Treatments Market