
 Infection Control Surveillance Solutions Market | 2026-2036
Infection Control Surveillance Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Infection Control Surveillance Solutions Market Analysis
Hospital procurement teams is reorganizing infection control budgets toward cloud-based surveillance platforms. RLDatix leverages its vertical integration into patient safety software to sustain recurring revenue streams. Becton, Dickinson and Company anchors its position through hardware-software bundling in acute care settings. Wolters Kluwer N.V. competes on clinical decision support content layered into surveillance workflows.
Infection control surveillance solutions encompass integrated hardware-software systems that aggregate patient data, environmental sensors, and laboratory results to detect healthcare-associated infections through algorithmic risk scoring and automated alerting. These platforms typically process HL7 FHIR-standardized electronic health record feeds alongside real-time location system tags to trigger isolation protocols. Software deployments currently dominate value capture as hospitals prioritize subscription-based analytics over capital-intensive hardware refreshes. Cloud-based delivery models are expanding fastest among mid-size health systems seeking to avoid on-premises infrastructure overhead.
The FDA oversees cybersecurity premarket requirements for networked surveillance devices, while the Centers for Medicare and Medicaid Services ties reimbursement to hospital-acquired infection reporting through the Hospital Inpatient Quality Reporting Program. Joint Commission accreditation standards further mandate active surveillance programs as a condition of operational licensure. Stakeholders must weigh interoperability investments against the fragmentation of state-level mandatory reporting regimes.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from eighteen months to under ninety days, forcing incumbent vendors to restructure engineering roadmaps around API-first integration with electronic health record systems.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Medicare reimbursement penalties for preventable infections are compelling health systems to automate surveillance workflows rather than rely on manual chart reviews.
- Real-time location system convergence:Bluetooth Low Energy and ultra-wideband tags are enabling contact tracing automation that reduces outbreak investigation time from days to hours.
- Mid-size hospital consolidation:Merged health networks in the United States are centralizing infection prevention budgets into enterprise software contracts with multi-facility analytics dashboards.
Market Restraints
- Cybersecurity validation costs:FDA premarket submission requirements for networked devices are extending product launch timelines by twelve to eighteen months for hardware-integrated platforms.
- Interoperability fragmentation:State-level mandatory reporting regimes in the United States lack standardized data elements, forcing vendors to maintain fifty-plus jurisdiction-specific reporting modules.
- Legacy infrastructure lock-in:On-premises data warehouse investments made during 2015-2020 are constraining cloud migration budgets at academic medical centers.
Strategic Opportunities
- Long-term care penetration:Skilled nursing facilities remain underpenetrated by automated surveillance, presenting white space for sensor-based environmental monitoring solutions.
- Antimicrobial stewardship integration:Convergence of pharmacy analytics with infection surveillance creates cross-functional platforms that capture pharmacy and infection prevention budgets simultaneously.
- Joint Commission accreditation mandates:Updated standards requiring active surveillance programs for surgical site infections are creating replacement demand at community hospitals with paper-based systems.
Industry Challenges
- Clinical informatics talent scarcity:Health systems lack staff capable of configuring FHIR-based data pipelines and tuning algorithmic alert thresholds to reduce false-positive rates.
- Multi-vendor integration complexity:Surveillance platforms must reconcile data from laboratory information systems, admission-discharge-transfer feeds, and building automation systems with incompatible data models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infection Control Surveillance Solutions Market |
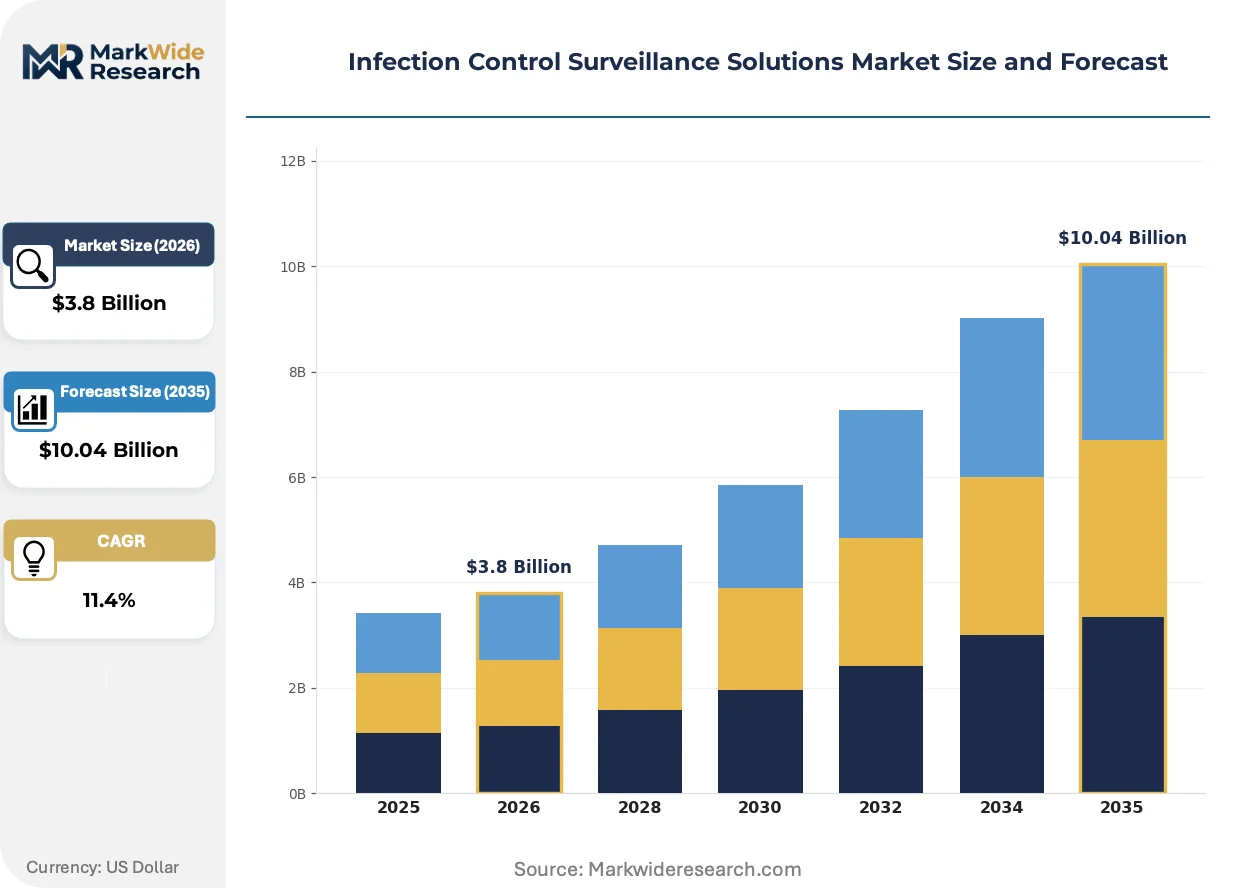
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Analytics End User: Hospitals, Nursing Homes, Clinics, Laboratories Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Technology: AI, IoT, Data Mining, Dashboard Solutions |
| Companies Covered | Baxter International Inc., RLDatix, Becton, Dickinson and Company, VigiLanz Corporation, bioMérieux, Premier Inc., Gojo Industries, Inovalon, Wolters Kluwer N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infection Control Surveillance Solutions Market Emerging Trajectories
Algorithmic risk scoring is migrating from retrospective reporting to prospective intervention, compressing the window between pathogen exposure and isolation protocol activation from hours to minutes.
Natural language processing engines trained on unstructured clinical notes are supplanting manual infection criteria verification by extracting relevant diagnostic phrases from physician documentation. Community hospitals with limited infection prevention staffing are adopting these tools fastest. The shift is compressing time-to-detection metrics and reducing dependency on specialized clinical reviewers.
FDA guidance on cybersecurity premarket submissions is mandating software bill of materials disclosure and vulnerability management plans for networked surveillance devices. Device manufacturers are restructuring quality management systems to accommodate continuous monitoring requirements. Acute care settings with embedded hardware sensors face the steepest compliance recertification burden.
Subscription pricing for analytics modules is displacing perpetual licensing for on-premises software across mid-size health systems. Vendors are unbundling implementation services from platform fees to accelerate land-and-expand strategies. The Southwest and Mountain West regions of the United States show the fastest uptake of this model among consolidating hospital networks.
Infection Control Surveillance Solutions Market Segmentation
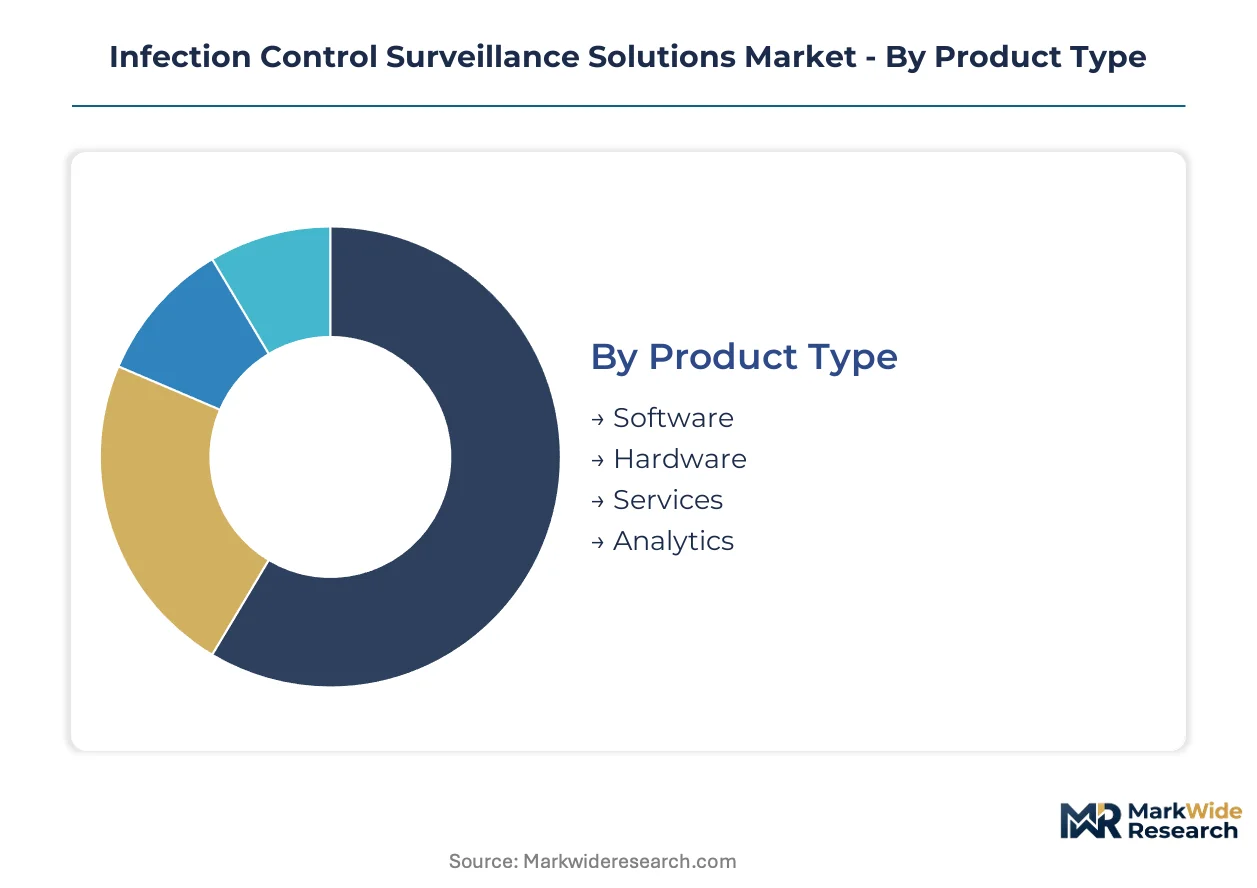
Segmentation in infection control surveillance solutions reveals how procurement priorities diverge across health system archetypes. Cloud-native software commands premium pricing while hardware-integrated platforms face elongating FDA certification cycles. Understanding these fault lines exposes where substitution threats and margin compression concentrate.
Product Type:
Software platforms face the most acute substitution pressure as hospitals pivot from perpetual licenses to API-first subscription models.
- Software:Cloud-native surveillance platforms aggregate HL7 FHIR feeds and laboratory data streams through algorithmic risk scoring engines. Demand concentrates in mid-size United States health systems consolidating infection prevention budgets into enterprise analytics contracts.
- Hardware:Environmental sensors and real-time location system tags require FDA premarket cybersecurity validation under evolving guidance. Academic medical centers with 2015-2020 on-premises data warehouse investments face constrained migration budgets.
- Services:Implementation and clinical informatics configuration support FHIR pipeline tuning and alert threshold optimization.
- Analytics:Subscription-based predictive modules displace retrospective reporting with prospective intervention capabilities.
Software retains volume leadership; Analytics holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich hospital networks from budget-constrained long-term care operators.
- Hospitals:Acute care settings deploy integrated hardware-software bundles with Bluetooth Low Energy contact tracing and automated isolation protocols. United States health systems centralize procurement through enterprise contracts spanning multi-facility dashboards.
- Nursing Homes:Skilled nursing facilities remain underpenetrated by automated surveillance, creating white space for sensor-based environmental monitoring with lower clinical informatics staffing requirements.
- Clinics:Outpatient settings prioritize mobile-accessible dashboards over full-platform deployments.
- Laboratories:Diagnostic facilities require interoperability with laboratory information systems and admission-discharge-transfer feeds.
Hospitals dominate current procurement value; Nursing Homes present the most rapid penetration opportunity.
Deployment:
Application context determines whether ninety-day cloud deployments or eighteen-month on-premises cycles prevail.
- Cloud-Based:API-first architectures compress implementation timelines and eliminate infrastructure overhead. Southwest and Mountain West United States hospital networks show fastest uptake among consolidating systems.
- On-Premises:Legacy data warehouse investments constrain migration budgets at academic medical centers with specialized security requirements.
- Hybrid:Split configurations process sensitive patient data locally while pushing analytics to cloud environments.
- Mobile:Point-of-care alerting extends surveillance workflows to infection prevention specialists conducting ward rounds.
Cloud-Based captures the majority of new contract value; Mobile is climbing the fastest among frontline adoption curves.
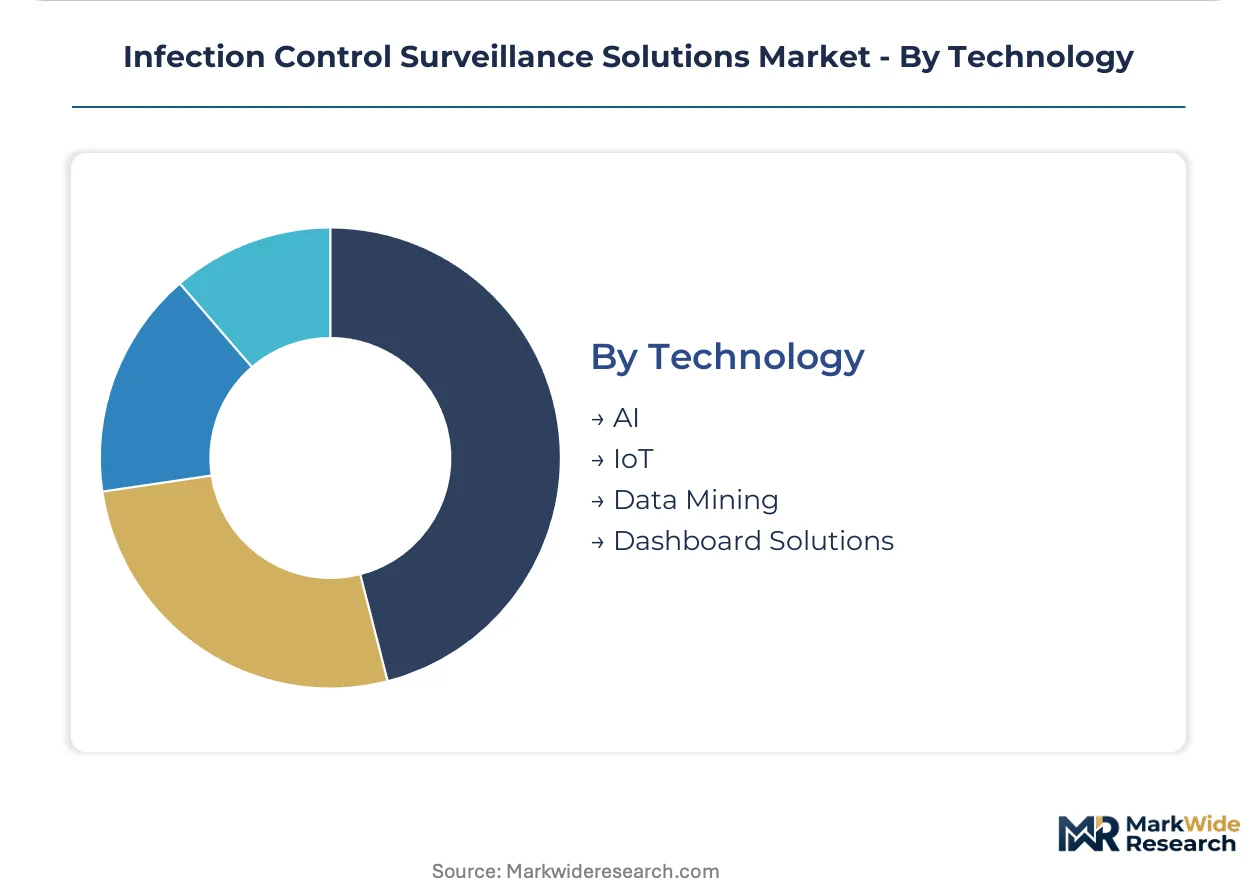
Technology:
Customer type sophistication separates AI-enabled predictive platforms from dashboard-centric reporting tools.
- AI:Natural language processing engines extract diagnostic phrases from unstructured clinical notes, compressing infection detection timelines. Community hospitals with limited infection prevention staffing adopt these tools fastest.
- IoT:Bluetooth Low Energy and ultra-wideband tags enable automated contact tracing that reduces outbreak investigation from days to hours.
- Data Mining:Retrospective pattern recognition supports regulatory reporting for CMS Hospital-Acquired Condition Reduction Program compliance.
- Dashboard Solutions:Visualization-centric platforms serve smaller facilities with paper-based surveillance systems transitioning to digital workflows.
AI commands the highest implementation investment; IoT is gaining share fastest through sensor convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border data flows through submarine cable landing stations in Virginia Beach and Los Angeles underpin North American surveillance platform deployment. Health system consolidation across the Great Plains and Mountain West routes procurement decisions through centralized enterprise contracts.
United States
Hospital-acquired condition penalties from CMS compel health systems toward automated surveillance workflows. FDA cybersecurity premarket requirements extend hardware-integrated platform timelines by twelve to eighteen months. The Southwest and Mountain West regions show fastest cloud-native uptake among consolidating hospital networks.
Germany
Academic medical centers in Baden-Württemberg and Bavaria maintain legacy on-premises data warehouse investments constraining cloud migration. EMA guidance on medical device software harmonizes with FDA cybersecurity frameworks for networked surveillance devices. The Rhine-Ruhr metropolitan cluster concentrates procurement for multi-facility analytics dashboards.
United Kingdom
NHS England's patient safety mandates accelerate centralized infection prevention budget allocation toward subscription analytics. MHRA post-Brexit regulatory divergence creates parallel certification tracks for surveillance software vendors. London and Southeast health networks drive API-first integration demand with electronic health record systems.
Japan
PMDA streamlined review pathways for SaMD reduce time-to-market for algorithmic risk scoring platforms. METI digital health subsidies support mid-size hospital cloud migration away from 2015-2020 infrastructure investments. The Kanto region around Tokyo anchors demand for Bluetooth Low Energy contact tracing automation.
Australia
TGA software as a medical device frameworks align surveillance platform certification with international FDA-EMA convergence. State-level mandatory reporting fragmentation across Victoria, New South Wales, and Queensland forces vendors to maintain jurisdiction-specific modules. The Sydney-Melbourne corridor concentrates private hospital network procurement for environmental sensor integration.
Infection Control Surveillance Solutions Market Vendor Landscape
Concentration sits with diversified health technology conglomerates and vertical software specialists rather than pure-play surveillance vendors. The vendor base spans three tiers: enterprise platforms bundling patient safety suites, hardware-integrated acute care specialists, and cloud-native analytics disruptors. Strategic moves center on API-first engineering restructuring and clinical informatics talent acquisition rather than capacity expansion.
Within the enterprise software tier, RLDatix and Wolters Kluwer N.V. exemplify platform consolidation strategies that capture recurring revenue through patient safety workflow integration. Becton, Dickinson and Company anchors the hardware-software bundling archetype through acute care embedded sensor deployments. These three represent distinct competitive vectors: vertical software depth, clinical decision support content layering, and physical-digital convergence in hospital settings.
| Leading Market Players |
|---|
| Baxter International Inc. |
| RLDatix |
| Becton, Dickinson and Company |
| VigiLanz Corporation |
| bioMérieux |
| Premier Inc. |
| Gojo Industries |
| Inovalon |
| Wolters Kluwer N.V. |
| Others |
Supply Flow & Price Mechanics
Cloud-native platform scale economies compress marginal delivery costs below on-premises alternatives, concentrating pricing power among vendors with established API integration libraries and tilting procurement toward multi-year enterprise subscriptions over capital-intensive hardware bundles.
Pricing Analysis
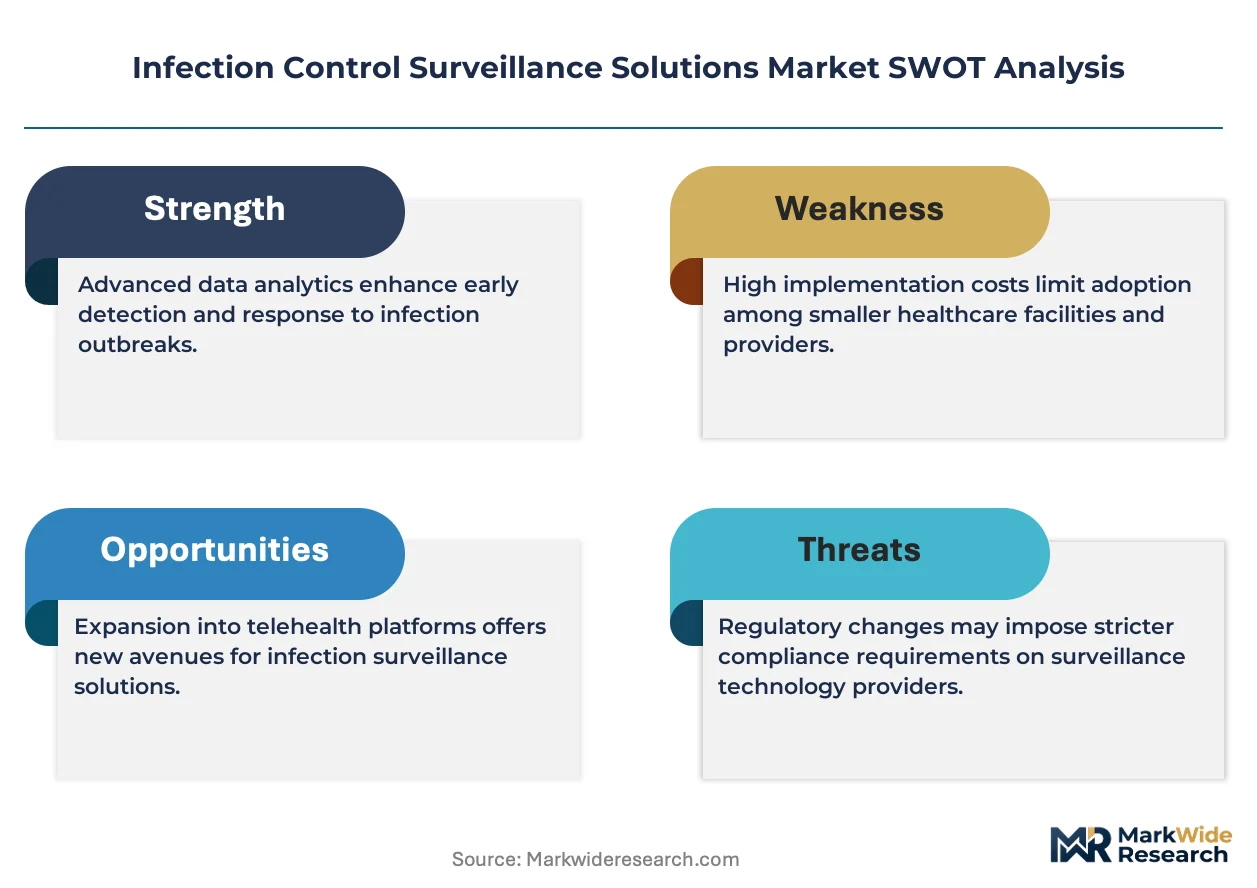
Volume-discount tiering structures separate enterprise health system contracts from mid-size hospital subscriptions and individual facility licenses. Pricing stratifies across premium AI-enabled predictive modules, standard cloud-based surveillance dashboards, and economy-tier retrospective reporting tools. Cost compression in the hardware-integrated segment intensifies because FDA cybersecurity premarket requirements extend certification timelines and inflate quality management overhead. Academic medical centers with legacy infrastructure investments demonstrate lowest price sensitivity, while community hospitals facing Joint Commission accreditation mandates exhibit highest budget elasticity.
Supply Chain Analysis
Inventory lead times for Bluetooth Low Energy sensors and ultra-wideband tags stretch twelve to eighteen months due to semiconductor fabrication scheduling at Taiwan and South Korea foundries. Software development draws from Indian engineering services, United States clinical informatics talent, and German precision sensor manufacturing. Single-source vulnerability concentrates in FDA-certified hardware components where cybersecurity validation cannot transfer between suppliers. Distribution runs through hospital procurement consortia and group purchasing organizations that aggregate demand across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as CMS reimbursement penalties compel health systems to replace paper-based surveillance with automated platforms, creating replacement demand that compounds with mid-size hospital consolidation.
For Market Incumbents: Shield recurring revenue streams by deepening API-first integration with Epic and Cerner electronic health record systems to raise switching costs. Accelerate clinical informatics talent acquisition to address FHIR pipeline configuration scarcity that constrains competitor deployment timelines. Prioritize antimicrobial stewardship module development to capture cross-functional pharmacy budgets before cloud-native disruptors unbundle analytics services.
For New Entrants and Emerging Players: Differentiate on sensor-based environmental monitoring for skilled nursing facilities where automated surveillance penetration remains minimal and clinical staffing constraints favor low-touch deployment models. Target the Southwest and Mountain West United States hospital networks where consolidating systems seek ninety-day cloud implementations without legacy infrastructure overhead. Pursue land-and-expand strategies by unbundling implementation services from platform fees to accelerate initial contract velocity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical software specialists with patient safety workflow integration that sustains subscription renewal rates above hardware-integrated platform alternatives. Long-term viability hinges on regulatory certification moats that extend FDA premarket timelines for new entrants. Acquisition target archetypes include cloud-native analytics disruptors with proven FHIR integration libraries. Monitor Joint Commission accreditation standard revisions as inflection indicators for replacement demand spikes at community hospitals.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Premarket Submission | Extends hardware-integrated platform launch timelines by twelve to eighteen months for networked surveillance devices. |
| Hospital System Partnership | Centralizes infection prevention budgets into enterprise contracts spanning multi-facility analytics dashboards. |
| Software Companion Development | Layers clinical decision support content into surveillance workflows to differentiate from dashboard-centric competitors. |
| CE Marking Pathway | Harmonizes with FDA cybersecurity frameworks for networked surveillance devices in European academic medical centers. |
| Reimbursement Strategy | Aligns platform value propositions with CMS Hospital-Acquired Condition Reduction Program penalty avoidance. |
Methodological Framework
Initial hypotheses were tested against primary input from infection prevention specialists, hospital procurement directors, biomedical engineers, and clinical informatics officers and refined through secondary validation against FDA premarket submission databases, CMS Medicare cost reports, hospital procurement consortium contracts, and Joint Commission accreditation standards. Bottom-up triangulation aggregated facility-level adoption patterns while top-down approaches cross-checked against health system consolidation announcements and GPO contract awards.
Variance decomposition across product type, deployment model, end-user facility scale, and technology sophistication segments informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated cloud-native platform deployment velocity, FDA cybersecurity guidance evolution, and real-time location system sensor convergence trends.
Material uncertainties — regulatory guidance revisions, health system merger timelines, and clinical informatics labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about interoperability standard adoption and reimbursement policy stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Patient Hygiene Aids Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Disinfection Equipment Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Hygiene Stations Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Antimicrobial Wipes Market