
 Typhoid Fever Vaccine Market | 2026-2036
Typhoid Fever Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Typhoid Fever Vaccine Market Analysis
The gap between premium conjugate vaccines and commodity live attenuated alternatives is broadening in procurement channels. GlaxoSmithKline leverages its Typbar TCV manufacturing scale to anchor supply contracts with UNICEF and national immunization programs. Bharat Biotech competes through differentiated conjugate technology leadership and WHO prequalification status for its typhoid conjugate candidate. Sanofi sustains position in oral vaccine segments through established distribution networks across Francophone Africa and Southeast Asia.
Typhoid fever vaccines are immunological preparations containing purified Vi polysaccharide, live attenuated Salmonella Typhi strain Ty21a, or protein-polysaccharide conjugates that stimulate humoral and cellular immunity against systemic typhoid infection, with formulations requiring cold chain maintenance at two to eight degrees Celsius and demonstrated efficacy duration spanning two to seven years depending on platform. The conjugate vaccine category leads value generation due to superior immunogenicity in children under two years and extended protection windows that reduce booster requirements. Oral vaccine demand accelerates in school-based campaigns where needle-free administration improves coverage rates and reduces healthcare worker burden. Live attenuated formulations occupy mature positions in traveler medicine channels where single-dose convenience commands price premiums.
WHO prequalification, FDA biologics licensing requirements, and EMA scientific opinion pathways collectively determine which manufacturers access pooled procurement mechanisms and national tender processes. National regulatory authorities in India and Indonesia apply stringently adapted standards that filter substandard products from public sector supply. Stakeholders must monitor evolving WHO Strategic Advisory Group of Experts recommendations on typhoid conjugate vaccine introduction schedules and age-targeting policies that will redirect procurement volumes across pediatric and adolescent segments.
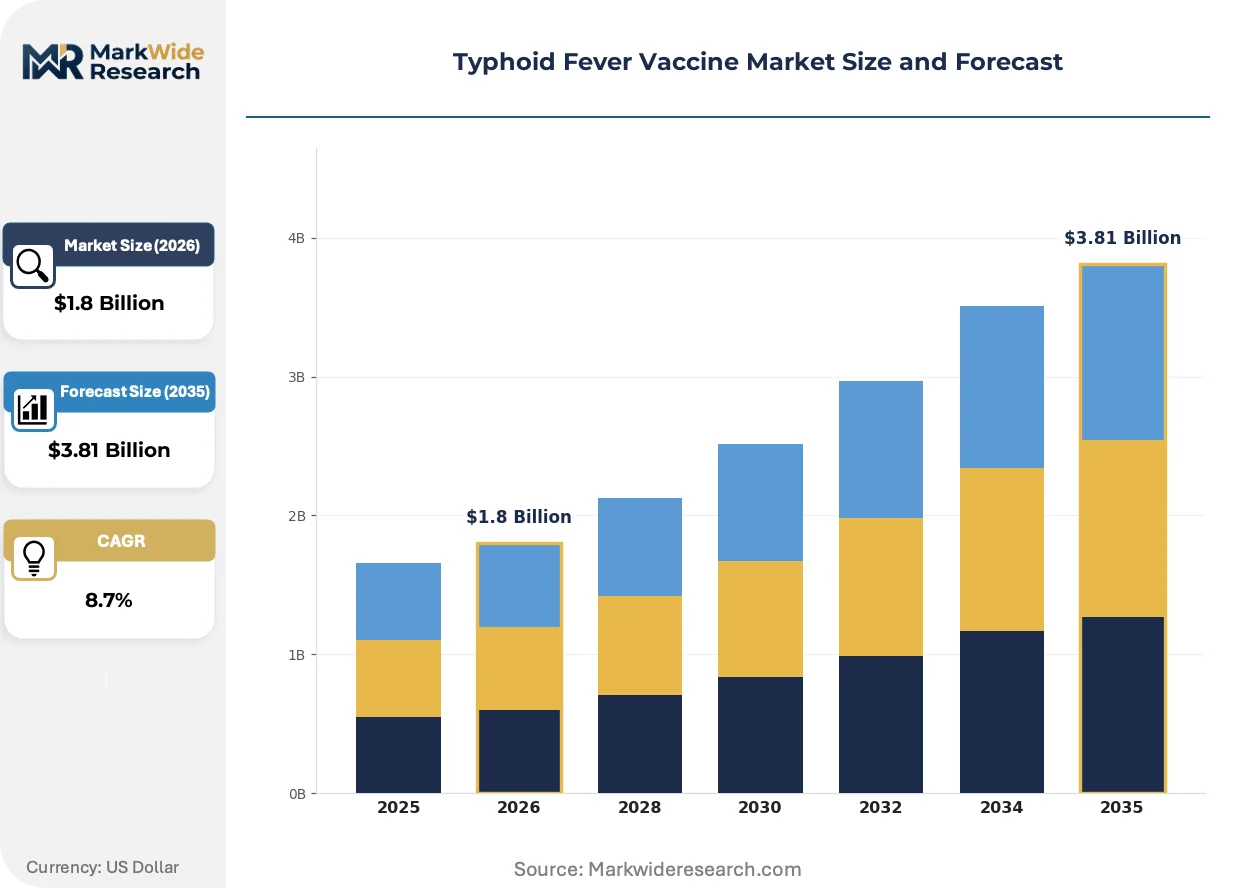
Market Dynamics
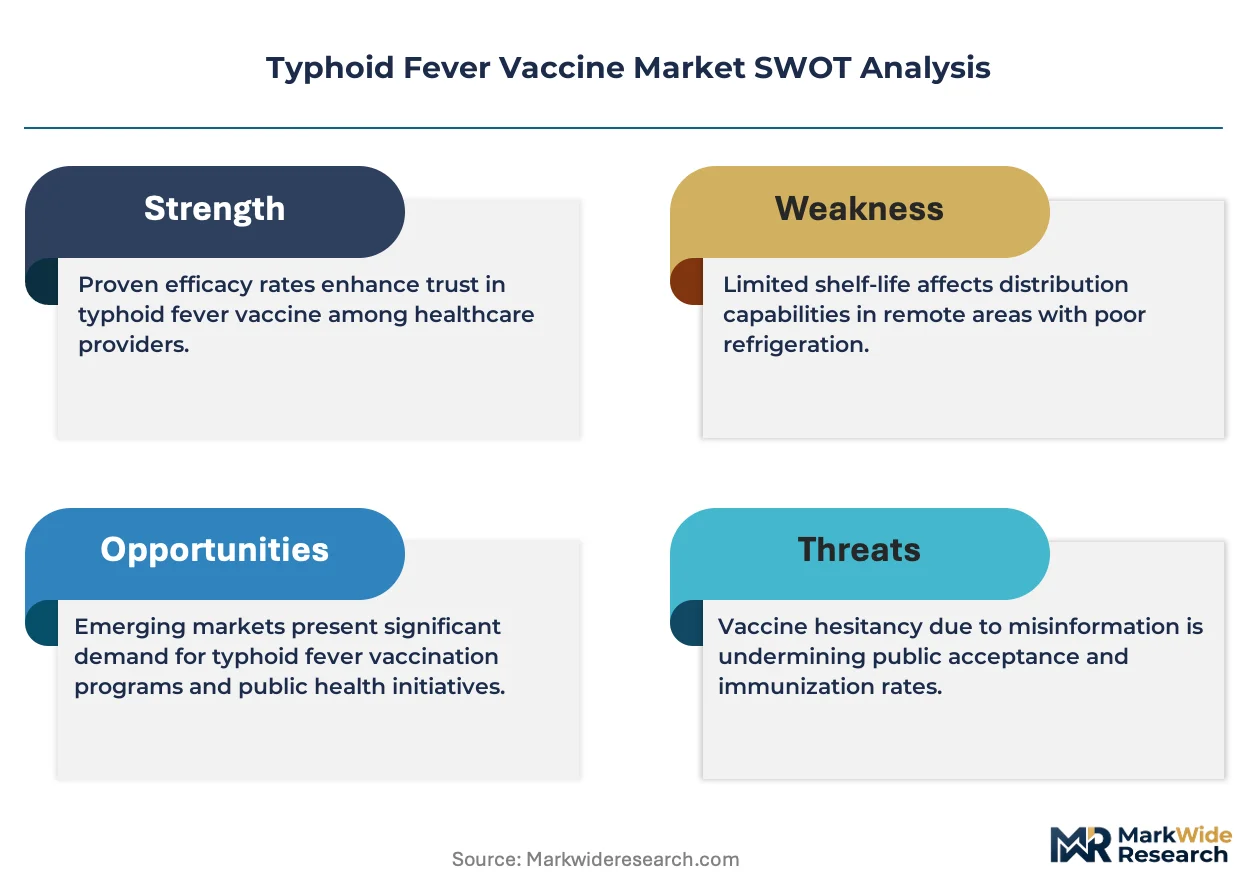
WHO Strategic Advisory Group of Experts recommendations on typhoid conjugate vaccine introduction schedules are redirecting procurement volumes across pediatric and adolescent segments, compressing demand windows for oral alternatives.
Growth Catalysts
- Gavi funding mechanisms:These pooled procurement vehicles unlock access to low-income country tenders in South Asia and sub-Saharan Africa, expanding addressable populations for conjugate formulations.
- Vi polysaccharide conjugation technology:Superior immunogenicity in children under two years extends protection windows and reduces booster requirements, anchoring pediatric immunization program preference.
- School-based campaign infrastructure:Needle-free oral administration improves coverage rates and reduces healthcare worker burden in mass vaccination settings across endemic regions.
Market Restraints
- Cold chain infrastructure gaps:Two to eight degrees Celsius maintenance requirements exclude last-mile distribution in rural sub-Saharan Africa and South Asian hinterlands.
- WHO prequalification timeline:Stringent stability and immunogenicity documentation requirements delay manufacturer access to UNICEF tenders by eighteen to thirty-six months.
- Live attenuated Ty21a strain limitations:Multiple-dose regimens and refrigeration needs constrain deployment in campaigns requiring rapid population coverage.
Strategic Opportunities
- Controlled temperature chain extension:Thermostable conjugate formulations would unlock distribution in Francophone West African countries lacking reliable cold chain infrastructure.
- Combination vaccine development:Vi polysaccharide conjugation platforms integrating meningococcal or pneumococcal antigens streamline national immunization program logistics.
- Travel medicine channel premiumization:Single-dose convenience commands price premiums in private clinics serving European and North American outbound travelers.
Industry Challenges
- Fill-finish capacity constraints:Sterile injectable manufacturing requires capital-intensive isolator technology and dedicated lyophilization lines that limit batch scale-up speed.
- Lot release testing timelines:National regulatory authorities in India and Indonesia apply stringently adapted pharmacopeial standards that extend batch-to-market intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Typhoid Fever Vaccine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccine, Inactivated Vaccine, Conjugate Vaccine, Oral Vaccine End User: Hospitals, Clinics, Research Institutes, Public Health Organizations Route of Administration: Intramuscular, Subcutaneous, Oral, Intradermal Age Group: Children, Adults, Elderly, Infants |
| Companies Covered | GlaxoSmithKline, Sanofi, Bharat Biotech, Biological E, PT Bio Farma, PaxVax, SK Bioscience, Zydus, Shanghai Institute of Biological Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Typhoid Fever Vaccine Market Emerging Trajectories
Conjugate platform engineering and cold chain innovation are compressing the viability gap between premium and commodity vaccine tiers, while procurement centralization reshapes manufacturer access patterns.
Vi polysaccharide-protein conjugation chemistry is automating consistency in antibody response across pediatric age brackets. National immunization programs in Bangladesh and Pakistan are adopting this platform for routine infant schedules. The technology is automating the shift from school-based catch-up campaigns to birth-dose integration, compressing oral vaccine demand windows.
EMA scientific opinion pathways and WHO prequalification standards are tightening stability documentation requirements for conjugate candidates. Manufacturers must now submit real-time and accelerated stability data across multiple temperature excursion scenarios. South Asian tender processes are responding by inserting cold chain verification clauses into supply agreements.
Buyer concentration through UNICEF and PAHO pooled procurement is displacing fragmented national tender processes. Francophone African ministries of health are consolidating orders through the Revolving Fund mechanism rather than bilateral negotiations. This consolidation is most visible in Senegal and Côte d'Ivoire, where single-source contracts now cover three-year supply horizons.
Typhoid Fever Vaccine Market Segmentation
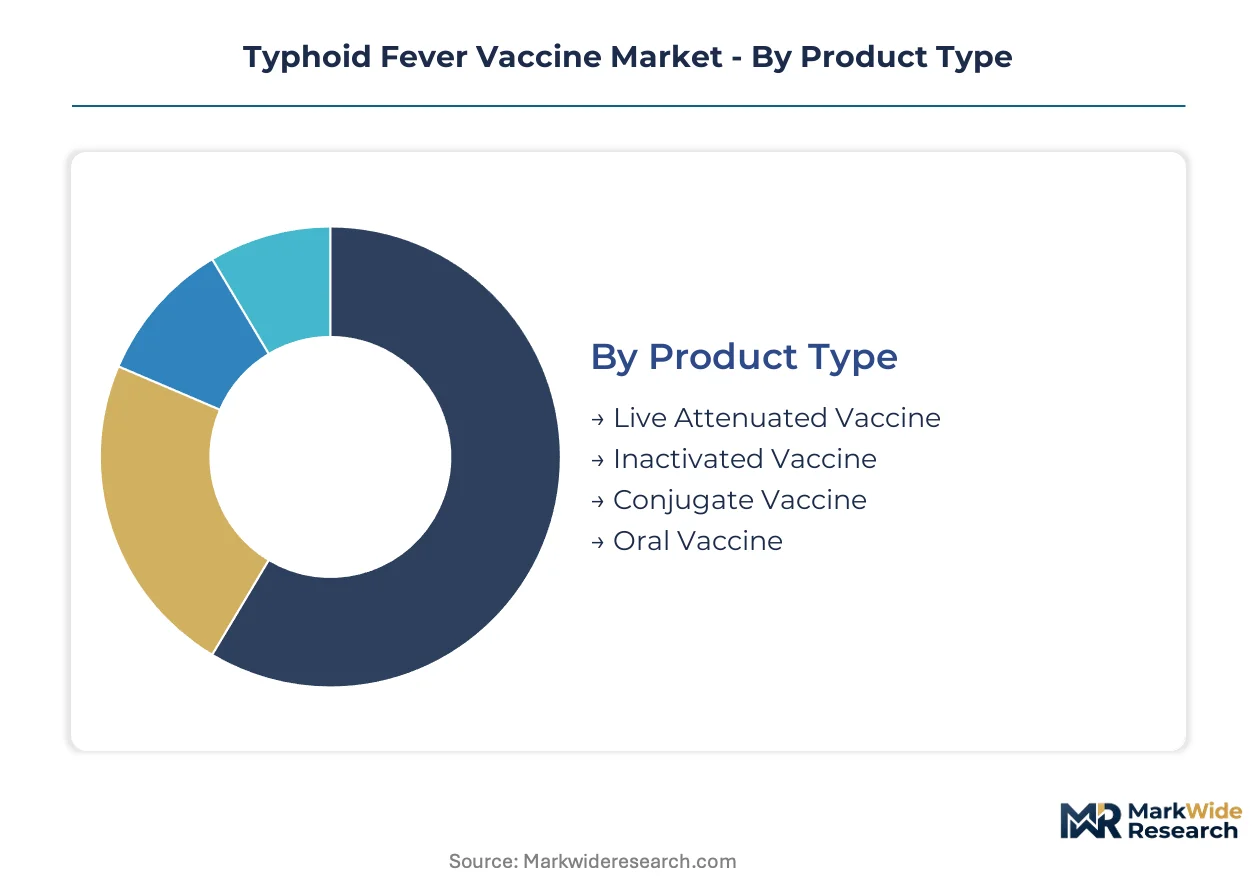
Typhoid vaccine procurement channels fragment across product platforms with divergent regulatory pathways. WHO prequalification status and national immunization program inclusion criteria determine which segments access Gavi-funded tenders versus private travel medicine markets.
Product Type:
WHO prequalification requirements vary sharply across platforms: conjugate vaccines face extended immunogenicity documentation timelines, while live attenuated formulations leverage decades of established safety databases.
- Conjugate Vaccine:Vi polysaccharide covalently linked to carrier proteins elicits T-cell dependent responses with durable immunity in pediatric populations. Demand concentrates in Bangladesh and Pakistan infant immunization programs where birth-dose integration is displacing school-based campaigns. Cold chain verification clauses in UNICEF supply agreements favor manufacturers with proven two-to-eight-degree stability data.
- Live Attenuated Vaccine:Ty21a strain requires multiple-dose oral regimens and stringent refrigeration, constraining deployment in rapid-coverage campaigns. Procurement volumes are compressing as national programs pivot toward single-dose conjugate alternatives with superior operational efficiency.
- Inactivated Vaccine:Heat-inactivated whole-cell formulations retain niche positions in traveler channels requiring rapid seroconversion.
- Oral Vaccine:Enteric-coated capsules eliminate needle requirements, sustaining demand in school-based delivery systems across Francophone West Africa.
Leading the category by volume: Conjugate Vaccine. Growing fastest: Oral Vaccine in campaign settings lacking injection infrastructure.
End User:
Procurement scale and price tolerance diverge between pooled multilateral mechanisms and fragmented private channels, with cost tiers stratifying across institutional buyer types.
- Public Health Organizations:Gavi-eligible country ministries and WHO regional offices aggregate demand through UNICEF and PAHO pooled procurement, commanding lowest unit prices through multi-year supply commitments. Tender specifications increasingly mandate conjugate platform compliance with infant schedule integration timelines.
- Hospitals:Tertiary facilities in urban India and Nigeria manage severe typhoid complications, generating post-exposure prophylaxis demand for rapid-acting parenteral formulations. Reimbursement pathways through national health insurance schemes determine product selection between premium conjugate and commodity alternatives.
- Clinics:Primary care networks in endemic districts serve as campaign distribution nodes, prioritizing oral vaccines for school-age cohorts.
- Research Institutes:Academic medical centers in Dhaka and Karachi conduct head-to-head efficacy trials, influencing national immunization technical advisory group recommendations.
Highest procurement volumes flow through Public Health Organizations. Steepest expansion trajectory: Hospitals in emerging market urban centers.
Route of Administration:
Delivery logistics and healthcare worker training requirements segment routes by campaign feasibility and cold chain dependency.
- Intramuscular:Deltoid or anterolateral thigh injection of conjugate formulations requires trained vaccinators and sterile equipment, limiting last-mile reach. Demand clusters in facility-based infant immunization programs with reliable cold chain infrastructure.
- Oral:Self-administered enteric-coated capsules bypass injection safety concerns and cold chain requirements, enabling community health worker deployment. Coverage rates improve in school-based campaigns across rural Senegal and Mali where needle disposal capacity is absent.
- Subcutaneous:Vi polysaccharide monovalent vaccines retain residual demand in traveler medicine channels.
- Intradermal:Fractional-dose intradermal delivery remains experimental, with pilot studies ongoing in Vietnamese provincial health systems.
Dominant by procurement volume: Intramuscular. Expanding most quickly: Oral in campaign settings.
Age Group:
Immunization schedule positioning and disease burden distribution determine age-targeting priorities across endemic country programs.
- Children:School-age cohorts historically anchored oral vaccine campaigns, but conjugate platform immunogenicity in children under two is redirecting procurement toward infant schedules. Pakistan and Bangladesh national programs now prioritize birth-dose or nine-month administration over catch-up campaigns.
- Adults:Traveler medicine channels in Europe and North America concentrate demand for single-dose convenience, with private clinics commanding substantial price premiums over public sector tenders. Occupational exposure programs for food handlers and healthcare workers sustain residual volumes.
- Infants:Conjugate vaccine compatibility with routine immunization platforms is accelerating co-administration with measles and pentavalent vaccines.
- Elderly:Immunosenescence concerns limit standalone demand, with coverage occurring through adult traveler or occupational channels.
Leading by current procurement volume: Children. Gaining share fastest: Infants through schedule integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka anchors typhoid vaccine procurement volume through its dense urban corridors and Gavi-eligible national immunization infrastructure. The city's pharmaceutical distribution networks channel conjugate formulations into Bangladesh's expanding infant immunization schedules.
Bangladesh
Urban slum populations in Dhaka and Chittagong drive conjugate vaccine demand through WHO-supported introduction campaigns. The country's national regulatory authority enforces cold chain verification protocols aligned with UNICEF supply standards. Manufacturing partnerships in the Gazipur pharmaceutical corridor are scaling fill-finish capacity for Vi polysaccharide conjugate production.
Pakistan
Sindh and Punjab provinces concentrate typhoid burden where conjugate vaccines now target children under two through routine immunization platforms. Federal health ministry directives prioritize birth-dose integration over school-based catch-up campaigns. Karachi's vaccine cold chain infrastructure supports last-mile distribution into peri-urban settlements lacking reliable refrigeration.
India
Hyderabad and Pune clusters host conjugate technology development and WHO prequalification activities for export markets. CDSCO applies stringently adapted pharmacopeial standards that filter substandard products from public sector tenders. Bharat Biotech's manufacturing base in Genome Valley supplies prequalified candidates to Gavi-funded procurement channels.
Nigeria
Lagos and Kano urban centers generate demand through phased typhoid conjugate vaccine introduction in high-burden districts. National Primary Health Care Development Agency coordinates with Gavi to unlock multi-year supply commitments. Cold chain gaps in northern states constrain oral vaccine deployment despite needle-free operational advantages.
Senegal
Dakar anchors Francophone West African procurement through PAHO Revolving Fund consolidation mechanisms. Ministry of health tenders now specify three-year supply horizons replacing fragmented bilateral negotiations. Oral vaccine campaigns in Thiès and Saint-Louis regions leverage school-based infrastructure where injection safety capacity remains limited.
Typhoid Fever Vaccine Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across conjugate platform development and oral formulation manufacturing. The market structure consolidates around three strategic tiers: multinational pharmaceutical conglomerates with WHO prequalification scale, emerging market biotech specialists with differentiated conjugate technology, and state-linked manufacturers serving domestic immunization programs. Dominant competitive moves include strategic partnerships for fill-finish capacity access and geographic expansion through prequalification pathway navigation.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline occupies a position exemplifying manufacturing scale advantages in UNICEF tender channels. Sanofi represents the diversified multinational archetype with established distribution networks across Francophone Africa. Bharat Biotech anchors the emerging market specialist tier through differentiated conjugate technology leadership and WHO prequalification status. These three company archetypes illustrate how regulatory pathway navigation and cold chain verification capabilities determine access to pooled procurement mechanisms.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Sanofi |
| Bharat Biotech |
| Biological E |
| PT Bio Farma |
| PaxVax |
| SK Bioscience |
| Zydus |
| Shanghai Institute of Biological Products |
| Others |
Supply Flow & Price Mechanics
Conjugate-versus-oral formulation divergence separates procurement channels into premium and commodity tiers, with WHO prequalification status determining which manufacturers access UNICEF pooled pricing versus fragmented national tenders. This bifurcation concentrates pricing power with prequalified suppliers while pushing non-qualifying producers toward traveler medicine channels where single-dose convenience commands substantial premiums.
Pricing Analysis
Value-based pricing anchors on immunogenicity outcomes in pediatric populations, with conjugate formulations commanding substantial premiums over live attenuated alternatives due to superior protection duration in children under two years. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with WHO prequalification and EMA scientific opinion pathways creating distinct price floors. Cost compression in oral vaccine tiers is intensifying because national programs in Bangladesh and Pakistan are pivoting toward infant schedule integration. Public health organizations through Gavi mechanisms exhibit highest price sensitivity, while private travel clinics in Europe and North America demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Vi polysaccharide supply rests on fermentation capacity concentrated in India, South Korea, and selected European facilities with established carrier protein conjugation expertise. Key inputs include purified polysaccharide antigen, CRM197 or tetanus toxoid carrier proteins, and specialized adjuvant formulations. Single-source vulnerability in sterile injectable fill-finish capacity creates bottlenecks, as isolator technology and dedicated lyophilization lines require capital-intensive investment with limited qualified suppliers. Distribution runs through UNICEF and PAHO pooled procurement mechanisms for endemic country programs, while traveler medicine channels utilize specialized cold chain logistics providers serving private clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification requirements function as a cost-of-compliance moat, filtering substandard manufacturers from Gavi-funded tenders and consolidating procurement access around capital-intensive players with proven stability documentation capabilities.
For Market Incumbents: Acquire sterile injectable fill-finish capacity in South Asian manufacturing corridors to secure supply commitments for conjugate platform scale-up. Bharat Biotech and GlaxoSmithKline should expand lyophilization line access through strategic toll manufacturing partnerships, defending against emerging entrants with abbreviated immunogenicity datasets. Cold chain verification capabilities represent the critical lever for tender retention as UNICEF inserts temperature excursion clauses into multi-year supply agreements. For New Entrants and Emerging Players: Regional distributors in Francophone West Africa offer the most penetrable channel for oral vaccine formulations where injection infrastructure remains limited. Target school-based campaign infrastructure in Senegal and Mali as the entry wedge, leveraging needle-free administration to bypass incumbent cold chain advantages. A co-development partnership with established Vi polysaccharide suppliers accelerates WHO prequalification timeline compression. For Investors and Strategic Acquirers: Re-rating potential sits with emerging market biotech specialists possessing differentiated conjugate technology and active WHO prequalification submissions, given Gavi funding mechanism expansion across South Asia and sub-Saharan Africa. Long-term viability over the next decade hinges on thermostable formulation capabilities that unlock distribution in last-mile settings lacking reliable refrigeration. The signal to watch is WHO Strategic Advisory Group of Experts recommendation shifts on age-targeting policies that redirect procurement volumes across pediatric segments.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks UNICEF tender access for manufacturers in India and South Korea. |
| Fill-Finish Capacity Expansion | Isolator technology investment in Hyderabad clusters reduces batch release timelines. |
| Controlled Temperature Chain Development | Thermostable formulations enable distribution in northern Nigerian states with cold chain gaps. |
| Combination Vaccine Platform | Vi polysaccharide conjugation with meningococcal antigens streamlines national immunization logistics. |
| Travel Medicine Channel Premiumization | Single-dose positioning in European private clinics commands substantial price premiums over public tenders. |
Methodological Framework
Independent corroboration across regulatory filings, procurement databases, and clinical trial registries underwrites the qualitative findings in this analysis. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and national regulatory authorities, UNICEF procurement managers, and hospital formulary directors in Dhaka and Karachi were combined with secondary validation from WHO prequalification listings, EMA scientific opinion pathways, and Gavi disbursement records. Bottom-up demand modeling across endemic country immunization programs and top-down supply capacity assessment at major manufacturing clusters were triangulated to ensure consistency.
Rate-of-change decomposition across the projection horizon separates volume growth from price evolution and mix shift effects. Segmentation dimensions modeled include product platform, route of administration, age group targeting, and regional regulatory cluster. CAGRs were derived from epidemiological burden projections, national immunization program expansion timelines, and tender award patterns. Industry-specific forecast inputs incorporate WHO Strategic Advisory Group of Experts recommendation trajectories and Gavi funding allocation cycles.
Caveats apply where regulatory timeline delays, cold chain infrastructure shortfalls, or competitor prequalification successes could materially shift the outlook. Forecasts reflect documented assumptions regarding national immunization program adoption curves and pooled procurement mechanism consolidation. A small set of named triggers warrants ongoing watch: WHO age-targeting policy revisions, thermostable formulation regulatory approvals, and fill-finish capacity expansion announcements in South Asian manufacturing corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Virology Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Retropharyngeal Abscess Market