
 Blood Culture Media Market | 2026-2036
Blood Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Culture Media Market Analysis
The EU In Vitro Diagnostic Regulation is restructuring procurement criteria for blood culture media across European hospital networks. Becton, Dickinson and Company leverages its automated platform integration to sustain long-term supply agreements with major health systems. bioMérieux SA anchors its competitive position through specialized chromogenic media formulations that reduce time-to-detection for bloodstream pathogens. Thermo Fisher Scientific competes by extending its distribution infrastructure into emerging diagnostic laboratory markets.
Blood culture media comprises nutrient-rich formulations designed to support bacterial and fungal proliferation from clinical blood specimens, typically containing peptones, yeast extract, sodium polyanethol sulfonate as an anticoagulant, and aerobic or anaerobic gas environments optimized for pathogen recovery. Automated blood culture systems and molecular diagnostics technologies represent the fastest-expanding technology segments as laboratories pursue reduced turnaround times for sepsis diagnosis. Blood culture bottles dominate product type volumes due to their compatibility with continuous monitoring instrumentation, while specialty media captures premium positioning for fastidious organism detection.
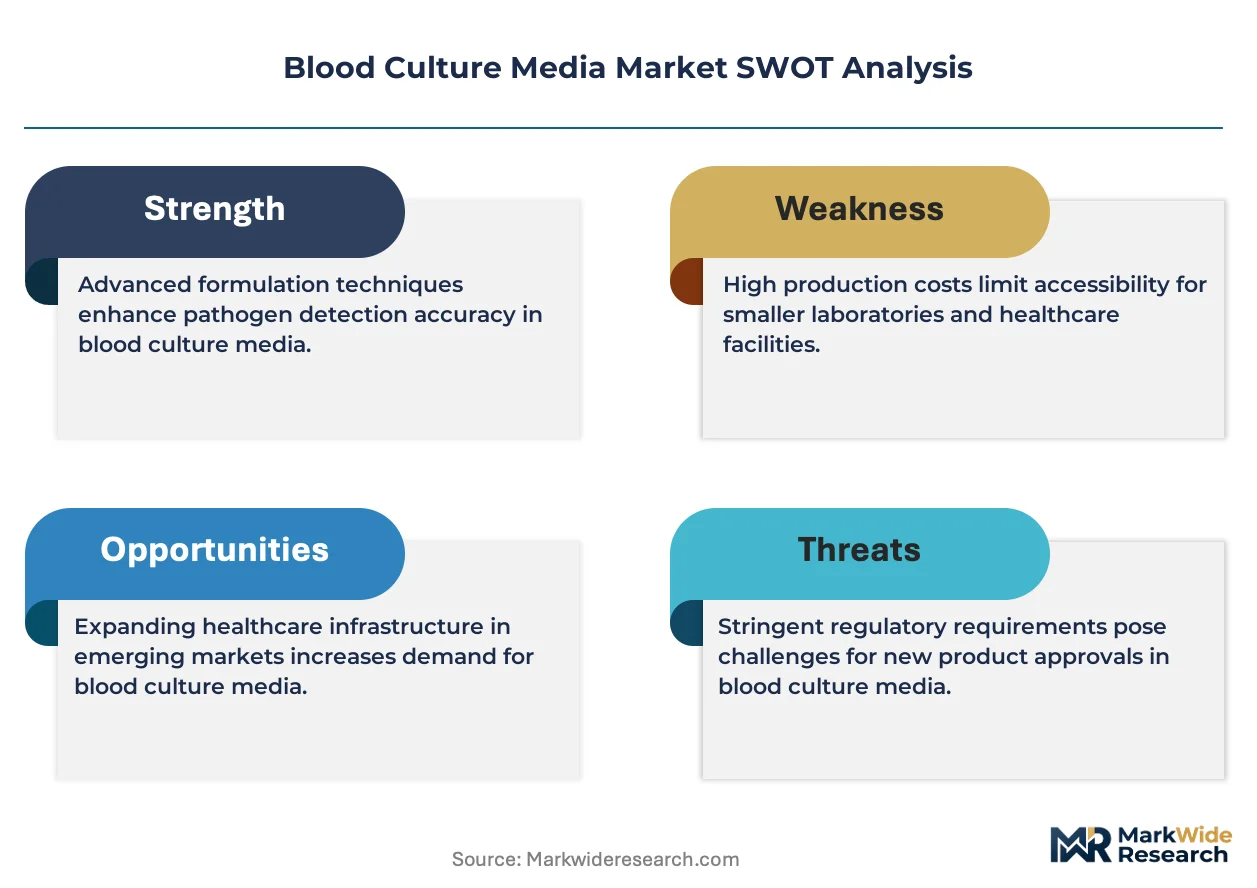
The FDA enforces stringent quality system requirements for blood culture media marketed as in vitro diagnostic devices, while the EU IVDR mandates enhanced clinical evidence and post-market surveillance for manufacturers seeking CE marking. Clinical Laboratory Improvement Amendments in the United States govern analytical performance standards that directly influence media selection by hospital laboratories. Stakeholders must monitor evolving regulatory convergence between FDA and notified body requirements as both jurisdictions tighten expectations for contamination control and analytical sensitivity documentation.
Market Dynamics
Antimicrobial stewardship programs in hospital systems are intensifying pressure for faster pathogen detection, forcing laboratories to reconfigure workflows around automated blood culture platforms and molecular adjunct technologies.
Growth Catalysts
- EU IVDR Implementation:Enhanced clinical evidence requirements for CE marking are filtering out substandard media suppliers, consolidating procurement toward validated manufacturers with robust quality systems.
- Sepsis Screening Protocols:Hospital emergency departments are embedding blood culture collection into triage workflows, expanding bottle consumption per patient encounter.
- Peptone Formulation Advances:Optimized nitrogen source blends are improving recovery rates for fastidious organisms, extending addressable pathogen coverage.
Market Restraints
- Sodium Polyanethol Sulfonate Volatility:Anticoagulant raw material costs fluctuate with petrochemical feedstock prices, compressing formulation margins.
- Single-Source Chromogenic Substrates:Specialty dye suppliers concentrate in Germany and Switzerland, creating geographic concentration risk for chromogenic media production.
- Anaerobic Recovery Limitations:Current aerobic-optimized systems miss 15-20% of bloodstream infections requiring strict anaerobic conditions, necessitating parallel workflow investments.
Strategic Opportunities
- India Diagnostic Expansion:Central government health mission funding for district hospital laboratories is creating first-time automated blood culture demand outside tier-one cities.
- Fungal Detection Adjuncts:Lysis-centrifugation paired with resin-containing media addresses rising candidemia incidence in immunocompromised patient populations.
- Digital Integration:Continuous monitoring systems with cloud-connected analytics are enabling remote laboratory oversight and networked antimicrobial stewardship.
Industry Challenges
- Microbiology Technologist Shortage:Specialized blood culture interpretation skills are declining as training programs shrink, forcing automation dependence.
- IVDR Technical Documentation Burden:CE marking renewal timelines have extended from 6 to 18 months, freezing product line extensions.
- Legacy System Interoperability:Proprietary data formats from incumbent automated platforms block seamless integration with third-party laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Culture Media Market |
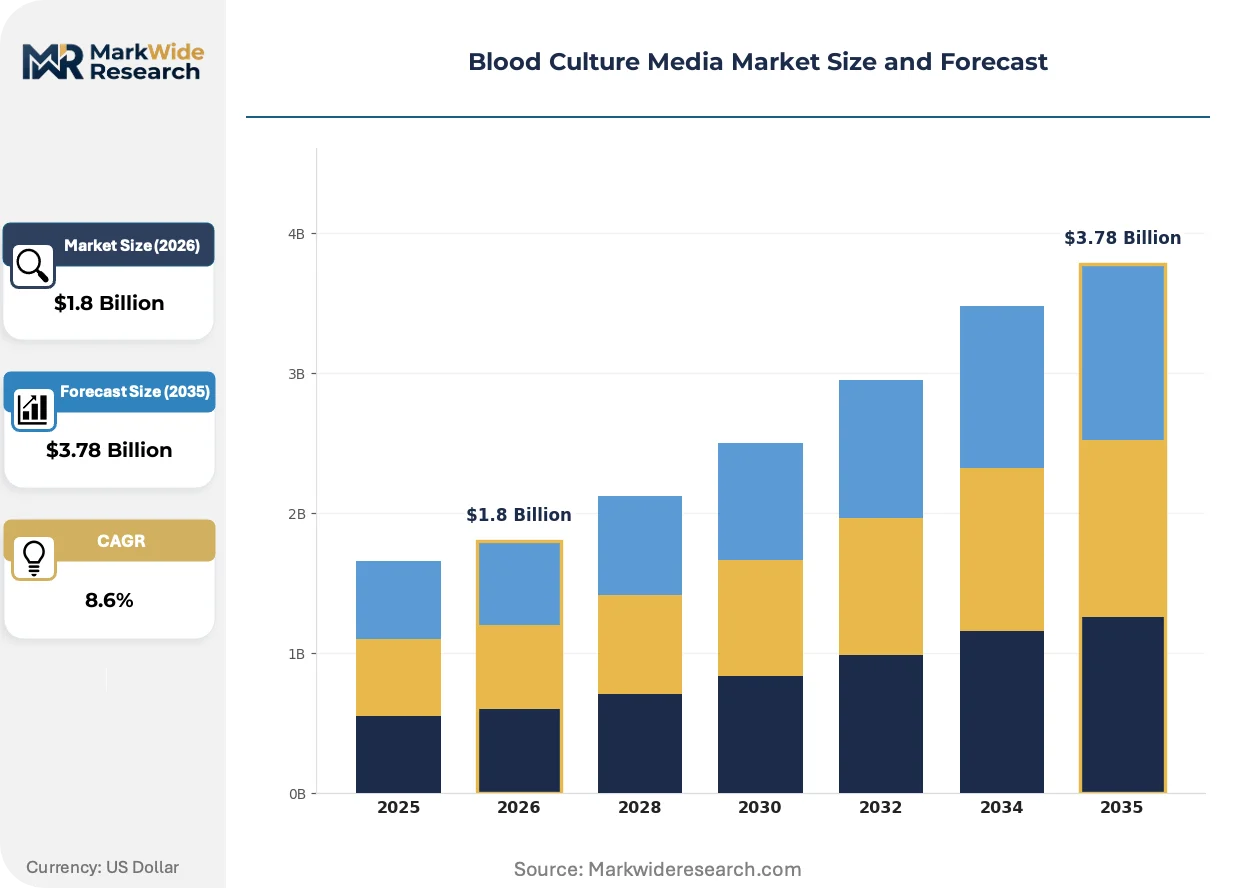
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broth Cultures, Agar Plates, Blood Culture Bottles, Specialty Media Technology: Automated Systems, Manual Techniques, Molecular Diagnostics, Conventional Methods End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Application: Infectious Disease Diagnosis, Pathogen Detection, Blood Transfusion Safety, Clinical Research |
| Companies Covered | Becton, Dickinson and Company, bioMérieux SA, Thermo Fisher Scientific, Roche Diagnostics, Bruker Corporation, Danaher Corporation, Luminex Corporation, Abbott Laboratories, T2 Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Culture Media Market Emerging Trajectories
Continuous monitoring instrumentation is displacing manual incubation and periodic inspection, while regulatory frameworks and procurement models are restructuring competitive access across hospital networks.
Rapid matrix-assisted laser desorption ionization time-of-flight mass spectrometry is decentralizing pathogen identification from centralized reference laboratories to acute care settings. Community hospitals with limited microbiology staffing are adopting benchtop platforms that interface directly with positive blood culture alerts. This convergence is compressing the window between culture positivity and targeted therapy initiation.
The EU In Vitro Diagnostic Regulation is mandating enhanced post-market surveillance and clinical performance documentation for blood culture media marketed as Class C devices. Manufacturers must maintain systematic vigilance data and periodic safety update reports, elevating compliance costs disproportionately for smaller formulation suppliers. German and French notified bodies are processing submissions with extended review cycles, delaying market access for novel chromogenic formulations.
Consolidated purchasing through regional laboratory networks is displacing individual hospital procurement autonomy in the United States. Multi-hospital systems are negotiating multi-year supply agreements with automated platform-integrated media suppliers, locking in volume commitments and technical service bundling. This concentration is most visible in Texas and Florida, where statewide laboratory cooperatives process sepsis screening for dozens of facilities under unified contracts.
Blood Culture Media Market Segmentation
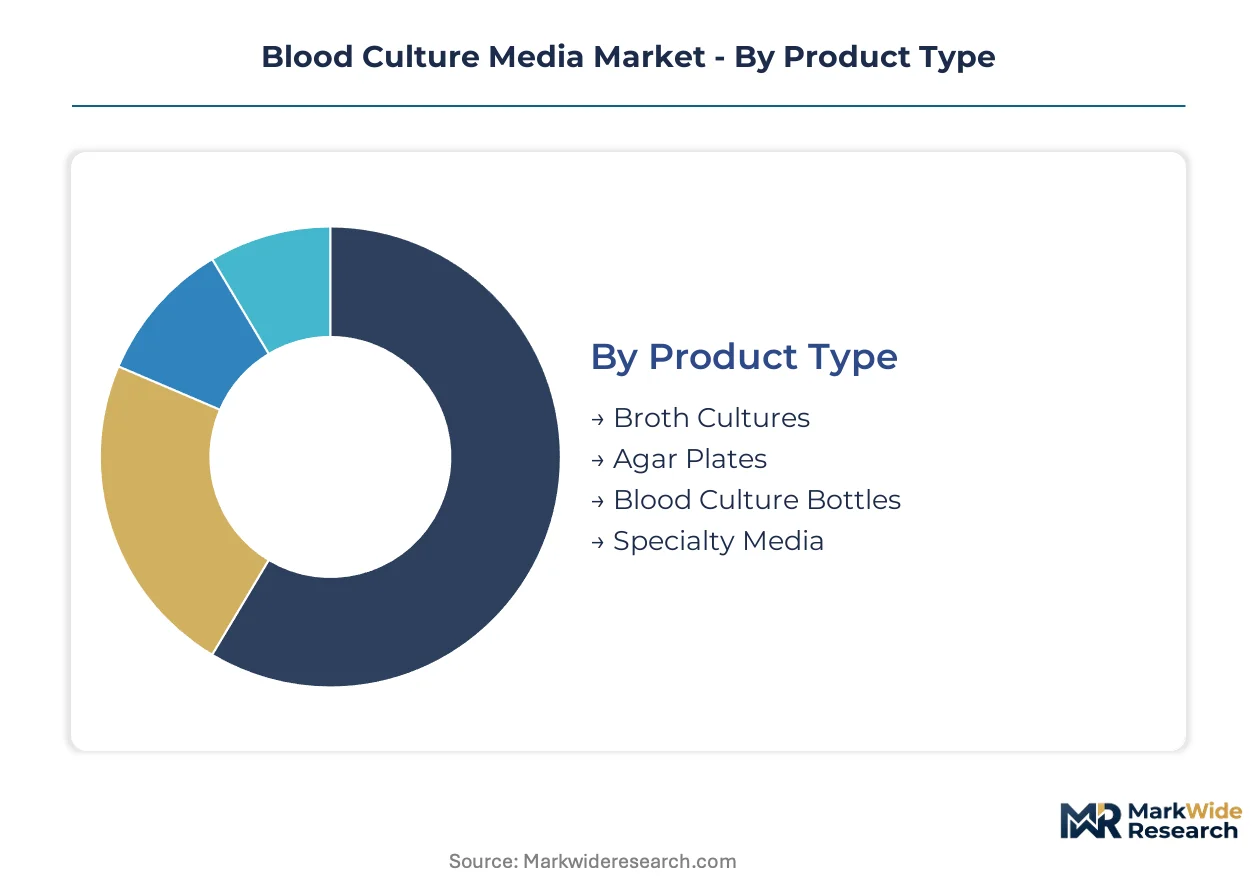
Blood culture media segmentation reflects divergent workflow architectures across laboratory settings. Product form factors determine compatibility with continuous monitoring instrumentation versus manual processing protocols. Technology tiers separate capital-intensive automated platforms from resource-constrained manual methods.
Product Type:
Standalone bottle formats integrate directly into automated incubation systems, while agar and broth variants require manual handling workflows.
- Blood Culture Bottles:Vacuum-sealed containers with pre-filled nutrient broth and anticoagulant formulations enable direct loading into automated incubation systems. Hospital emergency departments in the United States and Germany process the highest per-facility volumes as sepsis screening protocols expand.
- Specialty Media:Chromogenic and resin-containing formulations target fastidious organisms including HACEK group bacteria and fungal pathogens. Demand concentrates in tertiary care centers managing immunocompromised patient populations where standard recovery rates prove inadequate.
- Broth Cultures:Bulk liquid formulations support reference laboratory subculture workflows and antimicrobial susceptibility testing preparation.
- Agar Plates:Solid-phase media enable colony isolation and morphological identification following initial blood culture positivity.
Blood culture bottles lead volumes today; specialty media is gaining share fastest.
Technology:
Capital deployment thresholds separate institutional adopters, with molecular adjuncts commanding premium positioning alongside primary culture systems.
- Automated Systems:Continuous monitoring platforms with optical sensors detect microbial growth through CO2 production and fluorescence signaling. Major health systems in Japan and the United States prioritize these systems to offset microbiology technologist staffing shortages.
- Molecular Diagnostics:PCR and MALDI-TOF MS identification from positive blood cultures compresses time-to-pathogen identification. Academic medical centers deploy these technologies to meet antimicrobial stewardship program targets for targeted therapy initiation.
- Manual Techniques:Periodic visual inspection and subculture processing persist in resource-limited settings and smaller diagnostic laboratories.
- Conventional Methods:Gram staining and biochemical testing from positive cultures remain embedded in regulatory-compliant confirmation workflows.
Automated systems dominate installed base; molecular diagnostics shows steepest expansion trajectory.
End User:
Specimen volume scale and reimbursement structure determine procurement authority and media consumption intensity.
- Hospitals:Inpatient facilities with emergency departments and intensive care units generate the highest blood culture collection rates per licensed bed. Sepsis bundle compliance mandates in the United States and EU member states embed collection into triage protocols.
- Diagnostic Laboratories:Regional reference networks and commercial testing providers aggregate specimens from multiple collection sites. Centralized processing in Germany and Japan achieves economies of scale through high-throughput automated platform utilization.
- Research Institutions:Academic medical centers and contract research organizations utilize blood culture media for clinical trial safety monitoring and epidemiological surveillance studies.
- Blood Banks:Transfusion services apply bacterial detection protocols to platelet components and donor screening specimens.
Hospitals lead absolute consumption; diagnostic laboratories are expanding share through network consolidation.
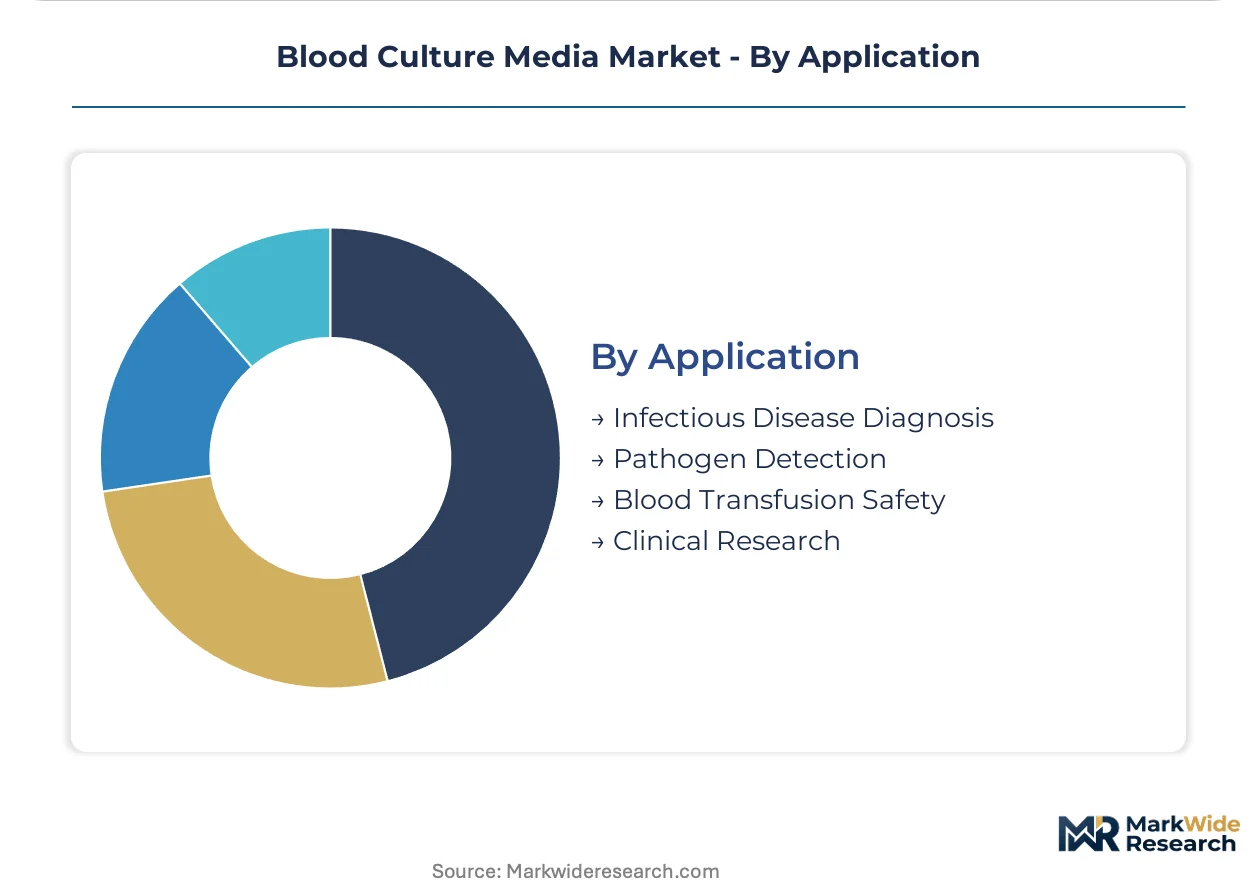
Application:
Clinical urgency and regulatory stringency differentiate testing categories, with infectious disease protocols commanding priority resource allocation.
- Infectious Disease Diagnosis:Sepsis and bacteremia detection represents the primary clinical indication driving blood culture utilization. FDA-cleared and CE-marked media formulations must demonstrate analytical sensitivity against reference strain panels.
- Pathogen Detection:Surveillance and outbreak investigation applications require expanded organism recovery capabilities including anaerobic and fungal coverage.
- Blood Transfusion Safety:Platelet bacterial contamination screening applies abbreviated culture protocols with rapid turnaround requirements.
- Clinical Research:Investigational drug trials and device validation studies utilize standardized media lots with documented quality control traceability.
Infectious disease diagnosis anchors current volumes; pathogen detection applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiology technologists cluster in Germany, Japan, and the United States, anchoring diagnostic capacity where automated blood culture adoption is most advanced. These talent concentrations determine where regulatory frameworks and procurement consolidation reshape competitive access.
United States
Hospital emergency departments embed blood culture collection into sepsis bundle protocols, driving per-facility bottle consumption. FDA quality system requirements filter supplier eligibility through analytical sensitivity documentation. Texas and Florida laboratory cooperatives negotiate multi-year supply agreements covering dozens of facilities under unified contracts.
Germany
Centralized laboratory networks in Bavaria and North Rhine-Westphalia achieve economies of scale through high-throughput automated platform utilization. EU IVDR mandates enhanced clinical evidence and post-market surveillance for CE marking, extending review timelines. German notified bodies process chromogenic media submissions with 18-month renewal cycles.
Japan
Metropolitan Tokyo and Osaka laboratory clusters prioritize continuous monitoring systems to offset microbiology staffing shortages. PMDA maintains stringent quality standards for in vitro diagnostic media marketed as medical devices. Academic medical centers in Kanto deploy MALDI-TOF MS identification to meet antimicrobial stewardship targets.
India
District hospital laboratories outside tier-one cities receive central government health mission funding for first-time automated blood culture installation. CDSCO regulates diagnostic media imports through quality control certification requirements. Maharashtra and Karnataka diagnostic clusters expand processing capacity for sepsis screening protocols.
United Kingdom
NHS laboratory networks consolidate procurement authority through regional pathology collaboratives in London and the Midlands. MHRA post-Brexit regulatory alignment maintains CE marking recognition while building UKCA capacity. Scottish and Northern Irish hospital systems coordinate blood culture media tendering through national supply frameworks.
Blood Culture Media Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the blood culture media landscape. Automated platform manufacturers with captive media supply chains hold structural advantages in multi-year hospital contracts. Three archetypes dominate: integrated diagnostic system suppliers, specialized chromogenic formulation specialists, and distribution-focused reagent providers. Consolidation through strategic partnerships and geographic expansion into emerging diagnostic laboratory markets represent the dominant competitive vectors.
Among integrated diagnostic conglomerates, Becton, Dickinson and Company and Danaher Corporation exemplify the capital-intensive archetype with automated platform-media bundling strategies. bioMérieux SA occupies a specialist position within the chromogenic formulation tier. Thermo Fisher Scientific represents the distribution-anchored model extending logistics infrastructure into developing markets. These three patterns structure how procurement consolidation and regulatory compliance costs filter competitive participation.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| bioMérieux SA |
| Thermo Fisher Scientific |
| Roche Diagnostics |
| Bruker Corporation |
| Danaher Corporation |
| Luminex Corporation |
| Abbott Laboratories |
| T2 Biosystems |
| Others |
Supply Flow & Price Mechanics
Specialized microbiology technologists in Germany and Japan command wage premiums that compress margins at formulation plants while creating three-tier pricing spreads between premium chromogenic media and economy-grade alternatives.
Pricing Analysis
Platform-integrated subscription pricing dominates hospital procurement, separating premium resin-containing formulations from standard aerobic bottles and economy manual-culture alternatives. Price differentiation hinges on CE marking tier under EU IVDR and bundled technical service levels. Pricing pressure stems from sodium polyanethol sulfonate feedstock volatility squeezing formulation margins. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize time-to-detection over unit cost.
Supply Chain Analysis
Direct-to-hospital contracts and regional laboratory cooperative agreements handle high-volume automated platform demand. Peptone suppliers concentrate in the United States and Germany, while chromogenic dye production rests on Swiss and German specialty chemical houses. Raw material dependencies include petrochemical-derived anticoagulants, nitrogen-source fermentation extracts, and resin-based adsorbents. Single-source chromogenic substrate concentration creates geographic vulnerability. Distribution runs through automated platform manufacturers with captive media supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood culture media market functions as a regulatory compounder where EU IVDR implementation timelines accelerate procurement consolidation toward validated manufacturers with documented clinical evidence packages.
For Market Incumbents: Acquire chromogenic formulation specialists to extend fastidious organism coverage and defend against molecular diagnostic adjunct substitution. Secure multi-year supply agreements with Texas and Florida laboratory cooperatives before IVDR renewal cycles freeze competitive access. Invest in post-market surveillance infrastructure to meet CE marking periodic safety update requirements. For New Entrants and Emerging Players: Enter via district hospital automation programs in Maharashtra and Karnataka where central government health mission funding creates first-time demand outside tier-one Indian cities. Target fungal detection adjunct formulations for immunocompromised patient populations. Pursue CDSCO import certification partnerships with established distribution networks. For Investors and Strategic Acquirers: Integrated diagnostic conglomerates are the most active acquirer in this space, seeking chromogenic media capabilities to complete platform bundling strategies. Long-term viability favors asset-light formulation specialists with IVDR technical documentation expertise over capital-heavy automated system manufacturers. Watch PMDA quality standard tightening in Japan as inflection indicator for regulatory convergence toward FDA-equivalent evidence requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Chromogenic Media Acquisition | Extends pathogen coverage for HACEK group and fungal detection in tertiary care centers. |
| IVDR Technical Documentation Buildout | Accelerates CE marking renewal timelines from 18 months toward competitive 12-month cycles. |
| District Hospital Automation Partnership | Captures first-time automated blood culture demand in Maharashtra and Karnataka diagnostic clusters. |
| Post-Market Surveillance Infrastructure | Generates systematic vigilance data required for Class C device periodic safety update reports. |
| MALDI-TOF MS Platform Integration | Compresses time-to-pathogen identification for antimicrobial stewardship program compliance. |
Methodological Framework
Multiple input streams — hospital laboratory directors, GPO contracts managers, regulatory affairs leads at IVD manufacturers, and biomedical engineers — were reconciled against FDA 510(k) filings, EU IVDR notified body submission databases, CDSCO import registration records, and hospital procurement contract disclosures. Bottom-up blood culture bottle consumption estimates from emergency department triage protocols were triangulated against top-down automated platform installed base counts.
Segment-level CAGRs across the projection horizon were derived from modeled interactions between sepsis screening protocol expansion, IVDR compliance cost pass-through, and antimicrobial stewardship program intensity. Segmentation dimensions included product form factor, technology tier, end-user facility type, and regional regulatory cluster. Forecast inputs incorporated peptone raw material cost indices and microbiology technologist workforce density by metropolitan statistical area.
Inputs from hospital procurement databases and GPO contract registries were available through the study window; gaps in notified body processing time data introduce uncertainty bands around CE marking renewal timeline assumptions. Forecasts reflect documented assumptions regarding EU IVDR implementation pacing and antimicrobial stewardship program adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
RT-PCR Kits Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Global Veterinary POC Diagnostic Market