
 Treponema Pallidum Tests Market | 2026-2036
Treponema Pallidum Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Treponema Pallidum Tests Market Analytics
Buyer concentration across hospital procurement networks is broadening as integrated delivery networks consolidate purchasing power while community clinics fragment demand into smaller, decentralized orders. Abbott Laboratories leverages its lateral flow manufacturing scale to serve high-volume screening contracts. Roche Diagnostics sustains premium positioning through automated immunoassay platforms. Siemens Healthineers anchors European hospital laboratory demand with integrated analyzer systems.
Treponema pallidum tests detect antibodies or nucleic acids from the bacterium causing syphilis, utilizing recombinant antigen preparations on nitrocellulose membranes or chemiluminescent microparticle substrates to achieve sensitivity thresholds below one nanogram per milliliter. These diagnostics serve public health screening, clinical confirmation, and blood safety verification purposes. Rapid tests and nucleic acid tests capture divergent margin pools, with point-of-care lateral flow devices commanding volume leadership in resource-limited settings while PCR-based platforms extract premium pricing from reference laboratories. Blood banks represent a structurally sticky end-user segment where regulatory mandates enforce recurring testing cadences.
The FDA's serological test guidance, WHO prequalification standards, and EU IVDR compliance frameworks collectively elevate validation burdens for market entrants while cementing incumbent positions. The FDA's updated donor screening requirements directly expand testing volumes across US blood collection facilities. Stakeholders must monitor evolving nucleic acid test reimbursement codes and polymerase chain reaction platform placement strategies in community health settings.
Market Dynamics
Automated immunoassay platforms are compressing turnaround times in hospital laboratories while lateral flow manufacturing scales tighten procurement leverage for high-volume screening contracts.
Growth Catalysts
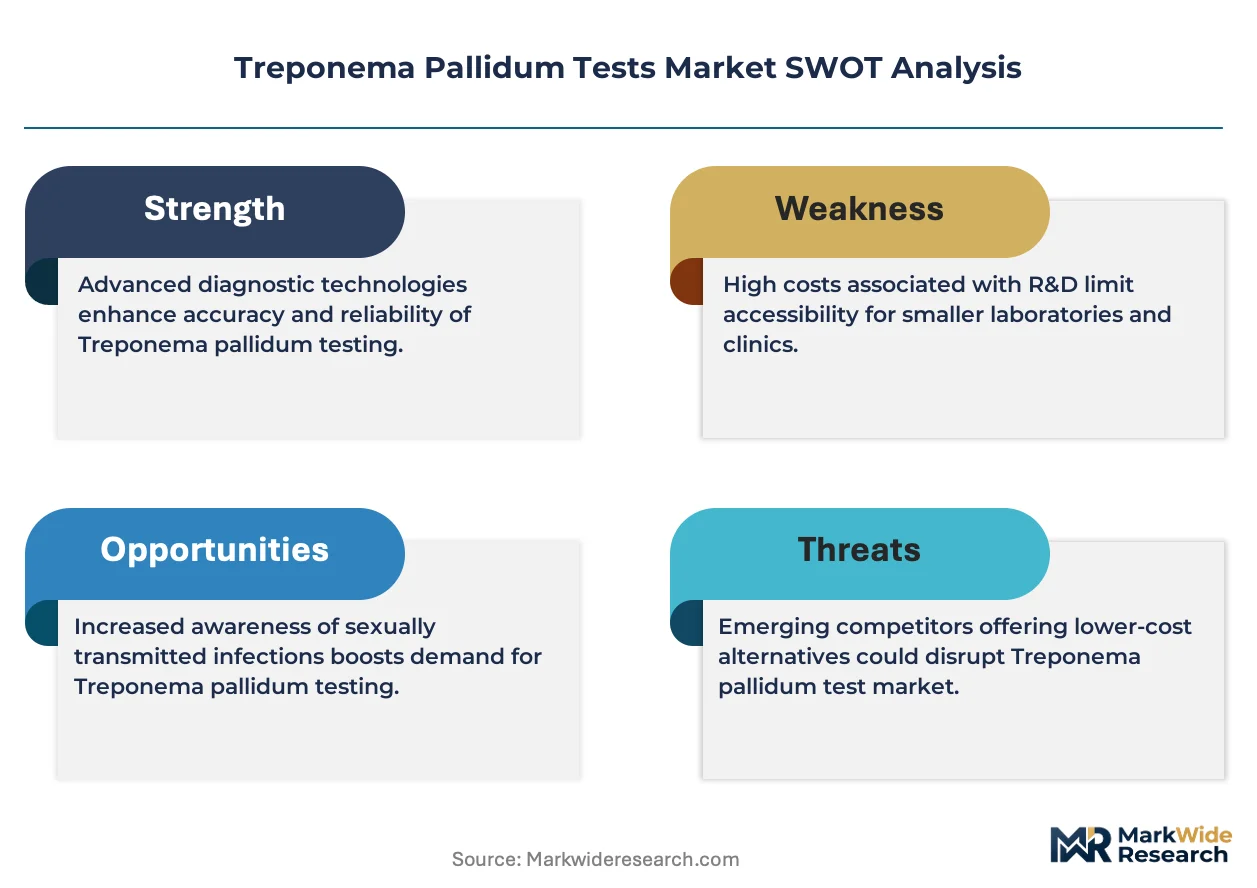
- Blood bank screening mandates:Regulatory protocols in the US enforce recurring testing cadences across collection facilities, creating structurally recurring demand for serological assays.
- EU IVDR compliance frameworks:Elevated validation requirements for in vitro diagnostics cement incumbent positions while raising barriers for new market entrants.
- Latin American public health expansion:Brazil and Mexico are deploying rapid diagnostic access programs in community health settings, broadening point-of-care test penetration.
Market Restraints
- Recombinant antigen input concentration:Nitrocellulose membrane supply chains concentrate among Asian specialty chemical producers, exposing manufacturers to raw material volatility.
- WHO prequalification timelines:Extended validation cycles for rapid diagnostic tests delay product entry into low-resource procurement programs.
- Nucleic acid amplification cost premiums:PCR platform capital requirements and reagent pricing limit adoption in decentralized clinic networks.
Strategic Opportunities
- Community health center channel development:Federally qualified health centers in the US represent underpenetrated volume for rapid treponemal tests outside traditional hospital procurement.
- Dual HIV-syphilis rapid test convergence:Multiplex lateral flow technology enables single-device screening programs targeting co-infection detection in maternal health settings.
- India's national syphilis elimination initiative:The country's health ministry is expanding antenatal screening access, creating procurement scale for domestically manufactured diagnostics.
Industry Challenges
- Chemiluminescent substrate formulation expertise:Microparticle chemistry talent scarcity constrains automated platform development timelines for mid-tier diagnostic firms.
- Legacy analyzer integration complexity:Reference laboratories face reconfiguration costs when connecting new treponemal assays to existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treponema Pallidum Tests Market |
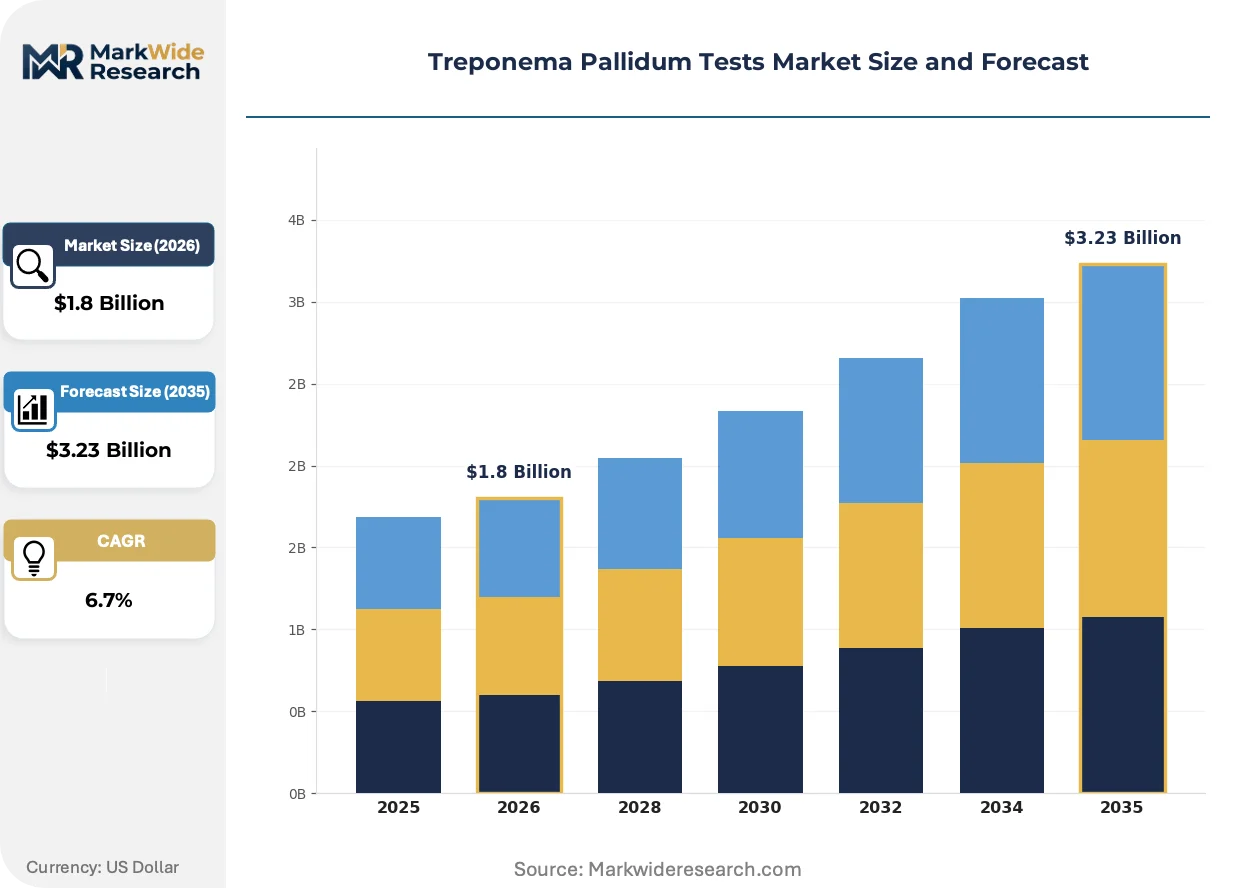
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Enzyme Immunoassays, Nucleic Acid Tests, Serological Tests End User: Hospitals, Laboratories, Clinics, Blood Banks Technology: Polymerase Chain Reaction, Immunofluorescence, Reverse Transcription, Lateral Flow Assay Application: Screening, Diagnosis, Surveillance, Research |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, bioMérieux, Becton Dickinson and Company, Bio-Rad Laboratories Inc., Danaher Corporation, Thermo Fisher Scientific Inc., DiaSorin SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treponema Pallidum Tests Market Evolving Landscape
Diagnostic platform architectures are bifurcating between high-throughput automation for centralized laboratories and miniaturized nucleic acid detection for decentralized deployment.
Isothermal amplification methods are rewriting the speed-versus-sensitivity trade-off in point-of-care syphilis detection. Community health clinics in resource-limited settings are adopting these chemistry platforms to bypass thermal cycler infrastructure requirements. The technology is compressing the window between sample collection and treatment initiation for exposed populations.
FDA's updated serological assay guidance is mandating enhanced specificity validation for treponemal screening tests. Blood collection facilities must now demonstrate cross-reactivity profiles against endemic treponematoses before assay implementation. US blood banks are responding by consolidating validation contracts with manufacturers holding pre-cleared 510(k) portfolios.
Integrated delivery networks are consolidating diagnostic procurement across multi-hospital systems, compressing vendor negotiation cycles from annual to quarterly rhythms. Traditional distributor relationships are yielding to direct manufacturer contracts with standardized pricing tiers. This concentration is most visible in US metropolitan markets where three-hospital systems anchor regional laboratory services.
Treponema Pallidum Tests Market Segmentation
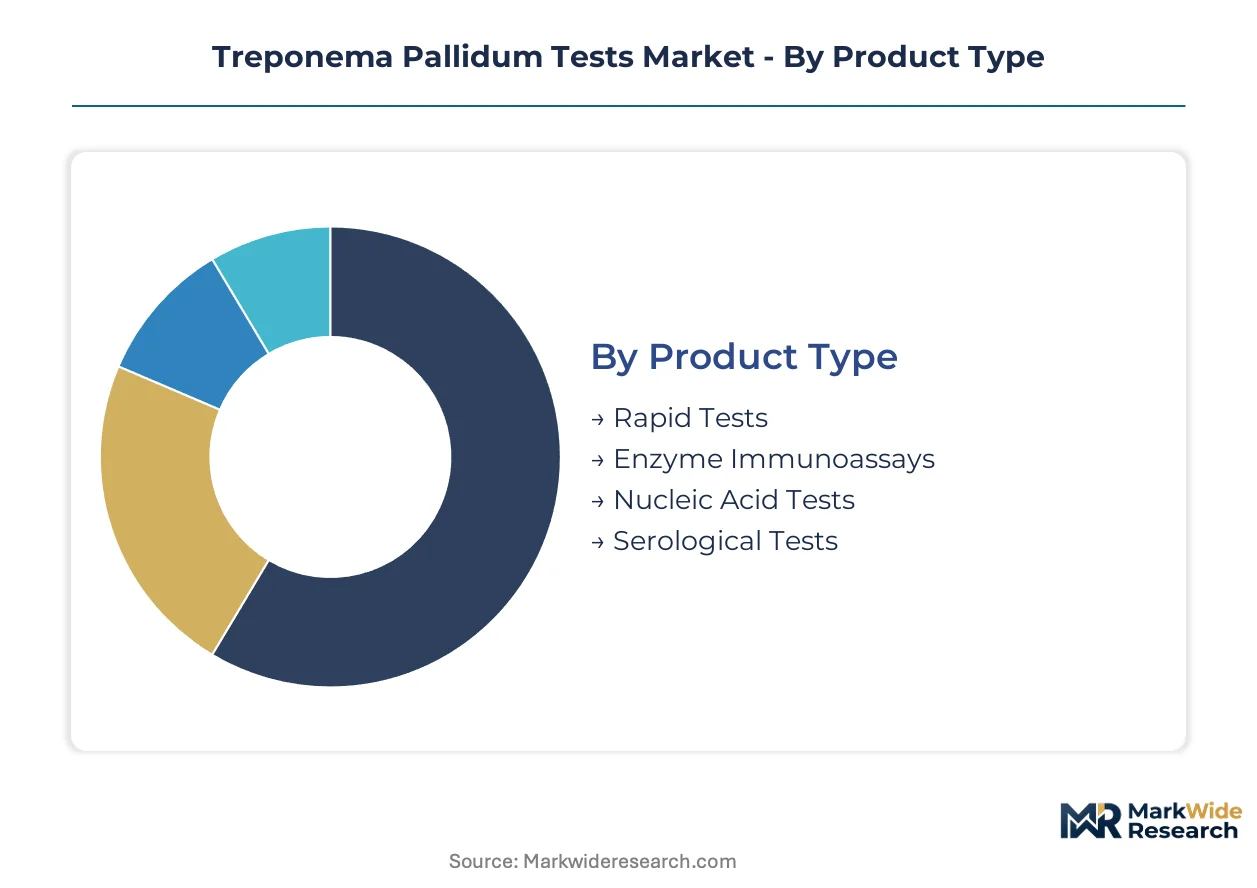
Segmentation in the Treponema Pallidum Tests Market reveals how testing modalities bifurcate between high-throughput centralized infrastructure and decentralized point-of-care deployment. Procurement patterns diverge sharply across end-user settings, with blood banks enforcing rigid validation standards while community clinics prioritize speed and portability.
Product Type:
Supply concentration in nitrocellulose membrane manufacturing shapes competitive dynamics across product categories, with lateral flow substrate availability determining production scalability for rapid test manufacturers.
- Rapid Tests:Lateral flow devices deploy recombinant treponemal antigens on nitrocellulose membranes, achieving qualitative results in 15-20 minutes without laboratory infrastructure. Demand concentrates in Brazil and Mexico where public health programs distribute point-of-care kits to community health workers. Brazil's SUS network procurement accounts for substantial volume in Latin American distribution.
- Enzyme Immunoassays:Microplate or chemiluminescent formats detect treponemal antibodies with quantitative sensitivity thresholds below one nanogram per milliliter. Hospital laboratories in Germany and France anchor European demand through automated platform integration. EU IVDR compliance requirements favor manufacturers with established quality management systems.
- Nucleic Acid Tests:PCR platforms target treponemal DNA with analytical specificity unobtainable through serological methods. Reference laboratories in the US deploy these for early infection detection where antibody responses remain undetectable.
- Serological Tests:Traditional flocculation and agglutination assays persist in resource-constrained settings where cold chain requirements limit reagent stability. India's national health programs maintain procurement contracts for these established formats.
Today's leader: Rapid Tests. Tomorrow's challenger: Nucleic Acid Tests.
End User:
Procurement consolidation across integrated delivery networks is compressing vendor margins for hospital segment suppliers while fragmenting demand into smaller orders from independent clinics.
- Hospitals:Acute care facilities require STAT turnaround capabilities for emergency department syphilis screening in pregnant patients presenting with unknown serostatus. US metropolitan three-hospital systems negotiate quarterly pricing tiers through direct manufacturer contracts.
- Laboratories:Reference and hospital-affiliated labs process high-volume screening panels with automated immunoassay platforms. Siemens Healthineers anchors substantial European laboratory demand through integrated analyzer placements.
- Clinics:Federally qualified health centers in the US represent underpenetrated volume for rapid treponemal tests outside traditional hospital procurement channels. Staffing constraints drive preference for waived-complexity testing formats.
- Blood Banks:Regulatory mandates enforce recurring testing cadences across collection facilities, creating structurally sticky demand for FDA-cleared serological assays. US blood collection facilities must demonstrate cross-reactivity profiles against endemic treponematoses before assay implementation.
Volume concentrates with Blood Banks. Margin expansion sits with Clinics.
Technology:
Platform chemistry expertise scarcity constrains development timelines, with microparticle formulation talent concentrated among incumbent diagnostic firms.
- Polymerase Chain Reaction:Thermal cycling amplification of treponemal DNA targets delivers definitive early infection detection. Capital equipment requirements and reagent pricing limit adoption in decentralized clinic networks despite superior analytical performance.
- Immunofluorescence:Direct fluorescent antibody staining of treponemal organisms requires specialized microscopy infrastructure and trained technologist interpretation. Reference laboratories retain this capability for confirmatory testing algorithms.
- Reverse Transcription:RNA-targeting amplification methods detect viable treponemal organisms, offering potential for treatment response monitoring. Research applications currently dominate clinical deployment.
- Lateral Flow Assay:Capillary-driven immunochromatography enables equipment-free operation in resource-limited settings. Isothermal amplification integration is rewriting speed-versus-sensitivity trade-offs for point-of-care deployment.
Maturity favors Lateral Flow Assay. Technical displacement threatens from isothermal amplification convergence.
Application:
Reimbursement coding differentiation creates margin stratification across use cases, with surveillance and research applications commanding premium pricing through grant-funded procurement.
- Screening:Population-level antibody detection programs target pregnant women, blood donors, and high-prevalence communities. India's national syphilis elimination initiative expands antenatal screening access, creating procurement scale for domestically manufactured diagnostics.
- Diagnosis:Symptomatic patient evaluation requires confirmatory algorithms combining treponemal and non-treponemal assays. Clinical laboratories sequence testing to resolve discordant results.
- Surveillance:Public health authorities track infection prevalence and antimicrobial resistance patterns through sentinel site reporting. WHO prequalification standards govern test selection for national program procurement.
- Research:Academic and pharmaceutical studies employ specialized assay formats for vaccine development and novel therapeutic evaluation. Extended validation cycles delay product entry into low-resource procurement programs.
Procurement volume flows to Screening. Pricing power accumulates in Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States blood collection facilities enforce stricter donor screening protocols than German hospital laboratories, yet both jurisdictions drive substantial automated platform demand through divergent procurement models.
United States
FDA donor screening mandates and integrated delivery network consolidation propel automated immunoassay procurement. The agency's updated serological assay guidance mandates enhanced specificity validation for treponemal screening. Three-hospital systems in metropolitan markets anchor regional laboratory services through quarterly manufacturer contracts.
Germany
EU IVDR compliance frameworks and reference laboratory automation sustain premium analyzer placements. EMA-aligned quality management requirements favor established manufacturers with documented quality systems. Siemens Healthineers anchors substantial European hospital laboratory demand through integrated analyzer placements in Bavaria and North Rhine-Westphalia.
Brazil
Public health program expansion and community health worker distribution networks broaden rapid test penetration. ANVISA regulatory oversight governs diagnostic registration for the SUS network. São Paulo and Rio de Janeiro metropolitan regions concentrate procurement volume for point-of-care lateral flow devices.
India
National syphilis elimination initiative funding and antenatal screening access programs create domestic manufacturing scale. CDSCO regulates in vitro diagnostic imports while the health ministry expands rural screening infrastructure. Maharashtra and Gujarat host emerging diagnostic production clusters serving government procurement contracts.
Japan
Reference laboratory consolidation and automated platform standardization sustain premium reagent demand. PMDA quality standards enforce rigorous post-market surveillance for serological assays. Kanto and Kansai regions concentrate hospital-affiliated laboratory networks deploying high-throughput screening panels.
Treponema Pallidum Tests Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and rapid test segments. The vendor base stratifies into three tiers: multinational conglomerates with cross-portfolio leverage, regional specialists with regulatory pre-qualification advantages, and emerging entrants targeting price-sensitive procurement programs. Strategic moves concentrate on automated platform placement contracts and rapid test manufacturing scale expansion.
Among diversified conglomerates, Abbott Laboratories and Roche Diagnostics exemplify contrasting scale strategies. Abbott leverages lateral flow manufacturing scale to serve high-volume screening contracts across public health networks. Roche sustains premium positioning through automated immunoassay platforms in reference laboratory settings. Siemens Healthineers occupies a position anchoring European hospital demand through integrated analyzer systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| bioMérieux |
| Becton Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| DiaSorin SpA |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between FDA-cleared automated platforms and waived-complexity rapid devices manifests in divergent margin architectures and procurement channel configurations across hospital networks and community health settings.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for rapid treponemal tests, compressing margins on lateral flow devices while automated immunoassay platforms sustain premium positioning through instrument-reagent bundling contracts. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status, WHO prequalification tier, and regional manufacturing origin. Pricing pressure stems from consolidated procurement across US integrated delivery networks, where quarterly vendor negotiations compress reagent pricing. Blood banks exhibit lowest price sensitivity due to regulatory mandate enforcement, while federally qualified health centers demonstrate highest sensitivity to per-test costs.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Miami anchor hub-and-spoke patterns for temperature-sensitive reagent logistics, with cold chain integrity governing transit windows for enzyme immunoassay components. Nitrocellulose membrane production concentrates in China and Japan, while recombinant antigen synthesis clusters in Germany and the United States. Single-source vulnerability in specialty chemical substrates exposes manufacturers to input volatility. Distribution runs through diagnostic distributor networks and direct manufacturer contracts, with hospital systems increasingly favoring latter arrangements for standardized pricing tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with demand gravitating toward automated platforms delivering enhanced specificity validation under tightened FDA serological assay guidance.
For Market Incumbents: To counter isothermal amplification displacement in point-of-care settings, Abbott Laboratories and Roche Diagnostics should deepen backward integration into nitrocellulose substrate manufacturing and accelerate chemiluminescent microparticle chemistry R&D. Securing multi-year placement contracts with US three-hospital systems locks in revenue visibility against emerging entrant price competition. For New Entrants and Emerging Players: Enter via Brazil's SUS network procurement channels and India's national syphilis elimination initiative, where domestic manufacturing requirements and price-sensitive public health budgets favor local production partnerships. Federally qualified health centers in the US Southeast represent the most penetrable segment, accessible through waived-complexity CLIA certification positioning and community health worker training programs. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding ANVISA or CDSCO prequalification advantages and established quality management systems for EU IVDR compliance. Five-to-ten year viability favors automated platform manufacturers with installed base expansion potential over pure-play rapid test producers facing margin compression. Monitor nucleic acid test reimbursement code expansions in US community health settings as inflection indicator for PCR platform adoption trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Dual HIV-Syphilis Multiplex Development | Single-device screening programs target maternal health co-infection detection in Brazil and India. |
| Isothermal Amplification Platform Launch | Loop-mediated amplification chemistry bypasses thermal cycler infrastructure in resource-limited clinics. |
| EU IVDR Quality System Certification | Documented quality management systems cement incumbent positions in German hospital laboratory procurement. |
| Integrated Delivery Network Direct Contract | Quarterly pricing tiers with US metropolitan three-hospital systems compress distributor intermediation. |
| Domestic Manufacturing Joint Venture | Local production in Maharashtra and Gujarat serves India's government antenatal screening procurement. |
Research Methodology
Coverage spans North America, Europe, Latin America, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and procurement databases. Diagnostic industry stakeholders including hospital laboratory directors, blood bank technical supervisors, GPO contracts managers, and biomedical engineers contributed qualitative inputs. Secondary sources encompass FDA 510(k) clearances, WHO prequalification listings, ANVISA registration databases, and EU IVDR technical documentation. Bottom-up test volume modeling triangulates against top-down market sizing from automated platform placements and rapid test distribution records.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the analysis window, with segmentation modeling across product type, end user, technology, and application dimensions. CAGRs derive from test volume trajectories in blood bank screening mandates, antenatal program expansions, and point-of-care adoption curves. Industry-specific forecast inputs include lateral flow manufacturing capacity additions, PCR platform placement cycles, and isothermal amplification chemistry validation timelines.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time distributor inventory data introduce uncertainty bands around rapid test volume estimates. Forecasts reflect documented assumptions regarding FDA guidance implementation timelines and public health program funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
DNA and RNA Probes Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global Companion Animal Diagnostics Market