
 E.Coli Latex Agglutination Test Kits Market | 2026-2036
E.Coli Latex Agglutination Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
E.Coli Latex Agglutination Test Kits Market Insights
Hospital procurement consortia is reshaping how E.coli latex agglutination test kits reach end users in the United States, with group purchasing organizations now dictating volume terms and supplier qualification criteria. Thermo Fisher Scientific leverages its diagnostic reagent manufacturing scale to sustain long-term supply agreements with integrated delivery networks. bioMérieux SA anchors its competitive stance through specialized microbiology testing portfolios that dominate reference laboratory channels. Hardy Diagnostics differentiates by occupying regional hospital markets with customized kit configurations and responsive technical service capabilities.
E.coli latex agglutination test kits employ latex particles coated with specific antibodies that visibly clump when exposed to target bacterial antigens, with sensitivity thresholds typically reaching detection limits suitable for clinical screening applications. Direct agglutination formats lead hospital laboratory adoption due to streamlined workflow integration and minimal equipment requirements, while lateral flow assays represent the fastest-growing product category as point-of-care settings demand result turnaround under fifteen minutes. Food safety agencies constitute a concentrated margin pool where regulatory audit frequency drives consistent kit replenishment cycles and premium pricing for certified reagent lots.
FDA quality system regulations and ISO 13485 medical device standards govern kit manufacturing validation, with FDA premarket notification pathways shaping product commercialization timelines for new entrants. The EPA's recreational water quality criteria indirectly stimulate kit demand by mandating E.coli monitoring protocols that laboratories must fulfill with standardized detection methods. Stakeholders must monitor evolving CLIA complexity classifications that could reclassify certain agglutination formats and alter laboratory personnel requirements for test execution.
Market Dynamics
Hospital-acquired infection surveillance mandates in the United States are compressing test turnaround requirements, forcing laboratories to requalify suppliers around same-day result capabilities rather than batch-processing economics.
Growth Catalysts
- Food Safety Modernization Act enforcement:FDA audit frequency for food processing facilities drives consistent kit replenishment cycles and elevates demand for certified reagent lots with documented traceability.
- Point-of-care workflow integration:Lateral flow assay formats penetrate urgent care clinics and physician office laboratories seeking pathogen screening without capital-intensive instrumentation.
- Recreational water monitoring expansion:EPA beach water quality criteria mandate E.coli detection protocols that environmental testing laboratories must fulfill with standardized agglutination methods.
Market Restraints
- Antibody raw material concentration:Polyclonal antibody production concentrates among specialized bioreactor operators in the United States and Western Europe, exposing kit manufacturers to batch-to-batch variability and extended lead times.
- CLIA complexity classification friction:Potential reclassification of direct agglutination formats to moderate-complexity status would trigger personnel certification requirements that smaller hospital laboratories cannot absorb.
- Molecular PCR substitution threat:Nucleic acid amplification platforms achieve single-digit colony-forming unit sensitivity that latex agglutination cannot match, capturing reference laboratory volume for definitive diagnosis.
Strategic Opportunities
- Veterinary diagnostic white space:Livestock and companion animal health screening represents an underpenetrated application where pathogen detection protocols mirror human clinical requirements but face less entrenched supplier relationships.
- Multiplexing technology convergence:Combination of latex particle engineering with fluorescent reporter systems enables simultaneous E.coli serotyping and virulence marker detection in single-reaction formats.
- Group purchasing organization channel innovation:Integrated delivery network procurement consortia create consolidated volume commitments that favor suppliers with manufacturing scale and long-term contract flexibility.
Industry Challenges
- ISO 13485 certification timeline compression:New entrants face eighteen-to-twenty-four month quality system validation periods before FDA premarket notification submission, delaying revenue generation and consuming working capital.
- Legacy laboratory information system integration:Hospital IT departments resist middleware development for result transmission from standalone agglutination readers, forcing manual data entry that erodes workflow efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E.Coli Latex Agglutination Test Kits Market |
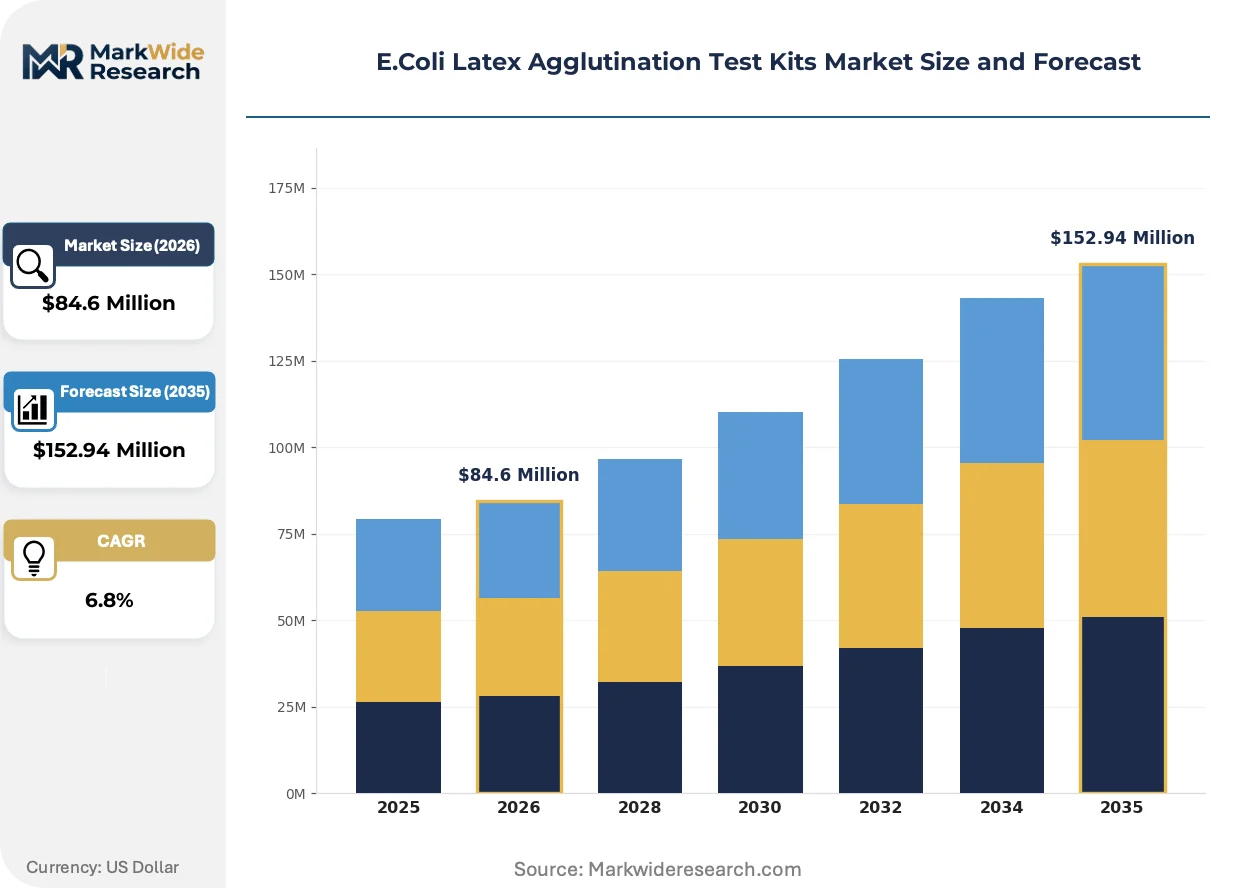
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $152.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Agglutination, Indirect Agglutination, Microparticle Agglutination, Lateral Flow Assays Application: Clinical Diagnostics, Water Quality Testing, Food Safety Testing, Research Laboratories End User: Hospitals, Diagnostic Centers, Commercial Laboratories, Food Safety Agencies Distribution Channel: Online Retail, Medical Supply Distributors, Direct Sales, Wholesalers |
| Companies Covered | Atlas Medical GmbH, Thermo Fisher Scientific Inc., bioMérieux SA, Bio-Rad Laboratories, Inc., Cardinal Health, Eurofins Scientific, Hardy Diagnostics, Creative Diagnostics, Liofilchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E.Coli Latex Agglutination Test Kits Market Trends and Innovations
Digital result interpretation and connected instrument platforms are restructuring how laboratories validate and document agglutination reactions, shifting competitive advantage toward software-integrated suppliers.
Fluorescent nanoparticle enhancement is virtualizing traditional visible-clump detection by enabling quantitative signal measurement through handheld fluorometers. Reference laboratories in the United States adopt these systems to replace subjective manual reading with objective threshold-based calling. The technology is virtualizing quality control documentation by generating machine-readable result files that integrate directly with laboratory information systems.
EPA recreational water quality criteria revisions tighten allowable E.coli thresholds for beach closures, expanding required test frequency during summer monitoring seasons. Environmental testing contractors respond by stocking higher kit volumes and qualifying secondary suppliers to avoid stockout risk during peak demand windows. Coastal municipalities in California, Florida, and New York represent the most affected geographies where delayed results trigger immediate public notification requirements.
Consolidated procurement through hospital group purchasing organizations concentrates volume among contracted suppliers and compresses switching flexibility for individual laboratories. Integrated delivery networks negotiate multi-year supply agreements that bundle E.coli kits with broader microbiology consumables, displacing standalone regional distributors. The phenomenon is most visible in the United States Midwest and Southeast where health system mergers have created super-regional purchasing entities controlling fifty-plus hospital laboratories.
E.Coli Latex Agglutination Test Kits Market Segmentation
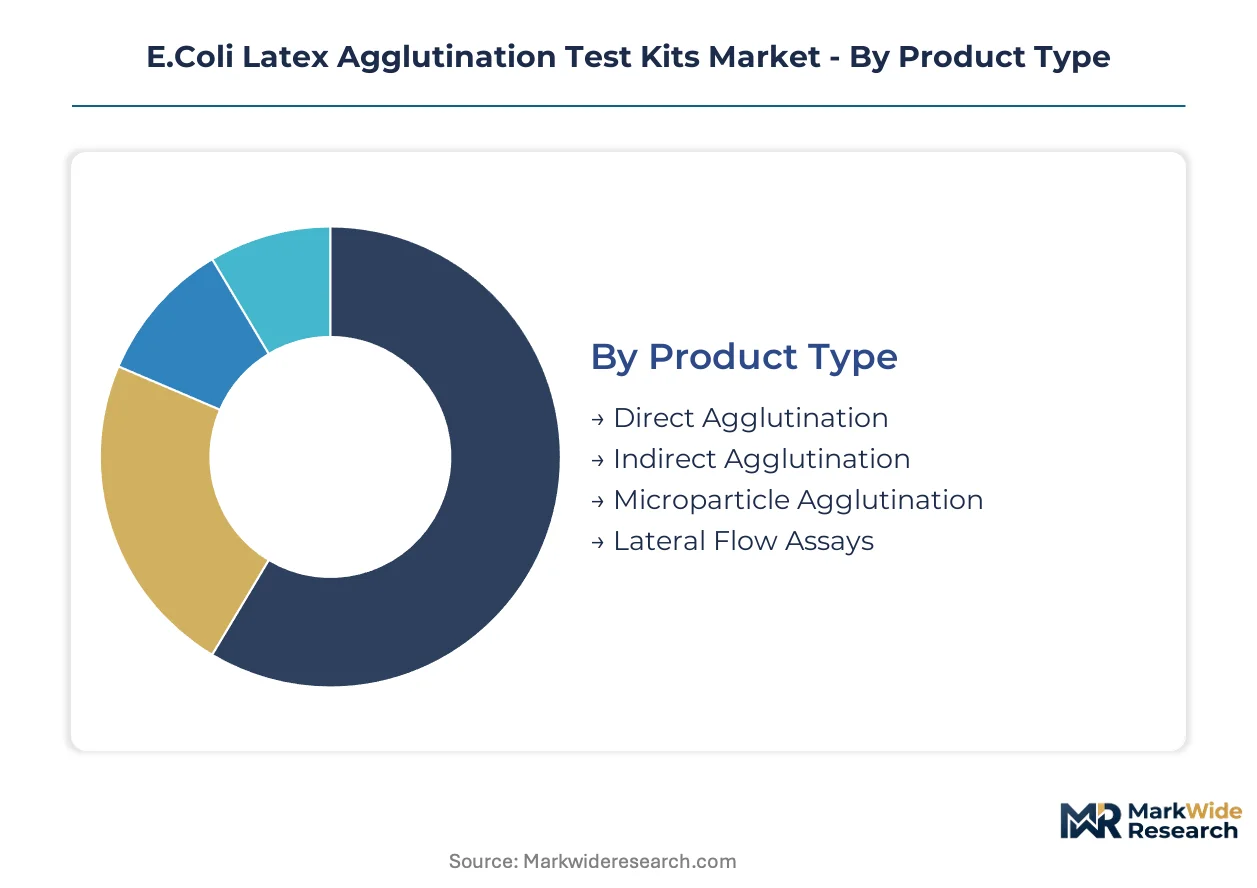
E.Coli latex agglutination test kits serve divergent operational environments requiring distinct performance specifications, workflow integration capabilities, and regulatory compliance profiles. Segmentation reveals how manufacturers align product architectures with end-user technical constraints and procurement patterns across clinical, environmental, and food safety domains.
Product Type:
Clinical laboratories and field testing operations deploy formats spanning simple visual assays to instrument-enhanced detection systems, with workflow speed and capital requirements driving selection.
- Direct Agglutination:Antibody-coated latex particles react visibly with bacterial antigens without secondary reagent steps, enabling processing in resource-limited hospital laboratories lacking automated platforms. Hospital procurement consortia in the United States favor this format for routine screening volumes where same-day turnaround satisfies infection surveillance mandates.
- Lateral Flow Assays:Membrane-based chromatographic strips deliver results under fifteen minutes through capillary action, requiring no equipment or trained microscopists. Urgent care clinics and physician office laboratories in Florida and Texas adopt these formats for point-of-care pathogen screening where capital-intensive instrumentation is impractical.
- Indirect Agglutination:Two-step reaction sequences using uncoated particles and separate antibody solutions achieve enhanced specificity for serotyping applications. Reference laboratories employ this format for epidemiological investigations requiring strain differentiation.
- Microparticle Agglutination:Submicron particle engineering improves sensitivity thresholds for low-bacterial-load specimens. Environmental testing contractors deploy these systems for EPA-mandated recreational water monitoring where detection limits approach regulatory action thresholds.
Established volume favors direct agglutination; emerging adoption favors lateral flow assays.
Application:
Regulatory enforcement intensity and testing frequency create divergent margin structures across end-use sectors, with food safety and water quality applications commanding premium pricing for certified reagent lots.
- Clinical Diagnostics:Hospital-acquired infection surveillance programs mandate routine E.coli screening with documented traceability for Joint Commission compliance. United States hospital laboratories process high-throughput volumes under compressed turnaround requirements, favoring suppliers with same-day replenishment capabilities.
- Food Safety Testing:FDA Food Safety Modernization Act enforcement drives consistent kit replenishment cycles at processing facilities subject to unannounced audits. Meat and poultry operations in the Midwest maintain standing orders with documented lot certification to satisfy USDA-FSIS verification protocols.
- Water Quality Testing:EPA recreational water criteria mandate E.coli monitoring at public beaches with immediate closure authority for threshold exceedances. California and New York municipalities stock elevated kit volumes during summer monitoring seasons to avoid stockout risk.
- Research Laboratories:Academic and government research facilities employ agglutination assays for method validation and epidemiological studies. Funding cyclicality creates lumpy demand patterns distinct from regulated commercial testing.
Regulatory compliance intensity concentrates margin in food safety; seasonal demand volatility characterizes water quality applications.
End User:
Procurement scale and technical sophistication create distinct customer segments with diverging supplier relationship requirements and price sensitivity profiles.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling E.coli kits with broader microbiology consumables. Super-regional purchasing entities in the United States Midwest and Southeast control fifty-plus hospital laboratories, concentrating volume among contracted suppliers.
- Diagnostic Centers:Independent reference laboratories demand high-throughput formats with laboratory information system integration. CLIA complexity classification sensitivity shapes personnel requirements and workflow design preferences.
- Commercial Laboratories:Environmental and food testing contractors serve dispersed geographic markets with variable seasonal demand. Secondary supplier qualification mitigates stockout risk during peak monitoring windows.
- Food Safety Agencies:Government laboratories enforce standardized methods with mandatory proficiency testing participation. Premium pricing for certified reagent lots reflects audit documentation requirements.
Consolidated procurement favors hospitals; specialized technical requirements favor diagnostic centers.
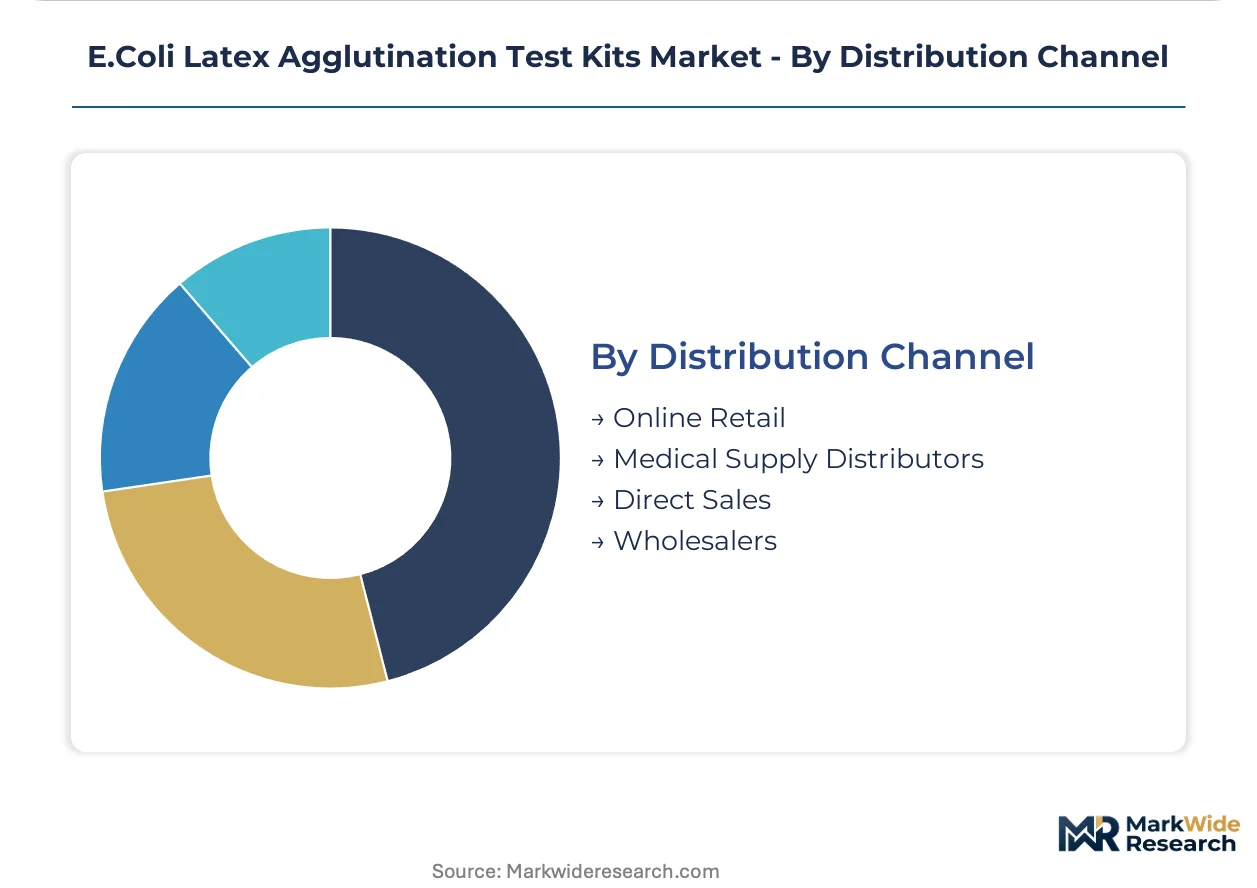
Distribution Channel:
Channel selection reflects order scale predictability, technical service requirements, and geographic coverage needs across end-user segments.
- Medical Supply Distributors:Regional distributors maintain local inventory positions and responsive technical service capabilities for hospital laboratories. Hardy Diagnostics occupies this channel with customized kit configurations and field application support.
- Direct Sales:Manufacturers engage large integrated delivery networks through dedicated account management and long-term contract flexibility. Thermo Fisher Scientific leverages manufacturing scale to sustain direct supply agreements.
- Online Retail:E-commerce platforms serve small research laboratories and veterinary clinics with low-volume, sporadic purchasing patterns. Price transparency intensifies competitive pressure in this segment.
- Wholesalers:Broad-line medical product wholesalers provide one-stop procurement convenience for smaller laboratories lacking specialized microbiology sourcing expertise.
Relationship-based contracting favors direct sales; transactional efficiency favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for certified reagent lots commands 30-40% markups in the United States compared to European tenders, where centralized procurement pools compress supplier margins. This asymmetry shapes how manufacturers allocate production capacity and prioritize regulatory compliance investments across geographies.
United States
Hospital-acquired infection surveillance mandates drive routine E.coli screening volumes through integrated delivery networks controlling fifty-plus laboratories. FDA Food Safety Modernization Act enforcement elevates kit performance standards with documented traceability requirements. California and Florida municipalities stock elevated volumes during summer beach monitoring seasons to satisfy EPA recreational water criteria.
Germany
Reference laboratory networks demand high-throughput formats with automated result documentation for epidemiological surveillance. EU In Vitro Diagnostic Regulation implementation extends quality system validation timelines for new kit introductions. Bavaria's clinical diagnostics cluster anchors microbiology testing innovation with specialized proficiency testing programs.
France
Food safety agencies enforce standardized detection methods with mandatory audit documentation for meat processing facilities. ANSM medical device oversight aligns with EU MDR requirements for clinical diagnostic kits. The Paris-Saclay research corridor supports method validation studies for emerging agglutination formats.
United Kingdom
NHS procurement frameworks consolidate microbiology consumables purchasing across hospital trusts, compressing supplier switching flexibility. UK Health Security Agency protocols mandate E.coli detection for environmental health investigations. Greater Manchester's integrated care systems pilot point-of-care screening in urgent care networks.
Japan
PMDA quality system regulations govern kit manufacturing validation with extended premarket review periods for novel detection formats. METI industrial standards support diagnostic reagent export competitiveness. The Kansai region's biomedical manufacturing base supplies antibody raw materials to regional kit assemblers.
E.Coli Latex Agglutination Test Kits Market Competitive Landscape
Integrated multinational conglomerates and specialized microbiology suppliers split the market between scale-driven procurement contracts and technical service relationships. Thermo Fisher Scientific leverages diagnostic reagent manufacturing scale to sustain long-term supply agreements with hospital networks. bioMérieux SA anchors its position through specialized testing portfolios dominating reference laboratory channels. Hardy Diagnostics occupies regional hospital markets with customized configurations. Competitive moves concentrate on group purchasing organization contract consolidation and lateral flow assay format development for point-of-care penetration.
Among United States-based conglomerates, Thermo Fisher Scientific exemplifies the scale-driven archetype through manufacturing breadth and integrated delivery network relationships. bioMérieux SA, a French-listed specialist, represents the microbiology-focused tier with concentrated expertise in reference laboratory channels. Hardy Diagnostics occupies the regional service-intensive segment with responsive technical support capabilities. Atlas Medical GmbH, a German GmbH-structured entity, sits within the European specialist tier serving tender-based procurement markets. These archetypes reflect how geographic origin and organizational structure shape competitive positioning rather than product-specific differentiation.
| Leading Market Players |
|---|
| Atlas Medical GmbH |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Bio-Rad Laboratories, Inc. |
| Cardinal Health |
| Eurofins Scientific |
| Hardy Diagnostics |
| Creative Diagnostics |
| Liofilchem |
| Others |
Pricing and Supply Chain Analysis
The Kansai region's biomedical manufacturing cluster anchors antibody raw material output for latex particle coating, concentrating upstream capacity that feeds pricing power to specialized bioreactor operators serving kit manufacturers. This geographic concentration creates asymmetric leverage where batch-to-batch variability in polyclonal antibody supply translates directly into reagent lot premiums for certified diagnostic-grade materials.
Pricing Analysis
Configured-to-order pricing for customized kit formats commands 15-25% premiums over standard direct agglutination configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and documented traceability depth. Cost compression in the standard tier intensifies because hospital procurement consortia negotiate multi-year volume commitments that squeeze standalone regional distributors. Diagnostic centers demonstrate least price sensitivity due to CLIA complexity compliance requirements, while urgent care clinics purchasing lateral flow assays through online retail channels exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing for latex particle synthesis concentrates among specialized bioreactor operators in the United States, Germany, and Japan. Kit assembly draws from antibody raw materials, nitrocellulose membranes for lateral flow substrates, and stabilized latex suspensions. Single-source vulnerability in polyclonal antibody production exposes manufacturers to extended lead times when bioreactor contamination events occur. Distribution runs through medical supply distributors maintaining regional inventory positions for hospital laboratory networks, with direct sales channels serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
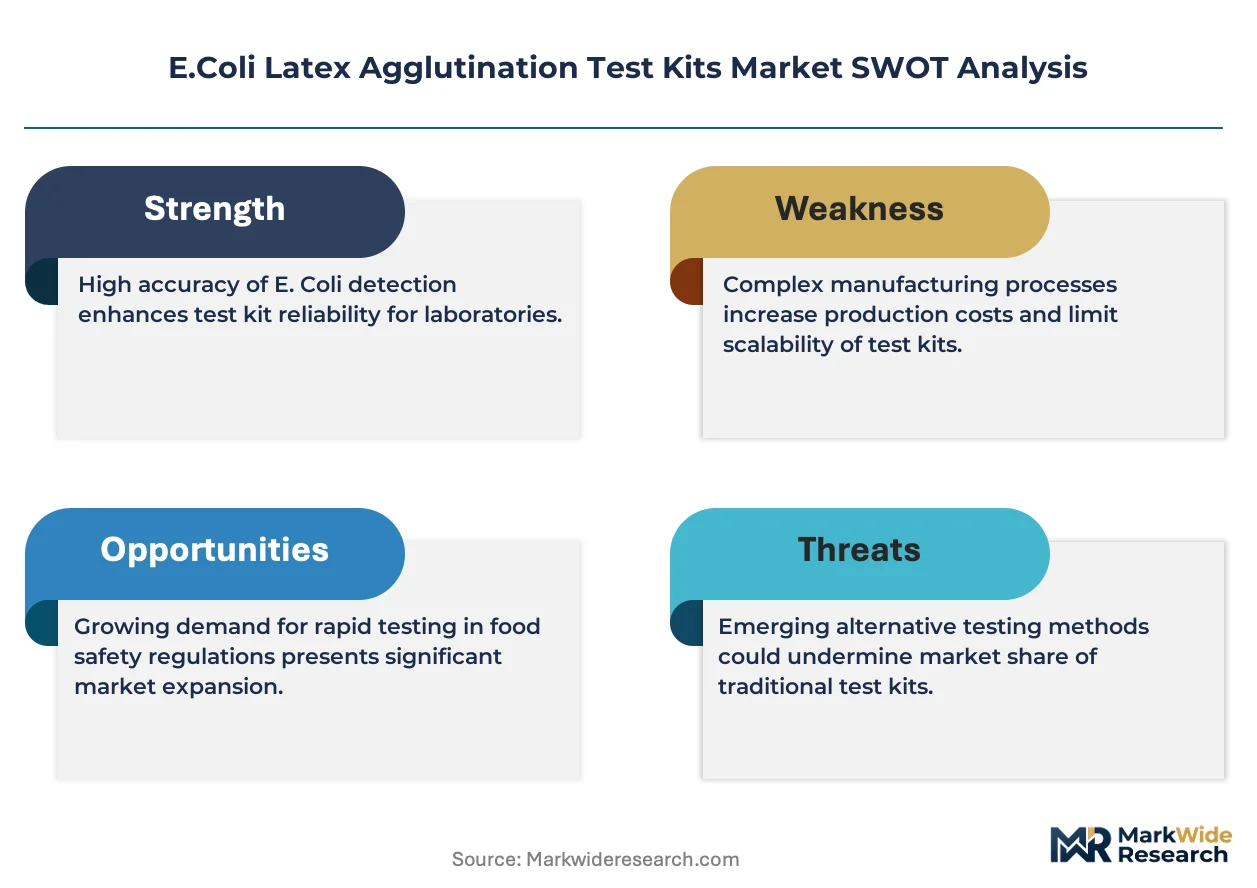
E.Coli latex agglutination test kits sit in early-cycle expansion as point-of-care workflow integration accelerates lateral flow adoption beyond traditional hospital laboratory boundaries. FDA Food Safety Modernization Act enforcement creates durable replenishment demand that insulates suppliers from cyclical testing volume volatility.
For Market Incumbents: Harden group purchasing organization contract positions by embedding E.coli kits within broader microbiology consumables bundles that raise switching costs for integrated delivery networks. Deepen backward integration into antibody raw material production to insulate against bioreactor operator concentration risk. Prioritize lateral flow assay format development to capture urgent care clinic volume before regional distributors establish supplier relationships. For New Entrants and Emerging Players: Latin American veterinary diagnostic markets offer underpenetrated white space where pathogen detection protocols mirror human clinical requirements but face less entrenched supplier relationships. Target livestock health screening applications with species-specific antibody configurations absent from incumbent portfolios. Pursue regulatory fast-track pathways through ANVISA in Brazil or COFEPRIS in Mexico to establish beachhead positions ahead of multinational scale entrants. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because FDA and EPA enforcement intensity creates recurring revenue visibility that transcends discretionary diagnostic spending cycles. Acquisition targets should display specialized microbiology testing portfolios with reference laboratory channel dominance or proprietary latex particle engineering capabilities. Monitor CLIA complexity classification proceedings as inflection indicators that would reclassify direct agglutination formats and alter laboratory personnel requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerates commercialization timelines for novel lateral flow assay formats targeting point-of-care settings. |
| ISO 13485 Quality System Certification | Validates manufacturing processes for FDA premarket submission and EU MDR technical documentation. |
| Hospital System Partnership Agreement | Secures multi-year supply commitments with integrated delivery networks controlling fifty-plus laboratories. |
| Software Companion Development | Enables digital result interpretation and laboratory information system integration for automated documentation. |
| Reimbursement Strategy Formulation | Aligns test pricing with CMS Medicare coverage determinations and commercial payer laboratory fee schedules. |
Research Methodology
Cross-validation between primary interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, EPA recreational water quality criteria documentation, hospital procurement contract filings, and ISO 13485 certification registries. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to ensure internal consistency across volume and value outputs.
Calibration against historical adoption curves for comparable rapid diagnostic formats ensures projection realism across the modeling period. The analytical framework segments by product type, application, end user, and distribution channel, with additional disaggregation by CLIA complexity classification and regulatory compliance tier. CAGRs derive from fitted growth curves incorporating penetration rates for lateral flow assays in point-of-care settings and EPA-mandated testing frequency for recreational water monitoring.
The forecast holds incumbent behavior within observed patterns; aggressive moves by molecular PCR platform developers or consolidated diagnostic conglomerates would shift outcomes beyond modeled ranges. Quarterly review of FDA warning letter issuance patterns, CLIA complexity reclassification proceedings, and group purchasing organization contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market