
 Industrial Wax Market | 2026-2036
Industrial Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wax Market Intelligence
The distinction between food-grade and technical-grade paraffin wax is collapsing as safety standards converge across end-use sectors. Sinopec Corporation leverages its vast refining capacity to supply commodity grades at scale. Exxon Mobil Corporation competes with specialized polymer-modified waxes for industrial applications. Sasol Limited differentiates through its proprietary gas-to-liquids technology, producing high-purity synthetic waxes.
Industrial wax is a class of organic, plastic-like substances, typically hydrocarbon-based, solid at ambient temperatures. These materials are characterized by specific melting points and viscosity, providing properties like water resistance, lubrication, and gloss. Paraffin wax remains the largest product type by volume due to its availability from petroleum refining. The packaging coatings application is seeing significant expansion, while the cosmetics end-user segment commands premium pricing for highly purified waxes.
Regulatory frameworks from the US FDA for food-contact materials and the EU's ECHA under REACH dictate purity and composition standards. In China, national GB standards enforce quality requirements for both imported and domestically produced waxes. These regulations directly influence market access and product formulation. Sourcing decisions between petroleum-derived, synthetic, and emerging bio-based waxes will determine long-term competitive advantage.
Market Dynamics
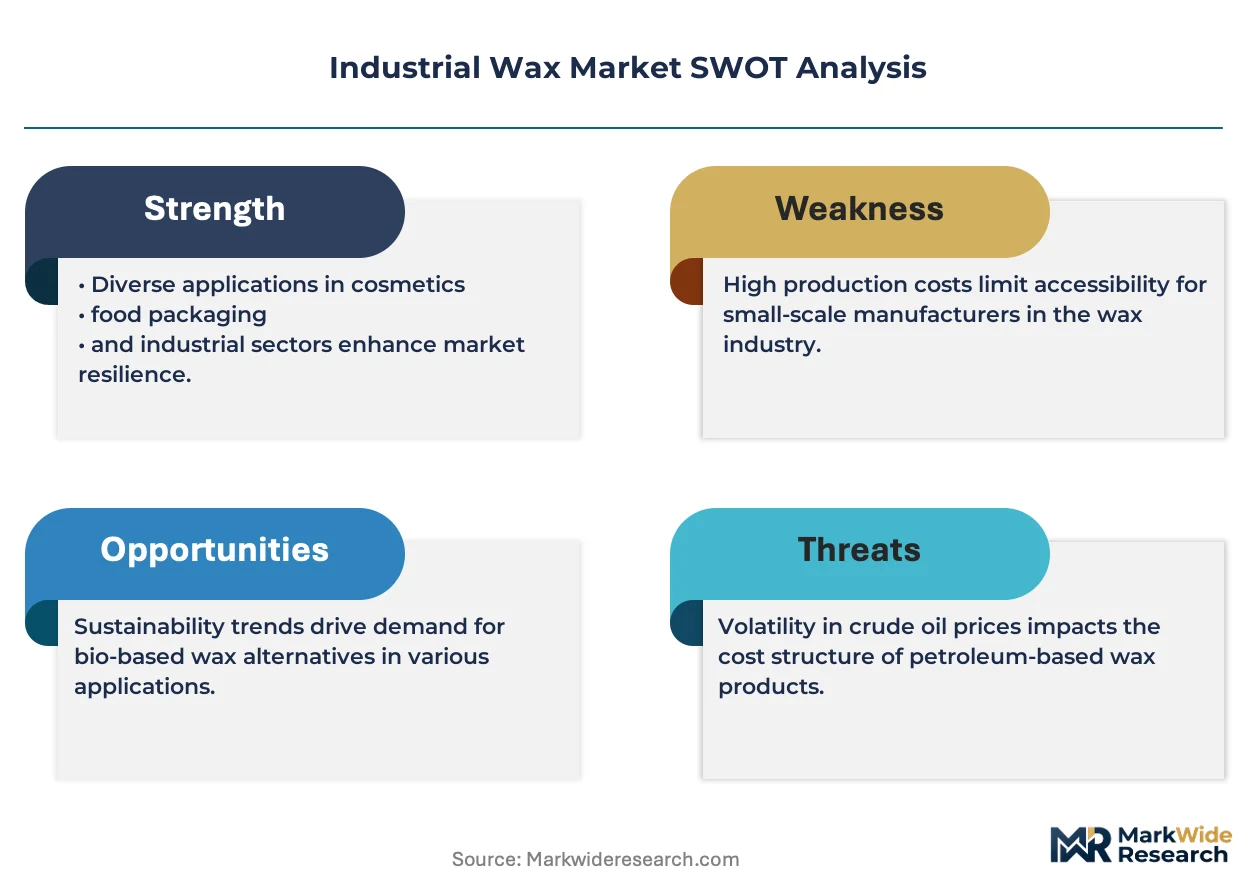
The industrial wax market is shaped by a fundamental tension between the scale of commodity petroleum-derived grades and the performance specifications of high-purity synthetic and bio-based alternatives, a divergence accelerated by global regulatory pressures on material safety.
Growth Catalysts
- Packaging Demand:Expansion in the food and beverage industry drives requirements for paraffin wax coatings on paper and board, where they provide essential moisture and grease resistance for flexible packaging and corrugated boxes.
- Chinese Manufacturing:China's large-scale candle manufacturing industry, combined with its expansive packaging sector, concentrates a significant volume of global demand for commodity-grade paraffin and microcrystalline waxes.
- Regulatory Convergence:The tightening of purity standards under frameworks like the EU's REACH is pushing technical-grade applications toward using food-grade waxes, simplifying supply chains and expanding the market for higher-margin products.
Market Restraints
- Input Cost Volatility:The price of petroleum-derived waxes, the market's largest segment, is directly linked to crude oil price fluctuations, creating margin pressure and sourcing instability for producers and end-users.
- Threat of Substitution:In high-performance applications, polymer-based coatings and hot-melt adhesives can offer superior durability and adhesion, presenting a significant substitution threat to traditional wax formulations.
- Regulatory Compliance Burden:Navigating disparate regulatory requirements, such as the US FDA's food-contact rules and China's GB standards, increases testing costs and time-to-market for manufacturers operating globally.
Strategic Opportunities
- Bio-Based Waxes:Growing consumer and regulatory preference for sustainability creates a significant opportunity for waxes derived from renewable sources like soy, palm, and rapeseed, particularly in cosmetics and food packaging.
- Phase Change Materials:The unique thermal properties of certain waxes present an opportunity in advanced applications like thermal management for electronics, energy storage systems, and smart textiles.
- Geographic Expansion:Rising industrialization and consumer goods manufacturing in Southeast Asia and Latin America create underpenetrated markets for specialized waxes in packaging, tires, and personal care products.
Industry Challenges
- Supply Chain Reconfiguration:Shifting from established petroleum refining supply chains to more fragmented and nascent bio-based or synthetic wax sources presents significant logistical and sourcing challenges for manufacturers.
- Certification Timelines:The lengthy and costly process of obtaining and maintaining food-contact and cosmetic-grade certifications from bodies like the FDA or under EU regulations can delay product launches and limit market access.
- Capital Investment:The construction of new gas-to-liquids (GTL) facilities for synthetic wax production or biorefineries for bio-based waxes requires substantial upfront capital expenditure, posing a barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wax Market |
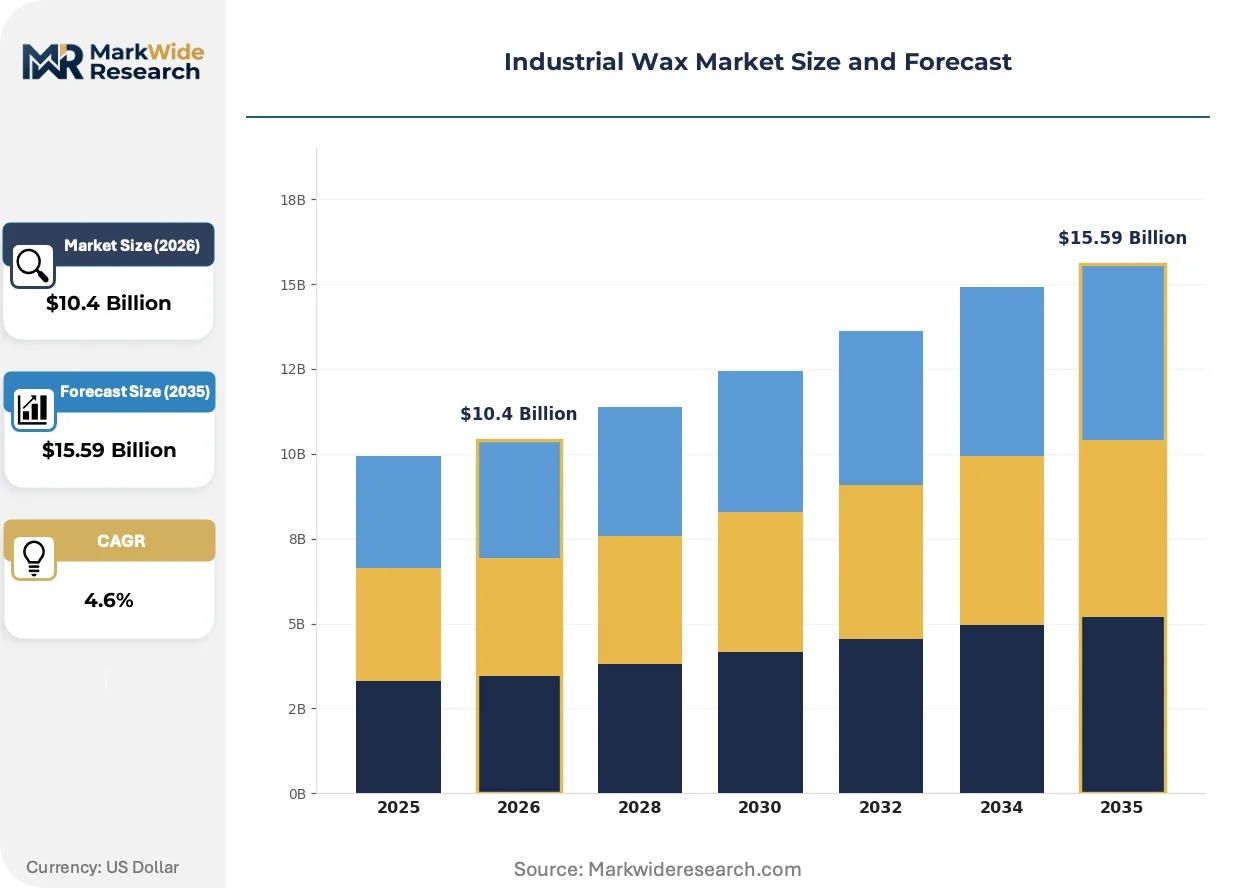
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $15.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Synthetic Wax, Beeswax, Ceresin Wax Application: Candles, Polishes, Adhesives, Lubricants, Packaging Coatings End User Industry: Cosmetics, Paper & Board, Food Processing, Pharmaceuticals, Electrical Form: Flake, Block, Powder, Liquid, Granular |
| Companies Covered | Numaligarh Refinery Limited, Sinopec Corporation, Exxon Mobil Corporation, The International Group, Inc., HollyFrontier Corporation, Shell plc, Petrobras, HCI Wax Co., Ltd., Sasol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wax Market Strategic Shifts & Innovations
The market's evolution is defined by a re-evaluation of wax based on its origin and purity. This shift moves purchasing criteria beyond simple cost-per-ton metrics to include lifecycle and performance considerations driven by regulatory and consumer demands.
Synthetic waxes, particularly those produced via Fischer-Tropsch (FT) synthesis, provide exceptionally high purity and precisely controlled melt points. End-users in sensitive sectors like cosmetics, pharmaceuticals, and polymer processing are adopting these materials for their consistent performance. The availability of these highly-engineered waxes is fragmenting the traditional, monolithic market that was once dominated by standard petroleum-based paraffin grades.
The European Union's REACH regulation mandates the registration, evaluation, and authorization of chemical substances, directly impacting hydrocarbon waxes. This forces producers and importers to conduct detailed risk assessments of their products' chemical composition, identifying and managing any substances of very high concern. This regulatory scrutiny most affects global suppliers exporting to the EU, who must invest heavily in chemical analysis and potential reformulation to ensure compliance.
A clear behavioral shift is visible as end-users in consumer-facing industries prioritize waxes from sustainable and renewable sources. This change disrupts the historical dominance of petroleum-derived paraffin, creating new demand for bio-based alternatives sourced from soy, palm, or carnauba. This preference for sustainable procurement is most advanced in European and North American markets, where brand owners respond to both consumer pressure and corporate sustainability goals.
Industrial Wax Market Segmentation
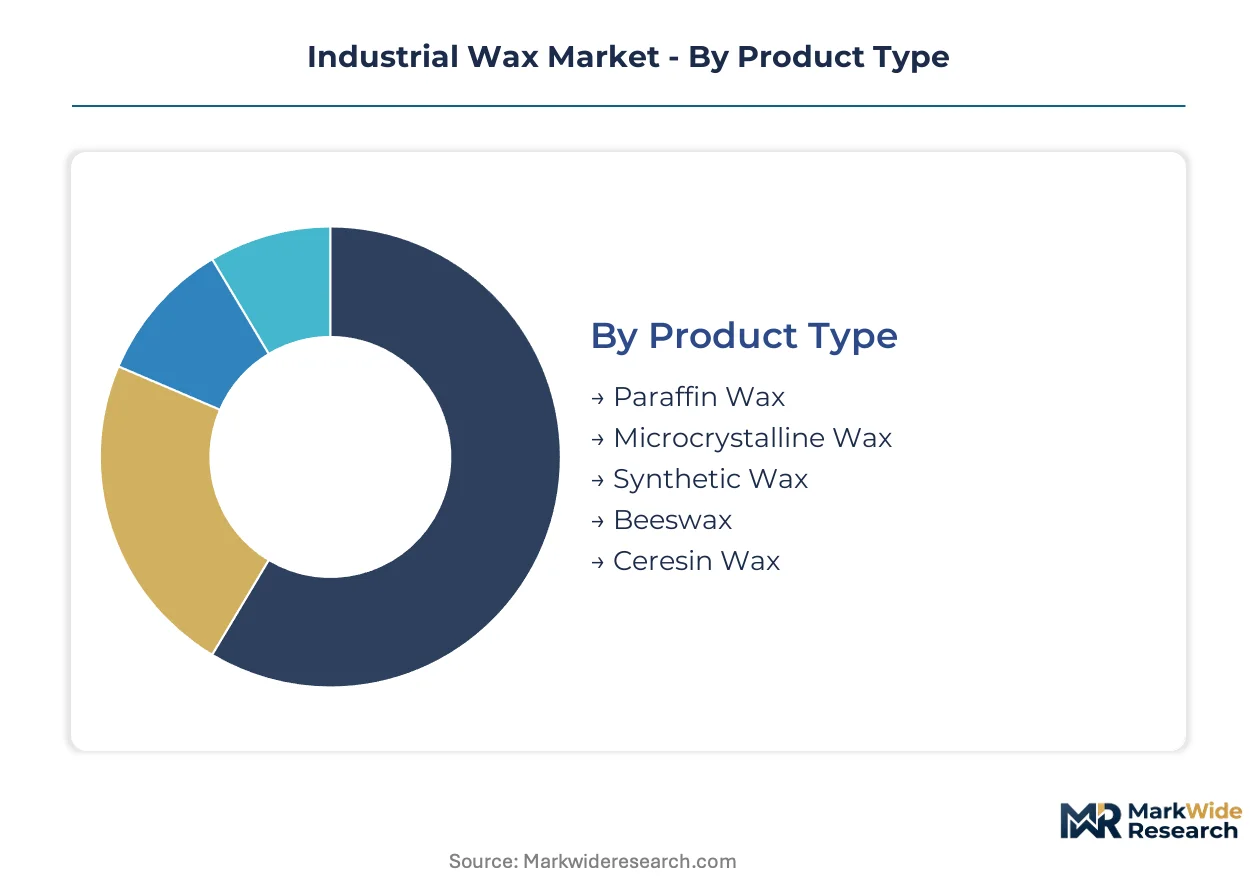
Segmentation analysis provides a critical framework for understanding the diverse applications and end-user requirements shaping the industrial wax market. Differentiating product types, forms, and industry-specific uses reveals distinct value chains. This granular view informs strategic decision-making across the supply landscape.
Product Type:
The industrial wax market's product types demonstrate varied channel requirements, from high-volume commodity distribution to specialized supply chains for high-purity grades.
- Paraffin Wax:This petroleum-derived wax consists primarily of saturated hydrocarbons, offering good moisture barrier properties and lubrication. Global demand concentrates in China's expansive candle and packaging manufacturing sectors due to its cost-effectiveness.
- Synthetic Wax:Produced via Fischer-Tropsch synthesis, these waxes offer exceptional purity and precisely controlled melting points. End-users in sensitive sectors like cosmetics and pharmaceuticals adopt these materials for consistent performance.
- Microcrystalline Wax:Derived from petroleum, this wax features smaller, more irregular crystals, providing excellent flexibility and adhesion for laminating and hot-melt applications.
- Beeswax:A natural wax produced by honeybees, beeswax finds application in cosmetics, pharmaceuticals, and candle production for its natural properties and pleasant aroma.
- Ceresin Wax:This mineral wax, often blended with other waxes, enhances hardness and melting point in polishes, cosmetics, and protective coatings.
Paraffin Wax dominates the installed base for commodity applications. Synthetic Wax is where expansion concentrates due to performance requirements.
Application:
The market's application segments show distinct performance criteria, influencing material selection and processing methods for industrial wax consumers.
- Packaging Coatings:These waxes provide essential moisture and grease resistance for paper and board, crucial for flexible packaging and corrugated boxes. Expansion in the food and beverage industry drives requirements for these coatings.
- Candles:Waxes serve as the primary fuel and structural component for candles, offering controlled burn rates and fragrance retention. China's large-scale manufacturing industry concentrates significant global demand for this application.
- Polishes:Waxes impart gloss, protection, and water repellency to surfaces in automotive, furniture, and floor care products.
- Adhesives:Waxes modify the viscosity and open time of hot-melt adhesives, improving bond strength and flexibility in various assembly processes.
- Lubricants:Waxes reduce friction and wear in industrial machinery, offering a solid or semi-solid lubricating film in high-pressure environments.
Packaging Coatings represents the fastest-growing trajectory, driven by consumer goods. Candles maintain a substantial volume base, particularly in Asian markets.
End User Industry:
End-user industries exhibit varied purity standards and regulatory compliance needs, directly influencing the type and grade of industrial wax procured.
- Cosmetics:This sector demands highly purified waxes for formulations like lipsticks, creams, and lotions, often commanding premium pricing due to strict safety standards. Regulatory frameworks like REACH influence material selection.
- Paper & Board:This industry utilizes waxes extensively for packaging coatings, enhancing moisture resistance and printability of paper and corrugated materials. Demand for food packaging drives material specifications.
- Food Processing:Waxes serve as protective coatings for fruits, vegetables, and cheeses, extending shelf life and improving appearance, subject to US FDA and EU EFSA regulations.
- Pharmaceuticals:High-purity waxes act as binders, excipients, and controlled-release agents in drug formulations and medical device coatings.
- Electrical:Waxes provide insulation and potting compounds for electronic components, protecting against moisture and vibration in various devices.
The Paper & Board sector constitutes a significant consumption base. Cosmetics is gaining share fastest due to premium product formulations.
Form:
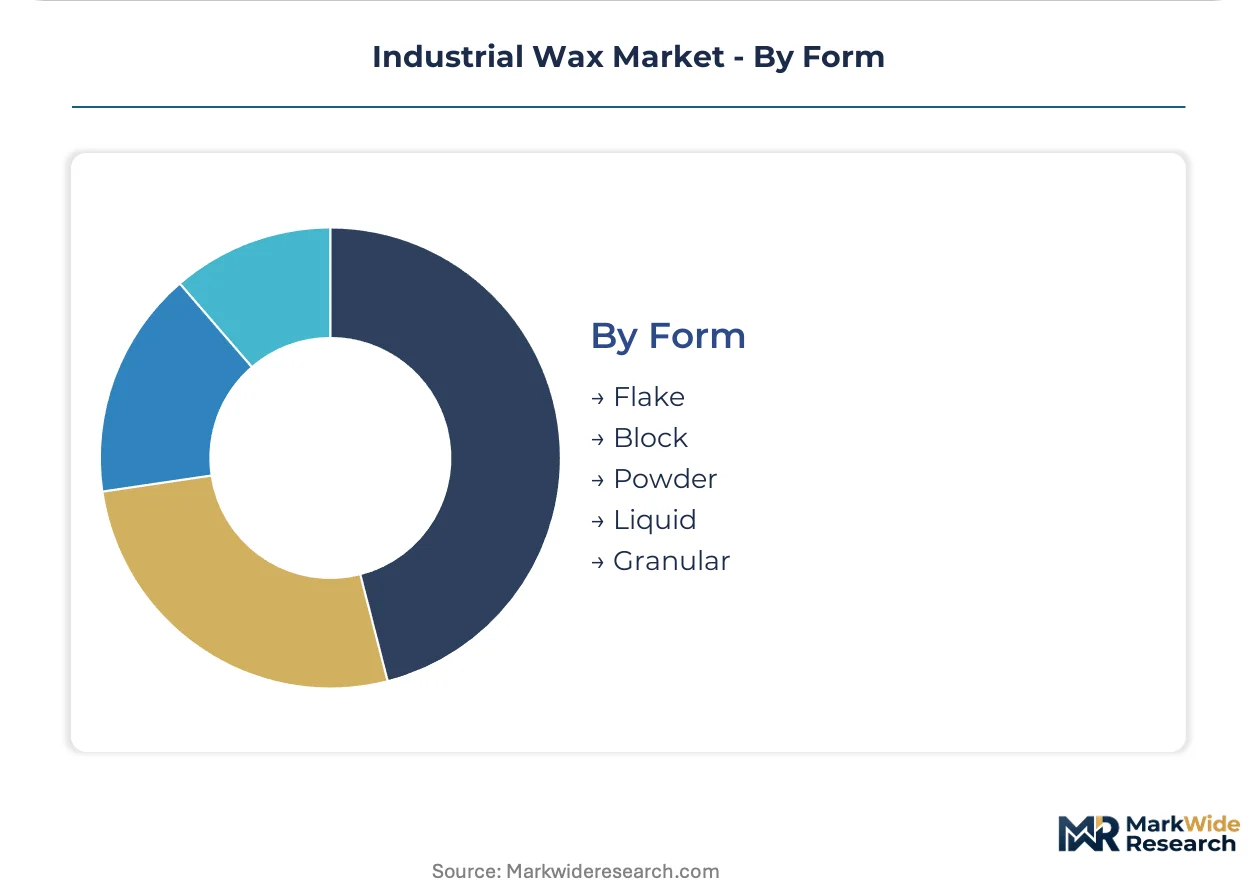
The physical form of industrial wax dictates handling, storage, and processing efficiency for end-users, affecting logistics and integration into manufacturing lines.
- Flake:This form offers ease of handling, melting, and blending, making it suitable for various industrial applications requiring precise dosing. It is widely used in packaging and candle manufacturing.
- Liquid:Waxes supplied in liquid form allow for continuous processing and direct integration into hot-melt systems, reducing pre-melting steps for high-volume operations. This form is common in adhesive and coating applications.
- Block:Large blocks of wax are suitable for bulk storage and melting, often preferred by large-scale manufacturers with dedicated melting equipment.
- Powder:This finely ground form facilitates uniform dispersion in polymer blends and dry-mix formulations, enhancing material properties.
- Granular:Granular waxes provide good flow characteristics for automated feeding systems, optimizing efficiency in compounding and molding processes.
Flake form remains a prevalent choice for its versatility. Liquid form is seeing the steepest expansion trajectory for integrated production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Industrial Wax Market exhibits a complex export-import balance, with major producing nations supplying commodity grades while others focus on high-purity imports. Regulatory frameworks and local industrial demands significantly shape regional consumption patterns. This dynamic influences trade flows and product specifications across diverse geographies.
China
China's vast candle manufacturing industry and expansive packaging sector drive significant demand for commodity-grade paraffin and microcrystalline waxes. National GB standards enforce stringent quality requirements for both domestic and imported products. The Yangtze River Delta region concentrates a large volume of this manufacturing, serving both domestic and export markets. This concentration supports large-scale wax distribution networks.
United States
The United States market sees strong demand from food packaging and personal care applications. The US FDA's regulations for food-contact materials dictate purity and composition standards for waxes. Petrochemical hubs along the Gulf Coast are central to petroleum-derived wax production, supplying various industrial users. This area supports extensive refining capacity.
Germany
Germany's industrial wax demand stems from its advanced automotive sector and specialized industrial applications. The EU's ECHA under REACH framework significantly influences material selection and product formulation for imported waxes. The Rhine-Ruhr region, a major chemical industry cluster, hosts both producers and advanced end-users of synthetic waxes. This area prioritizes high-purity grades.
India
India's expanding packaging industry and growing candle manufacturing sector create substantial demand for industrial waxes. The Bureau of Indian Standards (BIS) sets quality benchmarks for various wax products across the country. Gujarat, with its robust chemical and industrial production base, is a key consumption and distribution hub for waxes. This region supports local and international suppliers.
Brazil
Brazil's industrial wax market is driven by its large consumer goods packaging sector and agricultural applications. ANVISA regulations govern the use of waxes in food contact materials and cosmetics, influencing product specifications. São Paulo state, a major industrial manufacturing center, sees significant consumption of waxes for various end-uses. This area attracts both local and international suppliers.
Industrial Wax Market Key Industry Players
Listed leaders compete with private specialists across the industrial wax market, influencing both commodity pricing and specialized product development. The market structure is tiered, featuring large, vertically integrated petrochemical companies alongside specialized manufacturers focusing on high-purity or bio-based alternatives. Strategic archetypes include integrated refiners, synthetic wax innovators, and emerging bio-based wax producers. Major competitive moves involve capacity expansion for commodity grades and strategic partnerships for niche applications.
At the scale-driven end, Sinopec Corporation, a Chinese state-owned enterprise, represents a major integrated refiner leveraging vast refining capacity for commodity wax supply. Exxon Mobil Corporation, a global energy and petrochemical company, occupies a position among players offering specialized polymer-modified waxes for industrial applications. Sasol Limited, a South African chemical and energy company, exemplifies innovation through its proprietary gas-to-liquids technology, producing high-purity synthetic waxes. These companies anchor different segments of the market, from high-volume commodity grades to performance-driven specialty products, influencing global supply dynamics. Their distinct operational models cater to diverse purity and volume requirements across various end-use sectors.
| Leading Market Players |
|---|
| Numaligarh Refinery Limited |
| Sinopec Corporation |
| Exxon Mobil Corporation |
| The International Group, Inc. |
| HollyFrontier Corporation |
| Shell plc |
| Petrobras |
| HCI Wax Co., Ltd. |
| Sasol Limited |
| Others |
Cost & Logistics Intelligence
Vast scale economies in petroleum refining underpin the industrial wax market, concentrating supply among a few large players. This structural advantage allows major refiners to influence price floors for commodity-grade paraffin waxes.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing model combining commodity spot rates for bulk paraffin with contract-based long-term offtake for specialized grades. Price differentiation stems from purity grade, such as US FDA food-contact approval, and the volume scale of procurement. Input cost volatility, particularly from crude oil price fluctuations, creates margin pressure for producers of petroleum-derived waxes. Commodity-focused candle manufacturers exhibit high price sensitivity, while pharmaceutical and cosmetic formulators prioritize performance and purity over cost.
Supply Chain Analysis
Rising inbound logistics costs, particularly for container shipping on trans-Pacific routes, impact the landed cost of industrial waxes. Global supply concentrates in China, driven by Sinopec's vast refining capacity, the United States, with major producers like Exxon Mobil, and South Africa, home to Sasol's synthetic wax production. The market draws heavily from crude oil and natural gas as primary feedstocks, making commodity price volatility a significant structural risk. Distribution runs through a network of large-scale chemical distributors and direct sales channels for specialized, high-purity waxes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial wax market is experiencing a significant shift in buyer power, driven by the consolidation of large-scale packaging and cosmetic formulators. These key buyers increasingly dictate material specifications and sustainability criteria, influencing market direction.
For Market Incumbents:Secure long-term offtake agreements with major packaging and candle manufacturers to stabilize commodity volume. Expand capacity in cost-advantaged regions for paraffin wax to counter input cost volatility. Invest in advanced certification for high-purity synthetic waxes, mitigating the threat of substitution from polymer-based coatings. Deepen R&D into bio-based wax alternatives to meet evolving sustainability demands from key end-users.
For New Entrants and Emerging Players:Lead with innovative bio-based wax formulations, particularly those derived from soy or palm, targeting the cosmetics end-user segment in European markets. Penetrate niche applications like phase change materials for thermal management in electronics, where performance specifications outweigh volume. Emphasize sustainability credentials and superior purity as a distinct go-to-market angle. Develop strategic partnerships with specialized formulators to accelerate product adoption in high-value sectors.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized synthetic wax producers with proprietary gas-to-liquids technology and robust certification portfolios. Long-term viability favors companies focused on high-purity, performance-driven solutions over commodity volume. Target acquisition archetypes include bio-based wax innovators with established supply chains for renewable feedstocks. The signal to watch is increasing regulatory mandates for bio-content in food packaging, indicating a shift in material preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Commodity Grades | This move stabilizes supply for China's expansive candle and packaging sectors, maintaining market share for large refiners. |
| Backward Integration into Natural Gas Feedstocks | Securing feedstock for gas-to-liquids (GTL) synthesis ensures cost stability and purity for synthetic wax producers. |
| Investment in Bio-based Wax Production | Developing renewable waxes from soy or palm addresses consumer and regulatory preference for sustainability in cosmetics. |
| Long-term Supply Agreements with Packaging OEMs | These agreements provide revenue predictability and market access for wax suppliers serving the food and beverage industry. |
| Joint Venture for Phase Change Material R&D | Collaborations accelerate innovation in advanced thermal management applications, expanding wax utility beyond traditional uses. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary research. Primary engagement involved plant managers, procurement leads at packaging OEMs, R&D directors for specialty chemicals, and regulatory affairs specialists. This was triangulated with secondary sources including customs/trade data, SEC 10-K filings, EU ECHA publications, and US FDA guidance documents. A bottom-up modeling approach was validated through top-down market sizing for accuracy.
Over the projection horizon, the analytical framework modeled market dynamics across product type, application, end-user industry, form, and regional production hubs. Compound annual growth rates were derived from historical trends and projected market shifts. Key industry-specific forecast inputs included crude oil price forecasts and packaging industry expansion rates. This multi-dimensional approach provided granular insights into market trajectories.
Forecasts assume regulatory continuity in EU REACH, US FDA, and China GB standards; material policy shifts would require re-modeling. Geopolitical disruptions affecting crude oil supply or significant advancements in substitute materials represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Paint Knife Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Cork Material Market
Industrial Materials
Injection Molding Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Tension Spring Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Global Cast Acrylic Sheet Market