
 North America Phenolic Insulation Market | 2026-2036
North America Phenolic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Phenolic Insulation Market Insights
Class A fire-performance specifications are reorganizing procurement priorities across commercial construction. Owens Corning leverages its mineral wool-phenolic hybrid systems to capture premium specification work. Kingspan Group anchors its position through controlled distribution of closed-cell phenolic boards for cold-chain infrastructure. Johns Manville Inc. specializes in laminated facing technologies that extend product durability in high-moisture HVAC applications.
North America phenolic insulation comprises thermoset polymer foam manufactured from phenol-formaldehyde resin with closed-cell structures achieving thermal conductivity values near 0.020 W/m·K, primarily deployed where fire resistance and low smoke emission outweigh polyurethane alternatives. Rigid foam dominates value capture due to entrenched specification in commercial roofing and wall assemblies. HVAC application demand is accelerating fastest as heat-pump retrofits require thinner insulation profiles in constrained mechanical rooms. Fire protection grade phenolic systems command margin premiums where NFPA 285 compliance mandates non-combustible core materials.
The EPA enforces AIM Act hydrofluorocarbon phase-down schedules that constrain blowing agent choices for domestic manufacturers. OSHA respiratory protection standards govern formaldehyde exposure limits during panel fabrication and jobsite cutting operations. State-level stretch codes in California and Massachusetts advance net-zero building mandates that favor phenolic's thermal efficiency in envelope designs. Stakeholders must track evolving EPA Significant New Alternatives Policy determinations for next-generation blowing agents to secure long-term formulation compliance.
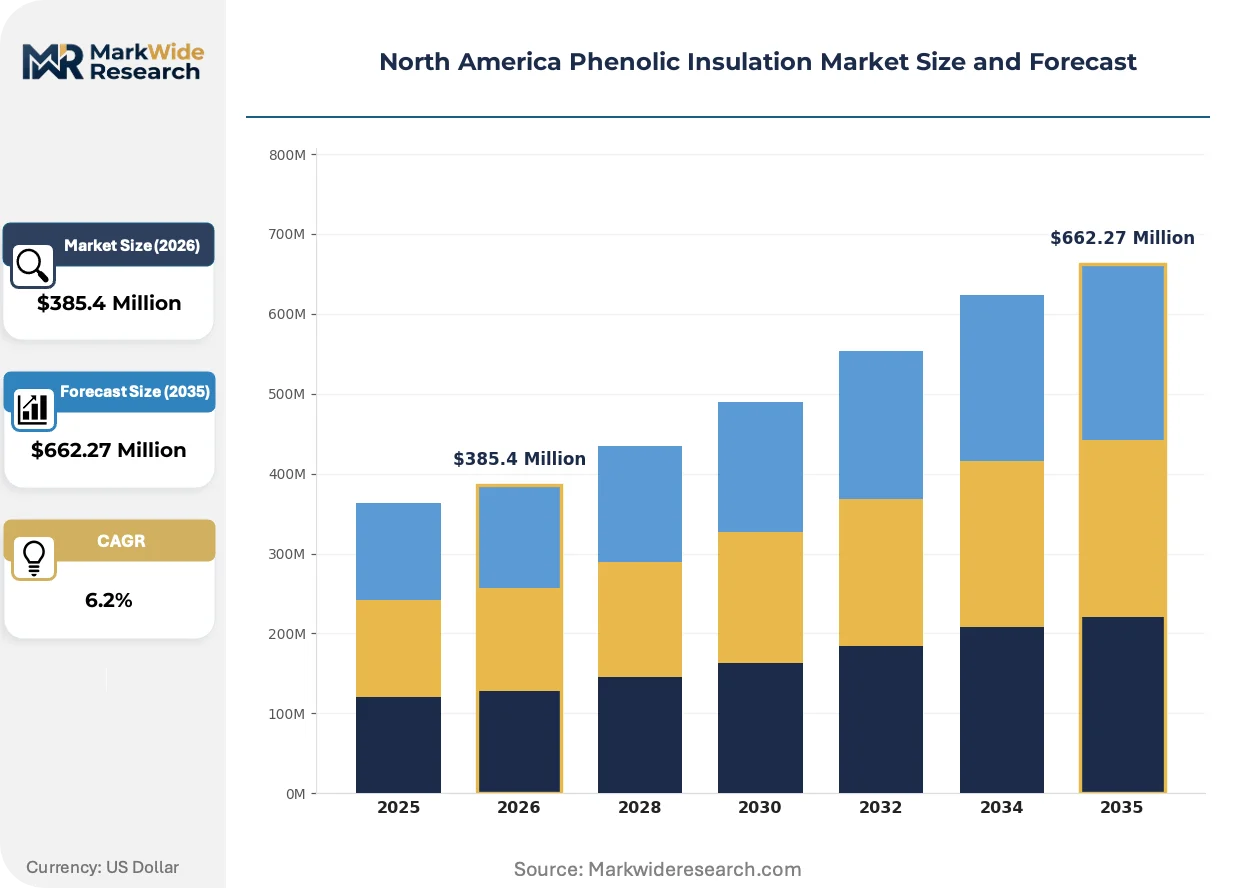
Market Dynamics
The EPA's phasedown of hydrofluorocarbon blowing agents under the AIM Act is forcing North American phenolic insulation manufacturers to reformulate entire product lines around lower-GWP alternatives, restructuring supply chains and procurement specifications simultaneously.
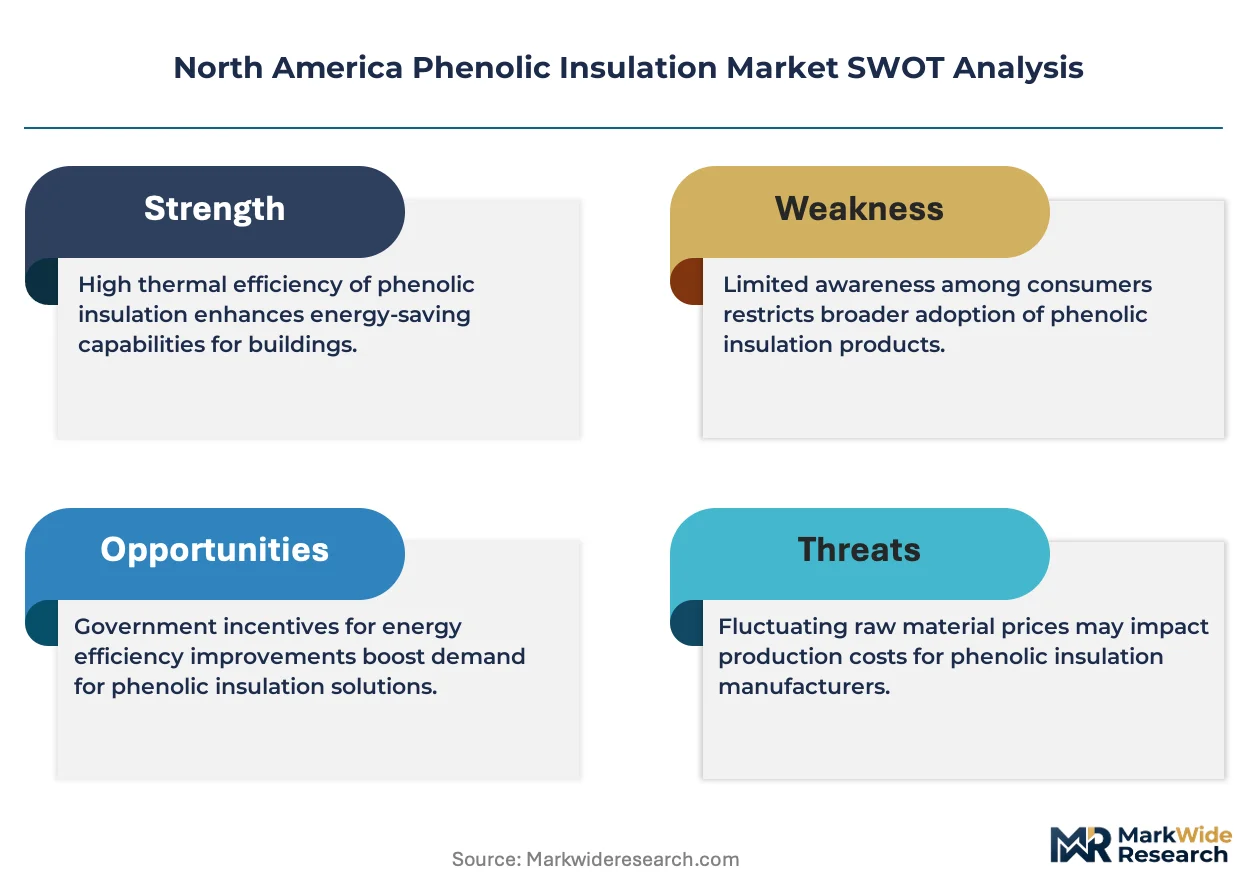
Growth Catalysts
- Cold-storage warehouse construction:United States distribution networks for frozen food and pharmaceuticals require phenolic's thermal efficiency in sub-zero environments where polyurethane alternatives fail fire codes.
- California Title 24:The state's building energy efficiency standards mandate thermal performance thresholds that phenolic foam achieves with thinner profiles than competing materials.
- Heat-pump retrofits:HVAC contractors in constrained mechanical rooms specify phenolic boards to meet R-value requirements within existing spatial envelopes.
Market Restraints
- Formaldehyde input volatility:Petrochemical feedstock fluctuations directly compress margins for resin producers concentrated along the US Gulf Coast.
- Single-source blowing agent dependency:Limited domestic suppliers of HFO-1234ze and cyclopentane create supply concentration risk for independent foam fabricators.
- Polyurethane substitution in residential:Lower-cost spray foam systems capture single-family construction where fire codes permit combustible materials.
Strategic Opportunities
- Massachusetts net-zero mandates:Stretch building codes in Boston and Cambridge create specification pull for high-performance envelope materials in commercial retrofits.
- Data center thermal management:Hyperscale facilities in Northern Virginia and Dallas-Fort Worth require phenolic's low-smoke properties for mission-critical insulation.
- Direct-to-contractor digital channels:Kingspan and Owens Corning are piloting specification tools that bypass traditional distributor markups in mid-market commercial projects.
Industry Challenges
- NFPA 285 certification timelines:Wall assembly testing protocols delay product launches by 18-24 months as laboratories face capacity constraints.
- Resin chemistry expertise scarcity:Formulation chemists with phenol-formaldehyde process knowledge are retiring faster than universities replenish talent pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Phenolic Insulation Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Flexible Foam, Coatings, Adhesives End User: Construction, HVAC, Industrial, Refrigeration Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Pipe Insulation Installation: New Construction, Retrofit, Residential, Commercial |
| Companies Covered | Saint-Gobain, Soprema Group, Kingspan Group, Rockwool International, Knauf Insulation, Owens Corning, Asahi Kasei Corporation, BASF SE, Johns Manville Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Phenolic Insulation Market Trends and Innovations
Formulation chemistry and specification workflows are undergoing parallel transformation as manufacturers navigate blowing agent transitions while digital tools reshape how architects and contractors select insulation systems.
Water-blown phenolic formulations are decomposing the traditional HFC-dependent manufacturing base. Owens Corning and Johns Manville have accelerated pilot production of aqueous-based systems that eliminate fluorinated blowing agents entirely. Cold-storage contractors in the Midwest are specifying these platforms for new warehouse construction, compressing the addressable market for legacy HFC-based products within three specification cycles.
The EPA's Significant New Alternatives Policy determinations are reshaping permissible formulation pathways. Each SNAP rule update immediately constrains which blowing agents domestic manufacturers may deploy, forcing simultaneous R&D investment across multiple chemical platforms. State environmental agencies in California and New York are layering additional notification requirements atop federal schedules, extending compliance timelines for smaller regional foam fabricators.
Building information modeling integration is altering specification authority. Architects in Texas and Florida now embed thermal performance data directly into digital construction documents, bypassing traditional distributor consultative selling. Mechanical contractors are accessing manufacturer-curated specification libraries through tablet-based field tools, collapsing the information asymmetry that previously favored established supplier relationships in commercial roofing and envelope assemblies.
North America Phenolic Insulation Market Segmentation
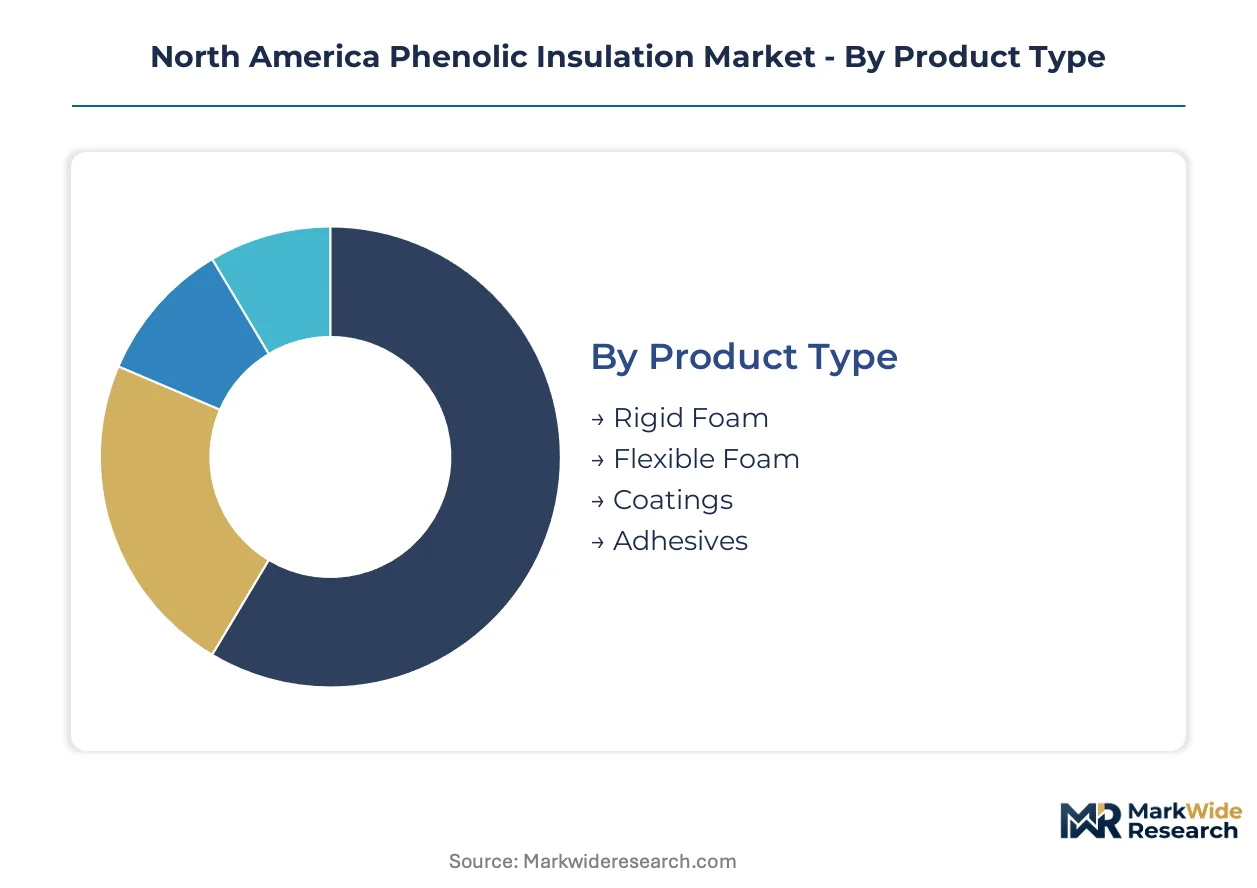
Phenolic insulation procurement channels diverge sharply across product forms and end-use specifications. Distributors, direct contractor sales, and specification-driven architectural channels each favor distinct segment combinations based on project scale and code complexity.
Product Type:
Rigid foam boards flow primarily through distributor networks serving commercial roofing contractors, while flexible foams and coatings reach end-users through specialized HVAC supply houses and direct manufacturer relationships.
- Rigid Foam:Closed-cell phenol-formaldehyde boards achieve thermal conductivity near 0.020 W/m·K. Demand clusters in US Gulf Coast petrochemical corridor retrofits where NFPA 285 fire compliance mandates non-combustible cores over polyurethane alternatives.
- Flexible Foam:Lower-density formulations adapt to irregular surfaces in mechanical rooms. Heat-pump retrofits across Massachusetts and California specify these profiles where spatial constraints prevent rigid board installation.
- Coatings:Spray-applied intumescent systems protect structural steel in high-rise construction. Application requires certified contractor networks concentrated in Chicago and Toronto metropolitan areas.
- Adhesives:Phenolic resin binders laminate facing materials to foam cores. Owens Corning and Johns Manville maintain captive adhesive production for quality control in hybrid insulation systems.
Rigid foam dominates installed base. Flexible foam is where expansion concentrates.
End User:
Cost tier stratification separates specification-grade commercial construction from price-sensitive residential applications, with industrial and refrigeration occupying premium-margin positions.
- Construction:Commercial envelope assemblies specify phenolic for Class A fire performance. California Title 24 energy standards and Massachusetts stretch codes drive specification in net-zero building retrofits.
- HVAC:Thinner insulation profiles solve space constraints in heat-pump conversions. Demand is climbing fastest in Northeast corridor mechanical rooms where legacy boiler systems require downsized replacement equipment.
- Industrial:Petrochemical facilities along Texas and Louisiana coastlines specify phenolic for process pipe insulation. OSHA formaldehyde exposure standards govern fabrication shop protocols.
- Refrigeration:Cold-storage warehouses require sub-zero thermal performance with low smoke emission. EPA AIM Act hydrofluorocarbon phasedown pushes manufacturers toward water-blown formulations for this segment.
Construction commands volume share. HVAC is gaining share fastest.
Application:
Application selection tracks directly to code jurisdiction, with fire protection and thermal insulation commanding specification authority while acoustic and pipe applications follow mechanical contractor preferences.
- Thermal Insulation:Dominates commercial roofing and wall assemblies. R-value performance per inch exceeds mineral wool and fiberglass alternatives in constrained envelope designs.
- Acoustic Insulation:Laminated phenolic-faced panels absorb mechanical noise in data centers. Northern Virginia hyperscale facilities specify low-smoke variants for mission-critical infrastructure.
- Fire Protection:Intumescent coatings and fire-resistant boards achieve NFPA 285 compliance. Wall assembly testing delays product launches 18-24 months as certification laboratories face capacity constraints.
- Pipe Insulation:Pre-formed phenolic shells insulate chilled water and refrigeration lines. Industrial facilities in Alberta oil sands and Texas refineries specify these for corrosion resistance under insulation.
Thermal insulation anchors revenue. Fire protection shows steepest expansion trajectory.
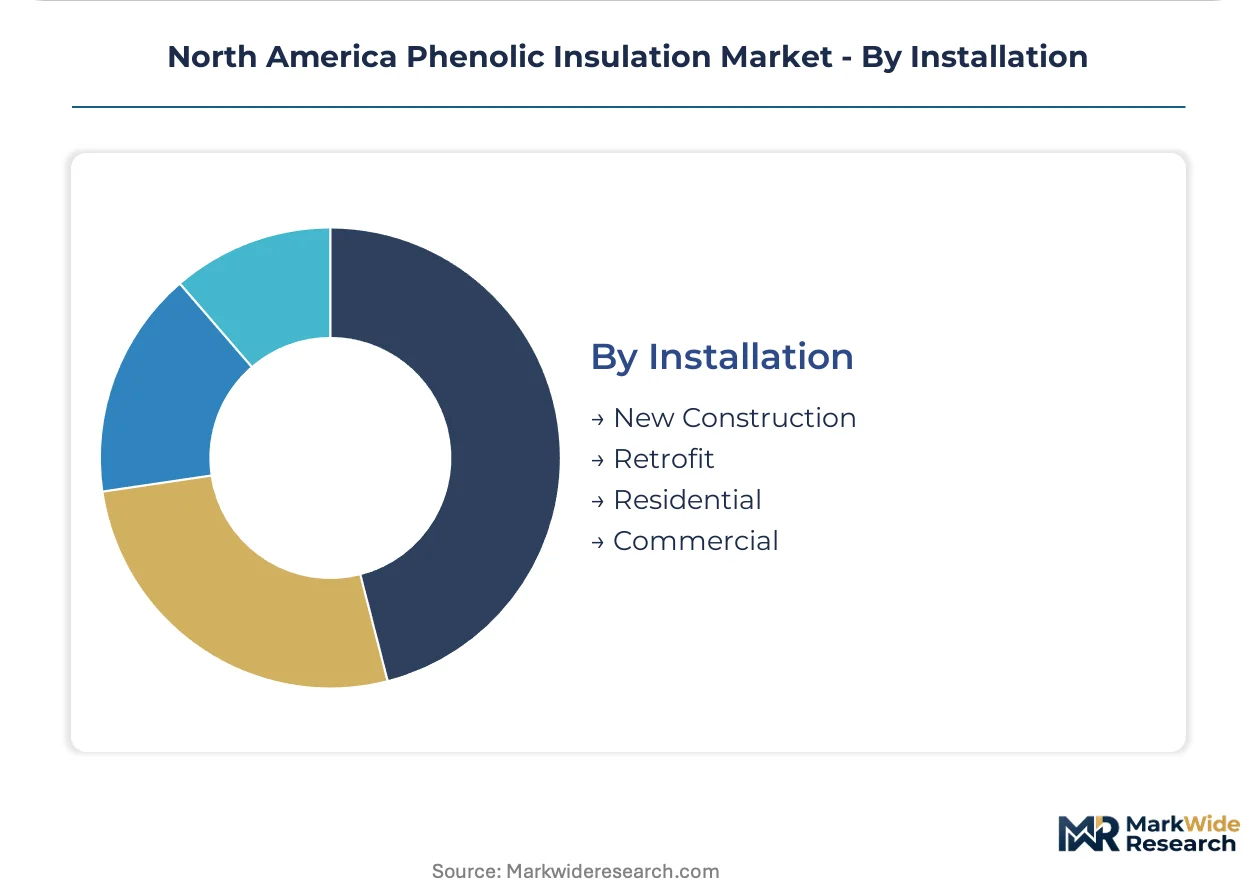
Installation:
Installation type determines channel economics, with new construction favoring distributor bulk sales and retrofit work shifting toward direct manufacturer-contractor relationships.
- New Construction:Large-scale commercial projects specify phenolic through architect-driven procurement. Building information modeling integration now embeds thermal performance data directly into digital construction documents.
- Retrofit:Existing building upgrades require custom fabrication and specialized installation. Kingspan and Owens Corning pilot digital specification tools that bypass traditional distributor markups in mid-market projects.
- Residential:Limited penetration due to polyurethane spray foam cost advantage. Single-family construction permits combustible materials where fire codes do not mandate phenolic performance.
- Commercial:Multi-story buildings drive specification for Class A fire ratings. Chicago, Boston, and San Francisco building departments enforce stringent NFPA 285 compliance for exterior wall assemblies.
New construction holds installed base dominance. Retrofit work is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in phenolic insulation track regional construction cycles and regulatory stringency. The United States maintains net import dependence for specialized blowing agent formulations, while Canada exports surplus rigid foam capacity to northern tier states. Mexico's emerging manufacturing base serves cross-border cold-storage projects.
United States
Cold-storage warehouse construction in the Midwest and Southeast drives specification volume. EPA AIM Act hydrofluorocarbon phasedown schedules constrain domestic formulation choices. The Texas-Louisiana Gulf Coast petrochemical corridor clusters industrial insulation retrofits where OSHA formaldehyde exposure standards govern fabrication protocols.
Canada
Alberta oil sands facilities specify phenolic pipe insulation for corrosion resistance under extreme thermal cycling. Health Canada and PMRA coordinate with EPA on blowing agent transition timelines. Toronto and Vancouver metropolitan areas enforce stringent NFPA 285 compliance for high-rise envelope assemblies, favoring non-combustible core materials.
Mexico
Cross-border cold-chain infrastructure expansion links Mexican produce distribution to US retail networks. Federal environmental regulations lag EPA schedules, creating formulation asymmetries for multinational manufacturers. Monterrey and Mexico City industrial zones concentrate panel fabrication serving northern border state projects.
California
Title 24 building energy efficiency standards mandate thermal performance thresholds that phenolic achieves with thinner profiles. The state's stretch codes advance net-zero mandates in Los Angeles and San Francisco commercial retrofits. Sacramento's regulatory framework often prefigures federal EPA determinations for lower-GWP alternatives.
Massachusetts
Boston and Cambridge stretch codes create specification pull for high-performance envelope materials in commercial building retrofits. Heat-pump conversions in legacy mechanical rooms demand thinner insulation profiles. The state's building department enforces among the most stringent fire-performance requirements for exterior wall assemblies.
North America Phenolic Insulation Market Competitive Landscape
Concentration sits with diversified building materials conglomerates controlling specification channels through distributor relationships and captive R&D capacity. Three to five multinational corporations anchor volume share, while regional fabricators compete on customization velocity for retrofit applications. Strategic archetypes separate mineral wool-phenolic hybrid specialists, closed-cell rigid foam pure-plays, and laminated facing technology developers. Competitive moves cluster around formulation chemistry transitions and direct-to-contractor digital channel pilots.
Among diversified building materials conglomerates, Owens Corning and Johns Manville occupy positions representing hybrid system capabilities, while Kingspan Group exemplifies controlled distribution models for cold-chain infrastructure. These three entities anchor the competitive structure through specification authority in commercial roofing and envelope assemblies. Regional fabricators and chemical specialists including BASF SE, Saint-Gobain, and Rockwool International sit within adjacent tiers, contributing formulation expertise and complementary insulation technologies that influence phenolic procurement decisions through bundled specification.
| Leading Market Players |
|---|
| Saint-Gobain |
| Soprema Group |
| Kingspan Group |
| Rockwool International |
| Knauf Insulation |
| Owens Corning |
| Asahi Kasei Corporation |
| BASF SE |
| Johns Manville Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA SNAP determinations for next-generation blowing agents simultaneously gate supplier qualification and stratify price tiers across the North American phenolic insulation market. Manufacturers holding early formulation approvals command premium positioning in specification-driven channels while independent fabricators face extended compliance timelines that compress their margin flexibility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Gulf Coast petrochemical corridor. Price differentiation centers on NFPA 285 certification grade and volume scale, with fire-rated systems capturing substantial premiums over standard thermal grades. Pricing pressure stems from formaldehyde feedstock volatility concentrated in Texas and Louisiana resin production. Residential contractors exhibit highest price sensitivity, diverting to polyurethane spray foam where fire codes permit combustible alternatives.
Supply Chain Analysis
Houston Ship Channel transit underwrites phenol-formaldehyde resin distribution to Midwest panel fabricators and Southeast cold-storage contractors. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on benzene derivatives, methanol, and specialized HFO-1234ze blowing agents. Single-source vulnerability in domestic cyclopentane supply creates concentration risk for independent foam producers. Distribution runs through national distributor networks serving commercial roofing contractors, with direct manufacturer channels expanding in retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against mineral wool hybrid systems and next-generation aerogel composites that threaten specification share in high-performance envelope applications.
For Market Incumbents: Secure captive supply of lower-GWP blowing agents through backward integration into HFO-1234ze procurement or long-term offtake agreements with domestic chemical producers. Accelerate water-blown formulation R&D to outpace EPA SNAP transition timelines and deny mineral wool competitors specification openings in California Title 24 projects. For New Entrants and Emerging Players: Differentiate on rapid-turnaround custom fabrication for Massachusetts and California retrofit contractors facing compressed project schedules. Target data center thermal management in Northern Virginia where low-smoke specifications and NFPA 285 compliance create barriers to established polyurethane suppliers. Deploy tablet-based specification tools that collapse information asymmetry in mid-market commercial roofing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates seeking to divest non-core insulation assets amid portfolio rationalization. Long-term viability hinges on formulation chemistry capabilities and distributor specification authority rather than commodity foam production. Monitor EPA SNAP rulemaking velocity as the critical inflection signal for stranded asset risk in legacy HFC-dependent production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agents | Captive HFO-1234ze supply secures formulation compliance ahead of EPA phasedown deadlines. |
| Water-Blown Formulation Scale-Up | Eliminates fluorinated agent dependency while qualifying for California Title 24 premium specifications. |
| Direct-to-Contractor Digital Channel | Kingspan and Owens Corning pilots bypass distributor markups in mid-market retrofit projects. |
| NFPA 285 Certification Investment | Wall assembly testing capacity constraints delay competitor launches 18-24 months. |
| Cold-Chain Infrastructure Partnership | Closed-cell phenolic boards capture frozen food distribution network expansion across the Midwest. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA AIM Act rulemaking documents, ACC industry statistics, and SEC 10-K disclosures from listed building materials conglomerates. Interviews with plant managers at Gulf Coast resin facilities, procurement leads at downstream HVAC contractors, distribution channel partners, and technical R&D directors at major insulation manufacturers informed demand-side validation. Bottom-up shipment data triangulates against top-down construction spending indices across the analysis window.
Segmentation dimensions modeled include product form (rigid foam, flexible foam, coatings, adhesives), end-use sector (construction, HVAC, industrial, refrigeration), application type (thermal, acoustic, fire protection, pipe insulation), and installation context (new construction, retrofit, residential, commercial). CAGRs derive from regression analysis of historical shipment volumes against macro construction indicators and regulatory compliance timelines. Blowing agent transition schedules and state-level stretch code adoption curves constitute key forecast inputs.
Material uncertainties — EPA SNAP determination delays, formaldehyde feedstock price spikes, and NFPA 285 laboratory capacity bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation velocity and substitution elasticity that practitioners should keep alternative scenarios live as AIM Act phasedown schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Shrink Tanks Market