
 Paint Knife Market | 2026-2036
Paint Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Knife Market Analytics
Professional-grade specification tiers is collapsing into mid-market offerings as hobbyist spending power rises and tool longevity expectations shift. Liquitex leverages its acrylic-centric ecosystem to bundle paint knives with medium systems. Winsor & Newton anchors its position through heritage craftsmanship positioning in European specialty retail. Daler-Rowney competes on accessible price points without sacrificing blade flexibility ratings.
A paint knife is a handheld blade tool with a flexible or rigid metal, plastic, or composite blade affixed to an offset or straight handle, engineered for applying, scraping, texturing, or mixing viscous paint media with controlled pressure and angular precision. Stainless steel variants dominate professional studios for edge retention and solvent resistance, while plastic and composite formulations serve educational and crafting segments where weight and cost matter more than blade longevity. Offset and trowel types capture the majority of professional artist demand due to knuckle clearance and load-bearing geometry, whereas palette and spatula configurations grow fastest in home improvement and crafting as consumers repurpose artist tools for decorative finishing and furniture restoration. Material-grade segmentation concentrates margin pools in stainless steel and composite categories where certification and alloy specification justify premium positioning.
REACH in Europe restricts certain plasticizers and surface coatings, compelling suppliers to document full material composition chains for blade and handle assemblies. The U.S. Consumer Product Safety Commission monitors sharp-edge labeling and age-grading for tools sold through educational channels, while California Proposition 65 disclosure requirements add compliance overhead for wood-handled variants with treated finishes. ISO 8124 toy safety standards indirectly shape junior and school-grade product design where paint knives blur into children's craft tools. Stakeholders must monitor evolving chemical disclosure mandates and educational procurement certification shifts to sustain market access across premium and institutional tiers.
Market Dynamics
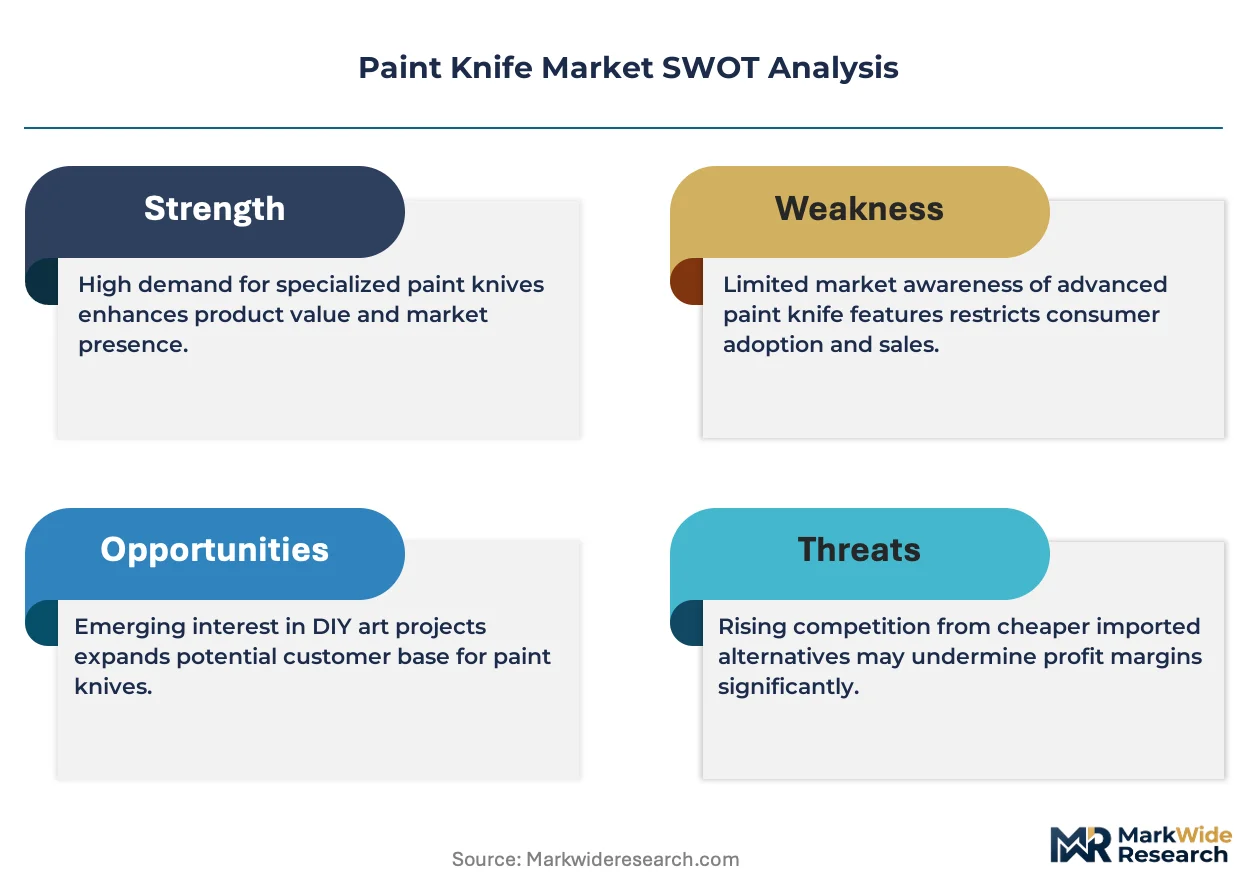
REACH compliance in Europe is forcing stainless steel substitution across blade manufacturing, collapsing legacy plasticizer-dependent supply chains while premium tool demand from German and US atelier culture sustains replacement velocity.
Growth Catalysts
- Vocational art education:Structured curricula in Germany and the United States institutionalize tool replacement cycles, creating predictable demand from accredited institutions.
- REACH chemical disclosure mandates:European manufacturers pivoting toward certified composites and stainless steel alloys capture margin pools inaccessible to uncertified competitors.
- Offset blade geometry:Knuckle-clearance engineering in trowel and offset configurations dominates professional studio procurement for load-bearing paint application.
Market Restraints
- Nickel alloy price volatility:Stainless steel blade production faces input cost pressure from commodity metal markets, squeezing mid-tier manufacturer margins.
- Chinese plastic molding concentration:Educational-grade composite knife supply chains cluster in Pearl River Delta facilities, creating single-source vulnerability.
- California Proposition 65 friction:Wood-handled variant distribution incurs disclosure overhead that blocks small-batch artisanal producers from mass retail channels.
Strategic Opportunities
- Furniture restoration repurposing:Home improvement consumers adopt artist-grade paint knives for decorative finishing, expanding addressable demand beyond traditional fine art verticals.
- EU Green Deal material incentives:Bio-based composite development receives preferential treatment in public procurement tenders for educational supply contracts.
- Direct-to-studio ecommerce:Specialty retailers bypass distributor markup by serving atelier customers through subscription replenishment models.
Industry Challenges
- ISO 8124 toy safety alignment:School-grade product design requires dual certification against artist tool and children's craft standards, extending development timelines.
- Alloy specification documentation:Full material chain traceability for REACH blade assemblies demands supplier audit infrastructure that smaller forges cannot maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Knife Market |
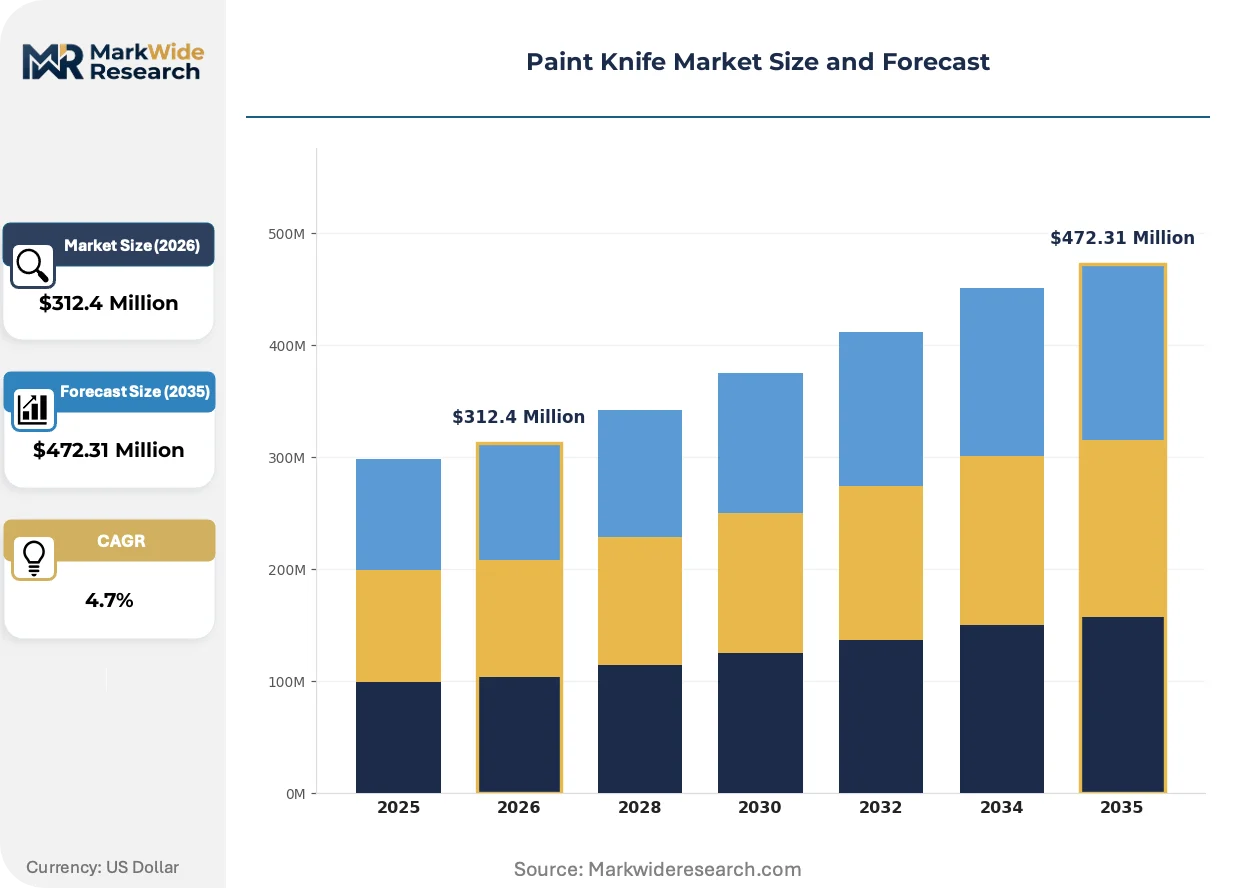
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Offset, Trowel, Spatula, Palette Material: Stainless Steel, Plastic, Wood, Composite Application: Artistic Painting, Home Improvement, Repair, Crafting End User: Professional Artists, Hobbyists, Contractors, Schools |
| Companies Covered | Liquitex, Winsor & Newton, Daler-Rowney, Golden Artist Colors, Princeton Artist Brush Co., Royal Talens, Martin F. Weber Co., Jack Richeson & Co., Silver Brush Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Knife Market Evolving Landscape
Blade material science and regulatory chemistry disclosure are converging to redefine competitive positioning, with certified metal alloys and composite formulations separating compliant suppliers from legacy plastic-dependent manufacturers.
Flexible stainless steel alloys with enhanced solvent resistance are supplanting chrome-plated carbon steel in professional studio environments. German atelier buyers and North American art schools now specify 316-grade stainless for edge retention under aggressive medium exposure. This metallurgical shift is compressing margin structures for traditional blade forges unable to source certified alloy stock.
ECHA enforcement of REACH Annex XVII restrictions on phthalate plasticizers forces handle assembly redesign across European distribution channels. Manufacturers must submit full SVHC documentation or face market withdrawal, with composite handle suppliers in Italy and Spain investing in bio-based polymer R&D to preempt regulatory exclusion. Educational procurement tenders now embed REACH compliance as a mandatory pass/fail criterion.
Palette knife configurations originally engineered for acrylic mixing now serve furniture restoration and decorative craft applications. Hobbyist buyers in the United States and United Kingdom repurpose artist tools for chalk paint and wax finishing, diverting volume from conventional putty knife categories. This consumption-pattern shift rewards manufacturers with flexible blade geometry portfolios spanning fine art and home improvement retail channels.
Paint Knife Market Segmentation
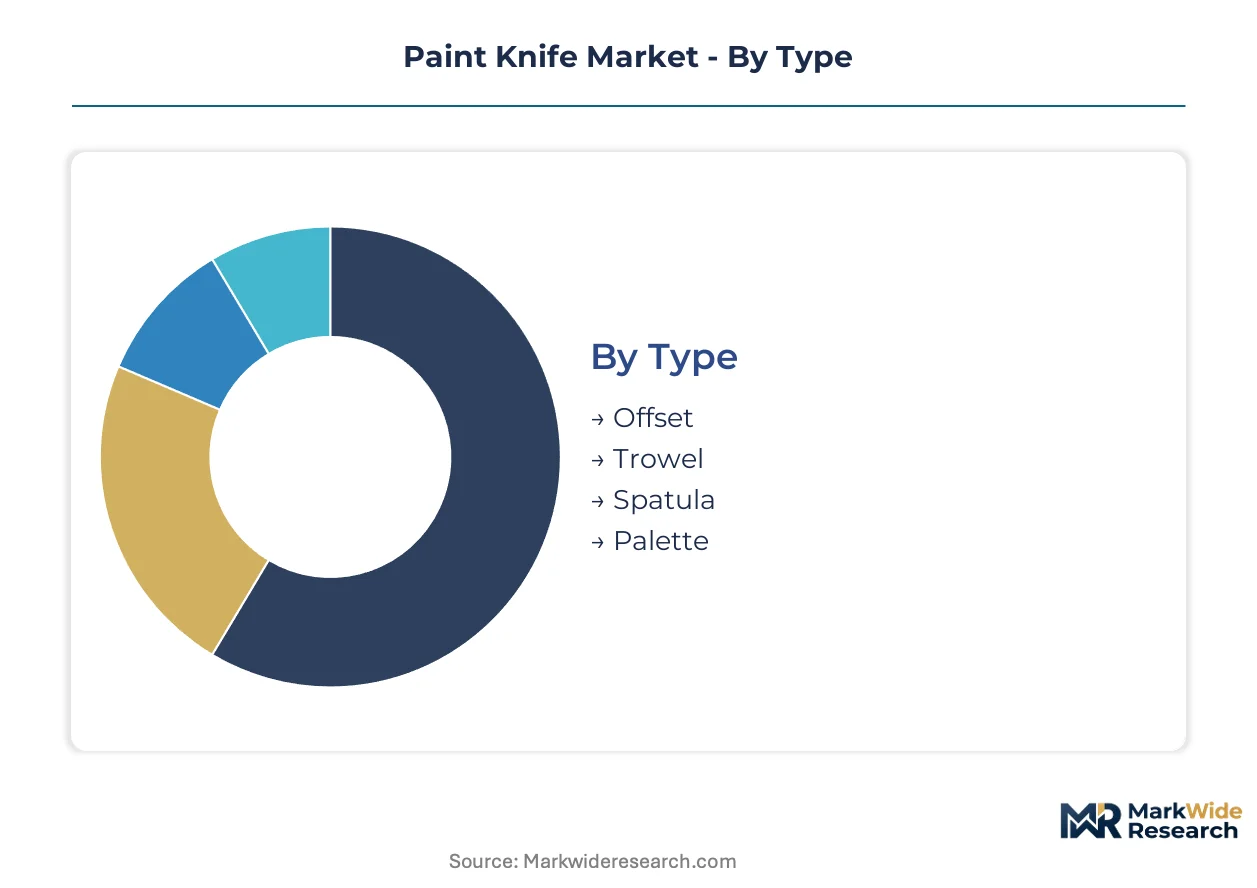
Paint knife segmentation separates margin pools by certification burden and performance specification. Regulatory chemistry disclosure and alloy traceability requirements fragment supplier capabilities across material tiers, creating distinct competitive arenas.
Type:
REACH Annex XVII compliance on blade coatings differentiates professional-grade geometries from educational variants in European distribution.
- Offset:Knuckle-clearance engineering with angled neck geometry positions this configuration for load-bearing acrylic and oil application in German and US atelier studios. REACH-compliant stainless steel blade assemblies command procurement preference from accredited art schools.
- Trowel:Broad rectangular blades with reinforced spines handle heavy impasto and texture building; demand concentrates in North American professional studios where solvent-resistant edge retention justifies premium replacement cycles.
- Spatula:Flexible narrow blades serve detail work and mixing; hobbyist adoption in furniture restoration channels drives volume outside traditional art supply retail.
- Palette:Rounded flexible blades engineered for color mixing now penetrate home improvement segments through chalk paint and wax finishing applications.
Established volume favors Offset; emerging adoption favors Palette.
Material:
Cost tier stratification aligns with compliance infrastructure requirements, separating certified alloy suppliers from commodity plastic molders.
- Stainless Steel:316-grade alloys with documented SVHC chains dominate professional procurement under ECHA enforcement; German blade forges capture margin pools through certified edge retention specifications.
- Composite:Bio-based polymer formulations receive EU Green Deal procurement preference in educational tenders; Italian and Spanish manufacturers invest in preemptive R&D to avoid REACH exclusion.
- Plastic:Pearl River Delta molding concentration serves price-sensitive educational segments where weight and disposability outweigh longevity requirements.
- Wood:Treated handle variants face California Proposition 65 disclosure friction that blocks small-batch artisanal producers from mass retail channels.
Certified stainless steel commands premium positioning; bio-composite development climbs the fastest toward regulatory-aligned procurement.
Application:
Customer type maturity separates replacement-driven institutional demand from discretionary hobbyist purchasing patterns.
- Artistic Painting:Structured vocational curricula in Germany and the United States institutionalize tool replacement cycles, creating predictable demand from accredited institutions with specified blade geometry requirements.
- Home Improvement:Furniture restoration and decorative finishing applications in the United States and United Kingdom repurpose artist-grade tools, diverting volume from conventional putty knife categories through flexible blade portfolios.
- Crafting:ISO 8124 toy safety alignment extends development timelines for school-grade products that blur into children's craft tool standards.
- Repair:Contractor-grade durability specifications favor stainless steel assemblies with solvent-resistant edge retention for professional maintenance applications.
Institutional artistic painting sustains replacement velocity; home improvement applications gain share fastest through cross-channel tool repurposing.
End User:
Supply concentration in Chinese plastic molding creates single-source vulnerability for educational segments while professional tiers demand documented alloy provenance.
- Professional Artists:German atelier culture and North American studio practice specify 316-grade stainless with full material chain traceability, compressing margins for uncertified blade forges.
- Schools:Educational procurement tenders embed REACH compliance as mandatory pass/fail criteria; dual certification against artist tool and children's craft standards extends supplier qualification timelines.
- Hobbyists:Rising spending power collapses traditional premium-mid-economy tier boundaries, shifting volume toward mid-market offerings with heritage craftsmanship positioning.
- Contractors:Repair and maintenance professionals prioritize blade longevity and solvent resistance over ergonomic handle design in high-frequency usage environments.
Professional artist specification drives certified alloy adoption; school procurement expands most quickly through compliance-mandated replacement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blade forging capacity clusters in German industrial zones and Chinese molding districts, while atelier demand concentrates in North American and European vocational education corridors. REACH enforcement and California Proposition 65 disclosure requirements fragment supplier access across major consumption regions.
United States
Vocational art education in Texas and California institutionalizes tool replacement cycles through accredited community college programs. The U.S. Consumer Product Safety Commission monitors sharp-edge labeling for educational channel sales. Brooklyn and Los Angeles atelier districts sustain premium stainless steel procurement from German blade forges.
Germany
Atelier culture in Berlin and Munich drives specification-grade demand for 316-grade stainless steel with documented SVHC chains. ECHA enforcement of REACH Annex XVII restrictions compels handle assembly redesign across Bavarian and North Rhine-Westphalian manufacturing zones. Solingen blade forges capture margin pools through certified edge retention specifications.
China
Pearl River Delta molding facilities supply educational-grade composite knives to price-sensitive institutional buyers. The Ministry of Ecology and Environment monitors chemical discharge from handle coating operations in Guangdong province. Shenzhen and Dongguan clusters face single-source vulnerability as Western buyers demand REACH-aligned material documentation.
United Kingdom
Hobbyist repurposing of artist tools for furniture restoration expands addressable demand beyond traditional fine art verticals. The UK REACH framework maintains alignment with EU chemical disclosure mandates post-Brexit. London and Manchester craft retail corridors drive palette knife adoption for chalk paint and wax finishing applications.
Italy
Bio-based polymer R&D investment in Lombardy and Veneto preempts regulatory exclusion from EU educational procurement tenders. ANSM chemical safety oversight extends to imported artist tool coatings through customs surveillance protocols. Milan specialty retailers serve atelier customers through direct-to-studio subscription replenishment models.
Paint Knife Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage European forges commanding certified alloy premiums while Asian molders capture educational volume through scale efficiency. The market structure separates into three strategic tiers: heritage craftsmanship specialists, acrylic-ecosystem bundlers, and accessible-price-point generalists. Dominant competitive moves include portfolio diversification into adjacent craft tool categories and strategic partnerships with educational procurement consortia.
Within the heritage craftsmanship tier, Winsor & Newton and Royal Talens occupy positions anchored by European specialty retail relationships and vocational education certification. Liquitex exemplifies the acrylic-ecosystem bundler archetype, leveraging medium-system integration to capture studio-grade demand. Among accessible-price-point competitors, Daler-Rowney and Golden Artist Colors represent mid-market positioning that collapses traditional premium-economy boundaries as hobbyist spending power rises.
| Leading Market Players |
|---|
| Liquitex |
| Winsor & Newton |
| Daler-Rowney |
| Golden Artist Colors |
| Princeton Artist Brush Co. |
| Royal Talens |
| Martin F. Weber Co. |
| Jack Richeson & Co. |
| Silver Brush Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German blade forges and North American art school procurement consortia lock in 316-grade stainless steel supply at fixed alloy premiums, anchoring price visibility for professional-tier manufacturers while exposing mid-market competitors to spot nickel volatility.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European distribution channels, forcing uncertified competitors toward commodity plastic segments. Three-tier pricing structure across premium, standard, and economy levels separates 316-grade certified assemblies from chrome-plated carbon steel and disposable educational variants. Cost compression in mid-tier stainless steel is intensifying because nickel alloy spot markets transmit volatility directly to uncertified blade forges. Hobbyist buyers in furniture restoration channels show least price sensitivity, while educational procurement officers in US community college systems negotiate volume discounts aggressively.
Supply Chain Analysis
Solingen forging district concentration in Germany underwrites professional-grade blade quality certification but creates single-source vulnerability for REACH-compliant alloy stock. Raw material flows draw from Swedish nickel ore refinement, Italian polymer compounding for bio-based handles, and Pearl River Delta injection molding for educational-grade plastics. Tariff exposure on Chinese composite knife imports into the United States threatens margin structures for price-sensitive institutional buyers. Distribution runs through specialty art supply retailers, direct-to-studio subscription services, and home improvement channel partners repurposing artist tools for decorative finishing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical disclosure mandates and EU Green Deal procurement incentives are disrupting competitive positioning, rewarding certified alloy suppliers with margin pools inaccessible to legacy plastic-dependent manufacturers.
For Market Incumbents: Shield certified market position by deepening backward integration into 316-grade alloy sourcing from Swedish refiners, eliminating spot market exposure. Accelerate bio-based polymer R&D investment to preempt REACH Annex XVII exclusion from Italian and Spanish educational tenders. Channel control through direct-to-studio subscription models defends against distributor margin compression.
For New Entrants and Emerging Players: Direct-to-studio replenishment service gaps where heritage forges under-serve independent atelier customers offer white-space entry. Furniture restoration tool repurposing in United Kingdom and United States home improvement channels presents fastest-penetration application vertical. Go-to-market through specialty craft retail partnerships bypasses entrenched art supply distributor relationships.
For Investors and Strategic Acquirers: Italian bio-composite specialists with EU Green Deal procurement credentials represent priority acquisition targets. Long-term viability hinges on regulatory compliance infrastructure rather than scale efficiency. Monitor ECHA enforcement intensity against phthalate plasticizers as inflection signal for composite handle demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Solingen forges securing Swedish nickel refinement contracts eliminate spot price volatility transmission. |
| Bio-Based Polymer Certification | Lombardy and Veneto manufacturers capture EU educational procurement preference through REACH-aligned R&D. |
| Direct-to-Studio Subscription Launch | Milan specialty retailers bypass distributor markup by serving Berlin and Munich atelier replenishment cycles. |
| Furniture Restoration Channel Expansion | United Kingdom and United States home improvement adoption diverts volume from conventional putty knife categories. |
| REACH Compliance Documentation Investment | Full SVHC material chain traceability separates certified suppliers from Pearl River Delta commodity molders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, US Consumer Product Safety Commission guidance documents, and EU Green Deal procurement tender databases. Primary interviews engaged blade forge operations managers, art school procurement directors, specialty retail category buyers, and composite polymer R&D leads across Germany, Italy, China, and the United States. Secondary validation drew from Solingen industry association reports, Pearl River Delta customs export records, and California Proposition 65 disclosure databases. Bottom-up demand modeling from accredited institution replacement cycles triangulates against top-down market sizing from art supply distributor revenue disclosures.
Segmentation dimensions modeled include blade geometry type, material certification tier, application vertical, and end-user procurement authority across the analysis window. CAGRs derive from replacement velocity in vocational education curricula and cross-channel adoption in home improvement applications. Industry-specific forecast inputs incorporate REACH Annex XVII enforcement timelines and EU Green Deal bio-based procurement incentive trajectories.
Forecasts assume regulatory continuity in EU REACH, UK REACH alignment, and California Proposition 65 enforcement regimes; material policy shifts would require re-modeling alloy substitution rates and composite handle demand curves. Practitioners should keep alternative scenarios live as ECHA phthalate restriction enforcement intensity and nickel alloy commodity volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Metal Molds Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Argon Knife Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Wood Protein Market
Industrial Materials
Pultrusion Products Market