
 Cork Material Market | 2026-2036
Cork Material Market Size, Share, and Industry Trends Forecast 2026-2036
Cork Material Market Intelligence
The European Union's Green Deal is shifting buyer preference toward renewable and recyclable materials in construction and packaging. Amorim Cork Composites leverages its extensive control over raw material supply from Portugal to maintain market leadership. Jelinek Cork Group specializes in a wide array of custom products, from industrial components to consumer goods. Granorte differentiates through design-forward composite cork solutions for interior flooring and wall coverings.
Cork material is a buoyant, elastic, and fire-retardant substance harvested from the bark of the Quercus suber tree. Its honeycomb-like cellular structure, filled with a gas similar to air, provides exceptional thermal and acoustic insulation properties. Among product types, agglomerated cork constitutes a significant volume share due to its use in industrial applications. The construction sector, particularly for flooring and insulation applications, represents the largest end-use market for these materials.
Product quality and market access are shaped by multiple regulatory frameworks. In Europe, CE marking is mandatory for cork insulation products under the Construction Products Regulation. In the United States, materials must comply with EPA standards regarding volatile organic compounds. Stakeholders must now focus on securing long-term, certified raw material supply chains to meet rising sustainability verification demands.
Market Dynamics
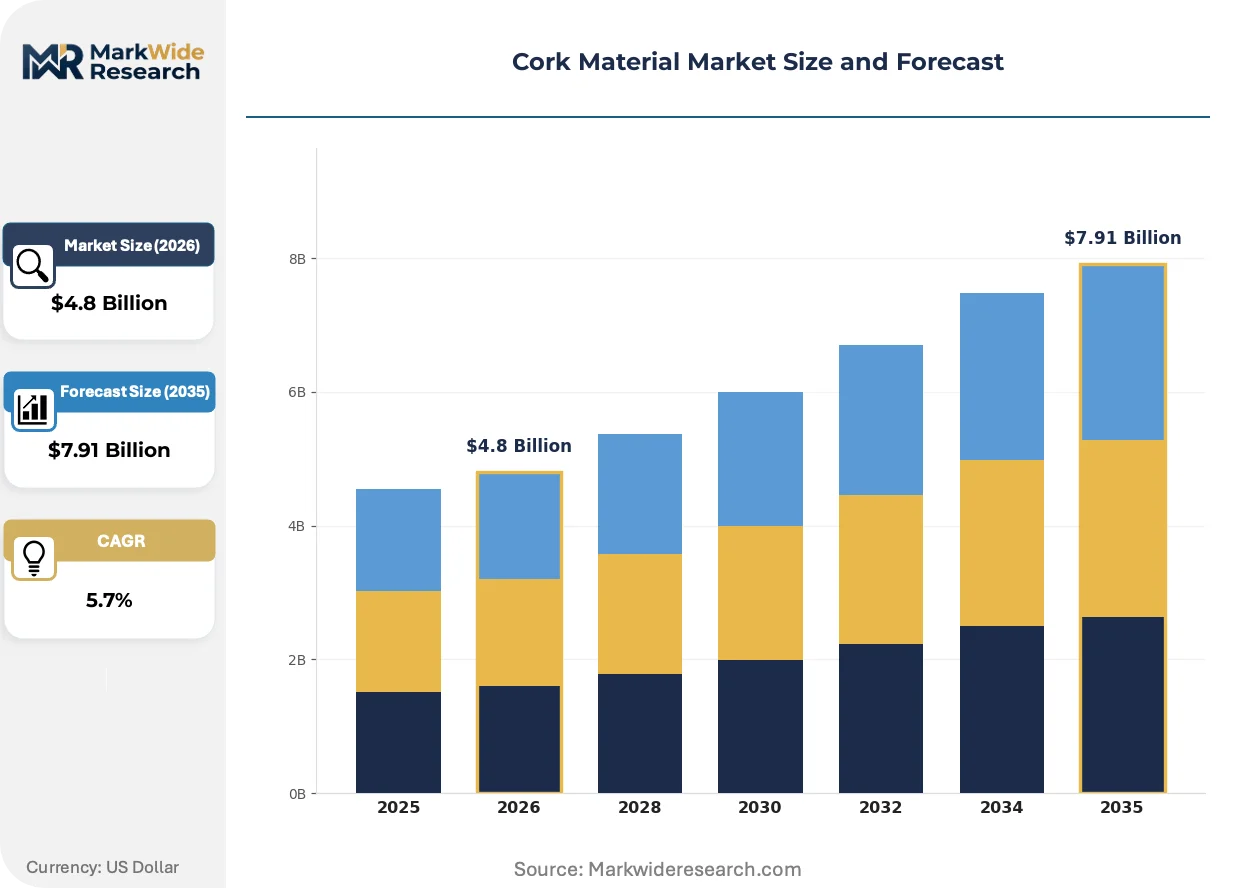
The cork material market's structure is defined by the geographic concentration of Quercus suber cultivation, primarily in Portugal, clashing with rising global demand for verified sustainable building materials driven by policies like the EU Green Deal.
Growth Catalysts
- Sustainable Construction Policy:The EU Green Deal promotes cork for thermal and acoustic insulation, meeting mandates for renewable, energy-efficient building materials.
- Premium Wine Sector:The wine industry’s reliance on natural cork stoppers for quality sealing and branding provides a stable, high-value demand base.
- Automotive Noise Reduction:Vehicle manufacturers use agglomerated cork for vibration damping and acoustic insulation, improving cabin comfort and reducing overall vehicle weight.
Market Restraints
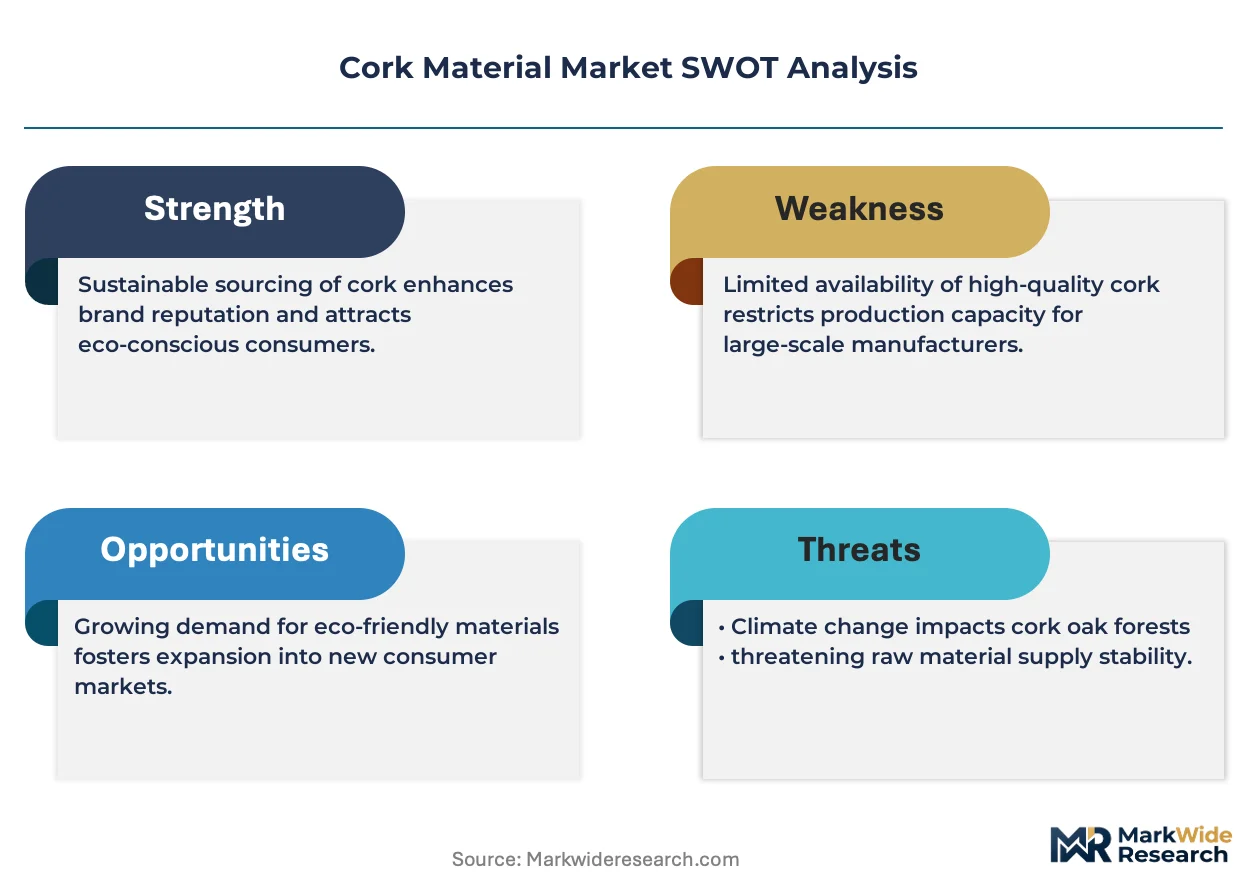
- Supply Chain Vulnerability:Dependence on Portugal’s Quercus suber forests creates market risk from climate change and regional pests, impacting raw material availability.
- Synthetic Material Competition:Lower-cost synthetic stoppers and foam insulation panels present a persistent substitution threat in the beverage and construction industries.
- Inelastic Supply Response:The nine-year harvest cycle for cork bark makes the raw material supply inherently slow to respond to sudden increases in demand.
Strategic Opportunities
- Asia-Pacific Green Building Markets:Untapped demand exists in the green building sectors of Japan and Australia for premium, sustainable insulation materials like cork.
- Advanced Industrial Composites:Developing cork composites for aerospace and EV battery casings provides entry into high-margin, technology-driven sectors beyond traditional markets.
- Forest Carbon Monetization:Certified carbon credit programs for managed cork oak forests can create new revenue and validate the material’s sustainability credentials.
Industry Challenges
- Certification Complexity:Implementing and maintaining chain-of-custody certifications, such as FSC, to meet buyer sustainability demands is a complex and costly operational hurdle for suppliers.
- Harvesting Labor Scarcity:The industry faces a shortage of skilled labor for the manual process of cork bark harvesting, which can constrain raw material supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cork Material Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cork, Agglomerated Cork, Composite Cork, Expanded Cork Application: Insulation, Flooring, Wall Coverings, Gaskets, Bulletin Boards, Footwear End User: Construction Companies, Manufacturers, Interior Designers, Artisans Packaging Type: Sheets, Rolls, Blocks, Tiles, Granules |
| Companies Covered | Amorim Cork Composites, Granorte, Jelinek Cork Group, Ecore International, Corksribas, LICO, Expanko, Green Building Supply, Manton Cork, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cork Material Market Strategic Shifts & Innovations
Technological advancements in material science are intersecting with a market-wide push for verifiable sustainability. This convergence is creating new product categories and altering the value proposition of cork in both traditional and novel applications.
Advanced cork composites blend granulated cork with specialized binders to create materials with specific thermal, acoustic, or vibration-damping properties. The automotive and aerospace industries are increasingly adopting these composites for lightweight components and insulation. This trend is decentralizing the material's value proposition from purely natural bark products toward a broader portfolio of engineered solutions.
In the United States, EPA standards limiting volatile organic compounds (VOCs) in building materials are directly influencing product specification for interior finishes. These regulations create a favorable market environment for naturally low-VOC materials. Consequently, cork flooring and wall coverings are gaining share in North American commercial and residential projects where indoor air quality is a primary design consideration.
A notable shift in buyer behavior is the prioritization of supply chain transparency and third-party sustainability certifications over pure price-based decisions. This trend is compelling suppliers to invest in chain-of-custody documentation, such as FSC certification, to secure contracts. This procurement pattern is most evident in European construction projects and with multinational consumer brands seeking to validate their ESG commitments.
Cork Material Market Segmentation
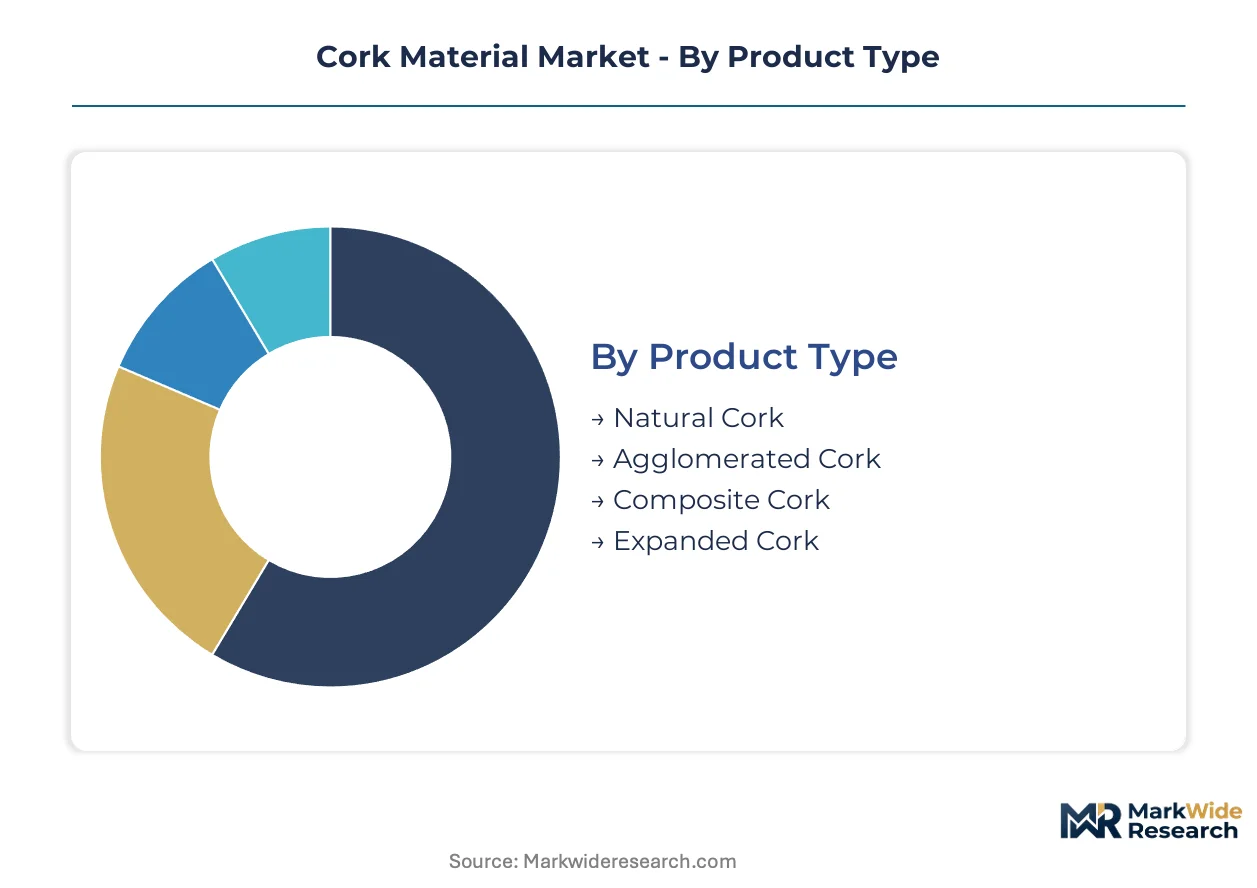
The cork material market delineates across various product forms, applications, end-users, and packaging types. Understanding these segments reveals specific demand patterns and areas for innovation within the industry. Each category reflects distinct material properties and market requirements for optimal performance.
Product Type:
The product type segmentation highlights the spectrum from naturally harvested bark to highly engineered composite solutions, catering to diverse performance and aesthetic needs.
- Agglomerated Cork:These products consist of cork granules bound with adhesives, offering consistent density and mechanical properties. Demand concentrates in industrial applications like gaskets and automotive components, driven by cost-effectiveness.
- Composite Cork:Combining cork granules with other materials, these composites are engineered for specific properties like enhanced durability or flexibility. Green building projects in Germany and the United States drive demand for high-performance composite flooring.
- Natural Cork:Directly cut from cork oak bark, natural cork maintains its inherent cellular structure, valued for aesthetic and sealing properties in the premium wine sector.
- Expanded Cork:Produced by steam-heating cork granules, this material expands and self-agglomerates without binders, primarily used for superior thermal and acoustic insulation in construction.
Leading the category by volume: Agglomerated Cork. Growing fastest: Composite Cork.
Application:
Application analysis reveals where cork's unique attributes provide the most functional value, influencing volume consumption across different industries.
- Insulation:Cork's cellular structure provides exceptional thermal and acoustic insulation, making it ideal for building envelopes and interior spaces. European construction policies, like the EU Green Deal, promote cork for energy-efficient building designs.
- Flooring:Offering resilience, sound absorption, and warmth underfoot, cork flooring is a preferred choice for residential and commercial interiors. North American projects specify cork due to its low VOC emissions and sustainable profile.
- Wall Coverings:These decorative and functional cork panels enhance interior aesthetics while contributing to acoustic comfort.
- Gaskets:Cork's compressibility and resistance to liquids make it suitable for sealing applications in engines and industrial machinery.
- Bulletin Boards:The self-healing nature and tack-retention of cork make it a classic material for display surfaces.
- Footwear:Lightweight and shock-absorbent cork finds use in shoe insoles and midsoles, providing comfort.
This application category sees Insulation dominating in adoption, while Flooring exhibits the steepest expansion trajectory.
End User:
The end-user segment differentiates demand based on procurement scale, technical specifications, and the ultimate purpose of the cork material.
- Construction Companies:These large-scale buyers procure cork for insulation, flooring, and wall covering installations in new builds and renovations. Sustainability certifications are critical for securing contracts in European green building projects.
- Manufacturers:Industrial manufacturers utilize cork for specific material properties in components like automotive vibration dampers or specialized gaskets. Product consistency and supply chain reliability are paramount for high-volume users.
- Interior Designers:Specifying cork for aesthetic and performance reasons, designers influence material selection for flooring and wall coverings in bespoke projects.
- Artisans:Small-scale craftspeople use cork for unique consumer goods, emphasizing its natural texture, lightweight properties, and eco-friendly appeal.
Demand from Construction Companies accounts for the largest share, with Manufacturers showing consistent growth.
Packaging Type:
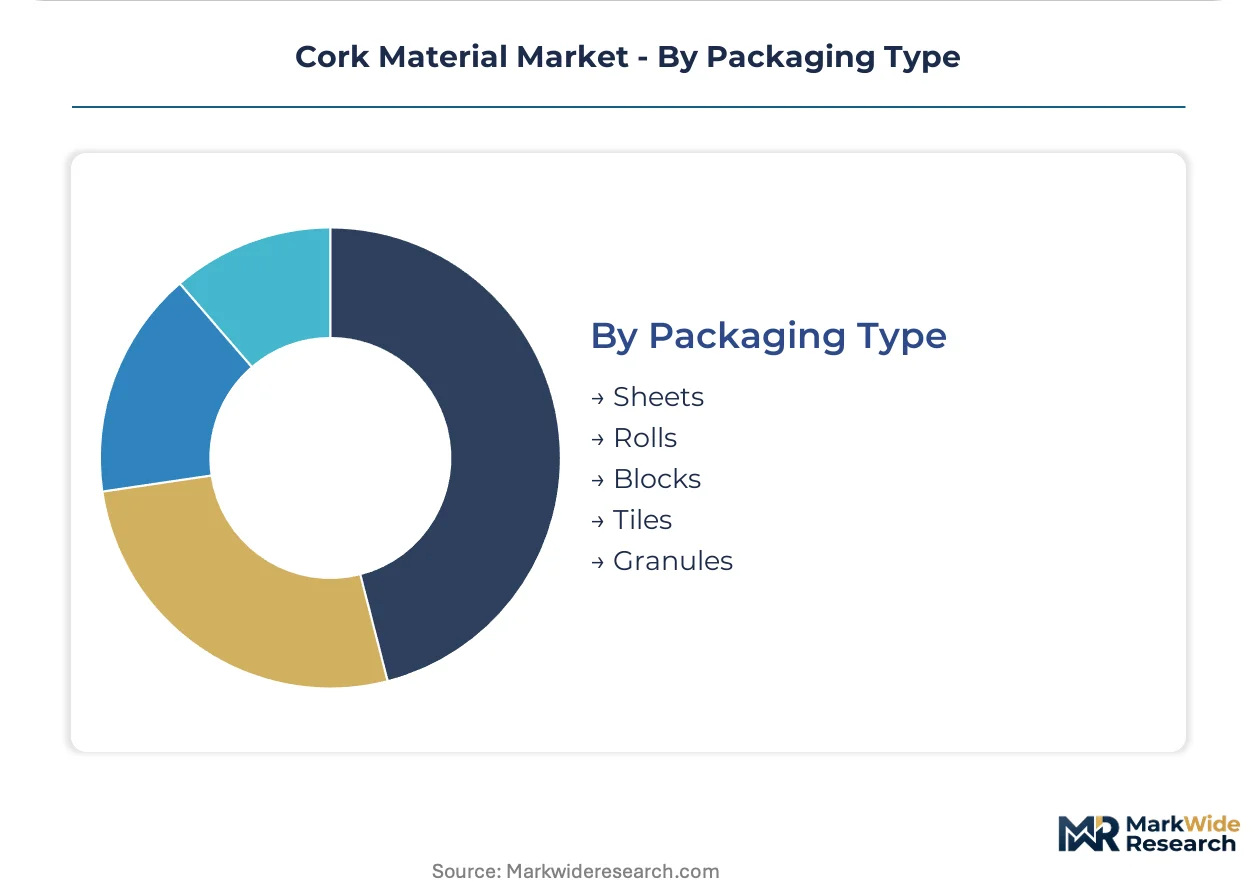
Packaging type segmentation reflects the various forms cork material is supplied, optimized for different manufacturing processes and end-use applications.
- Granules:Comprising small cork particles, granules serve as raw material for agglomerated cork, composites, and insulation fill. Their versatility makes them essential for high-volume industrial processing.
- Sheets:Flat, uniform sections of cork are widely used for insulation boards, flooring underlays, and gasket fabrication due to ease of handling and cutting. The construction sector relies heavily on sheet-form cork.
- Rolls:Providing continuous lengths of cork material, rolls suit applications requiring extensive coverage, like underlayment for large flooring areas.
- Blocks:Dense, solid forms of cork are often carved or cut into specialized components, including stoppers for premium wines.
- Tiles:Pre-cut, finished cork tiles are primarily used for decorative flooring and wall covering applications, offering aesthetic appeal and straightforward installation.
The utility of Granules enables broad industrial use, while Sheets are gaining traction in specific niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cork material market exhibits a distinct production-consumption divide, with raw material supply heavily concentrated in specific European regions. Demand for finished cork products, however, disperses globally, driven by construction and packaging sectors. This geographic split necessitates robust supply chain management for manufacturers.
Portugal
Portugal dominates global cork production, housing extensive Quercus suber forests. The country's forestry policies support sustainable harvesting practices to maintain this natural resource. Lisbon and Porto serve as key hubs for cork processing and export operations.
Germany
German demand for cork material is strong in green building projects, particularly for insulation. The EU Green Deal mandates drive the specification of renewable and energy-efficient building materials. Cities like Frankfurt and Munich prioritize low-VOC construction, favoring cork flooring and wall coverings.
United States
The United States market shows increasing demand for high-performance cork products in sustainable construction. EPA standards regarding volatile organic compounds influence material selection for interior finishes. California and the Pacific Northwest demonstrate significant uptake in residential and commercial green building.
Japan
Japanese construction is exploring sustainable insulation materials, presenting an opportunity for premium cork products. Government initiatives promoting energy efficiency in buildings could further boost cork adoption. Tokyo and Osaka's urban development projects seek advanced acoustic and thermal solutions.
Spain
Spain is a significant producer of cork, second only to Portugal, with a focus on both raw material and processed products. National environmental regulations encourage sustainable forest management practices for cork oak woodlands. Catalonia and Andalusia are key regions for cork harvesting and manufacturing.
Cork Material Market Key Industry Players
The competitive structure tilts toward integrated material specialists and diversified product manufacturers. The market includes large-scale raw material processors alongside niche providers of custom cork solutions. Key strategic moves involve securing long-term, certified raw material supply chains and expanding product portfolios into advanced composites. Geographic expansion into emerging green building markets also represents a significant competitive thrust.
Among the integrated material specialists, Amorim Cork Composites, a Portuguese entity, exemplifies extensive control over raw material sourcing and large-scale processing capabilities. Granorte, another European firm, occupies a position in design-forward composite cork solutions, particularly for interior flooring and wall coverings. Jelinek Cork Group, a North American company, represents providers specializing in a wide array of custom cork products, ranging from industrial components to diverse consumer goods. These companies collectively anchor significant segments of the cork material value chain, each leveraging distinct strengths.
| Leading Market Players |
|---|
| Amorim Cork Composites |
| Granorte |
| Jelinek Cork Group |
| Ecore International |
| Corksribas |
| LICO |
| Expanko |
| Green Building Supply |
| Manton Cork |
| Others |
Cost & Logistics Intelligence
Raw material cost, primarily cork bark, dictates upstream pricing power, which then cascades through various processing stages to influence the final product price points for construction and industrial end-users.
Pricing Analysis
Value-based pricing anchors the cork material market, reflecting its superior performance attributes in insulation and acoustic damping. Price differentiation stems from certification levels, such as FSC, and the degree of customization in composite cork solutions. Pricing softness stems from the availability of lower-cost synthetic alternatives in both the construction and beverage industries. Construction companies exhibit higher price sensitivity for basic insulation, while interior designers prioritize aesthetic and certified performance.
Supply Chain Analysis
Single-source vulnerability sits with Portugal's Quercus suber forests, which provide the primary raw material for global cork production. The supply chain draws heavily from cork bark and specialized binders for composite products. Inelastic supply response due to the nine-year harvest cycle for cork bark presents a structural risk to market stability. Distribution extends through direct sales to large industrial manufacturers and specialized distributors serving construction projects and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cork material market is positioned for consolidation, with increasing certification costs and supply chain complexities forcing smaller, less integrated players to exit.
For Market Incumbents: Deploy strategic R&D investment into advanced composites for high-margin applications. Diversify the product portfolio to reduce reliance on traditional segments facing synthetic competition, mitigating market share erosion. Secure long-term, certified raw material supply agreements to counter supply chain vulnerability and meet rising sustainability verification demands.
For New Entrants and Emerging Players: Underserved green building specifiers in Asia-Pacific represent a significant entry point for premium cork solutions. Target high-performance acoustic and thermal insulation applications in urban residential projects. A direct-to-specifier education model, highlighting cork's low VOC emissions and sustainability credentials, can accelerate market penetration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated mid-cap specialists in European cork-producing regions with robust raw material access. Long-term viability over a five-to-ten-year window hinges on sustainable forestry management and product innovation. The signal to watch is the successful commercialization of advanced cork composites in aerospace or electric vehicle battery casings.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Certified Forest Management | Secures long-term raw material supply for Amorim Cork Composites. |
| Invest in Advanced Composite R&D | Enables Granorte to develop new products for high-performance sectors. |
| Regional Market Expansion (Asia-Pacific) | Jelinek Cork Group can tap into emerging green building demand. |
| Automate Cork Processing | Improves operational efficiency for Ecore International's production lines. |
| Develop Bio-based Binders | Reduces environmental footprint for Corksribas' agglomerated products. |
Research Approach
Independent corroboration across primary interviews, market reports, and regulatory documents underwrites the qualitative findings within this analysis. This approach combines insights from construction procurement managers, cork material engineers, sustainability consultants, and forestry experts. Secondary data sources include EU Green Deal policy papers, EPA standards documents, FSC certification databases, and industry association publications, triangulated with bottom-up and top-down market sizing.
The rate-of-change decomposition framing informs the quantitative market forecast across the analysis window. This framework models segmentation dimensions including product type, application, end-user, packaging type, and regional regulatory compliance. Compound annual growth rates are derived by integrating historical trends with future demand projections based on key industry-specific inputs, such as Quercus suber harvest yields and green building project pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts, climate change impacts on cork oak forests, and technological breakthroughs in synthetic alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Couplings Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Paint Knife Market
Industrial Materials
Noise Reduction Plastic Gear Market