
 Paraffin Wax Market | 2026-2036
Paraffin Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Paraffin Wax Market Analysis
Refined-grade paraffin wax is rotating toward higher oil-content thresholds and lower aromatic specifications across industrial procurement channels. Sasol leverages captive Fischer-Tropsch feedstock to sustain fully refined output for European coating formulators. ExxonMobil anchors North American supply through integrated Gulf Coast refining complexes. Sinopec dominates spot-market flows into Asian packaging converters with scale advantages on semi-refined streams.
Paraffin wax comprises a mixture of solid hydrocarbons derived from petroleum slack wax via solvent deoiling or hydrotreating, with melting points typically spanning 46°C to 68°C depending on carbon-chain distribution. It functions primarily as a barrier agent, binder, and moisture seal across candles, coatings, and food-grade packaging films. Fully refined grades command premium positioning in cosmetics and food-contact applications where FDA and EFSA purity ceilings apply, while semi-refined volumes compete on cost in industrial coatings and general candle production. Candle wax as a product category retains mature demand in developed economies but faces substitution pressure from vegetable-based alternatives in premium consumer segments. Microcrystalline wax occupies a narrower niche in adhesives and rubber compounding where higher melt viscosity delivers performance advantages standard paraffin cannot match.
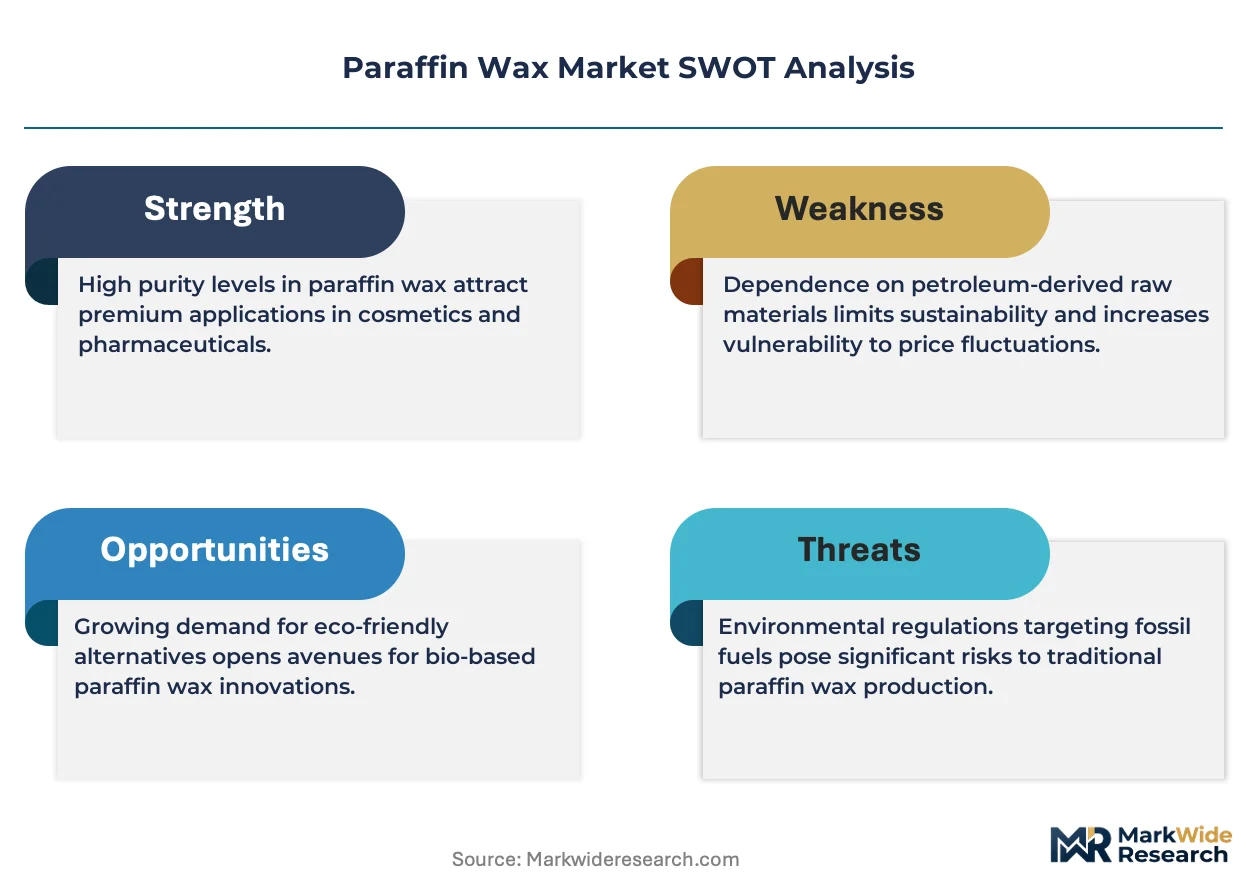
EPA fuel-quality standards indirectly constrain slack wax availability by altering refinery yield structures, while REACH registration requirements in Europe filter out lower-purity imports from non-EEA sources. FDA food-contact regulations under 21 CFR 172.886 and 178.3710 delineate permissible oil content and UV absorbance limits for direct and indirect food applications. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs for dual-certification rise and sourcing flexibility narrows.
Market Dynamics
Refinery yield restructuring under EPA fuel-quality standards is compressing slack wax availability and forcing coating formulators toward captive Fischer-Tropsch supply chains. This feedstock squeeze is redrawing competitive boundaries between petroleum-derived and synthetic wax producers across industrial procurement channels.
Growth Catalysts
- REACH compliance thresholds:European ECHA registration requirements for fully refined grades are filtering out lower-purity imports and consolidating premium supply around certified producers.
- Candle manufacturers:Southeast Asian candle producers are expanding orders for fully refined paraffin as export markets tighten purity specifications for consumer goods.
- Packaging sector scaling:China's domestic coating and flexible packaging converters are absorbing semi-refined volumes at scale, anchoring regional demand concentration.
Market Restraints
- Slack wax input volatility:EPA fuel-quality standards alter refinery yield structures, constraining the primary feedstock for solvent deoiling processes.
- Supplier concentration risk:Middle Eastern and North American integrated refiners control disproportionate shares of exportable slack wax supply.
- Vegetable wax substitution:Soy and palm-derived alternatives are capturing premium candle segments where sustainability positioning commands price premiums.
Strategic Opportunities
- Food-contact certification gap:FDA 21 CFR 172.886 compliance for direct food applications remains underpenetrated among mid-scale Asian producers.
- Cosmetics-grade white space:EFSA purity ceilings for topical applications are creating tiered entry points for hydrotreated ultra-refined streams.
- Microcrystalline convergence:Blending paraffin with higher-melt-viscosity microcrystalline wax opens rubber compounding and adhesive niches.
Industry Challenges
- Dual-certification timelines:Simultaneous FDA and REACH compliance requires 18-24 month validation cycles that freeze sourcing flexibility.
- Hydrotreater capex intensity:Ultra-low aromatic production demands continuous catalytic hydrogenation investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraffin Wax Market |
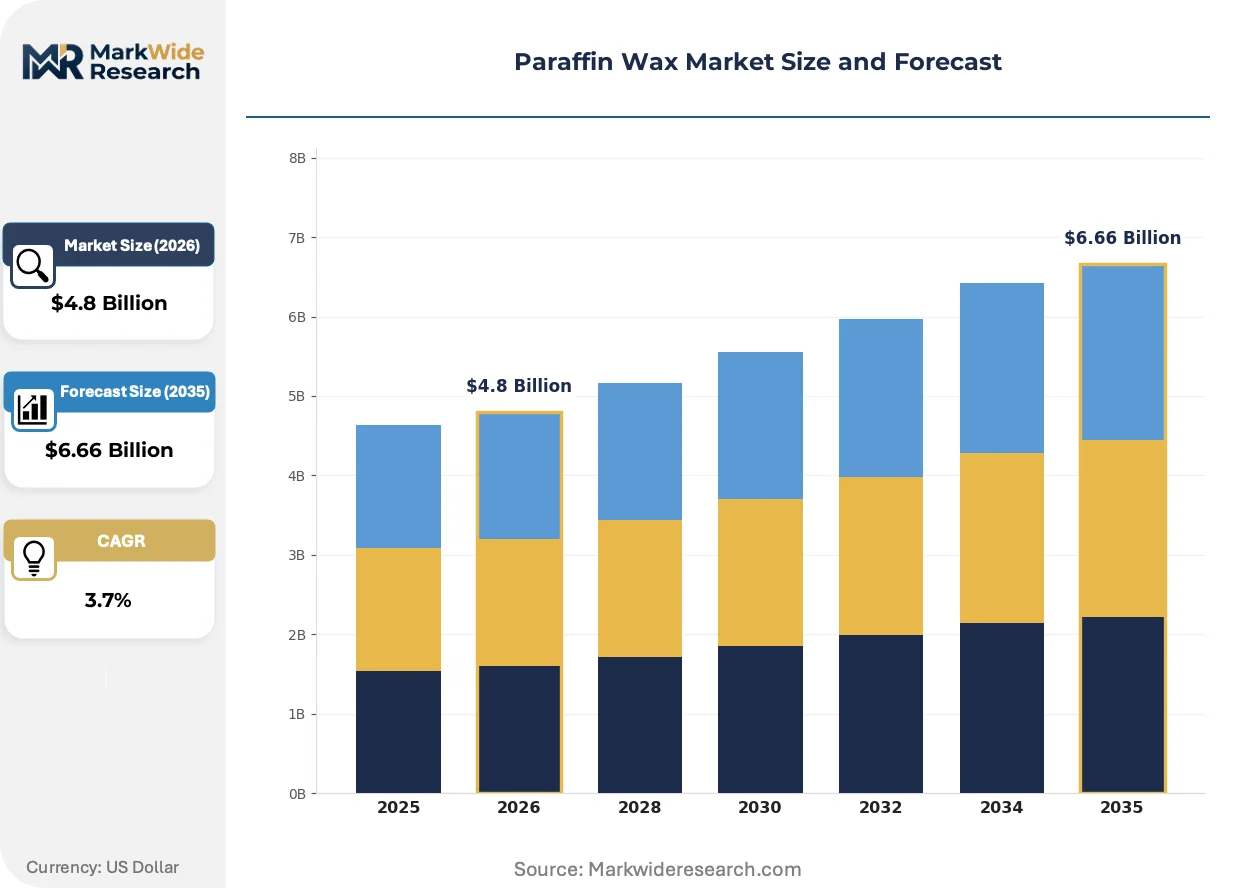
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Refined, Semi-Refined, Microcrystalline, Candle Wax Application: Candles, Coatings, Cosmetics, Packaging End User: Food Industry, Healthcare, Personal Care, Industrial Form: Solid, Liquid, Granular, Block |
| Companies Covered | ExxonMobil, Sinopec, Sasol, Shell, PetroChina, Petrobras, Repsol, The International Group, NIPPON SEIRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraffin Wax Market Emerging Trajectories
Processing technology and regulatory stringency are splitting the paraffin market into parallel supply tracks. Producers now face divergent investment paths depending on which purity tier and end-use certification they target.
Hydrotreating technology for aromatic reduction is bifurcating the fully refined segment into pharmaceutical-grade and standard food-grade supply pools. European coating formulators are adopting pharmaceutical-grade streams for high-barrier packaging films, while Asian converters remain on standard food-grade specifications. This technology split is compressing margin recovery for producers caught between certification tiers without scale in either.
REACH registration requirements under ECHA jurisdiction are tightening UV absorbance and polycyclic aromatic hydrocarbon limits for imported paraffin. Industrial consequence includes exclusion of semi-refined streams from European cosmetics and food-contact channels. Asian exporters are responding by redirecting lower-purity volumes toward Middle Eastern and African markets with less stringent import specifications.
Direct procurement from integrated refiners is displacing traditional distributor channels for volume buyers in packaging and candle manufacturing. Large Southeast Asian candle producers now contract directly with Gulf Coast and Middle Eastern refiners, bypassing regional traders. This channel compression is most visible in Indonesia and Vietnam where converter consolidation has created minimum viable contract sizes for direct supply relationships.
Paraffin Wax Market Segmentation
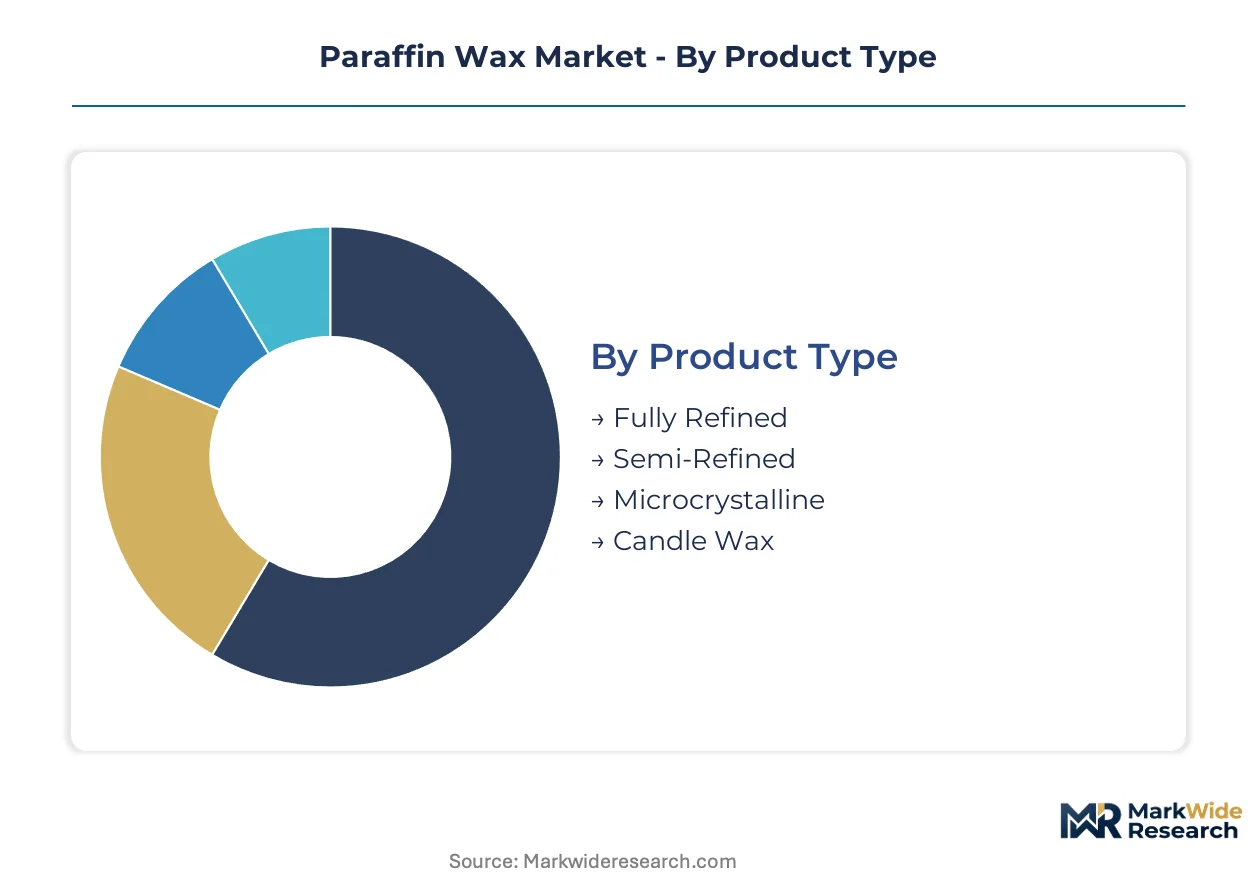
Paraffin wax segmentation reflects divergent purity thresholds across regulatory jurisdictions. FDA and EFSA compliance requirements split procurement channels into certified and uncertified supply pools, reshaping competitive boundaries between grades.
Product Type:
FDA 21 CFR 172.886 and REACH ECHA registration requirements impose distinct purity ceilings that stratify the product landscape into certified and industrial tiers.
- Fully Refined:Hydrotreated to ultra-low aromatic content below 0.5% oil residue and sub-1% UV absorbance thresholds. European coating formulators absorb certified volumes for high-barrier packaging films where EFSA ceilings apply; hydrotreater capex intensity filters out mid-scale competitors from this tier.
- Semi-Refined:Solvent-deoiled to 1-3% oil content without catalytic hydrogenation. China's domestic packaging converters source this grade at scale for flexible film lamination; cost positioning dominates procurement decisions over certification compliance.
- Microcrystalline:Higher-melt-viscosity branched hydrocarbons from dewaxed residual oil. Rubber compounding and adhesive applications demand this niche where standard paraffin lacks sufficient tack and temperature resistance.
- Candle Wax:Blended formulations optimized for burn characteristics and fragrance retention. Southeast Asian manufacturers expand orders for fully refined grades as export markets tighten consumer-goods specifications.
Established volume favors semi-refined grades; emerging adoption favors fully refined certification compliance.
Application:
End-use concentration determines margin recovery potential across coating, consumer, and industrial channels.
- Candles:Mature demand in developed economies faces substitution pressure from soy and palm-derived alternatives in premium segments. Southeast Asian producers drive residual growth through export-oriented manufacturing.
- Coatings:Barrier films and hot-melt adhesives consume paraffin for moisture sealing and gloss control. European formulators pivot toward pharmaceutical-grade streams as REACH tightens import specifications.
- Cosmetics:Topical applications require EFSA-compliant ultra-refined hydrotreated output. This segment commands premium positioning where purity documentation supports brand claims.
- Packaging:Flexible film converters in China absorb semi-refined volumes for cost-sensitive lamination. Direct procurement from Gulf Coast refiners is displacing traditional distributor relationships.
Packaging anchors volume concentration; cosmetics delivers steepest expansion trajectory for certified producers.
End User:
Customer-type differentiation separates compliance-intensive buyers from price-driven industrial accounts.
- Food Industry:Direct and indirect food-contact applications demand FDA 21 CFR 178.3710 compliance with strict oil-content and UV-absorbance documentation. Dual-certification timelines of 18-24 months freeze sourcing flexibility for mid-scale Asian producers.
- Healthcare:Pharmaceutical-grade specifications for ointment bases and coating excipients require continuous catalytic hydrogenation investments that strain balance sheets outside integrated refining.
- Personal Care:Cosmetics and topical formulations follow EFSA purity ceilings. Hydrotreated ultra-refined streams create tiered entry points for producers with validated supply chains.
- Industrial:General manufacturing, rubber compounding, and corrosion protection tolerate higher oil content. This segment competes on delivered cost rather than certification documentation.
Industrial buyers dominate transaction volume; food and healthcare segments concentrate margin capture.
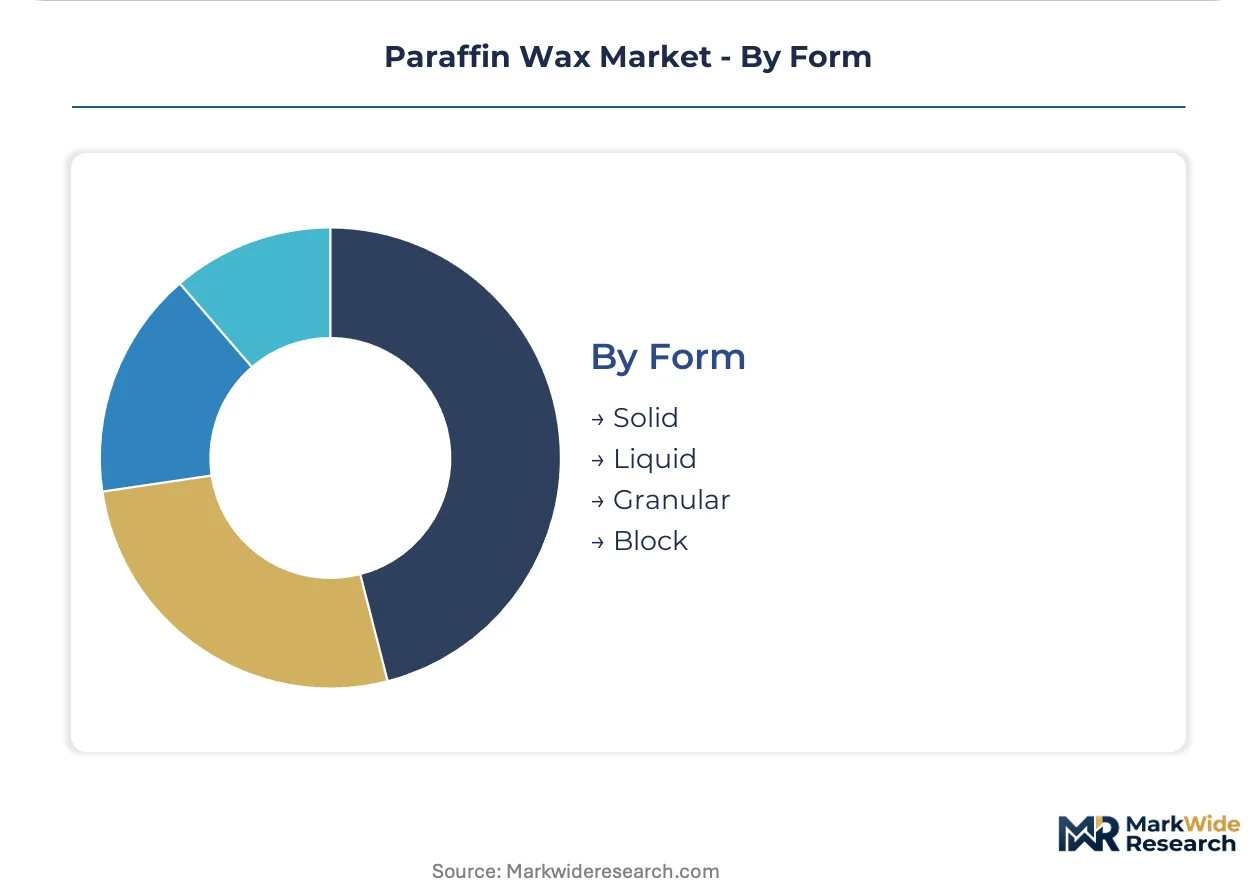
Form:
Physical configuration aligns with processing economics and end-use handling requirements.
- Solid:Slab and bulk forms for high-volume coating and candle manufacturing. Solid delivery minimizes packaging cost for integrated converters with heated storage.
- Liquid:Molten tanker delivery eliminates remelting energy for continuous coating operations. Gulf Coast refiners favor liquid form for direct supply contracts with large Southeast Asian buyers.
- Granular:Free-flowing particles for automated dosing in rubber compounding and hot-melt adhesive production. Granular form reduces handling labor in continuous process lines.
- Block:Molded units for small-batch candle makers and specialty cosmetics formulators. Block configuration supports manual handling where automated systems are uneconomical.
Liquid and solid forms command industrial scale; granular and block configurations serve specialized processing needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refiners in the United States, China, and Saudi Arabia control the bulk of exportable slack wax supply. This geographic clustering shapes procurement patterns for coating formulators and candle manufacturers worldwide. Regional regulatory divergence is fragmenting certification requirements across jurisdictions.
United States
Gulf Coast refining complexes anchor North American paraffin output for coating and packaging channels. EPA fuel-quality standards indirectly constrain slack wax yields by altering refinery processing economics. Houston-area petrochemical corridors supply molten tanker deliveries directly to Southeast Asian converters, bypassing traditional distributor networks.
China
Domestic packaging and coating sectors absorb semi-refined volumes at scale, concentrating regional demand around coastal manufacturing clusters. GB standards for food-contact materials impose purity documentation requirements on local producers. Yangtze River Delta flexible film converters source directly from Sinopec refineries, locking in volume contracts.
Germany
European coating formulators pivot toward pharmaceutical-grade paraffin streams as REACH registration tightens import specifications. ECHA jurisdiction filters lower-purity semi-refined imports from non-EEA sources. Ruhr industrial corridor refiners leverage hydrotreater investments to sustain certified output for high-barrier packaging films.
Saudi Arabia
Middle Eastern integrated refiners export disproportionate shares of global slack wax feedstock. SAMR-equivalent standards in destination markets shape export grade specifications. Eastern Province refining complexes supply volume buyers in Indonesia and Vietnam under direct procurement contracts.
Japan
Specialty cosmetics and pharmaceutical applications demand ultra-refined hydrotreated grades with full EFSA-equivalent documentation. METI industrial standards reinforce purity thresholds for topical and food-contact uses. Kansai region formulators source validated supply chains for ointment bases and coating excipients.
Paraffin Wax Market Vendor Landscape
Concentration sits with integrated petroleum refiners and captive Fischer-Tropsch producers who control upstream feedstock access. Mid-scale hydrotreater operators occupy a squeezed middle tier between certification-intensive premium segments and cost-driven industrial volumes. Two strategic archetypes dominate: integrated majors with refinery-captive supply and synthetic wax specialists with Fischer-Tropsch technology. Competitive moves center on direct procurement relationships with volume buyers and hydrotreater capacity additions for aromatic reduction.
Within the integrated petroleum archetype, ExxonMobil and Sinopec occupy positions reflecting geographic supply dominance. Sasol represents the synthetic Fischer-Tropsch tier with captive feedstock integration. These three anchors exemplify how upstream control over slack wax or synthetic gas-to-liquids feedstock determines competitive positioning across fully refined and semi-refined market tiers.
| Leading Market Players |
|---|
| ExxonMobil |
| Sinopec |
| Sasol |
| Shell |
| PetroChina |
| Petrobras |
| Repsol |
| The International Group |
| NIPPON SEIRO |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Gulf Coast refiners and Southeast Asian candle manufacturers lock in both supply access and price visibility across multi-year horizons, insulating volume buyers from spot volatility while freezing sourcing flexibility under EPA fuel-quality constraints.
Pricing Analysis
FDA 21 CFR 172.886 dictates the pricing tier structure across the paraffin market, separating pharmaceutical-grade hydrotreated streams from standard food-grade and industrial semi-refined volumes. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment, oil-content thresholds, and aromatic specifications. Cost compression in semi-refined grades is intensifying because vegetable wax substitution in premium candles erodes paraffin positioning. Industrial coating buyers exhibit highest price sensitivity, while cosmetics formulators absorbing EFSA-compliant ultra-refined streams show lowest.
Supply Chain Analysis
Middle Eastern slack wax export terminals underwrite global feedstock flows for solvent deoiling and hydrotreating operations. Production concentrates in the United States, China, and Saudi Arabia, with raw material flows drawing from petroleum refining byproducts, Fischer-Tropsch synthetic streams, and dewaxed residual oil stocks. Single-source vulnerability sits with integrated Gulf Coast refiners controlling disproportionate exportable volumes. Distribution runs through direct procurement relationships displacing traditional distributor channels for large Southeast Asian converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paraffin wax market functions as a regulatory-moat business where REACH and FDA compliance entrenchment creates switching costs that freeze out uncertified competitors and anchor margin capture with validated producers.
For Market Incumbents: Fortify hydrotreater capacity positions in the Ruhr and Gulf Coast corridors to sustain pharmaceutical-grade output as ECHA tightens UV absorbance ceilings. Expand direct supply contracts with Indonesian and Vietnamese candle manufacturers before Fischer-Tropsch synthetic wax specialists scale European coating penetration. Certification investment represents the critical defensive lever against vegetable wax substitution in premium consumer segments. For New Entrants and Emerging Players: Differentiate on FDA 21 CFR 178.3710 compliance for direct food-contact applications, a segment where mid-scale Asian producers remain underpenetrated. Target China's Yangtze River Delta flexible film converters with semi-refined volumes undercutting Sinopec spot pricing. Pursue toll-processing arrangements with captive slack wax suppliers rather than greenfield refinery investments. For Investors and Strategic Acquirers: Fischer-Tropsch synthetic wax specialists with validated EFSA supply chains present the most defensible acquisition profile for long-term positioning. Hydrotreater capex intensity and 18-24 month dual-certification timelines erect barriers that protect incumbent returns across a 5-10 year window. Watch for EPA fuel-quality standard revisions that alter slack wax yield structures as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Capacity Expansion | Enables pharmaceutical-grade output for EFSA-compliant European coating formulators. |
| Backward Integration into Slack Wax | Secures feedstock access against EPA yield restructuring and refinery concentration. |
| Long-term Supply Agreement | Locks in volume commitments with Indonesian candle manufacturers bypassing distributors. |
| Joint Venture | Combines Fischer-Tropsch technology with regional packaging converter market access. |
| Green Manufacturing Transition | Positions for vegetable wax hybrid formulations in sustainability-sensitive premium segments. |
Methodological Framework
A spread of perspectives from refinery operations managers, coating formulator procurement leads, candle manufacturer supply planners, and ECHA regulatory consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with downstream technical directors and channel partners, validated against customs trade data, SEC refinery segment disclosures, ACC industry reports, and FDA 21 CFR registration databases. Bottom-up volume modeling from end-use consumption patterns triangulated with top-down refinery capacity assessments.
Segmentation dimensions modeled include purity grade tier, end-use application channel, physical delivery form, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Forecast inputs incorporated EPA fuel-quality standard yield impacts, REACH ECHA registration timelines, and vegetable wax substitution elasticities in premium candle segments.
The analysis sits within stated boundaries; outcomes outside sustained refinery yield restructuring or accelerated REACH enforcement would require recalibration. Forecasts reflect documented assumptions around slack wax availability, hydrotreater commissioning schedules, and certification cost trajectories. Revision becomes warranted when vegetable wax price parity crosses thresholds that trigger rapid substitution in export-oriented Southeast Asian manufacturing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Synthetic Wax Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Ethyl Linalool Market