
 Plastic Compounding Machinery Market | 2026-2036
Plastic Compounding Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Compounding Machinery Market Analytics
Digital twin integration with real-time screw profile optimization is reshaping how compounders achieve batch consistency and energy efficiency. Coperion GmbH leverages its ZSK twin-screw platform to dominate high-throughput engineering polymer applications. KraussMaffei Group anchors its position through integrated compounding and direct extrusion systems that eliminate intermediate pelletizing. The Japan Steel Works, LTD. specializes in large-scale co-rotating extruders for the Asian automotive supply chain.
Plastic compounding machinery encompasses extruders, mixers, and integrated systems that melt, blend, and homogenize polymer resins with additives, fillers, and reinforcements at controlled temperatures typically between 180°C and 350°C and screw speeds up to 1,200 rpm, producing pelletized or directly extruded outputs for downstream manufacturing. Twin-screw extruders command the premium product tier due to their superior dispersive and distributive mixing capability for filled and reinforced compounds. Continuous processing technology leads throughput economics in high-volume automotive and packaging applications, while reactive processing represents the fastest-growing technology segment as compounders pursue in-situ polymerization and grafting reactions to create novel alloy materials without separate reactor investments.
The EPA regulates volatile organic compound emissions from extrusion operations under Clean Air Act standards, while OSHA mandates machine guarding and lockout protocols that influence equipment design and plant layout decisions. REACH and RoHS frameworks in Europe restrict hazardous substance content in compounded plastics, compelling machinery investments that support compliant formulation tracking and rapid recipe changeover. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will reshape capital allocation between equipment efficiency upgrades and alternative material processing capabilities.
Market Dynamics
Automotive lightweighting mandates and EU F-Gas Regulation compliance deadlines are forcing compounders to retire legacy single-screw lines and adopt energy-integrated twin-screw platforms with real-time thermal management.
Growth Catalysts
- REACH and RoHS substance restrictions:European compounders must track hazardous content across formulations, driving machinery investments with embedded spectroscopic verification and automated recipe logging.
- Reactive processing technology:In-situ polymerization eliminates separate reactor capital, allowing mid-scale compounders to produce engineering alloys without chemical plant infrastructure.
- German automotive supply base:BMW, Mercedes-Benz, and Volkswagen tier suppliers concentrate specialized extrusion demand in Baden-Württemberg and Bavaria, anchoring regional machinery deployment.
Market Restraints
- Specialized alloy steel supply:Screws and barrels require nitrided bimetallic grades from a concentrated German and Japanese supplier base, exposing lead times to 14-20 week volatility.
- Clean Air Act VOC thresholds:EPA emission limits on extrusion operations compel fume capture and thermal oxidizer investments that add 15-25% to facility capex budgets.
- Technical limitation in heat-sensitive bio-additives:Natural fiber and starch-based fillers degrade above 200°C, restricting throughput on standard processing platforms designed for 280-320°C engineering polymers.
Strategic Opportunities
- India PLI scheme for automotive:Domestic content requirements for electric vehicle components will localize compounding capacity, creating machinery demand for engineering polymer formulations previously imported from Europe.
- Digital twin convergence with AI-driven screw optimization:Real-time rheological modeling reduces startup scrap rates and energy intensity, compressing payback periods for advanced control system upgrades.
- Extended producer responsibility mandates:Post-consumer recycled content quotas in France, Italy, and Spain require multi-feedstock processing flexibility that favors modular twin-screw configurations with rapid barrel reconfiguration.
Industry Challenges
- Process control engineering talent scarcity:Compounders struggle to hire operators capable of calibrating distributed control systems for reactive extrusion with live viscosity feedback loops.
- CE marking and machinery directive certification timelines:Third-party conformity assessment for safety-integrated extrusion lines extends delivery schedules by 4-7 months, compressing order-to-commission windows.
- Legacy DCS integration friction:Brownfield sites with 1990s-era distributed control architectures face protocol incompatibility when retrofitting IoT-enabled temperature and pressure sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Compounding Machinery Market |
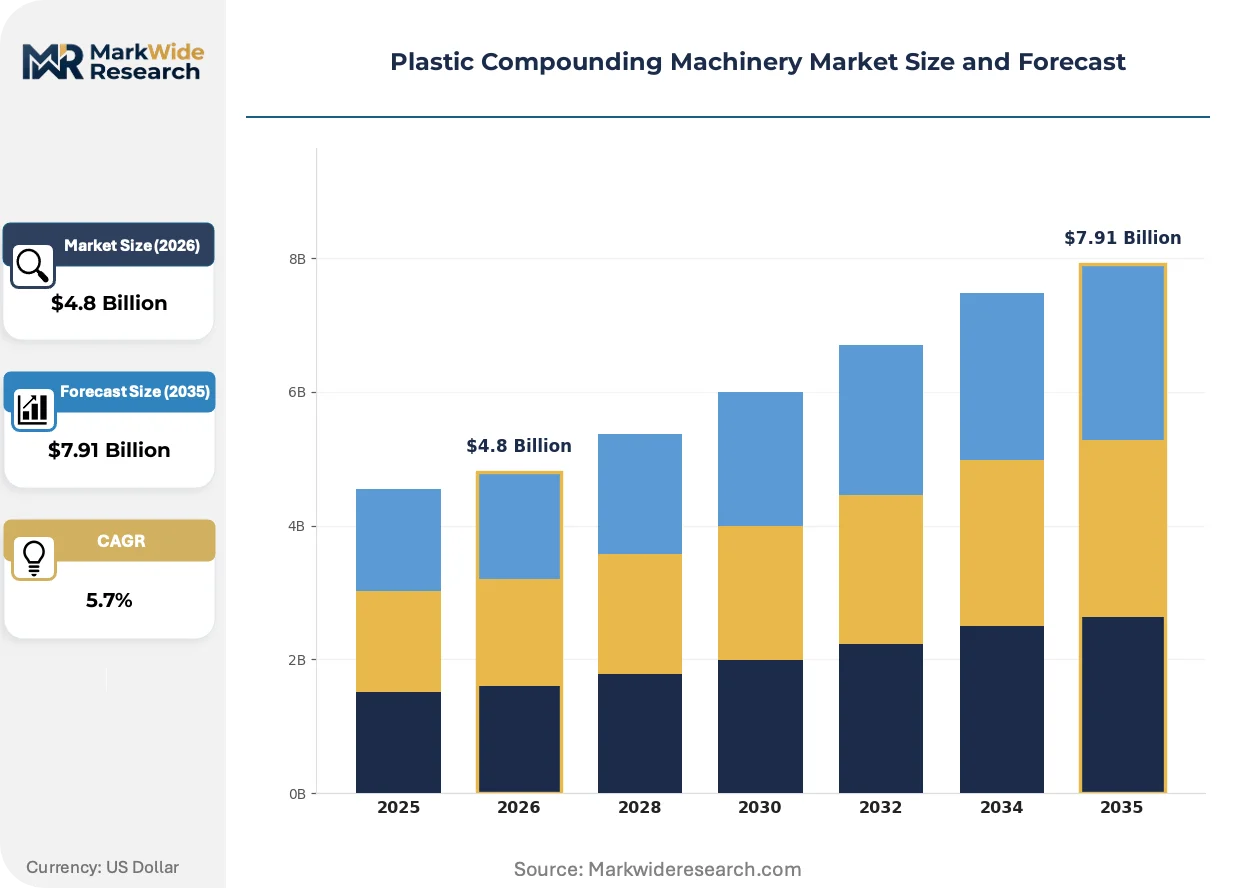
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw Extruders, Twin-Screw Extruders, Batch Mixers, Compounding Systems Technology: Continuous Processing, Batch Processing, Reactive Processing, Melt Blending End User: Automotive, Packaging, Consumer Goods, Electrical & Electronics Application: Film Production, Sheet Extrusion, Rigid Packaging, Compounding |
| Companies Covered | Coperion GmbH, CPM Extrusion Group, Farrel Corporation, ICMA San Giorgio S.p.A., Kobe Steel, Ltd., KraussMaffei Group, The Japan Steel Works, LTD., USEON (Nanjing) Extrusion Machinery Co.,Ltd., Shibaura Machine CO., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Compounding Machinery Market Evolving Landscape
Thermal efficiency imperatives and formulation traceability requirements are accelerating control system architecture replacement cycles. Machinery vendors now embed edge computing nodes directly at barrel zones, enabling localized decision-making without centralized PLC latency.
Real-time screw profile optimization software is digitizing batch consistency protocols across high-throughput automotive compounders. Tier-one suppliers in Germany and the US Midwest deploy these systems to maintain ±0.5% additive dispersion tolerance across 24-hour production runs. The technology is digitizing quality assurance workflows that previously required offline laboratory verification, compressing release-to-ship timelines from hours to minutes.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cooling system redesigns in extrusion temperature control units. Machinery OEMs now specify propane and CO2-based chillers as default configurations for new orders. Southeast Asian export-oriented compounders face the steepest adaptation curve, as their installed base relies heavily on R-134a systems now subject to import quota restrictions.
Automotive procurement departments are consolidating approved machinery vendor lists from 12-15 suppliers to 4-6 strategic partners with full lifecycle service capabilities. Direct extrusion-to-thermoforming integration contracts now specify uptime guarantees rather than equipment specifications alone. This concentration is most visible in Germany, where Volkswagen Group's unified technical standards have eliminated regional machinery specification variance across its 28 component plants.
Plastic Compounding Machinery Market Segmentation
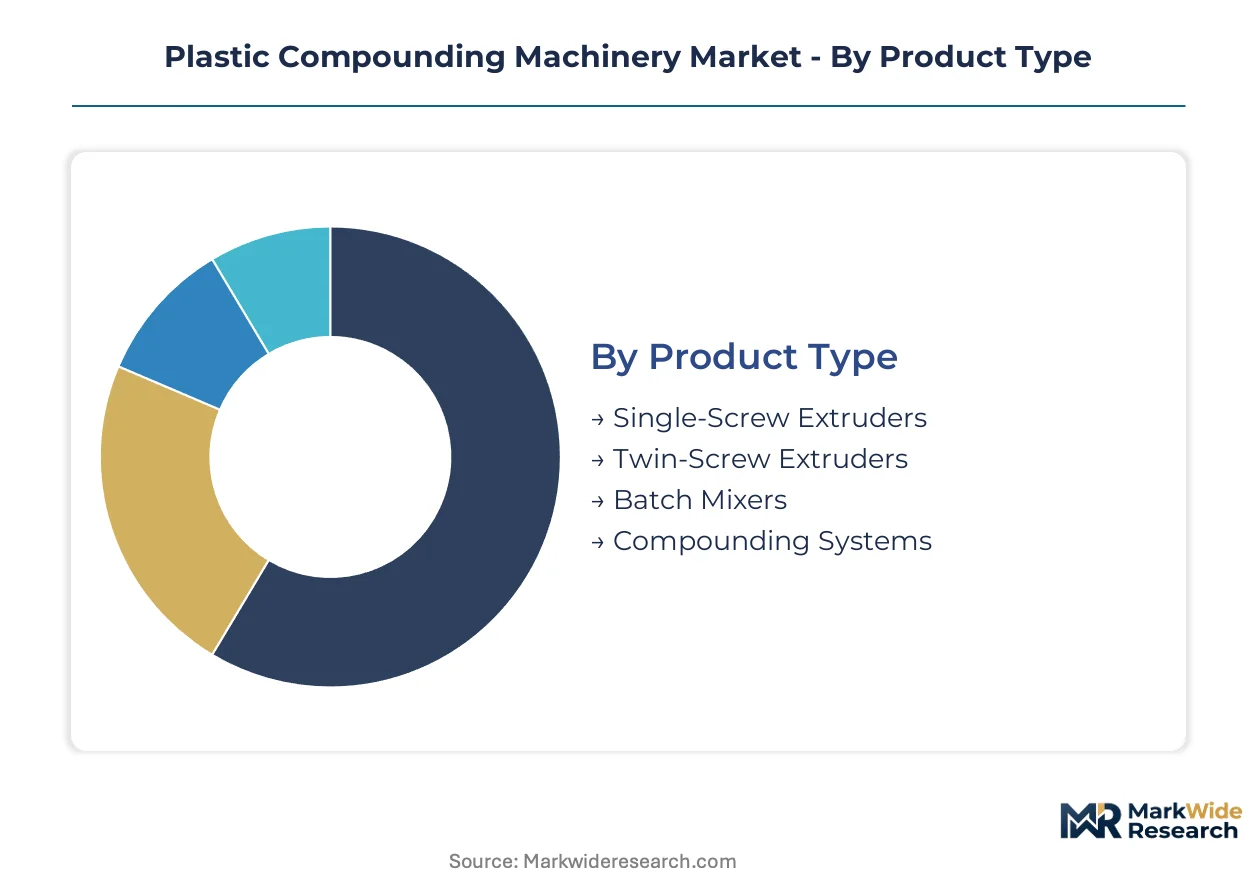
Segmentation in plastic compounding machinery reveals how equipment specifications align with distinct thermal regimes, throughput requirements, and regulatory compliance burdens across manufacturing verticals. Each dimension—product architecture, processing modality, end-use destination, and output format—carries different capital intensity and lifecycle service implications.
Product Type:
Cost tier determines mixing intensity, energy integration, and barrel metallurgy across the installed base.
- Twin-Screw Extruders:Co-rotating intermeshing screws deliver dispersive and distributive mixing at controlled shear rates for highly filled engineering polymers. German automotive compounders in Baden-Württemberg specify these platforms for carbon fiber-reinforced PA6 formulations under EU F-Gas Regulation thermal efficiency mandates.
- Single-Screw Extruders:Simpler solids conveying and melting sections serve low-complexity commodity compounding with lower capital outlay and reduced maintenance intervals. US Gulf Coast polyolefin operations favor these units for high-volume color masterbatch production where additive dispersion tolerance permits broader variance.
- Batch Mixers:Internal mixer configurations with tangential or intermeshing rotors handle specialty rubber and thermoset precursor formulations requiring precise temperature-time profiles.
- Compounding Systems:Integrated upstream feeding, extrusion, and downstream pelletizing or direct forming lines eliminate intermediate handling for automotive tier-one suppliers.
Twin-Screw Extruders hold installed capacity. Compounding Systems are rotating up the share rankings.
Technology:
Processing modality governs residence time distribution, heat history, and the feasibility of in-situ chemical reactions.
- Reactive Processing:Controlled polymerization, grafting, and chain extension within the extruder barrel enables alloy creation without separate reactor vessels. Mid-scale European compounders exploit this capability to produce compatibilized blends for electrical connector housings while avoiding chemical plant licensing.
- Continuous Processing:Steady-state operation at throughputs exceeding 5,000 kg/hour dominates automotive and packaging volume applications where recipe changeover frequency is low. Japanese automotive supply chains standardize on these platforms for just-in-time delivery to assembly plants.
- Batch Processing:Discrete mixing cycles accommodate frequent formulation switches and small lot sizes for specialty medical and aerospace compounds.
- Melt Blending:Physical dispersion of immiscible polymers and additives without chemical reaction serves cost-sensitive commodity applications.
Continuous Processing dominates throughput economics. Reactive Processing is climbing the fastest as compounders seek chemical plant avoidance.
End User:
Customer type dictates specification stringency, certification requirements, and service response time expectations.
- Automotive:Lightweighting mandates for powertrain and interior components drive demand for long-glass-fiber polypropylene and carbon fiber-reinforced compounds. Volkswagen Group's unified technical standards across 28 component plants have consolidated approved machinery vendor lists to strategic partners with full lifecycle capabilities.
- Packaging:High-output lines for multilayer film and rigid container applications prioritize rapid recipe changeover and FDA-compliant contact surfaces. Extended producer responsibility mandates in France, Italy, and Spain are forcing post-consumer recycled content integration.
- Consumer Goods:Aesthetic and tactile requirements for appliances and furniture sustain demand for specialized color and effect masterbatch compounding.
- Electrical & Electronics:Flame retardancy and dielectric property specifications require precise additive incorporation with batch traceability for RoHS compliance.
Automotive holds installed capacity. Packaging is rotating up the share rankings.
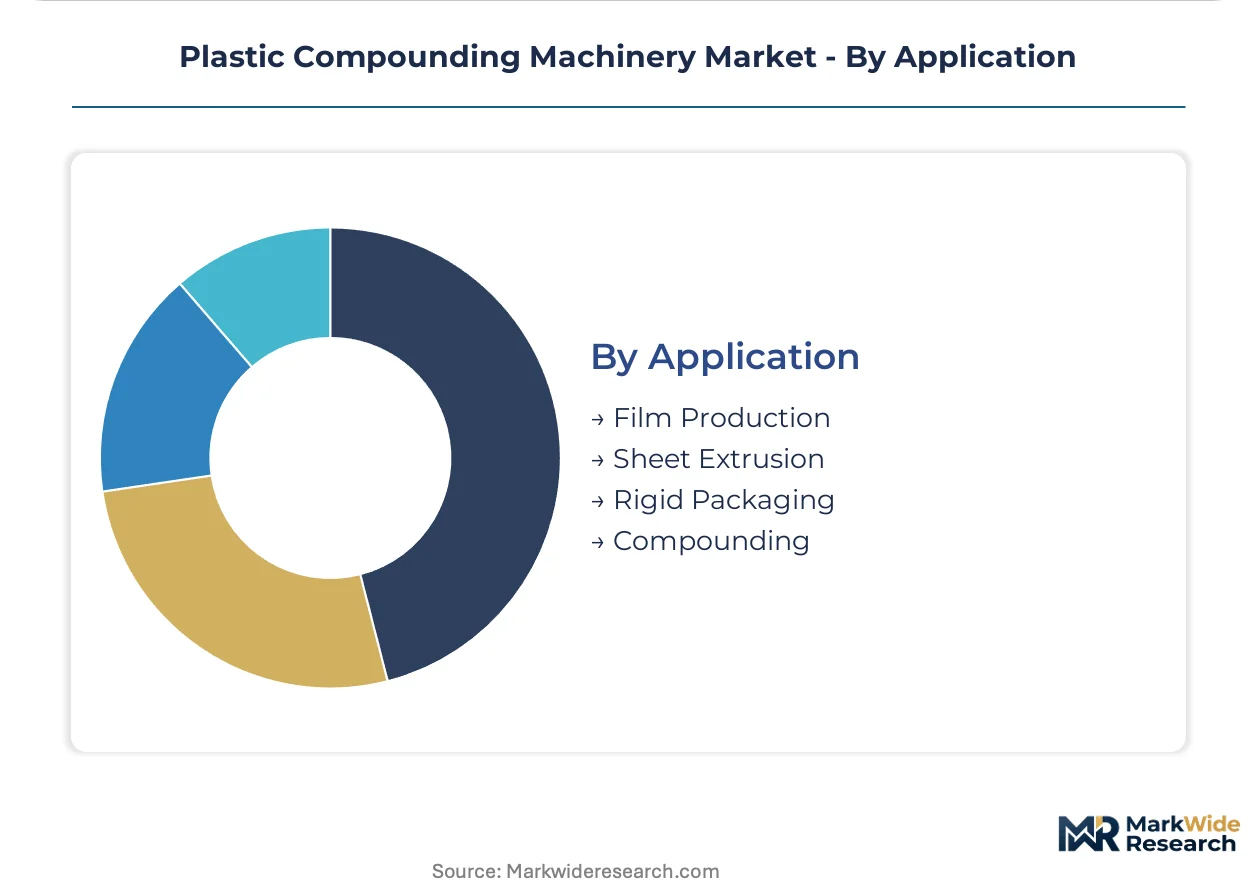
Application:
Output format determines downstream integration depth and whether pelletizing or direct forming delivers superior total cost.
- Compounding:Pellet production for subsequent injection molding or extrusion remains the dominant value capture mode, with quality systems tracking additive dispersion to ±0.5% tolerance. German machinery vendors anchor this segment through integrated process control architectures.
- Sheet Extrusion:Direct calendering or roll-stack forming of compounded melt serves thermoforming feedstock for food packaging and automotive interior panels. US Midwest operations are deploying real-time screw profile optimization to maintain gauge consistency across 24-hour runs.
- Film Production:Blown and cast film lines for flexible packaging require specialized die designs and bubble stability control systems.
- Rigid Packaging:Injection-stretch blow molding and thermoforming feedstock production for bottles and containers demands precise IV control for PET and barrier polymer formulations.
Compounding holds installed capacity. Sheet Extrusion is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive compounders in Germany, tier suppliers in the US Midwest, and export processors in China concentrate machinery procurement decisions across three distinct buyer archetypes with divergent specification stringency.
Germany
BMW, Mercedes-Benz, and Volkswagen tier suppliers drive specialized twin-screw demand for carbon fiber-reinforced PA6 formulations. The EU F-Gas Regulation mandates thermal efficiency upgrades across Baden-Württemberg and Bavaria processing plants. Stuttgart anchors regional machinery deployment through Volkswagen Group's unified technical standards across 28 component plants.
United States
Polyolefin masterbatch producers in the Gulf Coast and automotive compounders in Michigan prioritize high-volume continuous processing lines. EPA Clean Air Act VOC thresholds compel fume capture and thermal oxidizer investments adding 15-25% to facility capex. Detroit-area operations deploy real-time screw profile optimization to maintain gauge consistency across 24-hour production runs.
China
Domestic automotive supply chain localization and packaging export processing sustain machinery demand across Yangtze River Delta manufacturing corridors. The country's dual carbon goals pressure processors toward energy-integrated platforms with real-time thermal management. Shanghai and Jiangsu province house the densest concentration of co-rotating extruder installations serving Asian automotive OEMs.
India
The PLI scheme for automotive components will localize engineering polymer compounding capacity previously imported from Europe. Domestic content requirements for electric vehicle supply chains create machinery demand for formulations meeting REACH-equivalent substance tracking. Maharashtra and Gujarat host emerging processing clusters serving Tata Motors and Mahindra & Mahindra tier networks.
Japan
Precision automotive and electrical connector compounders sustain demand for large-scale co-rotating extruders with tight residence time control. METI efficiency standards and JIS certification requirements shape machinery specification protocols. Nagoya and Osaka industrial corridors concentrate specialized equipment serving Toyota and Honda supply bases.
Plastic Compounding Machinery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor structure anchored by German and Japanese engineering heritage. The installed base concentrates around twin-screw platform specialists with full lifecycle service capabilities and integrated direct extrusion system providers that eliminate intermediate pelletizing. Three archetypes dominate: premium-tier European OEMs with automotive certification depth, mid-scale Asian fabricators with cost-optimized modular configurations, and specialized reactive processing technology licensors. Competitive moves center on digital twin convergence partnerships and strategic consolidation of approved vendor lists by automotive procurement departments.
Within the premium-tier European vector, Coperion GmbH and KraussMaffei Group occupy positions exemplifying integrated process control architectures and direct extrusion-to-thermoforming capabilities respectively. The Japan Steel Works, LTD. anchors the large-scale co-rotating specialization serving Asian automotive supply chains. These three entities represent distinct competitive positioning around mixing intensity, downstream integration depth, and regional market anchoring rather than overlapping product substitution.
| Leading Market Players |
|---|
| Coperion GmbH |
| CPM Extrusion Group |
| Farrel Corporation |
| ICMA San Giorgio S.p.A. |
| Kobe Steel, Ltd. |
| KraussMaffei Group |
| The Japan Steel Works, LTD. |
| USEON (Nanjing) Extrusion Machinery Co.,Ltd. |
| Shibaura Machine CO., LTD |
| Others |
Value Network & Pricing Analysis
The Hamburg-Shanghai container corridor shapes landed cost differentials for nitrided bimetallic screws and barrels, concentrating pricing power among German and Japanese metallurgy suppliers while forcing compounders in Southeast Asia to absorb freight volatility or shift to modular equipment configurations with shorter replacement cycles.
Pricing Analysis
Cost-plus contracts with German specialty steel indexation dominate long-term machinery procurement, with premium twin-screw platforms commanding substantial markups over standard single-screw alternatives based on CE certification depth and embedded spectroscopic verification capabilities. Pricing stratifies across premium, standard, and economy tiers according to thermal efficiency ratings and real-time control architecture sophistication. Cost compression in the mid-tier segment is intensifying because Chinese fabricators are fielding modular co-rotating extruders with competitive throughput specifications. Automotive tier-one suppliers in Baden-Württemberg exhibit the lowest price sensitivity due to unified technical standards mandating lifecycle service capabilities, while Indian packaging processors emerging under PLI scheme localization show acute sensitivity to upfront capital outlay.
Supply Chain Analysis
Upstream polymer resin and specialty alloy feedstock dependencies concentrate manufacturing input costs across Germany, Japan, and China, with nitrided bimetallic grades for screws and barrels drawing from a concentrated metallurgy base in the Ruhr Valley and Osaka industrial corridors. Critical component dependencies include precision gearbox assemblies, thermal oxidizer systems for EPA compliance, and edge computing nodes for barrel zone control. Single-source vulnerability in specialized alloy steel supply exposes machinery OEMs to 14-20 week lead time volatility when German foundry capacity tightens. Distribution runs through direct sales engineering teams for premium automotive accounts and regional distributor networks serving mid-scale packaging compounders in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated direct extrusion-to-thermoforming systems that eliminate pelletizing intermediates and compress total cost for automotive tier suppliers.
For Market Incumbents: Pre-empt margin erosion by securing captive supply of nitrided bimetallic screw metallurgy through backward integration into German or Japanese specialty steel partnerships, while embedding AI-driven screw optimization as standard across all ZSK-class platform configurations to defend against Chinese modular competitors fielding comparable throughput at lower price points. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Gujarat processing clusters serving Tata Motors and Mahindra & Mahindra tier networks, where PLI scheme domestic content requirements are localizing engineering polymer compounding capacity previously imported from Europe and machinery procurement decisions remain less consolidated than in German automotive supply bases. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming extrusion machinery divisions lacking digital twin capabilities or automotive certification depth, with long-term viability hinging on reactive processing technology licensure and service network density rather than pure manufacturing scale; watch for inflection when automotive procurement departments accelerate vendor list consolidation from 12-15 suppliers to 4-6 strategic partners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive metallurgy access insulates against 14-20 week German and Japanese supplier lead time volatility. |
| Digital Twin Platform Deployment | Real-time screw profile optimization reduces startup scrap rates and compresses payback periods for control upgrades. |
| Reactive Processing Technology Licensure | In-situ polymerization capability enables mid-scale compounders to produce engineering alloys without chemical plant infrastructure. |
| CE Marking and Machinery Directive Certification Investment | Accelerated conformity assessment timelines differentiate vendors facing 4-7 month third-party delivery extensions. |
| Extended Producer Responsibility Compliance Integration | Multi-feedstock processing flexibility captures post-consumer recycled content quota mandates in France, Italy, and Spain. |
Research Methodology
A spread of perspectives from extrusion plant managers, automotive tier-one procurement leads, aftermarket service heads, and polymer formulation engineers converged on the working assumptions, with secondary validation drawing from customs and trade data, VDMA machinery production statistics, SEC filings of listed industrial equipment manufacturers, and EPA Clean Air Act enforcement records. Bottom-up capacity installations by country and top-down end-use demand segmentation were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product architecture, processing modality, end-use industry, and output format dimensions. CAGRs were derived from regression analysis of historical capacity deployment against automotive lightweighting mandates and regulatory compliance deadlines, incorporating EU F-Gas Regulation phase-down schedules and India PLI scheme implementation timelines as structural demand shifters.
Sensitivities concentrate around automotive production volatility, specialty alloy steel supply disruptions, and regulatory acceleration of extended producer responsibility schemes. Cross-checking against VDMA order intake statistics and regional machinery production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Neoprene Foam Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
High Speed Dispersers (HSD) Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Saudi Arabia Industrial Insulation Market