
 South America Adhesives and Sealants Market | 2026-2036
South America Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Adhesives and Sealants Market Analytics
Brazil's southeastern manufacturing belt is tilting toward higher-specification adhesive production to serve automotive and electronics clusters. Henkel AG & Co. KGaA leverages its localized compounding facilities to supply reactive polyurethane systems directly to OEM assembly lines. Dow anchors its position through captive silicone production integrated with regional silicone monomer supply. Sika AG specializes in construction-grade epoxy and acrylic formulations for Brazil's infrastructure rehabilitation programs.
Adhesives and sealants comprise formulated polymer systems engineered to bond, seal, or coat substrates through mechanisms including covalent crosslinking, mechanical interlocking, or surface wetting, with viscosities ranging from water-thin cyanoacrylates to thixotropic gap-filling pastes exceeding one million centipoise. Their primary industrial purpose centers on replacing mechanical fasteners, enabling lightweight material joining, and providing environmental barriers against moisture, chemicals, and thermal cycling. Water-based acrylic technology leads volume consumption across South American packaging and construction applications due to lower VOC profiles and simplified handling requirements. Reactive polyurethane and epoxy systems capture disproportionate margin pools in automotive structural bonding and electronics encapsulation where cure speed and thermal stability command price premiums. Hot melt technology sustains growth in corrugated packaging and disposable hygiene assembly driven by high-speed line integration and elimination of solvent drying stages.
ANVISA regulates adhesive compositions intended for medical device or food-contact applications through biocompatibility and migration testing protocols that extend product registration timelines. Brazil's environmental regulator enforces CONAMA resolutions limiting aromatic solvent content in industrial coatings and adhesives, pushing reformulation toward water-based and high-solids alternatives. REACH-equivalent chemical notification requirements under Mercosur frameworks create compliance complexity for imported raw materials. Stakeholders must monitor regulatory divergence between Brazilian state-level environmental enforcement and harmonized Mercosur standards to anticipate reformulation costs and supply chain reconfiguration needs.
Market Dynamics
Brazil's tightening VOC emission framework under CONAMA resolutions is forcing wholesale reformulation of solvent-based adhesive portfolios, compressing margins for imported specialty chemicals while creating localized compounding advantages.
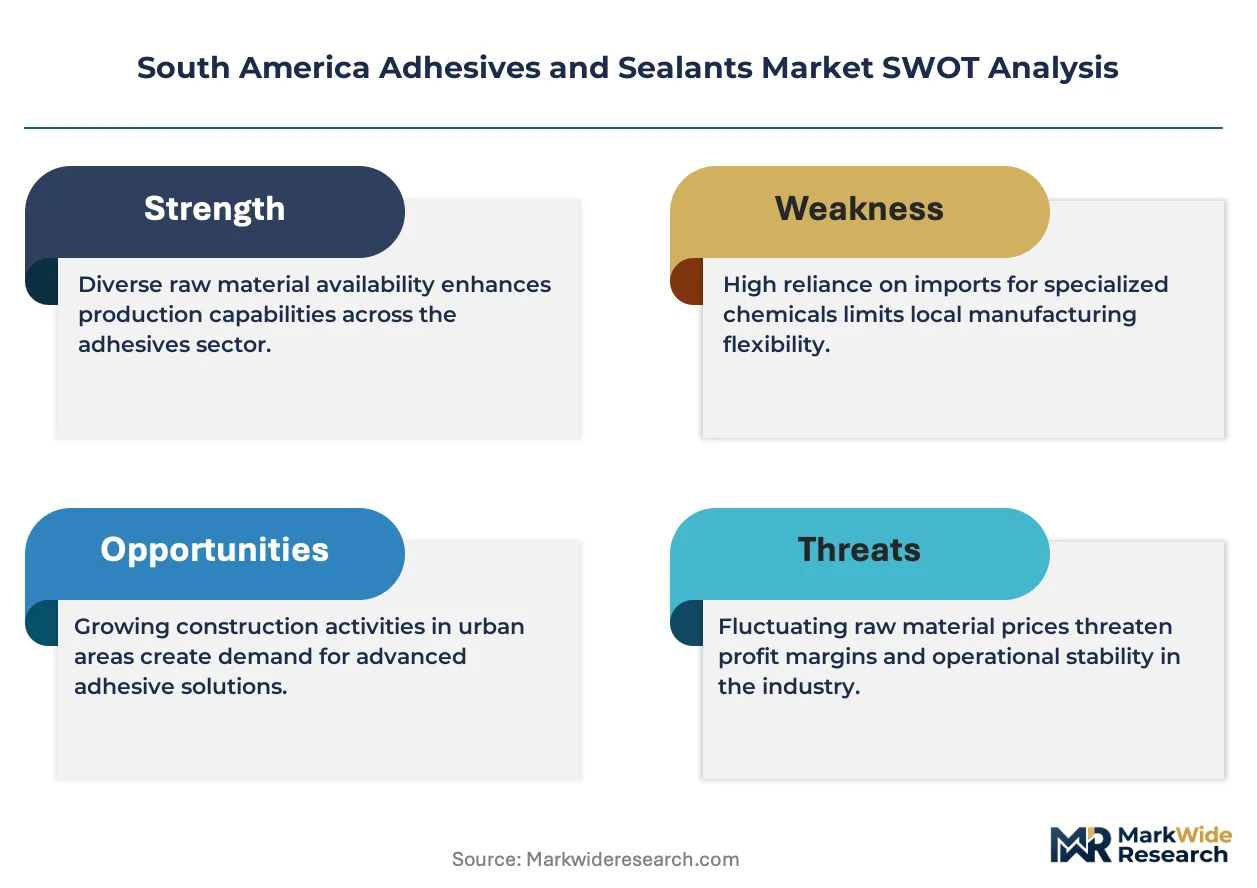
Growth Catalysts
- Automotive lightweighting mandates:Brazilian OEM assembly plants are expanding structural bonding applications to replace mechanical fasteners in mixed-material vehicle platforms.
- ANVISA medical device registration pathways:Biocompatibility-tested adhesive systems for wearable diagnostics and drug-delivery devices command premium positioning in São Paulo's medical manufacturing corridor.
- Water-based acrylic technology maturation:Simplified handling requirements and reduced workplace exposure liabilities accelerate adoption across corrugated packaging and construction assembly lines.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with international crude pricing, compressing margin visibility for polyurethane system suppliers.
- Silicone monomer supply concentration:Regional silicone precursor production clusters in Argentina and southern Brazil create geographic dependency risks for sealant formulators.
- Cure-speed limitations of water-based systems:Extended drying cycles restrict water-acrylic technology from high-speed automotive assembly applications where reactive polyurethane dominates.
Strategic Opportunities
- Colombian Andean infrastructure corridor:Tunnel rehabilitation and hydroelectric projects generate demand for high-performance epoxy injection systems and flexible joint sealants.
- Chilean lithium battery gigafactory cluster:Thermal management and cell-to-pack bonding applications require specialized thermally conductive adhesives with dielectric stability.
- Mercosur REACH-equivalent harmonization:Unified chemical notification frameworks reduce compliance fragmentation for regional raw material sourcing.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in reactive hot-melt and UV-cure systems concentrates among retiring technical specialists in São Paulo's industrial belt.
- ANVISA registration timeline compression:Extended biocompatibility testing protocols for food-contact adhesives delay product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Adhesives and Sealants Market |
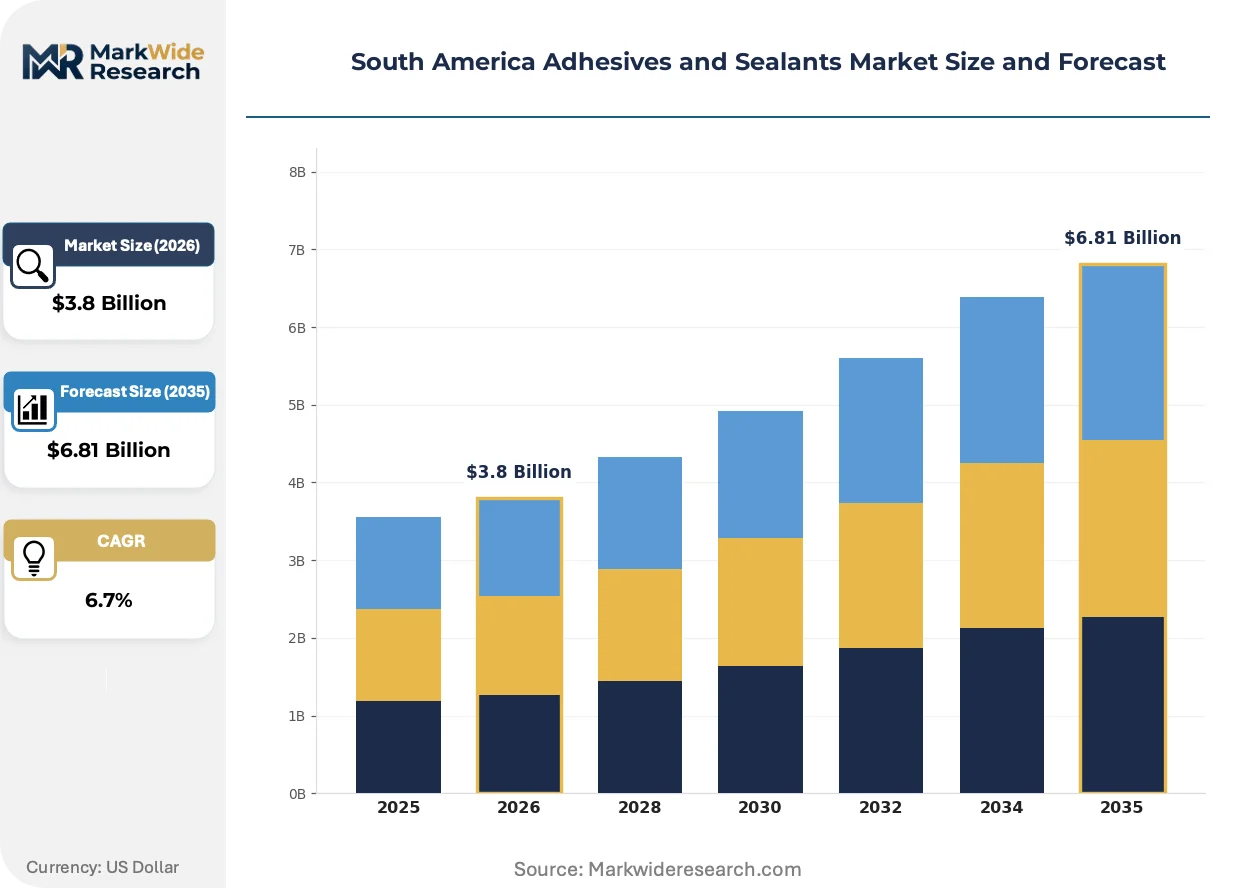
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Construction, Automotive, Electronics, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | H.B. Fuller Company, Huntsman International LLC, Henkel AG & Co. KGaA, Wacker Chemie AG, Dow, 3M, Arkema, Parker Hannifin Corp, Sika AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Adhesives and Sealants Market Evolving Landscape
Reactive curing technologies and bio-based feedstocks are compressing traditional formulation paradigms across South American adhesive manufacturing, with regulatory chemistry restrictions accelerating substitution timelines.
UV-LED curable acrylate systems are penetrating electronics assembly and medical device bonding applications where thermal curing damages heat-sensitive substrates. Brazilian contract manufacturers serving consumer electronics OEMs are retrofitting dispensing lines to accommodate 395-nm wavelength curing stations. Solvent-based drying ovens and thermal cure infrastructure is rendering obsolete in greenfield facility investments.
CONAMA Resolution 491 and subsequent state-level environmental enforcement in São Paulo and Minas Gerais are mandating aromatic solvent reductions in industrial adhesive formulations. Formulators are accelerating water-based and high-solids polyurethane development to maintain product registration validity. Construction-grade sealant portfolios face the most immediate compliance pressure due to volume-scale environmental exposure.
Direct technical service engagement is displacing traditional distributor-led specification selling in automotive and electronics verticals. Henkel and Dow have established embedded application engineering teams at major OEM assembly plants in São Paulo's ABC industrial region. Chilean mining equipment manufacturers and Colombian infrastructure contractors now expect formulation customization support as a standard procurement condition.
South America Adhesives and Sealants Market Segmentation
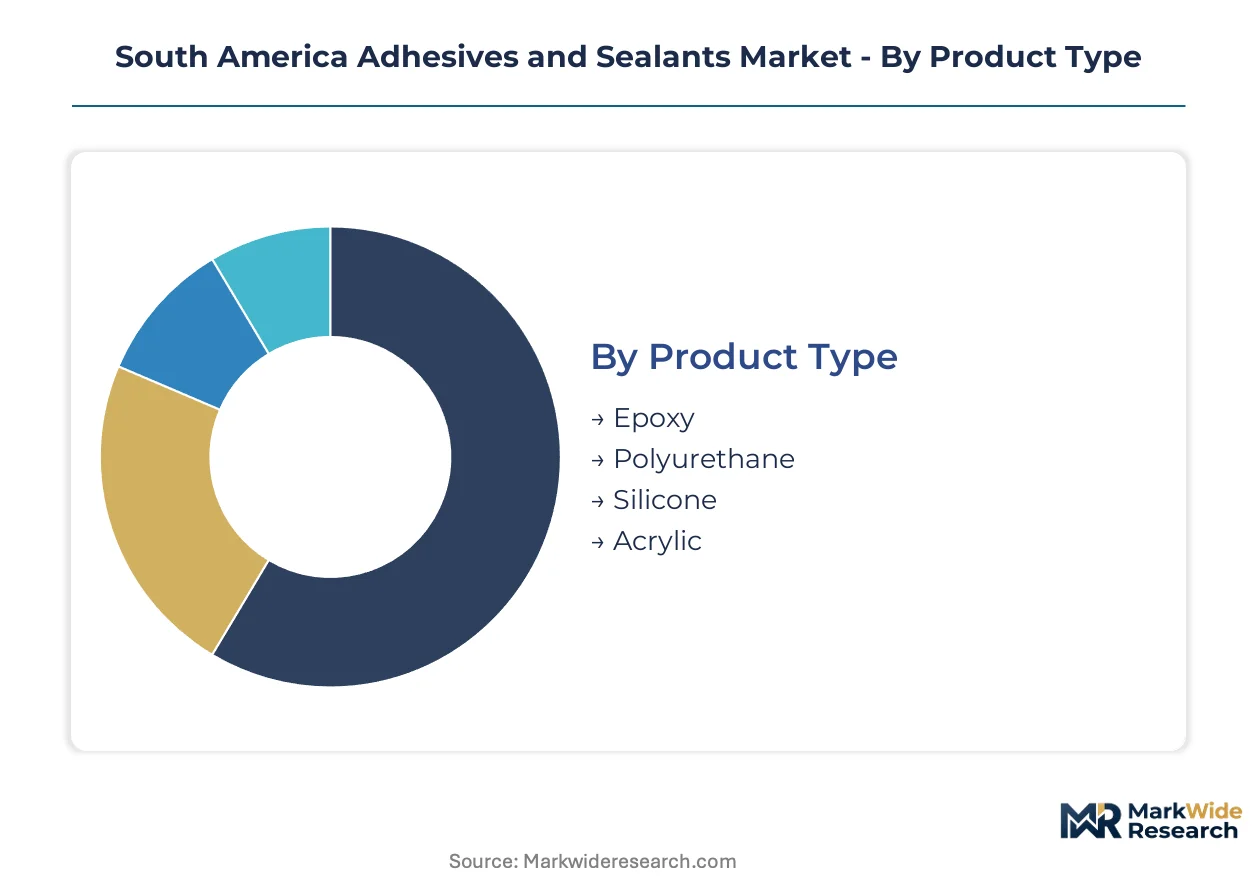
Adhesives and sealants in South America exhibit divergent performance profiles across chemistry platforms and application verticals. Segmentation reveals how formulation technology and end-use specifications dictate procurement patterns, margin structures, and regulatory exposure across Brazil's industrial corridor and Andean markets.
Product Type:
Polyurethane and silicone formulations sit at opposite ends of the maturity spectrum—one entrenched in automotive structural bonding, the other expanding through infrastructure weatherproofing demands.
- Epoxy:Two-part thermosetting systems delivering high shear strength and chemical resistance. Demand concentrates in São Paulo's industrial belt for concrete repair and composite manufacturing, with ANVISA registration requirements extending commercialization timelines for food-contact variants.
- Polyurethane:Reactive systems forming durable elastomeric bonds through isocyanate-polyol chemistry. Brazilian OEM assembly plants in Minas Gerais specify these for mixed-material vehicle platforms where mechanical fasteners add weight.
- Silicone:Siloxane-based sealants with superior UV stability and temperature cycling resistance. Argentine monomer supply clusters feed formulators serving Chilean mining infrastructure and Colombian tunnel rehabilitation projects.
- Acrylic:Water-dispersed or solvent-borne systems offering rapid tack and cost-efficient bonding. Packaging converters across Brazil's southeastern states favor these for corrugated board assembly under tightening CONAMA VOC limits.
Acrylic retains volume leadership; polyurethane holds the steepest expansion curve.
Application:
Application segmentation tracks capital expenditure cycles—construction and automotive absorb bulk volume, while electronics and packaging respond to consumer demand shifts and e-commerce logistics scaling.
- Construction:Structural adhesives and joint sealants for commercial building envelopes, bridge rehabilitation, and waterproofing membranes. Colombian Andean infrastructure corridors and Brazilian federal housing programs sustain procurement volumes.
- Automotive:Structural bonding for lightweighting initiatives, NVH damping, and direct glazing applications. OEM plants in São Paulo's ABC region specify reactive systems that cure within paint shop thermal cycles.
- Electronics:Die attach compounds, thermal interface materials, and display bonding for consumer device assembly. Chilean lithium battery gigafactories are emerging as a specialized demand node for thermally conductive formulations.
- Packaging:Case and carton sealing, label adhesives, and flexible lamination for food and consumer goods. High-speed corrugated lines in Brazil's interior states favor hot melt systems over water-based alternatives for throughput.
Construction absorbs the highest absolute volume; electronics is climbing the fastest as regional device manufacturing scales.
End User:
End user categories reflect supply chain position—manufacturers and contractors drive specification, while distributors and retailers handle fragmented downstream fulfillment.
- Manufacturers:Industrial entities integrating adhesives into production processes. Automotive OEMs and electronics contract manufacturers in São Paulo demand embedded technical service and formulation customization.
- Contractors:Construction and infrastructure specialists applying sealants in field conditions. Colombian tunnel rehabilitation and Chilean mining projects require on-site application engineering support.
- Retailers:Hardware and home improvement channels serving maintenance, repair, and consumer DIY segments. Brazilian retail chains stock water-based acrylics for interior finishing applications.
- Distributors:Intermediaries aggregating SKU breadth for regional industrial supply. Distributor-led specification selling is yielding to direct manufacturer engagement in automotive and electronics verticals.
Manufacturers command the steepest expansion trajectory; distributors retain the broadest SKU coverage.
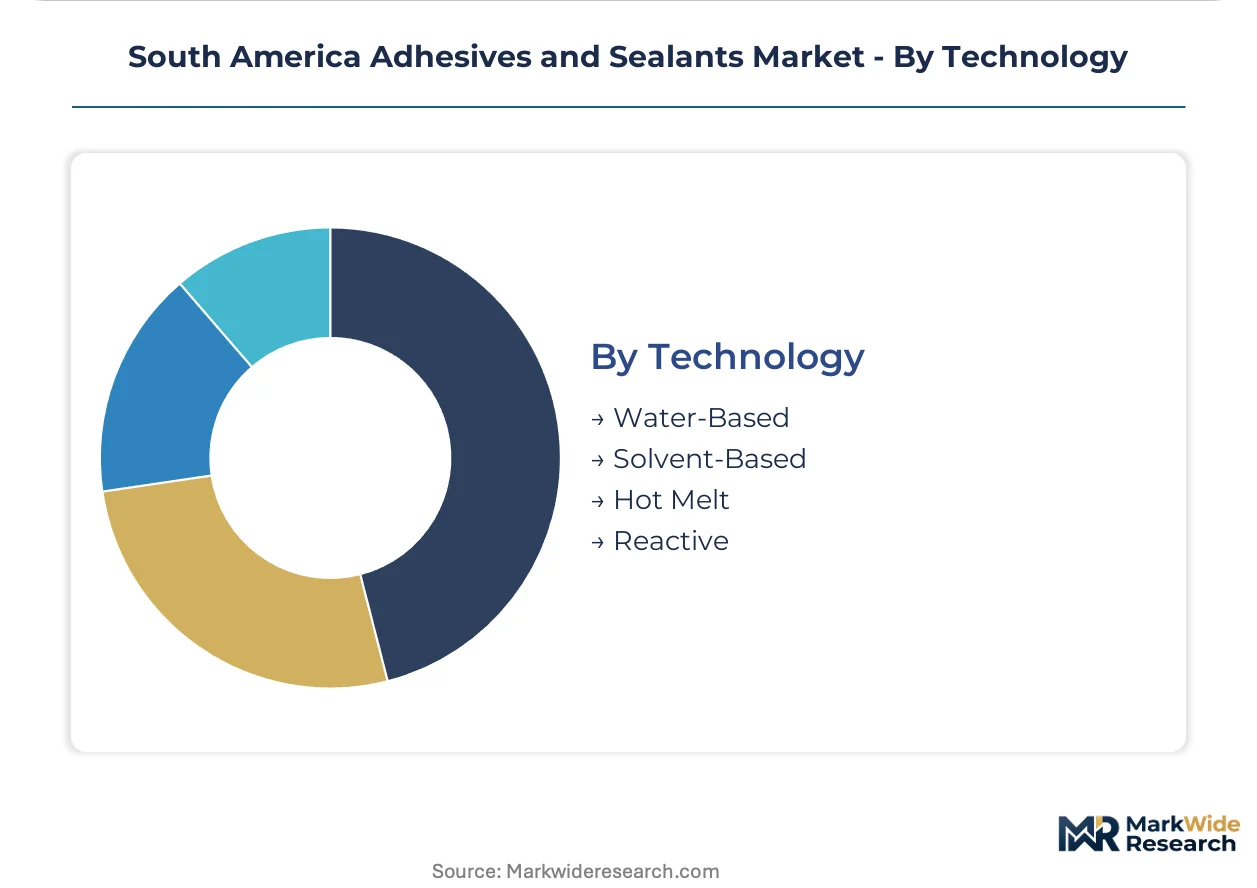
Technology:
Technology segmentation tracks regulatory chemistry evolution—water-based and reactive systems gain share as solvent-based portfolios face reformulation pressure under CONAMA resolutions.
- Water-Based:Acrylic and polyurethane dispersions using water as primary carrier. Brazilian packaging and construction sectors favor these for reduced workplace exposure and simplified handling, though extended drying cycles limit automotive adoption.
- Solvent-Based:Systems employing aromatic or aliphatic hydrocarbons for rapid drying and substrate wetting. ANVISA and state-level environmental enforcement in São Paulo and Minas Gerais are compressing permissible formulations.
- Hot Melt:Thermoplastic adhesives applied molten and solidifying on cooling. Corrugated packaging lines across Brazil's interior favor these for elimination of drying stages and high-speed integration.
- Reactive:Chemically curing systems including two-part epoxies, polyurethanes, and UV-acrylates. Automotive structural bonding and electronics encapsulation in São Paulo's manufacturing belt specify these for thermal stability and cure speed.
Water-based technology retains volume leadership; reactive systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paranaguá Container Terminal anchors Brazil's adhesive import corridor, channeling polyurethane raw materials from Argentine petrochemical clusters into São Paulo's manufacturing belt.
Brazil
Automotive OEM assembly plants in Minas Gerais specify reactive polyurethane systems for mixed-material vehicle platforms. ANVISA's biocompatibility testing protocols extend registration timelines for food-contact adhesive variants by 18-24 months. São Paulo's ABC industrial region concentrates embedded application engineering teams from multinational suppliers serving electronics contract manufacturers.
Argentina
Silicone monomer production clusters in southern Buenos Aires province supply sealant formulators across the Southern Cone. The country's national chemical regulator enforces Mercosur-aligned REACH-equivalent notification requirements for imported raw materials. Córdoba's automotive component plants consume increasing volumes of hot melt adhesives for interior trim assembly.
Chile
Lithium battery gigafactories in the Atacama Desert corridor generate specialized demand for thermally conductive adhesives with dielectric stability. The national environmental regulator enforces strict VOC limits on industrial coating and adhesive operations. Santiago's mining equipment manufacturers now expect formulation customization support as standard procurement conditions.
Colombia
Tunnel rehabilitation and hydroelectric projects along the Andean infrastructure corridor absorb high-performance epoxy injection systems. The national infrastructure agency prioritizes flexible joint sealants for seismic-resistant construction standards. Bogotá's construction contractors source directly from Brazilian formulators to bypass distributor markups on critical infrastructure materials.
South America Adhesives and Sealants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying differentiated chemistries. The vendor base stratifies across three tiers: multinational compounders with localized production assets, regional distributors aggregating SKU breadth, and niche formulators serving single-vertical specifications. Two strategic archetypes dominate: captive silicone producers leveraging backward integration into monomer supply, and reactive system houses embedding technical service at OEM assembly lines. Capacity expansion and direct technical service engagement constitute the dominant competitive moves, displacing traditional distributor-led specification selling.
Among Germany-based chemical conglomerates, Henkel AG & Co. KGaA and Wacker Chemie AG exemplify contrasting archetypes—one representing formulation-to-application integration, the other anchoring upstream material science capabilities. Dow occupies a position bridging both tiers through captive regional production. These three entities collectively illustrate how geographic proximity to Brazilian automotive and electronics clusters determines competitive positioning.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Huntsman International LLC |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| Dow |
| 3M |
| Arkema |
| Parker Hannifin Corp |
| Sika AG |
| Others |
Value Network & Pricing Analysis
The Paranaguá Container Terminal's freight cost dynamics amplify supply concentration effects across Brazilian adhesive markets, compressing margins for imported specialty chemicals while rewarding localized compounding operations with pricing power over solvent-reformulated portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-registered medical-grade formulations from industrial construction adhesives and commodity packaging hot melts. Price differentiation hinges on certification tier and volume scale, with biocompatibility-tested systems commanding substantial premiums over CONAMA-compliant construction variants. Pricing pressure stems from petrochemical feedstock volatility eroding polyurethane system margins. Small-scale distributors exhibit highest price sensitivity; automotive OEMs prioritize technical service over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced silicone monomer technologies limit flow diversification from Argentine production clusters into Brazilian sealant formulators. Geographic supply concentration centers on Argentina, southern Brazil, and imported Asian petrochemicals. Raw material dependencies include silicone precursors, aromatic polyols, and isocyanate intermediates. Single-source vulnerability from Argentine monomer clusters threatens regional sealant capacity. Distribution runs through Paranaguá port logistics into São Paulo's ABC industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to Brazilian automotive production cycles, where OEM assembly plant utilization rates dictate adhesive procurement intensity across reactive polyurethane and hot melt categories.
For Market Incumbents: Pre-empt margin erosion from water-based reformulation mandates by deepening captive silicone production assets in southern Brazil. Consolidate technical service teams at São Paulo electronics contract manufacturers before distributor-led specification selling disappears entirely. Lock in long-term polyol supply agreements to buffer crude-linked input cost volatility.
For New Entrants and Emerging Players: Establish a beachhead in Colombian tunnel rehabilitation epoxy systems where Brazilian formulator presence remains thin and infrastructure spending accelerates. Target Chilean lithium battery thermal interface materials as the most penetrable specialized segment. Pursue direct contractor engagement models bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Regional formulators with ANVISA-registered medical adhesive portfolios and embedded OEM technical service contracts represent the most defensible acquisition archetype. Long-term viability over the next decade rests on regulatory chemistry adaptation capabilities rather than commodity scale. Monitor CONAMA resolution enforcement intensity as the critical inflection signal for reformulation cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer Production | Captive Argentine supply clusters insulate formulators from export-control disruptions and raw material cost spikes. |
| ANVISA Registration Investment | Biocompatibility certification opens premium medical device bonding segments with extended commercialization timelines. |
| Embedded Technical Service Deployment | Application engineering teams at São Paulo OEM plants displace distributor-led specification selling permanently. |
| Water-Based Portfolio Reformulation | CONAMA compliance maintains product registration validity under tightening São Paulo and Minas Gais enforcement. |
| Andean Infrastructure Corridor Partnership | Direct engagement with Colombian tunnel contractors captures high-performance epoxy injection system demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with adhesive formulating plant managers, automotive OEM procurement leads, construction contractor technical directors, and ANVISA regulatory affairs specialists. Secondary validation drew from Brazilian customs trade data, CONAMA resolution filings, SEC 10-K chemical segment disclosures, and Argentine petrochemical export statistics. Bottom-up volume triangulation across end-use applications was cross-checked against top-down petrochemical feedstock consumption estimates.
Calibration of projection models applied scenario-weighted growth assumptions across the analysis window, with segmentation dimensions spanning chemistry platform, technology type, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting penetration rates and infrastructure spending cycles. Industry-specific forecast inputs included polyurethane system cure-speed specifications and silicone sealant UV-stability performance thresholds.
Stress conditions across crude oil price bands, ANVISA registration timeline extensions, and Mercosur harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM platform engineering decisions. Material shifts in CONAMA resolution implementation or Brazilian automotive production allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market