
 High Pressure Braided Tubing (HPBT) Market | 2026-2036
High Pressure Braided Tubing (HPBT) Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Braided Tubing (HPBT) Market Insights
Modular catheter-tubing bundles is realigning procurement patterns across cardiovascular and endoscopy OEMs. Saint-Gobain leverages its fluoropolymer compounding depth to anchor premium HPBT supply to European device makers. Zeus Company specializes in tight-tolerance extrusion for neurovascular applications, while Freudenberg Medical competes through integrated cleanroom manufacturing across multiple continents.
High Pressure Braided Tubing consists of an inner polymer liner, a wire or textile reinforcement braid, and an outer jacket extruded to withstand operating pressures typically exceeding 1,000 psi without catastrophic failure. Polyurethane formulations dominate medical-grade HPBT due to kink resistance and biocompatibility, though nylon commands aerospace hydraulic lines where chemical resistance outweighs flexibility needs. Small-bore diameters lead absolute volume in interventional cardiology, while ultra-high-pressure configurations represent the fastest-expanding margin pool as downhole oil tools and aircraft hydraulics push material limits.
FDA 21 CFR Part 820 quality-system requirements and EU MDR technical-documentation standards shape product-development timelines and market-access costs for HPBT suppliers serving regulated industries. ISO 13485 certification functions as a baseline qualifier for medical tubing vendors, with notified-body scrutiny intensifying for permanent implant contact applications. Stakeholders must monitor how REACH chemical restrictions and evolving EPA per- and polyfluoroalkyl substance rules alter polymer feedstock availability and reformulation costs.
Market Dynamics
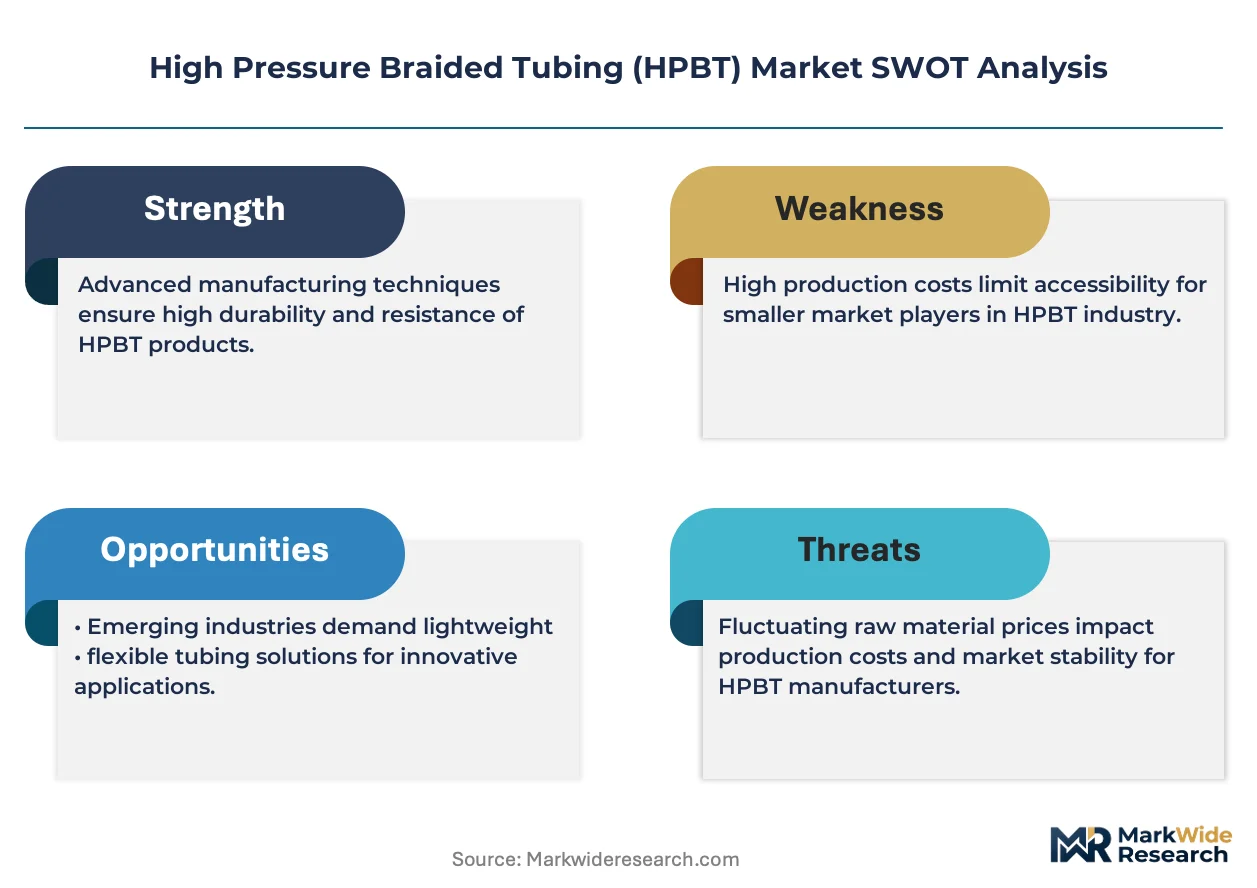
Modular catheter-tubing bundles are restructuring procurement economics across cardiovascular and endoscopy OEMs, compressing supplier margins while elevating technical qualification thresholds for braided reinforcement vendors.
Growth Catalysts
- EU MDR material-traceability mandates:Device manufacturers must document polymer feedstock origins through finished-goods distribution, creating qualified-supplier scarcity that rewards compliant HPBT vendors with multi-year contracts.
- Catheter-based intervention volume:Structural heart and peripheral vascular procedures are expanding addressable demand for small-bore braided lumens in interventional suites across tertiary hospitals.
- Polyurethane compounding advances:Enhanced kink resistance and burst-pressure ratings in thermoplastic polyurethane formulations are extending HPBT service life in dynamic bending applications.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE and FEP resin supply concentrates among three global chemical producers, exposing tubing extruders to allocation risk during semiconductor-sector demand spikes.
- Notified-body backlog under EU MDR:Technical documentation review timelines for permanent implant contact applications now stretch 18-24 months, freezing new product introductions.
- Metal-braid substitution in aerospace:Titanium and stainless-steel hardlines retain preference in ultra-high-pressure hydraulic circuits above 5,000 psi, capping HPBT penetration in defense aviation.
Strategic Opportunities
- India medical device PLI scheme:Production-linked incentives for domestic catheter manufacturing are attracting HPBT suppliers to establish compounding and extrusion capacity near Mumbai and Hyderabad clusters.
- Downhole oil-tool pressure ratings:Exploration operators are specifying 10,000-plus psi braided configurations for MWD and LWD telemetry strings, opening margin-rich engineering-service contracts.
- Cleanroom-as-a-service models:Contract manufacturers in Costa Rica and Malaysia now offer integrated braiding, extrusion, and terminal sterilization, reducing OEM capital intensity.
Industry Challenges
- Multi-lumen co-extrusion expertise:The convergence of braid architecture with thin-wall liner co-extrusion requires process engineers with 10-plus years of medical-tubing experience, a scarce profile in emerging manufacturing hubs.
- ISO 13485 certification maintenance:Surveillance audits demand continuous CAPA documentation and supplier quality agreements that consume 15-20 percent of quality-assurance headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Braided Tubing (HPBT) Market |
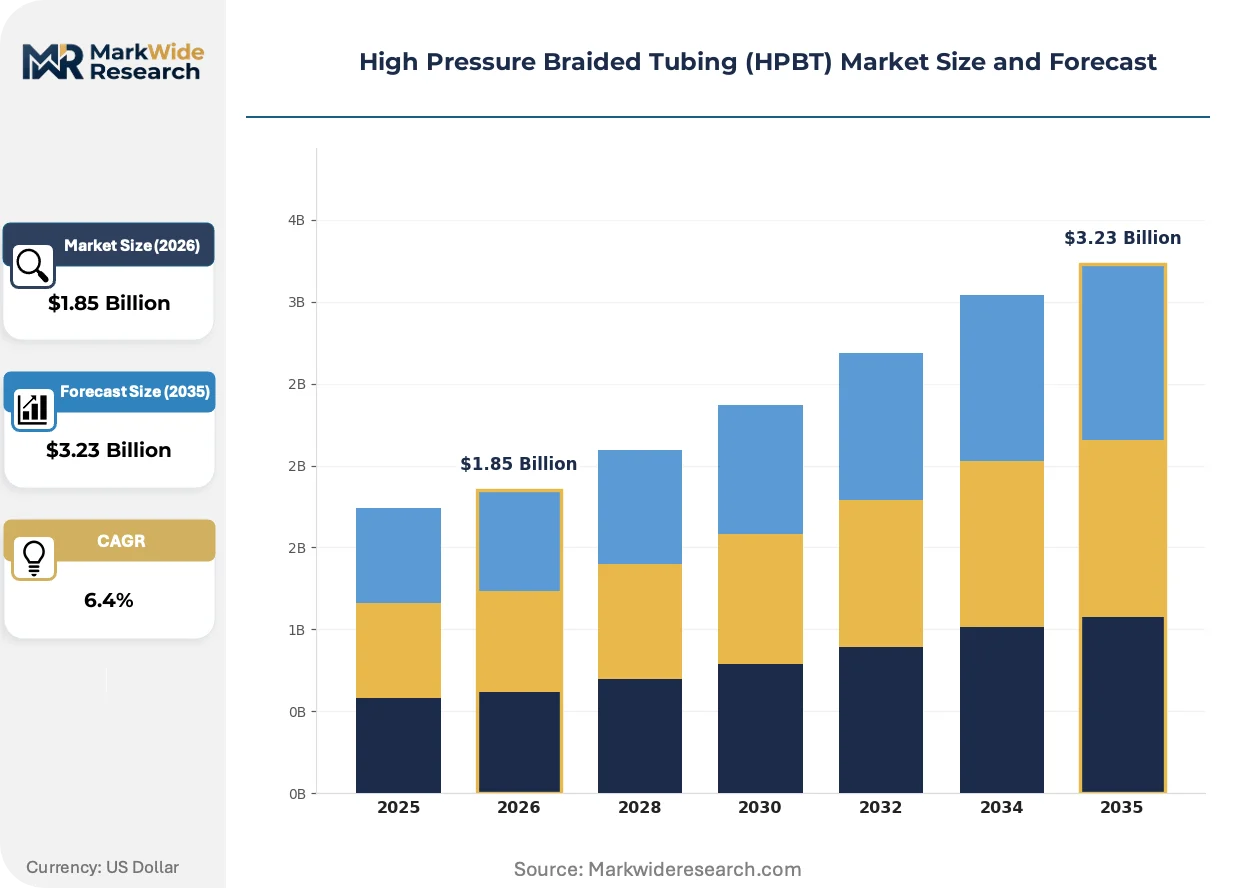
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, Nylon, PVC, Rubber Application: Aerospace, Automotive, Oil & Gas, Industrial Equipment End User: Manufacturing, Transportation, Construction, Healthcare Diameter: Small Bore, Medium Bore, Large Bore, Ultra High Pressure |
| Companies Covered | Spectrum Plastics Group, Nordson Medical, Saint-Gobain, RAUMEDIC, Freudenberg Medical, Zeus Company, Biomerics, VistaMed, CVP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Braided Tubing (HPBT) Market Trends and Innovations
Digital thread technologies and predictive burst-testing protocols are compressing product-development cycles while elevating performance-validation standards across medical and industrial HPBT applications.
Laser-welded braid terminations are decentralizing supply chain risk by enabling localized jacket-bonding operations without centralized crimping equipment. Neurovascular device manufacturers in Minnesota and Bavaria are adopting this capability to qualify secondary suppliers within 90-day windows rather than 12-month legacy timelines. The technology is decentralizing geographic dependency on single-source finishing houses.
EPA per- and polyfluoroalkyl substance rules are forcing reformulation of PTFE-lined HPBT toward perfluoroalkoxy alkane and modified ethylene-tetrafluoroethylene alternatives. Compounders face 18-24 month validation cycles with device OEMs, slowing new product ramps. Cardiac catheter applications with permanent implant contact face the steepest compliance cost escalation.
Hospital procurement consortia are consolidating tubing and component purchasing through single-source agreements that bundle HPBT with molded connectors and sterilization services. Original equipment manufacturers respond by acquiring captive braiding capacity or exclusive toll-manufacturing arrangements. This consolidation is most visible in Germany, where university hospital purchasing alliances now represent 40 percent of cardiovascular device procurement volume.
High Pressure Braided Tubing (HPBT) Market Segmentation
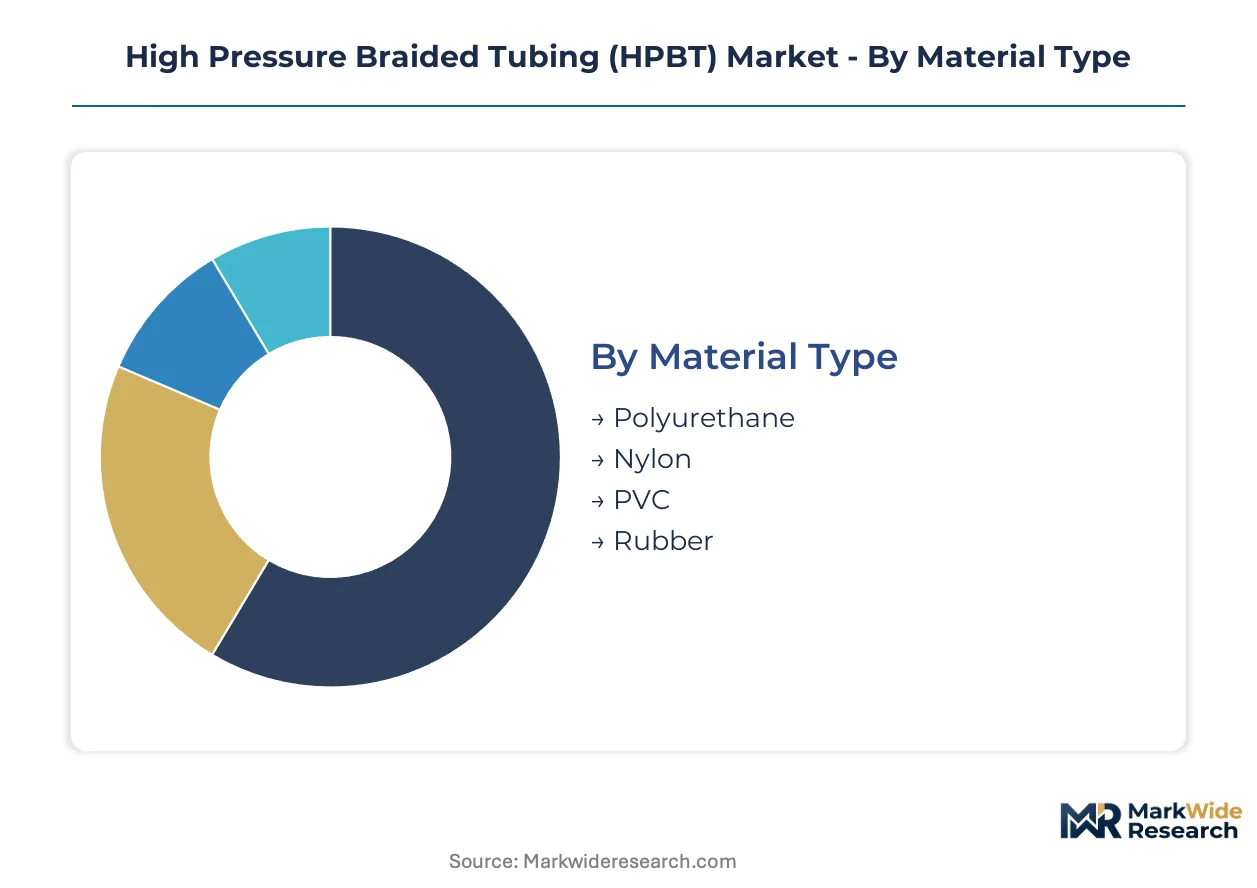
HPBT segmentation reflects divergent capital requirements across material compounding, precision extrusion, and regulatory qualification layers. Procurement decisions by cardiovascular OEMs and aerospace hydraulic systems engineers drive tiered pricing and supplier selection criteria.
Material Type:
Polyurethane compounding demands the heaviest upfront investment in medical-grade cleanrooms and FDA-validated batch records.
- Polyurethane:Thermoplastic formulations dominate catheter-based interventions due to kink resistance and biocompatibility. Minnesota and Bavaria device clusters source tight-tolerance extrusions for neurovascular applications.
- Nylon:Semicrystalline polyamides withstand hydraulic fluid exposure in aircraft systems where chemical resistance outweighs flexibility requirements. Aerospace OEMs in Toulouse and Wichita specify PA11 and PA12 grades for fuel-line integration.
- PVC:Plasticized formulations serve industrial pneumatic circuits and lower-pressure medical drainage applications.
- Rubber:Elastomeric reinforcement layers provide vibration damping in heavy equipment hydraulic assemblies.
Most installed capacity flows through Polyurethane. Expansion is steepest in Nylon as defense aviation procurement accelerates.
Application:
Volume concentration aligns with procedure throughput and fleet replacement cycles rather than unit margin.
- Aerospace:Hydraulic flight-control systems and fuel transfer lines specify burst ratings exceeding 3,000 psi. FAA certification timelines stretch 24-36 months for new braid configurations.
- Automotive:Power-steering and brake-fluid lines consume medium-bore diameters in high-volume assembly plants. Tier-1 suppliers in Stuttgart and Detroit integrate HPBT into modular fluid-routing bundles.
- Oil & Gas:Downhole measurement-while-drilling telemetry strings push 10,000-plus psi operating envelopes.
- Industrial Equipment:Construction machinery and material-handling systems specify cost-optimized rubber-PVC hybrids for hydraulic power transmission.
Production gravity centers on Aerospace for margin contribution. Fastest volume gains are occurring in Oil & Gas as exploration depths increase.
End User:
Customer-type segmentation reveals divergent procurement sophistication and qualification burden.
- Manufacturing:Factory-automation and machine-tool builders specify standardized bore sizes with 48-hour replacement availability.
- Transportation:Automotive and commercial-vehicle OEMs impose PPAP documentation and statistical process control mandates on braid suppliers.
- Construction:Heavy-equipment rental fleets prioritize field-durability over specification precision.
- Healthcare:Catheter OEMs in Massachusetts and Baden-Württemberg demand ISO 13485 certification and EU MDR technical documentation for permanent implant contact applications.
Contract value concentrates in Healthcare. Procurement velocity is accelerating fastest in Transportation as electric-vehicle hydraulic architectures proliferate.
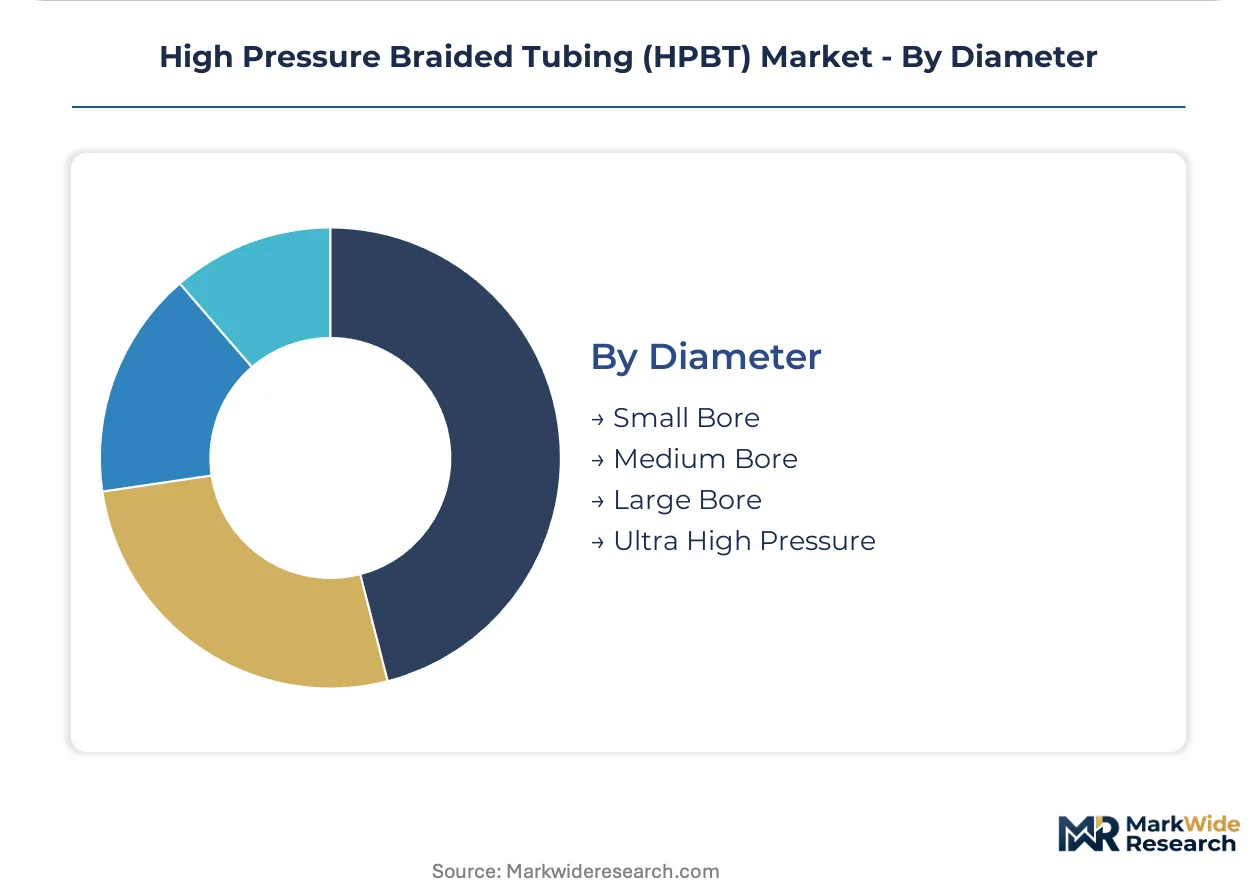
Diameter:
Bore-size segmentation maps directly to pressure-rating architecture and braid-density engineering.
- Small Bore:Sub-3mm lumens enable minimally invasive cardiovascular and peripheral vascular interventions. Interventional cardiologists in Cleveland Clinic and Charité Berlin drive demand for multi-lumen configurations.
- Medium Bore:Industrial pneumatics and automotive fluid lines occupy the 6-12mm range with standardized end-fitting interfaces.
- Large Bore:Marine hydraulics and mining equipment specify reinforced jackets for abrasion resistance in exposed installations.
- Ultra High Pressure:Wire-braid densities exceed 70 picks per inch to contain 10,000-plus psi in subsea and downhole environments.
Absolute volume flows through Small Bore. Engineering-service margins expand most quickly in Ultra High Pressure as material limits are tested.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The HPBT industry traces its commercial origins to post-war aerospace hydraulic systems development in the United States, with medical-grade extrusion capabilities later scaling through Minnesota and Bavaria device manufacturing clusters during the 1980s catheter revolution.
United States
Cardiovascular OEM procurement from Cleveland Clinic and Mayo Clinic networks drives demand for sub-3mm multi-lumen configurations. FDA 21 CFR Part 820 quality-system enforcement extends validation timelines for new braid architectures. Minneapolis-St. Paul anchors neurovascular tubing supply chains where Zeus Company and Biomerics maintain extrusion operations.
Germany
University hospital purchasing alliances in Baden-Württemberg and Bavaria now consolidate 40 percent of cardiovascular device procurement through bundled tubing-connector-sterilization agreements. EU MDR technical-documentation standards stretch notified-body review to 18-24 months for permanent implant applications. Freudenberg Medical operates integrated cleanroom facilities across multiple continents from its Weinheim headquarters.
China
Domestic catheter manufacturing expansion concentrates in Suzhou and Shenzhen precision-machining corridors serving interventional cardiology growth. NMPA medical-device registration requirements intensify polymer feedstock documentation burdens. Yangtze River Delta extrusion houses are qualifying braided reinforcement vendors for export to European OEMs.
India
Production-linked incentive schemes for domestic catheter manufacturing attract HPBT suppliers toward Mumbai and Hyderabad medical-device clusters. CDSCO medical-device rules harmonize with EU MDR traceability mandates for polymer sourcing. Maharashtra-based contract manufacturers are building ISO 13485-certified braiding capacity to serve export markets.
Switzerland
Swissmedic oversight of permanent implant contact applications maintains stringent batch-record requirements for thermoplastic polyurethane formulations. Precision manufacturing in the Jura Arc and Lake Geneva region supplies catheter OEMs with tight-tolerance extrusions. Swiss compounders specialize in fluoropolymer alternatives as EPA per- and polyfluoroalkyl substance restrictions pressure PTFE reformulation.
High Pressure Braided Tubing (HPBT) Market Competitive Landscape
The competitive structure tilts toward integrated material-compounding specialists with validated FDA master files and EU MDR technical documentation. Market access rewards vendors possessing decade-long OEM qualification relationships rather than pure scale. Three archetypes dominate: fluoropolymer compounders with vertical resin control, precision extrusion houses with neurovascular tolerance capabilities, and contract manufacturers offering cleanroom-as-a-service bundling. Capacity expansion and strategic toll-manufacturing partnerships constitute the primary competitive vectors as OEMs seek supply security.
Among European material science conglomerates, Saint-Gobain anchors premium fluoropolymer supply through compounding depth and regulatory documentation heritage. Precision extrusion specialists include Zeus Company, which occupies a position exemplifying tight-tolerance capabilities for neurovascular applications. Freudenberg Medical represents the integrated cleanroom manufacturing archetype with multi-continent production footprints serving both medical and industrial demand streams.
| Leading Market Players |
|---|
| Spectrum Plastics Group |
| Nordson Medical |
| Saint-Gobain |
| RAUMEDIC |
| Freudenberg Medical |
| Zeus Company |
| Biomerics |
| VistaMed |
| CVP Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive fluoropolymer compounding by Saint-Gobain and three Asian resin producers anchors supply positioning and pricing power for medical-grade HPBT serving FDA and EU MDR qualified-device markets. This upstream control lets compounders command premium positioning while extruders without resin access absorb margin compression from polyurethane feedstock volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical grades from industrial pneumatic lines. Price differentiation hinges on FDA master file validation and EU MDR technical documentation completeness. Pricing pressure stems from hospital procurement consortia bundling tubing with connectors and sterilization services. Automotive OEMs exhibit highest price sensitivity; neurovascular device manufacturers show lowest.
Supply Chain Analysis
PTFE and FEP resin supply rests on Japanese, Chinese, and American specialty chemical producers, exposing tubing extruders to allocation risk. Raw material dependencies include thermoplastic polyurethane pellets, stainless-steel wire braid, and fluoropolymer liners. Single-source vulnerability concentrates in semiconductor-sector demand spikes competing for fluoropolymer feedstock. Distribution runs through cleanroom-as-a-service contract manufacturers in Costa Rica and Malaysia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPBT operates as a late-cycle quality story as catheter OEMs shift procurement toward permanent implant contact specifications requiring 18-24 month notified-body validation.
For Market Incumbents: Deepen backward integration into fluoropolymer resin sourcing to defend against PTFE allocation risk from semiconductor demand spikes. Expand ISO 13485-certified cleanroom capacity in India PLI corridors to capture catheter manufacturing migration. Prioritize EU MDR technical documentation heritage as a renewal barrier against emerging Asian compounders. For New Entrants and Emerging Players: Capture downhole oil-tool engineering-service contracts where 10,000-plus psi specifications command margin premiums absent from commoditized industrial lines. Target India's Maharashtra and Telangana medical device clusters where CDSCO rules harmonize with EU MDR traceability. Lead with laser-welded braid termination capabilities to qualify within 90-day OEM windows. For Investors and Strategic Acquirers: Roll-up economics work for precision extrusion specialists with neurovascular tolerance capabilities because FDA master file scarcity creates durable competitive moats. Five-to-ten year viability favors compounders with validated fluoropolymer alternatives as EPA per- and polyfluoroalkyl substance restrictions pressure PTFE reformulation. Watch notified-body backlog duration as inflection indicator for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified-body scrutiny for permanent implant contact applications stretches 18-24 months, freezing unqualified competitors. |
| Fluoropolymer Alternative Formulation | EPA per- and polyfluoroalkyl substance rules force 18-24 month OEM validation cycles for PTFE replacements. |
| India PLI Corridor Capacity Buildout | Production-linked incentives attract HPBT suppliers toward Mumbai and Hyderabad medical-device clusters. |
| Laser-Welded Braid Termination Adoption | Minnesota and Bavaria neurovascular OEMs deploy this capability to qualify secondary suppliers within 90-day windows. |
| Cleanroom-as-a-Service Partnership | Costa Rica and Malaysia contract manufacturers bundle braiding, extrusion, and terminal sterilization for OEM capital relief. |
Research Methodology
Bottom-up catheter OEM demand modeling reconciled against top-down fluoropolymer resin supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital GPO contracts managers, regulatory affairs leads at device manufacturers, and precision extrusion plant managers combined with secondary validation from FDA 510(k) filings, EU MDR notified-body databases, NMPA registration records, and customs trade data. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of cardiovascular procedure volumes, aerospace hydraulic fleet replacement cycles, and oil exploration depth trajectories informed projection parameters. Segmentation modeling spans material type, application, end user, and diameter bore size across the analysis window. CAGRs derive from regression against named demand drivers including catheter-based intervention expansion and downhole pressure rating escalation.
Notified-body backlog duration, fluoropolymer feedstock allocation shocks, and EPA chemical restriction enforcement are the dominant revision risks. Forecasts reflect assumptions about regulatory timeline stability and resin supply concentration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Global Melamine Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Industrial Gaskets Market